
 Toner Resins Market | 2026-2036
Toner Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Toner Resins Market Intelligence
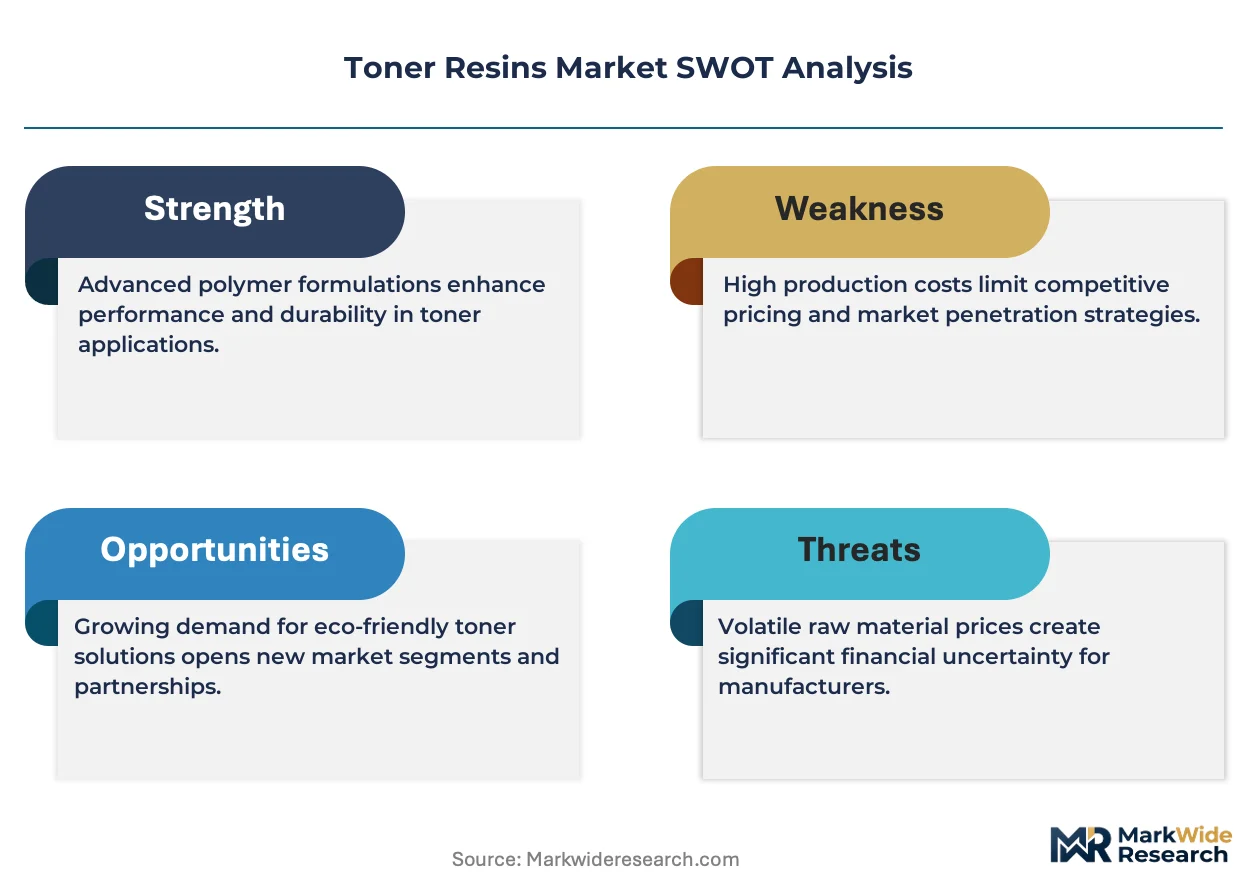
Packaging is recalibrating toner resin consumption patterns as brand owners accelerate short-run digital label production. Kao Corporation leverages its polymer synthesis expertise to dominate high-clarity polyester grades for food-contact applications. Mitsubishi Chemical anchors supply across East Asia through integrated petrochemical feedstock access. Fujikura Kasei differentiates via proprietary dispersion technology that narrows particle size distribution.
Toner resins are thermoplastic binders—typically styrene-acrylic copolymers or crosslinked polyesters with glass transition temperatures between 55°C and 75°C—that encapsulate pigment and charge-control agents into particles capable of electrophotographic image transfer and fuser adhesion. Polyester formulations lead in commercial printing due to superior low-temperature fusing and reduced energy consumption in high-speed presses. Styrene resins retain mature volume in office supplies where cost thresholds dominate procurement decisions. Acrylic variants represent the fastest-growing chemistry in industrial printing as UV-curable hybrid systems gain traction for durable goods marking.
EPA regulations in the United States restrict volatile organic compound emissions from toner manufacturing facilities, pushing producers toward waterborne dispersion processes. REACH and RoHS frameworks in Europe mandate phthalate-free plasticizers and full substance disclosure across resin supply chains. China's GB standards, administered by SAMR, set particle migration limits for food-contact printed materials. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment product portfolios.
Market Dynamics
Digital printing adoption across packaging converters is compressing run lengths and accelerating resin formulation cycles, forcing suppliers to balance low-temperature fusing performance against tighter particle size tolerances.
Growth Catalysts
- Short-run label production:Brand owners in food and beverage packaging are migrating from flexographic to toner-based digital workflows, expanding addressable resin volumes for polyester grades.
- REACH chemical disclosure mandates:European ECHA requirements for full substance transparency are advantaging integrated resin producers with captive analytical capabilities over import-dependent distributors.
- UV-curable hybrid systems:Industrial marking applications for durable goods are absorbing acrylic-urethane hybrid chemistries that fuse at lower temperatures than conventional styrene-acrylic binders.
Market Restraints
- Styrene monomer volatility:Feedstock price swings tied to Asian naphtha cracker economics compress margin predictability for commodity-grade toner resin producers.
- China supply concentration:Domestic cartridge manufacturing clusters in Guangdong and Jiangsu provinces create geographic dependency risk for non-Asian brand owners seeking dual-source security.
- Phthalate substitution costs:REACH and RoHS prohibitions on legacy plasticizers force reformulation investments that fragment product portfolios across regulatory jurisdictions.
Strategic Opportunities
- India packaging digitization:Domestic label converters under BIS quality mandates represent underpenetrated demand for food-contact compliant polyester resins as import substitution accelerates.
- Waterborne dispersion processes:EPA VOC restrictions in the United States are creating first-mover advantages for resin producers with commercialized aqueous particle synthesis capabilities.
- AI-driven print job routing:Convergence of machine learning algorithms with electrophotographic presses enables real-time resin parameter adjustment, opening service-layer revenue for chemistry suppliers.
Industry Challenges
- Polymer synthesis talent scarcity:Specialized expertise in controlled radical polymerization for narrow polydispersity resins concentrates in Japanese and German research clusters, constraining new entrant scale-up.
- Food-contact certification timelines:FDA indirect additive petitions and EFSA safety evaluations extend commercialization cycles by 18-36 months for novel polyester compositions.
- Legacy press compatibility:Resin producers must maintain backward formulation compatibility with installed fuser subsystems across multi-generation equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toner Resins Market |
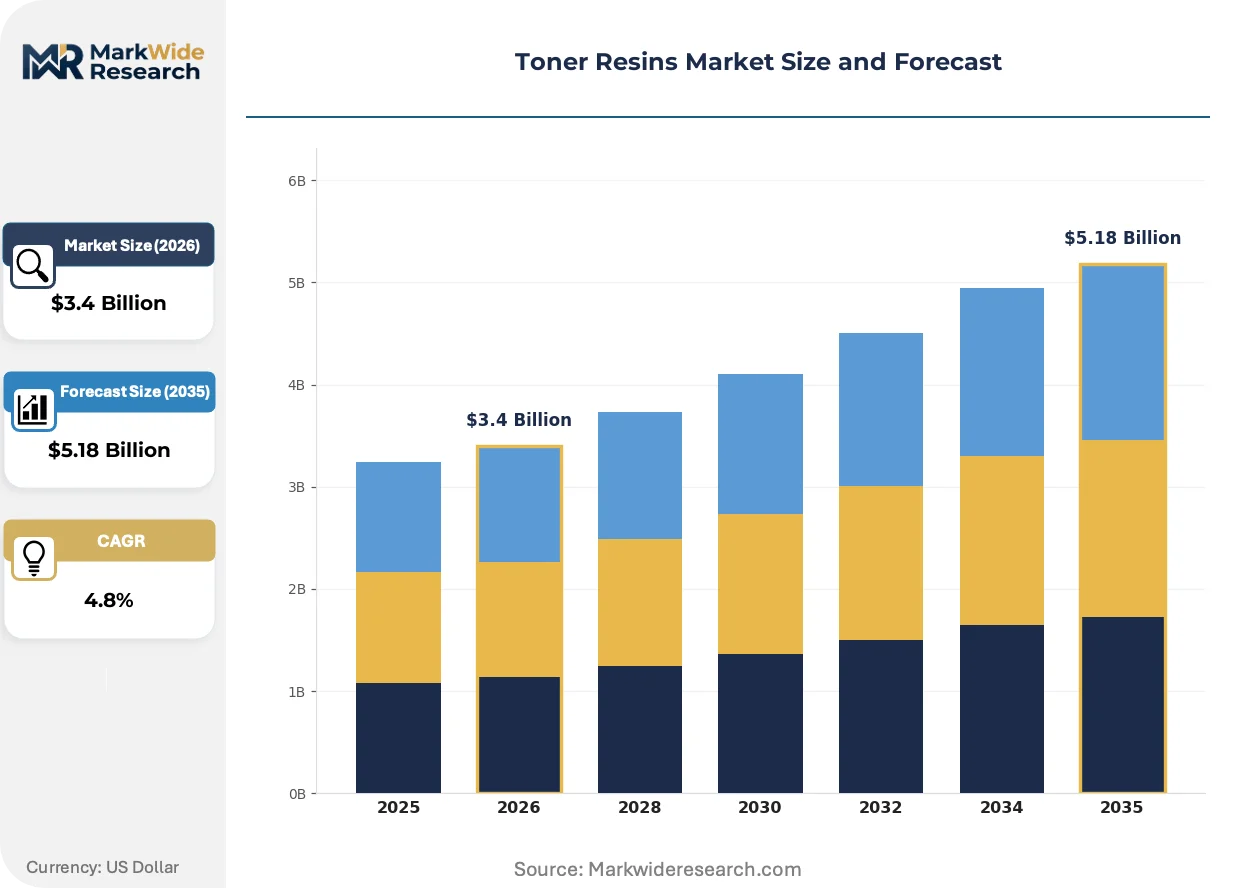
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Styrene, Acrylic, Polyurethane Application: Commercial Printing, Packaging, Office Supplies, Industrial Printing End User: Printers, Manufacturers, Corporates, Educational Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Kao Corporation, Fujikura Kasei, ZEON, Nippon Carbide Industries, Dianal America, DuPont, Mitsubishi Chemical, Nippon, Canon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toner Resins Market Strategic Shifts & Innovations
Formulation science is converging with regulatory compliance architecture as resin producers architect products for simultaneous multi-jurisdiction approval. Three developments are compressing competitive timelines.
Crosslinked polyester architectures with tunable glass transition temperatures are absorbing fuser energy requirements that previously demanded higher-temperature styrene-acrylic systems. Commercial printers operating Ricoh and Konica Minolta production presses are specifying these grades for 1200-dpi food packaging work. The technology is absorbing market share in applications where energy costs and substrate heat sensitivity previously constrained toner adoption.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants at US toner manufacturing facilities is accelerating capital redeployment toward aqueous dispersion technologies. Production economics now favor continuous reactor designs over batch suspension polymerization for new capacity investments. Midwestern resin compounders are retrofitting solvent recovery systems or relocating mixing operations to avoid Title V permitting thresholds.
Brand owner sustainability scorecards are rewriting procurement specifications to prioritize bio-based diol content and mass-balance certification. Major label converters in Germany and the Netherlands are inserting resin carbon intensity metrics into supplier qualification questionnaires. This behavioral shift is most visible in European personal care and premium food segments where packaging serves as brand differentiation.
Toner Resins Market Segmentation
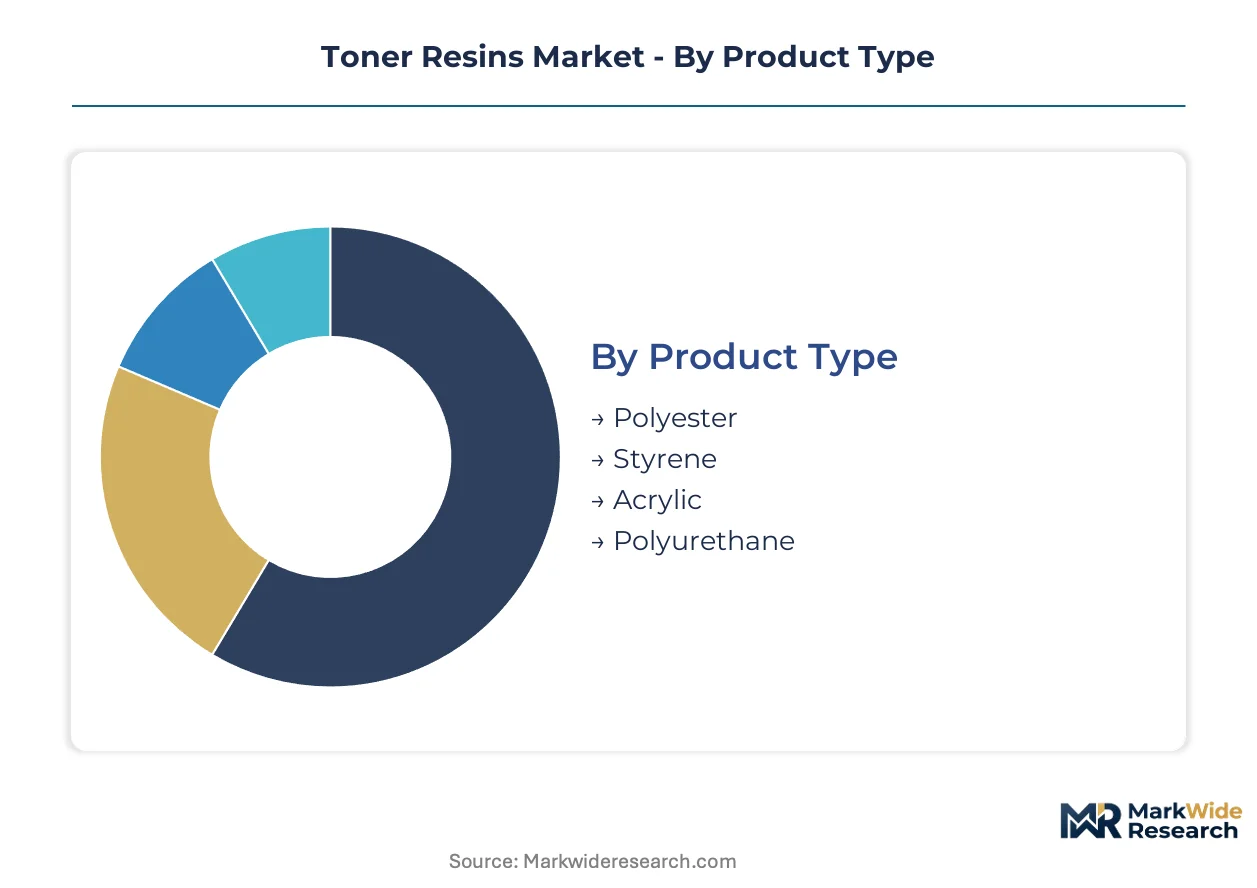
Toner resin formulations diverge sharply across chemistry families and end-use thermal requirements. Procurement patterns split between high-volume commodity grades and specification-driven premium formulations for food-contact and industrial durability applications.
Product Type:
Volume concentration favors commodity chemistries with established feedstock infrastructure. Premium positioning attaches to engineered polyesters and hybrid systems commanding formulation premiums.
- Polyester:Crosslinked copolyesters with tunable glass transition temperatures between 55°C and 75°C enable low-temperature fusing for high-speed commercial presses. Demand concentrates in European food packaging converters under EFSA food-contact mandates, where energy reduction and substrate heat sensitivity drive specification upgrades.
- Styrene:Styrene-acrylic copolymers dominate legacy office equipment fleets where cost thresholds override performance optimization. Procurement remains anchored in mature cartridge remanufacturing clusters across Guangdong and Jiangsu provinces serving Asia-Pacific supply chains.
- Acrylic:UV-curable acrylic-urethane hybrids are gaining traction in industrial marking for durable goods.
- Polyurethane:Specialty elastomeric binders serve niche flexible packaging applications requiring substrate adhesion.
Mature deployment sits with Styrene. Newer deployment is concentrated in Polyester.
Application:
Application segmentation tracks the divergence between long-run analog workflows and short-run digital production economics.
- Commercial Printing:High-volume production environments utilizing Ricoh, Konica Minolta, and Xerox presses specify narrow particle size distribution resins for 1200-dpi resolution. German and Dutch label converters are inserting carbon intensity metrics into supplier scorecards, reshaping procurement toward mass-balance certified polyesters.
- Packaging:Brand owners in beverage and personal care segments are compressing run lengths and migrating from flexographic to toner-based digital workflows. REACH chemical disclosure requirements are advantaging integrated resin producers with captive analytical capabilities over import-dependent distributors.
- Office Supplies:Cost-optimized styrene-acrylic formulations serve installed equipment bases with backward compatibility constraints.
- Industrial Printing:Durable goods marking applications absorb acrylic-urethane hybrid chemistries for UV-curable systems.
Procurement scale concentrates in Commercial Printing. Specification complexity is expanding fastest in Packaging.
End User:
End user segmentation reflects the split between specification-setting OEMs and price-sensitive aftermarket participants.
- Printers:Commercial print service providers operate as formulation gatekeepers, specifying resin grades that determine fuser subsystem compatibility and image quality outcomes. Japanese and German press manufacturers maintain tight qualification protocols that fragment supplier access.
- Manufacturers:Toner cartridge producers and remanufacturers in China are scaling domestic resin consumption to serve Asia-Pacific supply chains, creating geographic concentration risk for dual-source strategies.
- Corporates:Enterprise fleet managers prioritize total cost of ownership over resin specification transparency.
- Educational Institutions:Public procurement frameworks emphasize cost minimization for high-volume document production.
Technical authority rests with Printers. Volume aggregation is shifting toward Manufacturers.
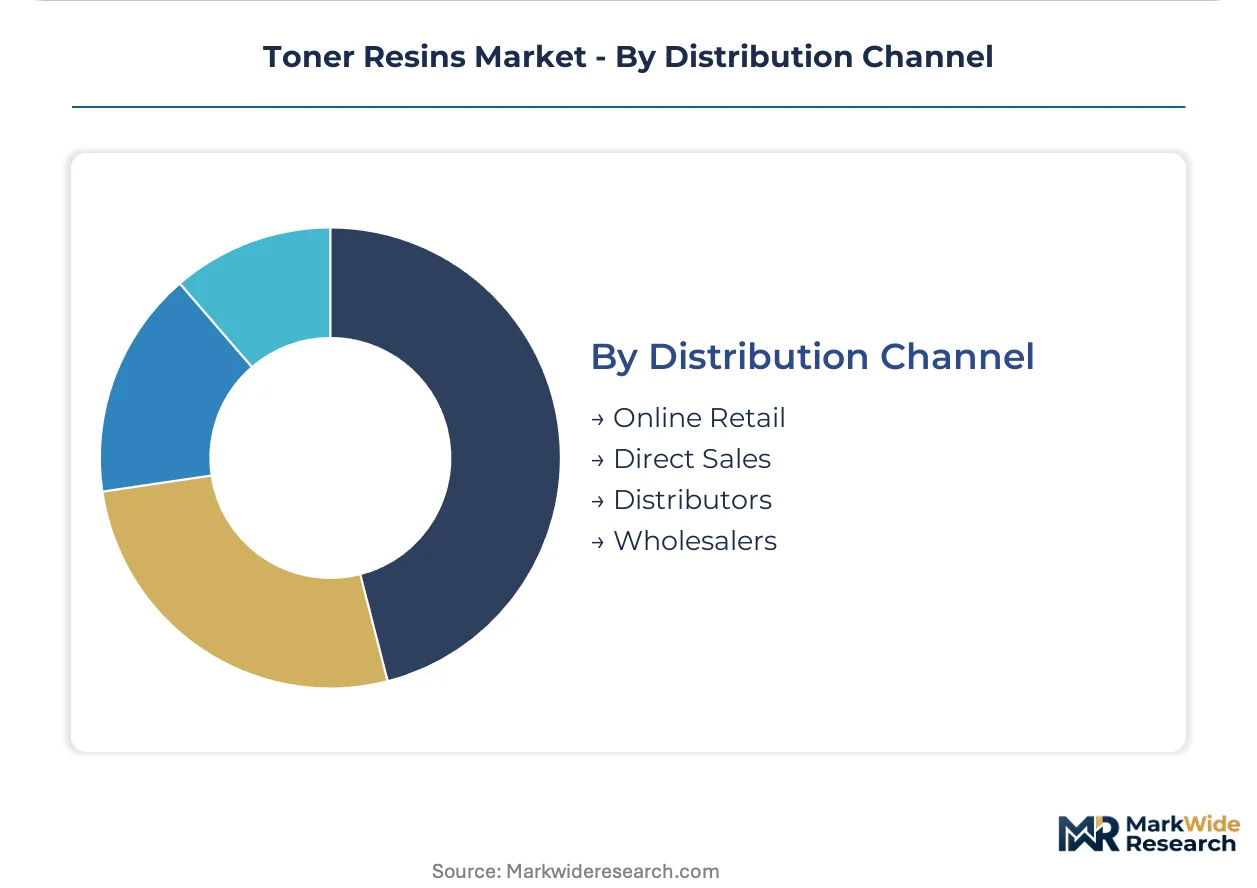
Distribution Channel:
Channel structure mirrors the tension between specification complexity and procurement efficiency.
- Direct Sales:Integrated resin producers with polymer synthesis expertise engage major label converters and packaging printers through technical service relationships. Kao Corporation and Mitsubishi Chemical leverage captive feedstock access and food-contact certification capabilities to bypass distributor margins.
- Distributors:Regional compounders serve mid-tier commercial printers with blended formulations and inventory pooling. EPA VOC enforcement is pushing US-based distributors toward aqueous dispersion product lines or solvent recovery investments.
- Online Retail:E-commerce platforms capture aftermarket cartridge sales with limited resin specification transparency.
- Wholesalers:Volume aggregators serve price-sensitive office supply channels with commodity-grade formulations.
Relationship intensity concentrates in Direct Sales. Transaction efficiency is expanding fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones have concentrated toner resin manufacturing capacity as domestic cartridge producers scale to serve Asia-Pacific supply chains. Guangdong and Jiangsu provinces anchor production clusters where integrated petrochemical feedstock access lowers formulation costs.
China
Domestic toner cartridge manufacturing in Guangdong and Jiangsu provinces is absorbing polyester resin volumes as brand owners shift procurement to local supply chains. SAMR-administered GB standards set particle migration limits for food-contact printed materials, tightening compliance requirements for resin imports. The Pearl River Delta cluster around Shenzhen and Dongguan houses integrated producers with captive analytical capabilities for REACH-aligned chemical disclosure.
United States
Commercial printers in the Midwest and Southeast are specifying low-temperature fusing polyesters for high-speed production environments. EPA enforcement of National Emission Standards for Hazardous Air Pollutants is accelerating capital redeployment toward aqueous dispersion technologies at manufacturing facilities. Resin compounders in Ohio and Michigan are retrofitting solvent recovery systems or relocating mixing operations to avoid Title V permitting thresholds.
Germany
Label converters in Bavaria and North Rhine-Westphalia are inserting carbon intensity metrics into supplier qualification questionnaires for mass-balance certified polyesters. ECHA REACH requirements for full substance transparency are advantaging integrated resin producers with captive analytical capabilities over import-dependent distributors. The Rhine-Ruhr industrial corridor anchors formulation R&D clusters serving EFSA-compliant food packaging specifications.
Japan
Polymer synthesis expertise in controlled radical polymerization concentrates in Kanto and Kansai research clusters, constraining new entrant scale-up for narrow polydispersity resins. METI industrial standards shape qualification protocols for electrophotographic press compatibility. Tokyo-Osaka corridor producers maintain tight technical service relationships with Ricoh and Konica Minolta equipment manufacturers.
India
Domestic label converters under BIS quality mandates represent underpenetrated demand for food-contact compliant polyester resins as import substitution accelerates. Maharashtra and Gujarat packaging clusters are digitizing short-run production workflows previously served by flexographic systems. Mumbai-Ahmedabad industrial corridor converters are migrating procurement specifications toward REACH-aligned chemical disclosure standards.
Toner Resins Market Key Industry Players
Top-tier vendors anchor integrated petrochemical supply chains, while mid-tier compounders compete on formulation flexibility and regional service density. The market structure reflects concentration among Japanese and German producers with polymer synthesis expertise, alongside Chinese scale players serving domestic cartridge manufacturing. Three archetypes dominate: integrated resin producers with captive feedstock access, specialized dispersion technology houses, and regional compounders blending commodity grades. Competitive moves center on backward integration into petrochemical feedstocks and aqueous dispersion capacity investments to satisfy EPA VOC enforcement.
Among Japanese chemical conglomerates, Kao Corporation, Fujikura Kasei, and Mitsubishi Chemical occupy positions reflecting distinct capability anchors. Kao exemplifies the integrated producer archetype with polymer synthesis expertise in high-clarity polyester grades. Fujikura Kasei represents the dispersion technology specialist tier, differentiated via proprietary particle size distribution control. Mitsubishi Chemical anchors supply across East Asia through integrated petrochemical infrastructure. These three names illustrate how geographic clustering and technical specialization stratify competitive positioning without requiring granular operational claims.
| Leading Market Players |
|---|
| Kao Corporation |
| Fujikura Kasei |
| ZEON |
| Nippon Carbide Industries |
| Dianal America |
| DuPont |
| Mitsubishi Chemical |
| Nippon |
| Canon |
| Others |
Cost & Logistics Intelligence
Asian naphtha cracker spreads cascade through styrene monomer pricing tiers, compressing margin buffers for commodity-grade producers while concentrating pricing power among integrated petrochemical houses with captive feedstock security.
Pricing Analysis
Short lead-time premiums attach to REACH-compliant polyester grades serving European food packaging converters, while spot inventory of legacy styrene-acrylic formulations trades at discount to contract volumes. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified polyesters from industrial-grade hybrids and remanufacturing feedstock. Cost compression in commodity styrene tiers is intensifying because of naphtha volatility and Chinese oversupply. Aftermarket cartridge remanufacturers in Guangdong exhibit highest price sensitivity; Japanese OEM qualification holders command lowest.
Supply Chain Analysis
Reverse logistics flows from cartridge remanufacturing clusters in Guangdong and Jiangsu feed recovered toner back into compounder blending operations, creating circular material loops that offset virgin resin demand. Supply concentrates in China, Japan, and Germany, with formulation R&D anchored in Kanto and Rhine-Ruhr corridors. Raw material dependencies center on purified terephthalic acid, styrene monomer, and specialty charge-control agents. Single-source vulnerability runs through Chinese coastal petrochemical infrastructure. Distribution runs through direct technical service relationships for premium grades and regional distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer synthesis capacity constraints prop pricing premiums, as controlled radical polymerization expertise concentrates in Japanese and German research clusters with limited new entrant scale-up pathways.
For Market Incumbents: Anticipate aqueous dispersion technology displacement of solvent-based batch processes by retrofitting Midwestern facilities or relocating mixing operations to avoid EPA Title V permitting thresholds. Defend formulation gatekeeper status with Ricoh and Konica Minolta through backward integration into petrochemical feedstocks. Prioritize captive analytical capabilities for REACH-aligned chemical disclosure to disadvantage import-dependent distributors.
For New Entrants and Emerging Players: EPA National Emission Standards for Hazardous Air Pollutants enforcement in the United States opens a window for first-mover aqueous dispersion producers with commercialized continuous reactor designs. Target underpenetrated Indian label converters under BIS quality mandates migrating from flexographic to toner-based digital workflows. Enter through technical service partnerships with Maharashtra and Gujarat packaging clusters seeking REACH-aligned resin specifications.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with solvent recovery retrofit obligations in Ohio and Michigan facing EPA compliance capital demands. Long-term viability hinges on aqueous dispersion technology maturation and bio-based diol feedstock scaling. Monitor EFSA safety evaluation timelines for novel polyester compositions as inflection indicator for premium grade supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Dispersion Capacity Buildout | EPA VOC enforcement advantages first movers with continuous reactor designs over batch suspension polymerization. |
| Backward Integration into Petrochemical Feedstocks | Kao Corporation and Mitsubishi Chemical leverage captive PTA and styrene access to bypass distributor margins. |
| Food-Contact Certification Investment | EFSA-compliant polyester grades command formulation premiums from German and Dutch label converters. |
| India Market Entry Partnership | Maharashtra and Gujarat packaging clusters under BIS mandates represent import substitution opportunities for REACH-aligned producers. |
| Reverse Logistics Network Development | Guangdong remanufacturing clusters create circular material loops that offset virgin resin cost exposure. |
Research Approach
Trade publications, customs databases, and SEC filings formed the secondary backbone, supplemented by primary interviews with polymer synthesis R&D directors, toner cartridge procurement leads at Chinese manufacturers, EPA compliance officers, and European label converter technical managers. Bottom-up volume estimates triangulated against top-down petrochemical feedstock consumption trends across the analysis window.
Historical trendline analysis of resin grade pricing spreads and production capacity utilization informed the projection framework. Segmentation dimensions modeled include chemistry family, application thermal requirements, food-contact certification tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating digital press installation rates and packaging run-length compression trends.
The model assumes a particular technology adoption path; alternative pathways for UV-curable acrylic-urethane hybrid systems would alter the outlook if industrial marking demand accelerates faster than projected. Forecasts incorporate assumptions regarding REACH enforcement consistency and naphtha cracker economics stability. Practitioners should monitor EFSA safety evaluation queue lengths and EPA Title V permitting backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Specialty Nitriles Market