
 Synthetic Leather Market | 2026-2036
Synthetic Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Leather Market Intelligence
A shift in demand from fast fashion towards durable automotive interiors is restructuring the synthetic leather value chain. This change prioritizes performance, longevity, and compliance with stringent industry standards over low-cost, high-volume production. Kuraray Co., Ltd. leverages its advanced microfiber technology to serve this premium automotive segment. Meanwhile, San Fang Chemical Industry Co., Ltd. sustains a strong position through its large-scale production of polyurethane-based materials for diverse applications, including footwear and furniture.
Synthetic leather is an artificial material engineered to replicate the appearance and texture of genuine leather. It typically consists of a fabric base, such as cotton or polyester, coated with a polymer layer like polyurethane (PU) or polyvinyl chloride (PVC). Its primary purpose is to offer a cost-effective, versatile, and animal-free alternative for various industries. Polyurethane-based products lead the market, valued for their breathability and soft feel over traditional PVC. While the footwear application constitutes the largest segment by volume, automotive interiors represent the fastest-growing application.
The market operates within a complex regulatory environment that directly influences material composition. The European Union's REACH regulation restricts the use of certain solvents like DMF in PU production, accelerating the shift to water-based alternatives. Concurrently, China's GB standards impose strict limits on volatile organic compound (VOC) emissions in materials used for vehicle interiors. Successfully developing and scaling solvent-free manufacturing processes while meeting divergent regional chemical standards will determine future market leadership.
Market Dynamics
Regulatory pressure for sustainable manufacturing, seen in the EU's REACH and China's GB standards, is compelling a technological pivot from solvent-based processes toward bio-based and water-based material formulations.
Growth Catalysts
- Automotive Sector Demand:The transition to electric vehicles elevates the importance of interior acoustics and premium feel, driving adoption of advanced microfiber and PU leathers over traditional textiles and PVC.
- Regulatory Frameworks:The EU's REACH regulation, which restricts DMF solvent use, acts as a powerful catalyst for innovation in water-based and solvent-free PU manufacturing technologies.
- Bio-Based Material Innovation:Advances in converting non-food biomass into polymer precursors create a strong pull from brands seeking to improve the sustainability profile of their footwear and accessory products.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations in petrochemical feedstocks like MDI and polyols, which are essential for polyurethane production and can compress manufacturer margins.
- Performance Parity Gaps:High-end applications still challenge synthetic materials to perfectly replicate the unique aging patina, moisture wicking, and long-term repairability of genuine full-grain leather.
- Substitution from Textiles:High-performance textiles and engineered fabrics, particularly those with recycled content and advanced coatings, present a viable alternative in applications like furniture and mass transit seating.
Strategic Opportunities
- Aviation and Marine Interiors:Developing materials that meet the stringent fire-retardancy, durability, and weight standards of the aerospace and marine sectors offers a high-margin growth avenue beyond automotive.
- Smart Material Integration:Embedding conductive fibers or printed circuits into synthetic leather creates opportunities for integrated controls and ambient lighting in automotive dashboards and furniture.
- Home Goods in India:The expanding middle class and urbanization in India present an underpenetrated market for durable and stylish synthetic leather in residential furniture and home décor applications.
Industry Challenges
- Capital-Intensive Process Scaling:Transitioning production from traditional solvent-based PU lines to modern, eco-friendly water-based or solvent-free systems requires significant upfront capital investment in new machinery and facilities.
- Divergent Standards Compliance:Manufacturers face complexity in formulating products that simultaneously satisfy the chemical restrictions of the EU's REACH and the VOC emission limits of China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Leather Market |
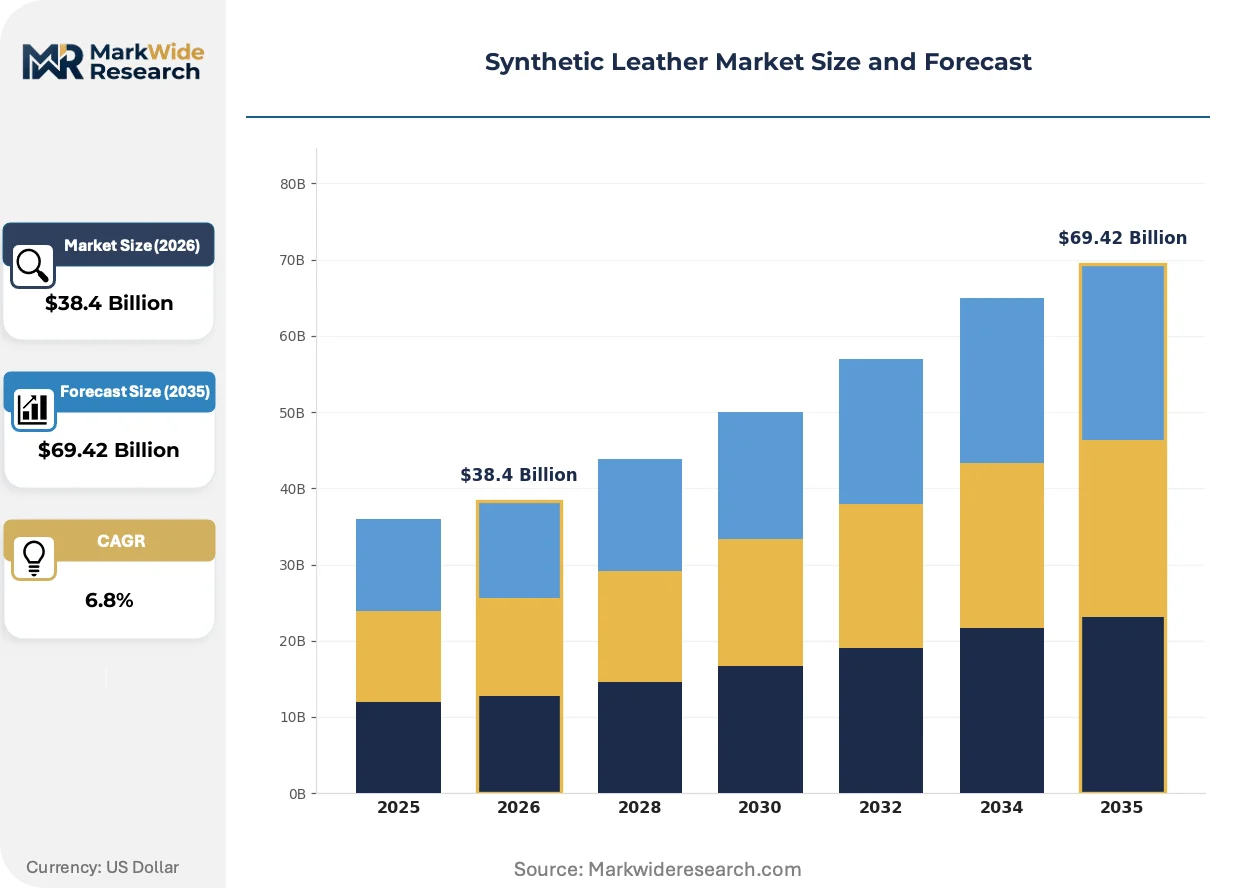
| Market Size in 2026 | $38.4 Billion |
| Market Size in 2035 | $69.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyvinyl Chloride, Microfiber, Silicone, Acrylic Application: Footwear, Furniture Upholstery, Automotive Interiors, Fashion Accessories, Sports Equipment End User: Shoe Manufacturers, Furniture Makers, Vehicle Assemblers, Apparel Producers, Sporting Goods Companies Distribution Channel: Wholesale, Online Retail, Specialty Stores, Direct Sales, Export |
| Companies Covered | Kuraray Co., Ltd., San Fang Chemical Industry Co., Ltd., Nan Ya Plastics Corporation, Teijin Limited, Toray Industries, Inc., Filwel Co., Ltd., Mayur Uniquoters Limited, Zhejiang Hexin Holdings Co., Ltd., Yantai Wanhua Synthetic Leather Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Leather Market Strategic Shifts & Innovations
Material science advancements are converging with stringent environmental regulations and evolving consumer expectations for sustainability. This confluence is fundamentally altering product design, manufacturing processes, and the very definition of performance in the synthetic leather industry.
Bio-based and recycled feedstocks are being integrated directly into polyurethane formulations. Automotive and fashion brands are rapidly adopting these hybrid materials to meet internal sustainability goals and demonstrate environmental stewardship to consumers. This development is unifying material performance requirements with circular economy principles, establishing a new benchmark for premium synthetic leather.
China's GB standards impose strict limits on volatile organic compound (VOC) emissions within vehicle cabins. This regulation compels suppliers to abandon or re-engineer traditional solvent-based coating processes in favor of water-based or solvent-free alternatives. Tier-1 automotive interior suppliers operating in or exporting to China are most directly impacted, accelerating investment in compliant production technology.
Procurement in automotive and contract furniture is evolving from material specification to verified lifecycle performance. This change disrupts the commodity model, favoring suppliers with certified data on abrasion, UV resistance, and cleanability. The shift is most pronounced in European and North American markets where long-term warranties are critical purchasing criteria.
Synthetic Leather Market Segmentation
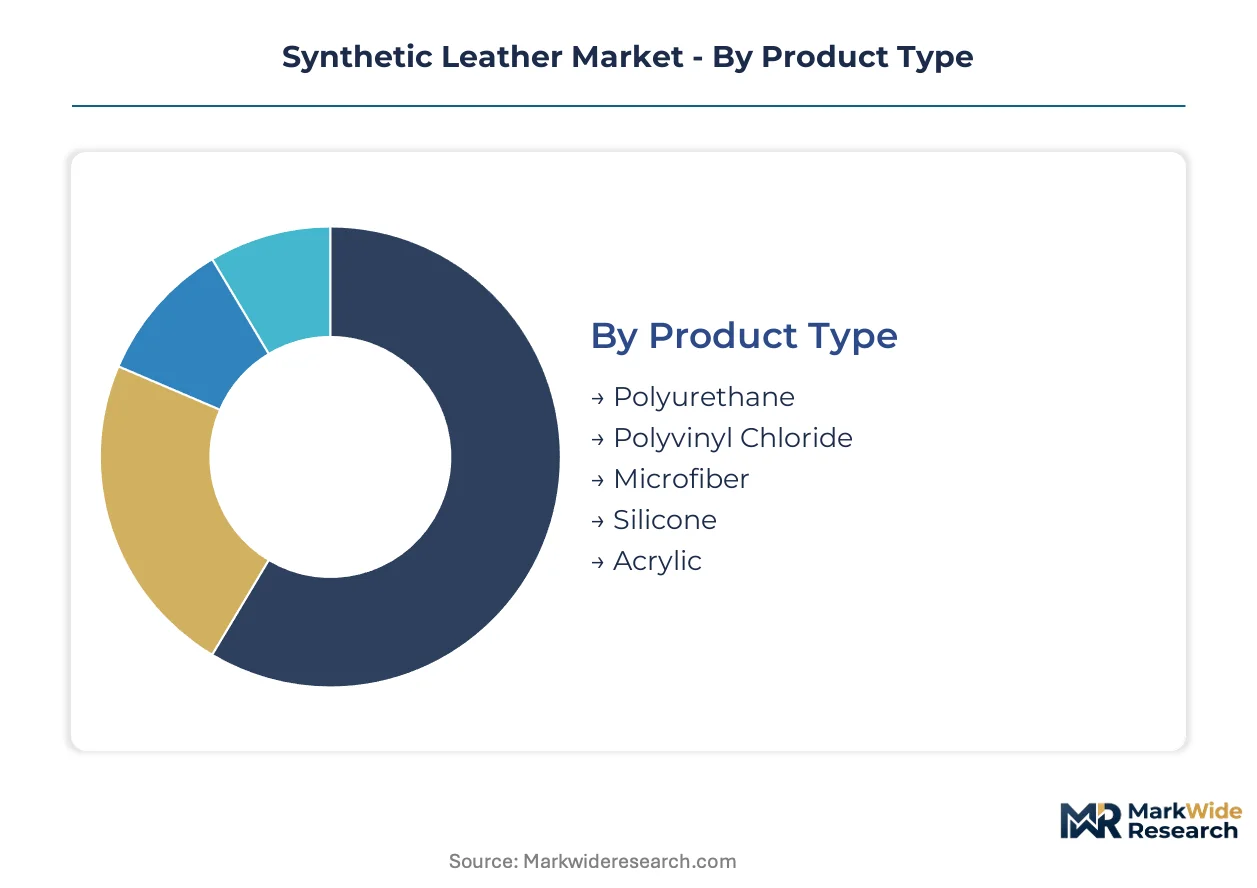
Segmentation analysis provides a granular view of the synthetic leather market, highlighting specific material preferences, application demands, and end-user requirements. Understanding these distinct segments allows manufacturers to tailor product development and strategic investments effectively. This detailed breakdown reveals where value is concentrated and where new growth opportunities are emerging across the industry landscape.
Product Type:
Supply concentration in synthetic leather production heavily influences material availability and cost structures across different product types.
- Polyurethane:This material consists of a polymer coating applied to a fabric base, valued for its breathability, soft feel, and versatility. Demand for polyurethane is substantial in footwear and furniture, offering a comfortable and durable alternative to genuine leather.
- Microfiber:Engineered with ultra-fine synthetic fibers, microfiber synthetic leather offers superior durability, a premium tactile feel, and enhanced aesthetic properties. This high-performance material sees significant demand in the automotive interiors sector, where it contributes to perceived luxury and longevity.
- Polyvinyl Chloride:PVC synthetic leather uses a plasticized vinyl coating, providing high resistance to wear and water, often at a lower cost point.
- Silicone:Silicone-based synthetic leather offers excellent environmental resistance, including UV stability and flame retardancy, making it suitable for demanding applications.
- Acrylic:Acrylic coatings provide a flexible and weather-resistant finish for synthetic leather, often used in outdoor furniture and specialized textile applications.
Polyurethane absorbs the bulk of installed capacity; Microfiber is expanding most quickly.
Application:
The varied cost tiers associated with synthetic leather applications dictate material selection and market accessibility for manufacturers.
- Automotive Interiors:Synthetic leather in automotive interiors covers seating, door panels, dashboards, and headliners, providing durability, ease of cleaning, and a premium aesthetic. The transition to electric vehicles elevates the importance of these materials for acoustics and passenger comfort.
- Footwear:This application includes uppers, linings, and insoles for various shoe types, prioritizing flexibility, abrasion resistance, and cost-effectiveness. Footwear remains the largest segment by volume, driven by global consumer demand for diverse styles.
- Furniture Upholstery:Synthetic leather provides a durable and stylish covering for residential and commercial furniture, offering resistance to spills and wear.
- Fashion Accessories:This segment includes handbags, belts, and wallets, where synthetic leather offers design versatility and an animal-free alternative.
- Sports Equipment:Synthetic leather is utilized in items like sports balls, gloves, and protective gear for its grip, durability, and moisture resistance.
Demand for Footwear drives significant volume, while Automotive Interiors commands higher margins.
End User:
Volume requirements from distinct end-user segments shape production scales and material specifications across the synthetic leather industry.
- Vehicle Assemblers:These manufacturers integrate synthetic leather into vehicle production lines, requiring materials that meet stringent performance standards for durability, VOC emissions, and aesthetic consistency. Procurement by vehicle assemblers is highly regulated, necessitating compliance with global automotive specifications.
- Shoe Manufacturers:This end-user group utilizes synthetic leather for a wide range of footwear products, prioritizing material flexibility, cost-efficiency, and aesthetic variety for mass production. Shoe manufacturers often seek materials with specific textures and finishes to cater to fashion trends.
- Furniture Makers:Furniture makers purchase synthetic leather for upholstery, balancing aesthetic appeal with durability and ease of maintenance for residential and commercial pieces.
- Apparel Producers:This segment uses synthetic leather for jackets, pants, and other garments, valuing its drape, texture, and ability to mimic genuine leather.
- Sporting Goods Companies:These companies procure synthetic leather for equipment requiring specific performance characteristics such as grip, water resistance, and longevity under demanding conditions.
Large-scale procurement by Shoe Manufacturers stabilizes production, and Vehicle Assemblers exhibit increasing material customization.
Distribution Channel:
Customer types within distribution channels determine lead times and service expectations for synthetic leather suppliers.
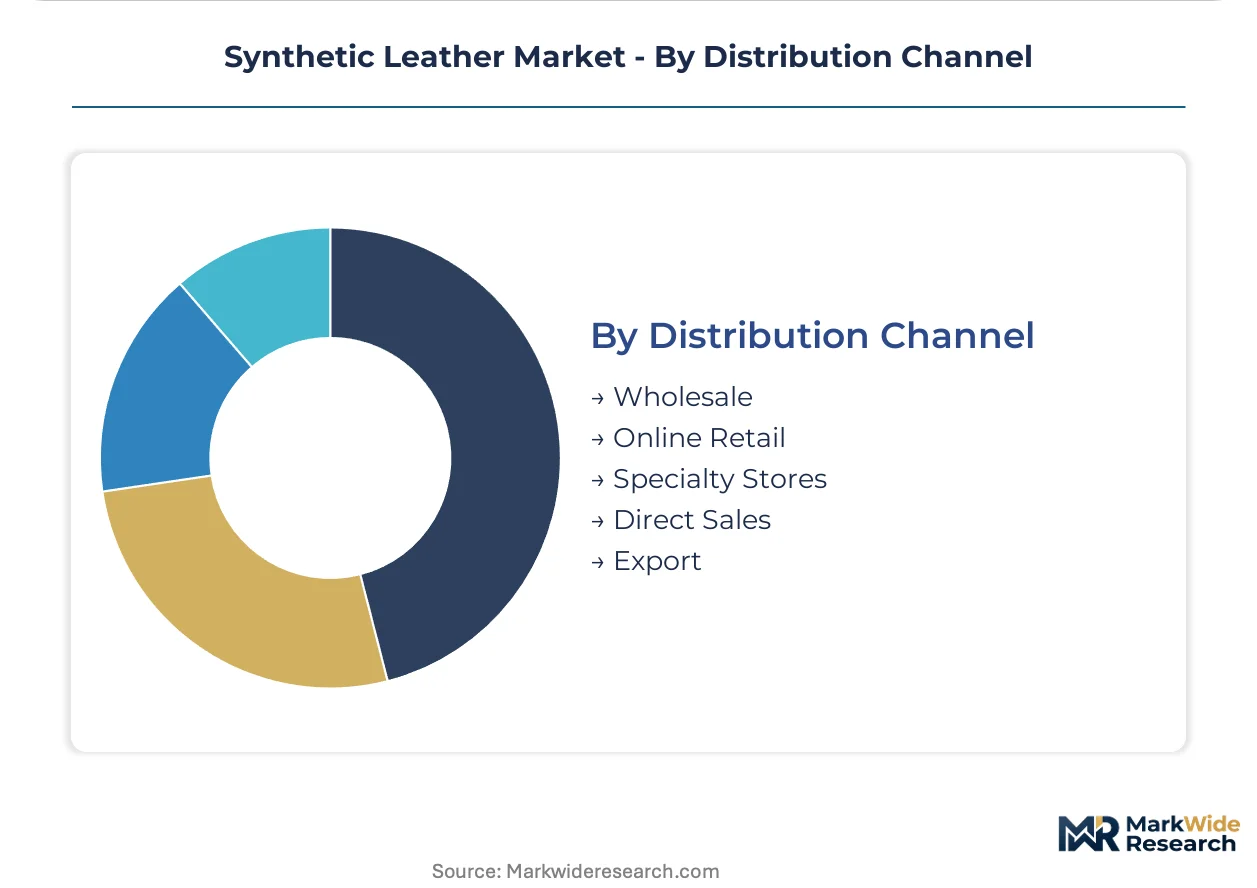
- Wholesale:This channel involves bulk sales of synthetic leather materials to large-scale manufacturers and distributors, characterized by high volume transactions and established supply chain relationships. Wholesale distribution often serves as the primary conduit for industrial-scale material procurement.
- Online Retail:Online retail channels facilitate the sale of synthetic leather products directly to consumers or small businesses, offering convenience and broader access to specialized materials. This channel supports niche markets and direct-to-consumer brands.
- Specialty Stores:Specialty stores offer curated selections of synthetic leather products, catering to specific design needs or premium segments with personalized service.
- Direct Sales:Direct sales involve manufacturers selling synthetic leather directly to end-user clients, allowing for customized orders and closer client relationships.
- Export:The export channel involves shipping synthetic leather materials across international borders to serve manufacturing hubs and markets worldwide.
Traditional channels like Wholesale handle the majority of volume, while Online Retail enables broader market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing centers across China and Vietnam, particularly those within established economic development zones, drive significant concentration in synthetic leather production. These zones benefit from robust infrastructure and skilled labor, attracting substantial investment in advanced material manufacturing. This regional specialization underpins global supply chains for diverse synthetic leather applications.
China
Automotive interiors and footwear production fuel substantial demand for synthetic leather across China. The Ministry of Ecology and Environment enforces stringent GB standards on volatile organic compound emissions for vehicle components. Industrial clusters in the Yangtze River Delta and Pearl River Delta regions are investing heavily in solvent-free and water-based polyurethane manufacturing technologies.
Vietnam
Export-oriented manufacturing for footwear and fashion accessories sustains Vietnam's synthetic leather market. The government actively promotes foreign direct investment in high-tech manufacturing, including advanced material production. Textile and footwear hubs around Ho Chi Minh City and Hanoi are expanding capacity for specialized synthetic leather to meet international brand requirements.
Germany
The premium automotive sector in Germany represents a strong demand driver for advanced synthetic leather, emphasizing durability and aesthetic quality. The European Union's REACH regulation dictates strict chemical substance restrictions, particularly for solvents like DMF in PU production. Automotive suppliers in Bavaria and North Rhine-Westphalia are at the forefront of developing bio-based and solvent-free synthetic leather solutions.
United States
Consumer demand for durable furniture and automotive interiors propels the synthetic leather market in the United States. Regulations from the Environmental Protection Agency influence manufacturing processes, encouraging more sustainable material production. Major manufacturing centers in the Southeast, particularly around North Carolina, see ongoing investment in advanced textile and material finishing technologies.
India
The expanding middle class and increasing urbanization in India create a strong pull for synthetic leather in home goods and footwear. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for various consumer products, including furniture materials. Manufacturing clusters in Gujarat and Tamil Nadu are witnessing growth in facilities producing cost-effective and durable synthetic leather for domestic consumption.
Synthetic Leather Market Key Industry Players
Top-tier vendors anchor the premium segment, focusing on high-performance materials for automotive and specialized applications, while mid-tier manufacturers compete on volume and cost-efficiency for footwear and furniture. The market exhibits a tiered structure, with material innovation and supply chain efficiency serving as primary competitive differentiators. Companies pursue strategic partnerships for technology co-development and expand their geographic footprint to serve key manufacturing hubs.
Among Asia-Pacific based material specialists, Kuraray Co., Ltd. represents an archetype focused on advanced microfiber technology for high-end automotive interiors. San Fang Chemical Industry Co., Ltd. exemplifies large-scale production of polyurethane-based materials, serving diverse applications from footwear to furniture. Nan Ya Plastics Corporation also occupies a significant position, leveraging its broad chemical manufacturing capabilities to produce various synthetic leather types for regional and international markets.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| San Fang Chemical Industry Co., Ltd. |
| Nan Ya Plastics Corporation |
| Teijin Limited |
| Toray Industries, Inc. |
| Filwel Co., Ltd. |
| Mayur Uniquoters Limited |
| Zhejiang Hexin Holdings Co., Ltd. |
| Yantai Wanhua Synthetic Leather Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
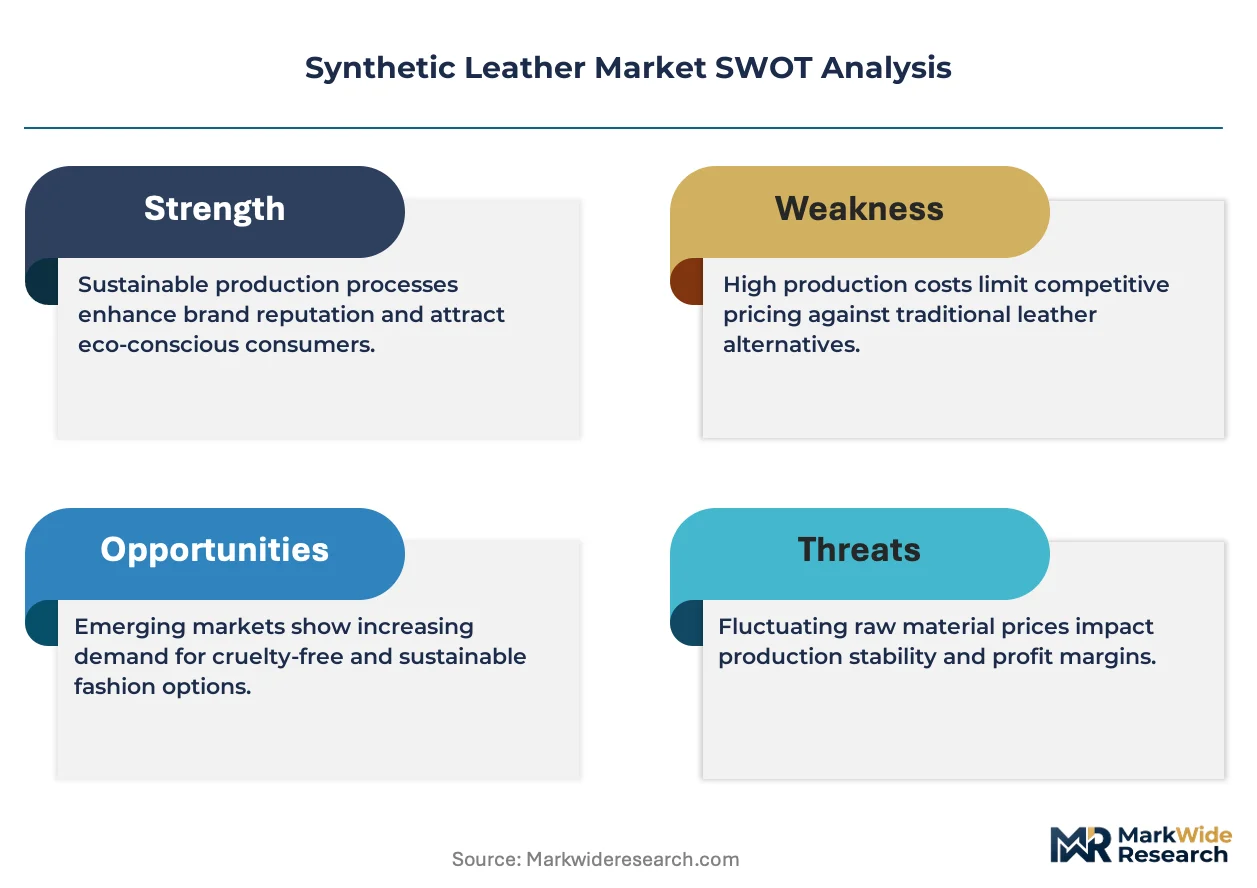
Petrochemical feedstock price volatility directly impacts synthetic leather production costs, influencing pricing tiers from raw material suppliers to finished goods manufacturers. This upstream cost fluctuation creates a ripple effect throughout the value chain.
Pricing Analysis
Premium pricing for synthetic leather with short lead times reflects expedited manufacturing and delivery capabilities, while larger volume orders often secure discounted rates for long-term contracts. The dominant pricing model remains per-unit transactional, though long-term offtake agreements are common for large-scale automotive suppliers. Price differentiation stems from quality grade, particularly for advanced microfiber materials, and compliance with stringent certifications like automotive OEM standards. Pricing pressure stems from input cost volatility, particularly for petrochemicals. Footwear manufacturers typically exhibit higher price sensitivity compared to premium automotive interior suppliers.
Supply Chain Analysis
Logistics and freight costs significantly influence the competitiveness of synthetic leather suppliers, especially for materials shipped from major production centers in China and Vietnam to global markets. The supply chain draws heavily on petrochemical feedstocks like MDI and polyols, primarily sourced from large chemical producers. A structural risk exists in potential trade tariffs or disruptions affecting these key manufacturing hubs. Distribution runs through a mix of wholesale channels for large manufacturers and direct sales for specialized applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic leather market is evolving into a vertical-integration race, as companies seek to control the supply of bio-based and recycled feedstocks to meet sustainability targets. This strategic move aims to secure critical material inputs and differentiate offerings.
For Market Incumbents: To counter the threat of material substitution from high-performance textiles, established synthetic leather manufacturers must invest in advanced R&D for next-generation microfiber and solvent-free PU technologies. Expanding capacity in bio-based material production within Vietnam or China can reinforce supply chain resilience and meet evolving regulatory demands like EU REACH. Certification investment for verified lifecycle performance also defends premium market share.
For New Entrants and Emerging Players: Price-point gaps between premium automotive materials and economy footwear options present opportunities for new entrants focusing on mid-tier furniture upholstery or home goods in India. Targeting underpenetrated regional markets with cost-effective, GB standards-compliant PU materials offers a viable entry strategy. A direct-to-consumer online retail model can capture niche demand for customized synthetic leather products.
For Investors and Strategic Acquirers: The accelerating adoption of water-based and solvent-free PU manufacturing technologies by Tier-1 automotive suppliers is the leading indicator that the market is shifting towards sustainable material leadership. Long-term viability for synthetic leather centers on companies with strong intellectual property in bio-based polymers and established relationships with automotive OEMs. Acquisition targets should include specialized firms with proven expertise in advanced microfiber production or compliant chemical formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Secures export-oriented manufacturing base for footwear and fashion accessories. |
| R&D in Bio-based PU | Addresses regulatory pressure from EU REACH and China's GB standards. |
| Automotive OEM Partnerships | Ensures early integration of advanced synthetic leather into new vehicle platforms. |
| Investment in Solvent-Free Production | Meets stringent VOC emission limits for vehicle interiors. |
| Acquisition of Microfiber Specialist | Enhances premium product portfolio for high-margin applications. |
Research Approach
Multi-period observation of synthetic leather production volumes and regulatory compliance rates anchored the trend analysis, supplemented by interviews with material scientists, automotive interior designers, footwear procurement managers, and chemical suppliers. Secondary validation involved reviewing customs data, national environmental agency reports, and corporate sustainability disclosures. This approach integrated bottom-up market intelligence with top-down industry trends.
Segment-weighting across product type, application, end-user, and regional manufacturing hubs informed the analytical framework over the projection horizon. Compound annual growth rates were derived from historical performance and anticipated shifts in material preference and regulatory impact. Key forecast inputs included projected electric vehicle production and global footwear consumption trends.
Inputs from major chemical producers and automotive OEMs were available through the study window; gaps in emerging bio-based feedstock supply data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Exosome Technologies Market
Others
Global on-Demand Laundry Service Market
Others
Digital LUX Meter Market
Others
Brown Ht Market
Others
Military Sensors Software Market
Others
Hardwood Market
Others
Boston Round Bottle Market
Others
Digital Mortgage Software Market
Others
Saudi Arabia Laser Hair Removal Market
Others
North America IT Device Market
Others
Hopper Dryers Market
Others
Plastic Films and Sheets Market
Others
Storage Dewars Market
Others
North America Luxury Car Market
Others
Workbench Tanks Market
Others
Reef Aquarium Market