
 Toy Packaging Market | 2026-2036
Toy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Packaging Market Analytics
China's Guangdong province is reconfiguring toy packaging supply chains through integrated paperboard and molded pulp capacity additions. Mondi leverages European recycled fiber networks to serve branded toy manufacturers with certified sustainable substrates. Hasbro anchors North American demand through direct vendor-managed inventory programs with big-box retailers. Stora Enso competes on Nordic forest certification credentials that satisfy multinational brand sustainability audits.
Toy packaging encompasses the structural and graphic enclosures engineered to protect, display, and merchandise play products from factory to point of sale, typically incorporating paperboard grades between 200-400 gsm, PET or PP windows, and UV-cured inks for shelf impact. Paper-based materials dominate volume for board games and construction sets where rigidity and print fidelity matter, while plastic blister packs sustain higher unit margins for action figures requiring visible product authentication. Interactive design complexity—incorporating QR-linked content, augmented reality triggers, or transformable structures—commands premium positioning as brands seek unboxing-driven social media engagement.
The US Consumer Product Safety Commission enforces small parts labeling and choke hazard warnings that dictate aperture dimensions and warning panel placement across all toy packaging formats. REACH and RoHS frameworks in Europe restrict phthalates and heavy metals in printed substrates and plastic films, compelling reformulation of conventional inks and coatings. China's GB standards for toy safety extend to packaging migration limits that affect adhesive and laminate selection for export-bound production. Stakeholders must monitor how extended producer responsibility schemes in California, Germany, and South Korea will reshape cost allocation between brand owners and packaging converters.
Market Dynamics
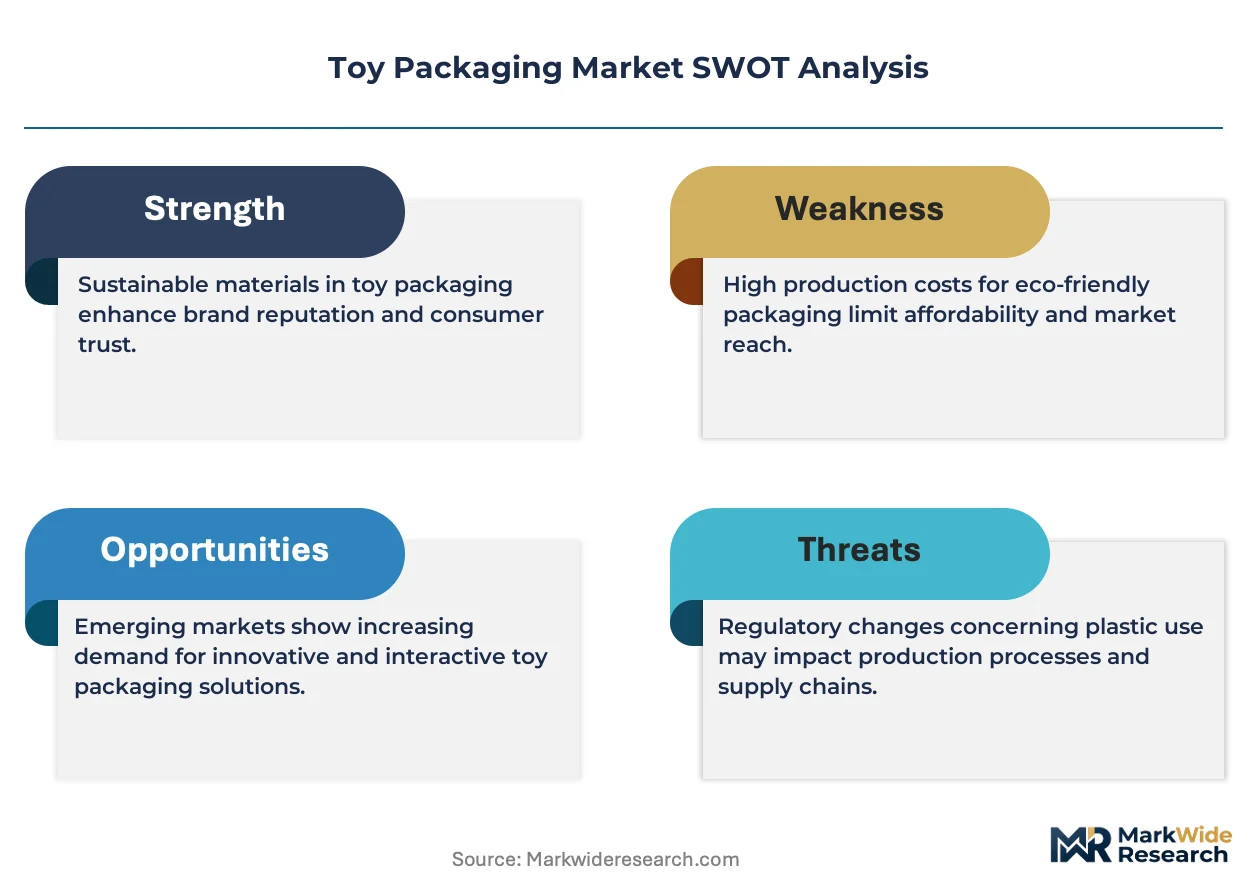
The EU's Packaging and Packaging Waste Regulation is forcing wholesale material transitions across toy packaging supply chains, compelling converters to certify fiber provenance and recovery pathways ahead of 2030 mandates.
Growth Catalysts
- Collectible adult hobbyist demand:Premium toy lines for adult collectors now command shelf space at specialty retailers and direct-to-consumer channels, expanding addressable market beyond traditional juvenile segments.
- REACH material compliance:European chemical restrictions on phthalates and heavy metals in printed substrates are accelerating adoption of water-based inks and bio-based laminates among export-oriented converters.
- Guangdong manufacturing cluster expansion:Integrated paperboard and molded pulp capacity additions in China's Pearl River Delta are shortening lead times for global toy brands sourcing packaging assembly.
Market Restraints
- Recycled fiber cost volatility:Post-consumer OCC pricing swings constrain margin predictability for converters dependent on European recycled fiber networks serving branded manufacturers.
- Single-source PET film concentration:Optical-grade PET window film for blister packs concentrates among Asian chemical producers, exposing toy packagers to supply disruption risk.
- Small parts testing bottlenecks:CPSC choke hazard aperture compliance requires third-party laboratory certification that extends new product launch timelines by 6-10 weeks.
Strategic Opportunities
- Extended producer responsibility tailwinds:California's SB 54 packaging waste regulations create first-mover advantage for converters offering closed-loop takeback programs to toy brand owners.
- QR-linked interactive packaging:Convergence of printed electronics with smartphone-native augmented reality enables unboxing-driven social media engagement that commands 15-25% packaging premiums.
- South Korean green procurement mandates:Government purchasing rules favoring recycled content create entry channel for certified sustainable substrates in Asia-Pacific toy distribution.
Industry Challenges
- Structural design-engineering talent scarcity:Shortage of packaging engineers capable of integrating transformable mechanics with child-safe aperture limits constrains interactive format development.
- Legacy UV curing line retrofit costs:Conventional solvent-based ink systems require capital-intensive LED-UV conversion to meet volatile organic compound emission limits in German production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Packaging Market |
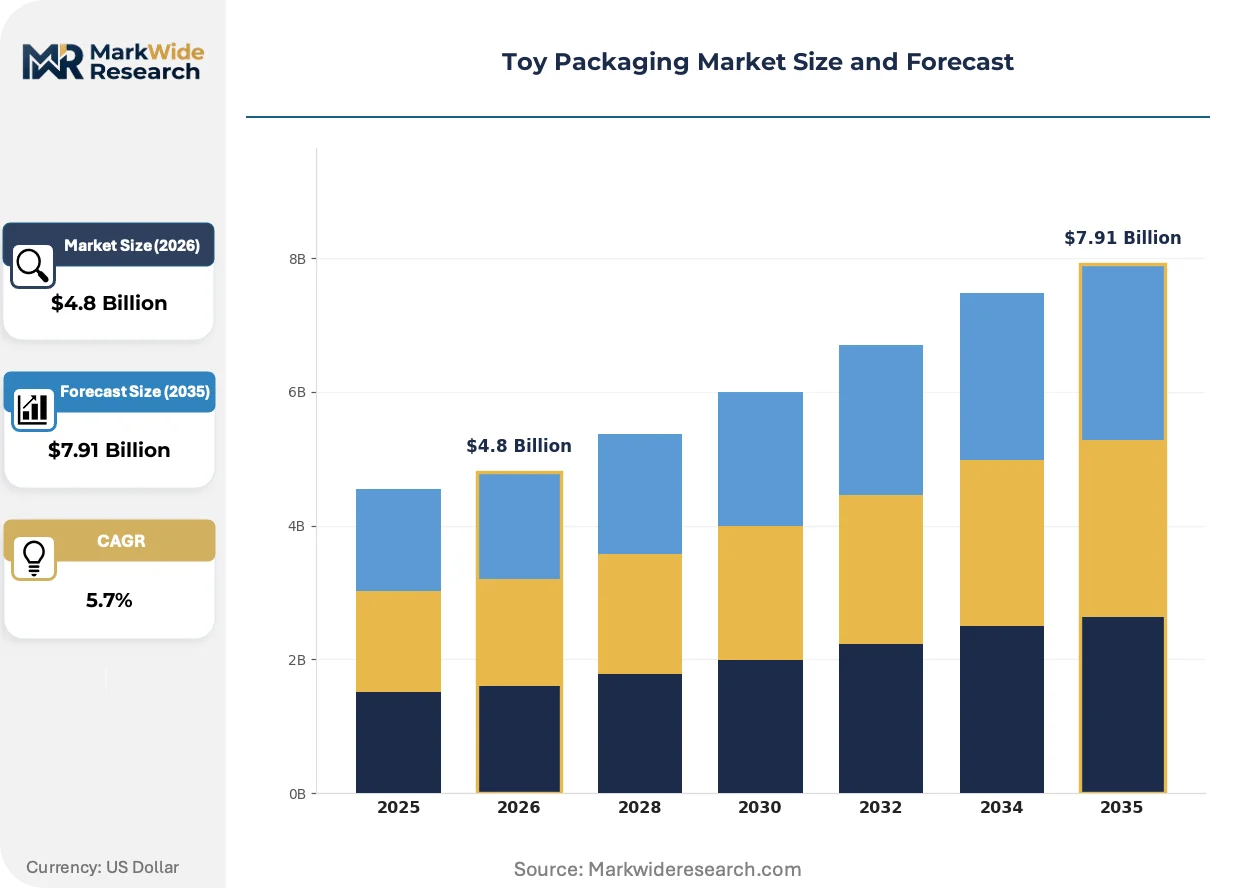
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Biodegradable Packaging Style: Box, Blister Pack, Bag, Sleeve End User: Retailers, Manufacturers, Wholesalers, Distributors Design Complexity: Simple, Interactive, Themed, Eco-friendly |
| Companies Covered | Mondi, Spin Master, Hasbro, Stora Enso, International Paper, Mattel, WestRock, Huhtamaki, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Packaging Market Evolving Landscape
Material authentication technologies and circular design protocols are redefining competitive differentiation in toy packaging, separating certified sustainable suppliers from conventional converters.
Molded pulp protective structures are migrating from secondary cushioning applications to primary retail-facing packaging for board games and construction sets. Hasbro and Mattel procurement teams now specify molded pulp tray inserts at 20-30% of new product briefs. This technology is migrating from cost-driven substitution to premium positioning as fiber-based aesthetics align with unboxing video content strategies.
REACH Annex XVII restrictions on microplastics in consumer products are compelling reformulation of conventional plastic window films and laminates. ECHA enforcement timelines require toy packagers to validate bio-based or mineral-filled alternatives by 2027. German and Nordic brand sustainability audits now exclude suppliers unable to demonstrate migration-compliant adhesive systems.
Direct vendor-managed inventory programs between toy manufacturers and big-box retailers are compressing order-to-delivery cycles from 8 weeks to 10-14 days. Walmart and Target distribution centers now require packaging suppliers to maintain 48-hour replenishment capability for high-velocity SKUs. This pattern is most visible in North American seasonal toy launches where inventory carry risk shifts upstream to converter balance sheets.
Toy Packaging Market Segmentation
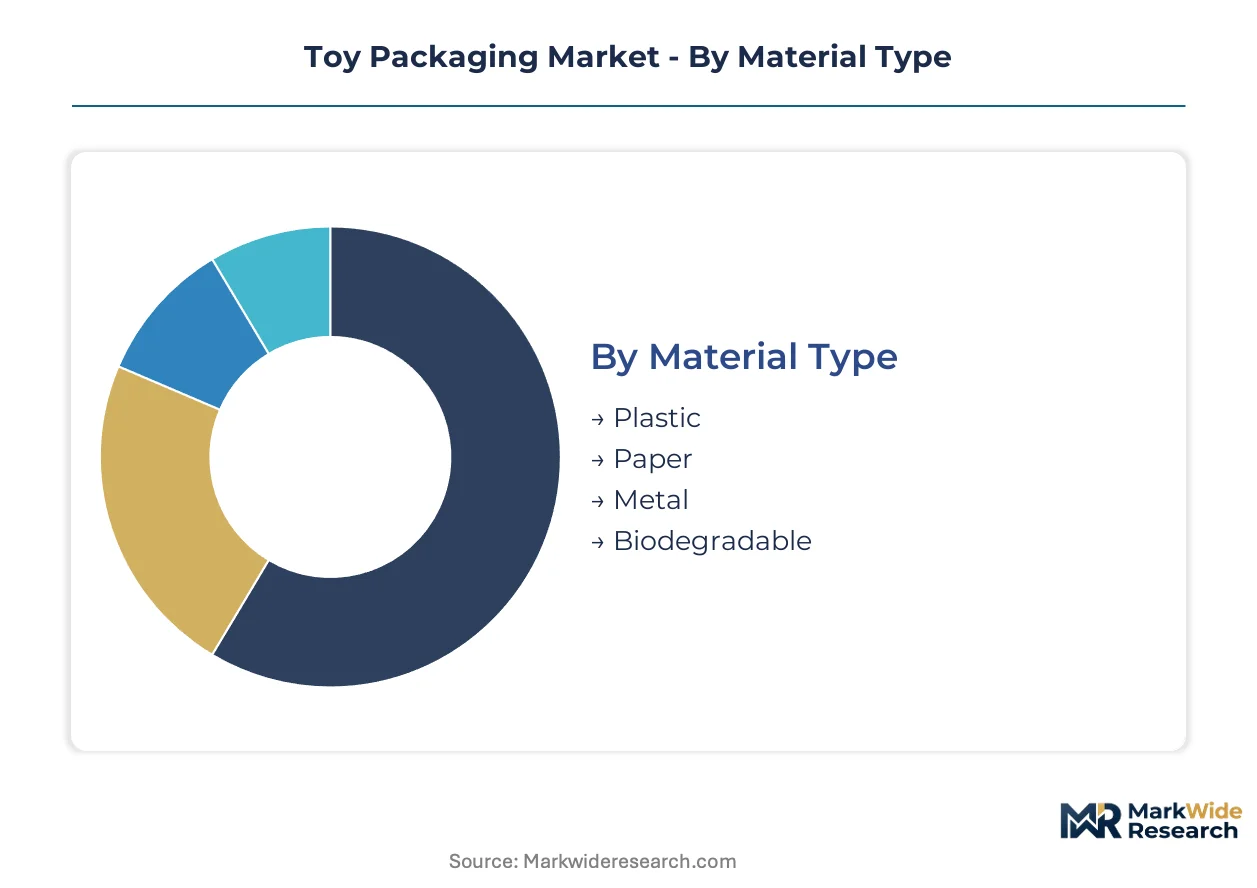
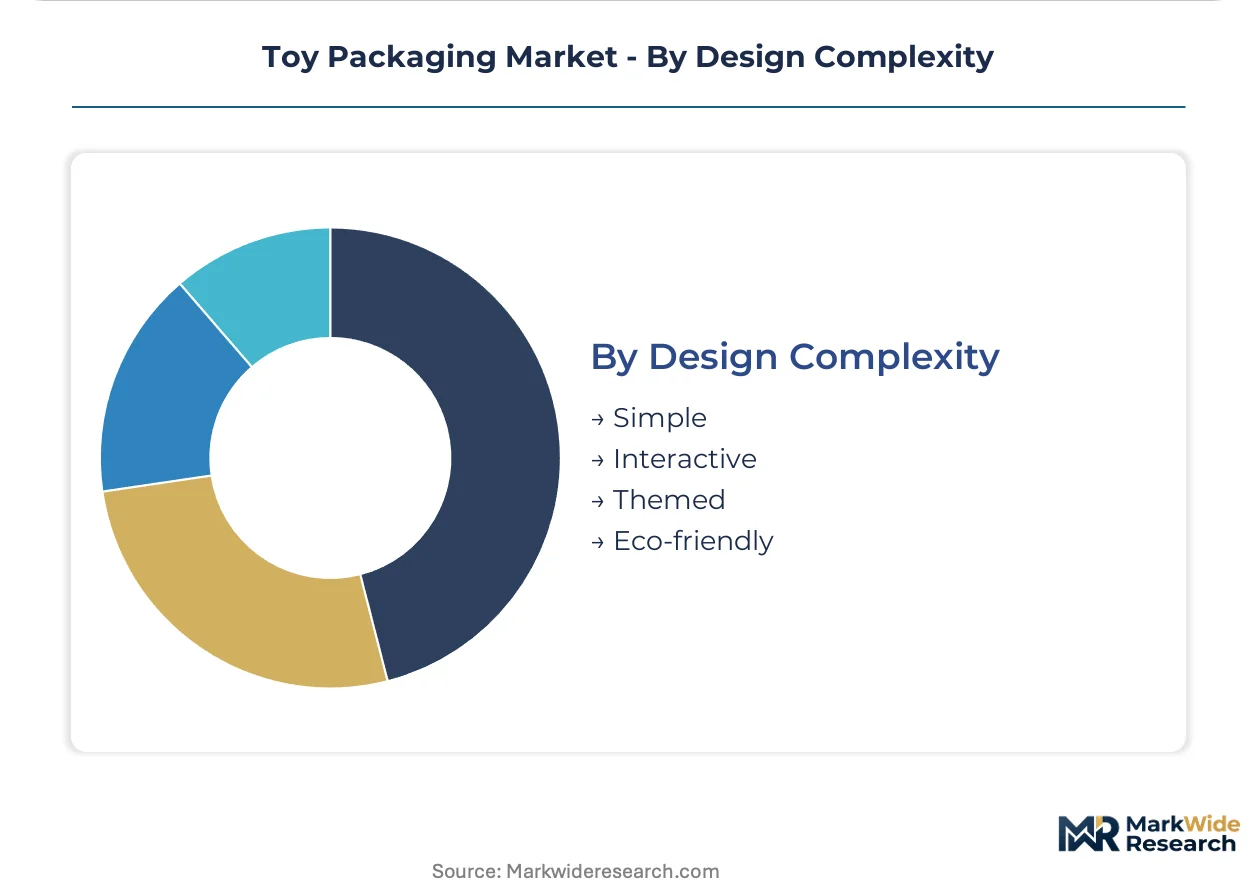
Material choices and design complexity tiers determine production economics and regulatory exposure for toy packaging converters. Packaging style and end-user channel configurations shape inventory velocity and margin capture across the value chain.
Material Type:
Plastic substrates turn over fastest in seasonal toy launches, while biodegradable alternatives face extended certification cycles that slow commercialization.
- Plastic:PET and PP films dominate blister pack windows and thermoformed trays with optical clarity requirements. Demand concentrates in Guangdong export assembly serving North American big-box retailers, where REACH migration limits are accelerating bio-based laminate trials.
- Paper:Coated folding cartonboard between 200-400 gsm anchors board game and construction set enclosures. German and Nordic brand sustainability audits favor FSC-certified fiber sourcing from integrated European mills.
- Metal:Tinplate and aluminum litho cans sustain premium collectible positioning for limited-edition hobbyist lines.
- Biodegradable:Molded pulp and PLA films gain specification share in EU-facing product briefs subject to Packaging and Packaging Waste Regulation mandates.
Paper dominates installed base. Biodegradable alternatives are where expansion concentrates.
Packaging Style:
Cost tier separation runs from commodity bag formats to engineered interactive boxes commanding 15-25% packaging premiums.
- Box:Rigid set-up and folding carton formats carry primary graphic branding for construction sets and board games. Walmart and Target vendor-managed inventory programs compress replenishment cycles to 48 hours for high-velocity SKUs.
- Blister Pack:Thermoformed plastic cavities bonded to printed card backing deliver visible product authentication for action figures. Optical-grade PET film supply concentrates among Asian chemical producers, exposing converters to disruption risk.
- Bag:Flexible polyethylene and laminated film pouches serve plush toys and low-margin impulse items.
- Sleeve:Printed paperboard bands and full-body shrink wraps provide secondary branding for bundled multi-packs.
Box formats dominate installed base. Blister pack specifications are where expansion concentrates.
End User:
Customer type determines order cadence, with direct retail programs running 10-14 day cycles versus manufacturer bulk procurement at 8-week horizons.
- Retailers:Walmart, Target, and specialty hobby chains drive vendor-managed inventory adoption that shifts carry risk upstream to converters. California SB 54 extended producer responsibility rules create first-mover advantage for closed-loop takeback providers.
- Manufacturers:Hasbro and Mattel procurement teams specify molded pulp inserts at 20-30% of new product briefs. Direct vendor programs compress design-to-delivery timelines for seasonal launches.
- Wholesalers:Regional distributors aggregate fragmented toy brand demand with less stringent sustainability certification requirements.
- Distributors:Third-party logistics providers manage packaging inventory positioning for import-dependent markets.
Retailers dominate installed base. Manufacturer direct programs are where expansion concentrates.
Design Complexity:
Margin tier separation stratifies between commodity simple formats and interactive designs integrating QR-linked augmented reality triggers.
- Simple:Standard folding carton and bag formats without secondary features serve price-sensitive juvenile toy segments. South Korean green procurement mandates exclude non-certified substrates from government purchasing channels.
- Interactive:Transformable structures and printed electronics enable unboxing-driven social media engagement. CPSC small parts testing requirements extend new product launch timelines by 6-10 weeks for aperture-critical designs.
- Themed:Licensed character graphics and seasonal decorative treatments command premium positioning for franchise-linked toy lines.
- Eco-friendly:Minimal ink coverage, mono-material construction, and explicit recycling instructions respond to EU EPR and German packaging waste regulations.
Simple designs dominate installed base. Interactive formats are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province concentrates integrated paperboard and molded pulp capacity that feeds both domestic Chinese consumption and export assembly for North American and European toy brands. This supply-side clustering shapes competitive dynamics across the value chain.
United States
Hasbro and Mattel procurement teams anchor North American demand through direct vendor-managed inventory programs with Walmart and Target. The CPSC enforces small parts labeling and choke hazard warnings that dictate aperture dimensions across all packaging formats. California's SB 54 extended producer responsibility regulations create first-mover advantage for converters offering closed-loop takeback programs.
Germany
REACH and RoHS frameworks restrict phthalates and heavy metals in printed substrates and plastic films, compelling reformulation of conventional inks and coatings. German brand sustainability audits now exclude suppliers unable to demonstrate migration-compliant adhesive systems. The country's packaging converters face capital-intensive LED-UV conversion requirements to meet volatile organic compound emission limits.
China
GB standards for toy safety extend to packaging migration limits that affect adhesive and laminate selection for export-bound production. The Pearl River Delta manufacturing cluster is reconfiguring supply chains through integrated paperboard and molded pulp capacity additions. Shenzhen and Dongguan converters now maintain 48-hour replenishment capability for high-velocity seasonal SKUs.
South Korea
Government purchasing rules favoring recycled content create entry channels for certified sustainable substrates in Asia-Pacific toy distribution. The country's green procurement mandates exclude non-certified substrates from official purchasing channels. Seoul-based converters are positioning to serve multinational brand sustainability audits.
United Kingdom
Specialty hobby retailers and direct-to-consumer channels expand addressable market for premium collectible toy lines among adult collectors. Post-Brexit regulatory alignment with EU Packaging and Packaging Waste Regulation maintains material recovery requirements for consumer goods. Midlands-based converters serve branded manufacturers with certified sustainable fiber sourcing.
Toy Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and film supply. The market exhibits tiered consolidation with multinational paper and packaging conglomerates competing against regional molded pulp specialists and Asian chemical film producers. Three archetypes dominate: integrated fiber-based substrate suppliers, specialty film and barrier converters, and vertically integrated toy manufacturers with captive packaging operations. Capacity expansion in Guangdong and strategic partnerships for certified fiber provenance represent the dominant competitive vectors.
Among Nordic forest-product conglomerates, Stora Enso occupies a position exemplifying certification-driven competitive differentiation. Mondi represents the integrated European recycled fiber network archetype serving branded toy manufacturers with sustainable substrates. Hasbro sits within the captive procurement tier, anchoring North American demand through direct vendor-managed inventory relationships with big-box retailers.
| Leading Market Players |
|---|
| Mondi |
| Spin Master |
| Hasbro |
| Stora Enso |
| International Paper |
| Mattel |
| WestRock |
| Huhtamaki |
| Amcor |
| Others |
Value Network & Pricing Analysis
Guangdong's Pearl River Delta manufacturing cluster concentrates integrated paperboard and molded pulp capacity that feeds export assembly for North American and European toy brands, translating supply-side density into asymmetric pricing power for converters serving multinational procurement teams.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across certified sustainable substrates versus conventional alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified fiber grades from generic recycled content and virgin pulp baselines. Pricing pressure stems from post-consumer OCC cost volatility that constrains margin predictability for European converters. Mass-market juvenile toy segments exhibit highest price sensitivity, while adult collectible hobbyist lines absorb premium positioning for interactive and eco-certified formats.
Supply Chain Analysis
Export-control restrictions on optical-grade PET film technology limit alternative supplier qualification for blister pack windows, reinforcing single-source concentration risk. Raw material flows draw from Chinese chemical producers for PET films, Nordic integrated mills for certified paperboard, and regional converters for molded pulp tooling. Supply chain risk centers on tariff exposure for North American-bound finished packaging assemblies. Distribution runs through vendor-managed inventory programs that compress replenishment cycles and shift carry risk upstream to converter balance sheets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toy packaging is approaching a platform-economics inflection as QR-linked augmented reality triggers and closed-loop takeback programs create ecosystem lock-in between brands, converters, and retail distribution networks.
For Market Incumbents: Build certification moats around EU EPR compliance and California SB 54 closed-loop infrastructure ahead of 2030 mandates. Defensive moves should anchor on Nordic forest certification credentials that satisfy multinational sustainability audits, while capacity additions in Guangdong shorten lead times for seasonal toy launches. Threat substitution from biodegradable alternatives and margin compression in commodity board grades demand proactive fiber provenance investments. For New Entrants and Emerging Players: Build out molded pulp primary packaging capabilities targeting Hasbro and Mattel procurement specifications now capturing 20-30% of new product briefs. Most penetrable white space sits in South Korean green procurement channels favoring recycled content substrates. Go-to-market positioning should emphasize 48-hour replenishment capability for Walmart and Target vendor-managed inventory programs. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility schemes will reshape cost allocation between brand owners and packaging converters. Acquisition targets should cluster around regional molded pulp specialists with EU EPR-ready certification stacks. Signal to monitor is REACH Annex XVII enforcement timelines compelling microplastic-free window film alternatives by 2027.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Fiber Provenance Investment | FSC and PEFC credentials satisfy German brand sustainability audits that now exclude non-compliant suppliers. |
| Molded Pulp Capacity Expansion | Primary retail-facing tray inserts capture specification share from Hasbro and Mattel procurement teams. |
| LED-UV Curing Line Retrofit | Emission compliance with German VOC limits enables continued production access for EU-facing toy brands. |
| Closed-Loop Takeback Program Launch | California SB 54 first-mover positioning secures preferred supplier status with Mattel and Target sustainability teams. |
| QR-Linked Interactive Packaging Development | Augmented reality triggers command 15-25% packaging premiums through unboxing-driven social media engagement. |
Research Methodology
A spread of perspectives from procurement directors at multinational toy manufacturers, sustainability leads at big-box retailers, packaging engineers at Guangdong converters, and regulatory affairs specialists at European fiber suppliers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC filings from publicly traded packaging conglomerates, EU ECHA regulatory databases, and CPSC enforcement archives. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Demand-supply balance dynamics across material type, packaging style, and end-user channel configurations anchored the analytical framework over the projection horizon. Segmentation dimensions modeled included substrate grade tier, design complexity tier, and regional regulatory cluster. CAGRs derived from regression analysis against historical production data and forward-looking procurement pipeline visibility. Industry-specific inputs incorporated REACH migration limit compliance costs and vendor-managed inventory adoption curves.
Sensitivities concentrate around EU Packaging and Packaging Waste Regulation enforcement timelines, post-consumer OCC price volatility, and CPSC small parts testing bottleneck durations. Forecasts reflect documented assumptions on certification adoption rates and retail channel consolidation patterns. Material shifts in optical-grade PET film supply concentration or German VOC emission limit stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rugged Tablet Market
Others
Sports Events Market
Others
Latin America Domestic CEP Market
Others
Asia-Pacific Legal Services Market
Others
Depth Gauge Market
Others
Dry Washer Market
Others
Global Microcontroller Embedded Systems Market
Others
Food Technology Market
Others
Folding Mobile Phone Market
Others
High Frequency Vibrator Market
Others
South America Automotive LED Lighting Market
Others
Composite Copper Foil Production Equipment Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Egg Market
Others
Mine Rescue Vehicle Market
Others
Turbo Mills Market