
 Wheel Loaders Market | 2026-2036
Wheel Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Loaders Market Outlook
Emissions-compliant Tier 4 Final specification is rotating through the product mix as fleet operators face compliance deadlines in North America and Europe. Caterpillar Inc. leverages its integrated powertrain manufacturing to control certification costs across multiple horsepower classes. XCMG sustains aggressive export pricing from its Xuzhou production base, while Komatsu Ltd. differentiates through its Intelligent Machine Control automation suite.
A wheel loader is a four-wheeled heavy equipment machine with an articulated steering frame and a front-mounted hydraulically operated bucket, typically rated by operating load from one to fifty-plus metric tons, designed primarily for scooping, lifting, and transporting loose materials over short distances. Compact and standard product types dominate unit shipments in urban construction and agricultural settings, though heavy-duty configurations capture disproportionate margin pools in mining contracts. Diesel fuel type retains installed-base dominance, yet electric and hybrid segments attract replacement interest where grid infrastructure or on-site renewables support charging logistics.
EPA Tier 4 Final, EU Stage V, and China's National VI-equivalent off-road standards collectively tighten particulate and NOx limits, forcing engine redesigns and after-treatment hardware that add cost but also create technical barriers for smaller assemblers. The US Occupational Safety and Health Administration and ISO 5006 visibility standards further shape cab design and camera-system specifications. Stakeholders must weigh electrification capital commitments against residual-value risk in markets where charging infrastructure remains fragmented.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission mandates are forcing diesel-electric hybrid architectures into the product mix faster than supply chains can absorb the transition costs.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Fleet operators in North America face replacement cycles that favor newer, certified equipment over retrofitting aging machines.
- Australian and Chilean mining expansion:Heavy-duty wheel loader fleets are scaling to replace aging equipment in copper and iron ore extraction corridors.
- China's inland infrastructure corridors:National highway construction zones and port expansion projects concentrate demand for standard and compact product types.
Market Restraints
- After-treatment hardware costs:Diesel particulate filters and selective catalytic reduction systems add procurement burden that compresses margins for rental fleet operators.
- Charging infrastructure fragmentation:Electric segment growth faces residual-value risk in markets where grid reliability or on-site renewable capacity remains inconsistent.
- Engine certification concentration:A limited supplier base controls EPA and EU-compliant powertrain platforms, creating procurement bottlenecks for smaller assemblers.
Strategic Opportunities
- India's national highway construction zones:Standard-capacity wheel loaders face underpenetrated demand as state-level contractors modernize equipment fleets.
- Intelligent Machine Control convergence:Automation suites integrating GPS grading and payload measurement create premium pricing power in mining contracts.
- EU Green Deal procurement incentives:Public infrastructure tenders increasingly weight lifecycle emissions, favoring hybrid and electric configurations in municipal applications.
Industry Challenges
- Powertrain engineering talent scarcity:Diesel-electric hybrid development requires skill sets concentrated among a narrow cohort of suppliers and OEM engineering centers.
- ISO 5006 visibility certification timelines:Cab redesign and camera-system integration for compliance create product launch delays across multiple horsepower classes.
- Legacy fleet integration friction:Telematics-enabled machines face interoperability barriers with older equipment in mixed-contractor job sites.
Report Scope
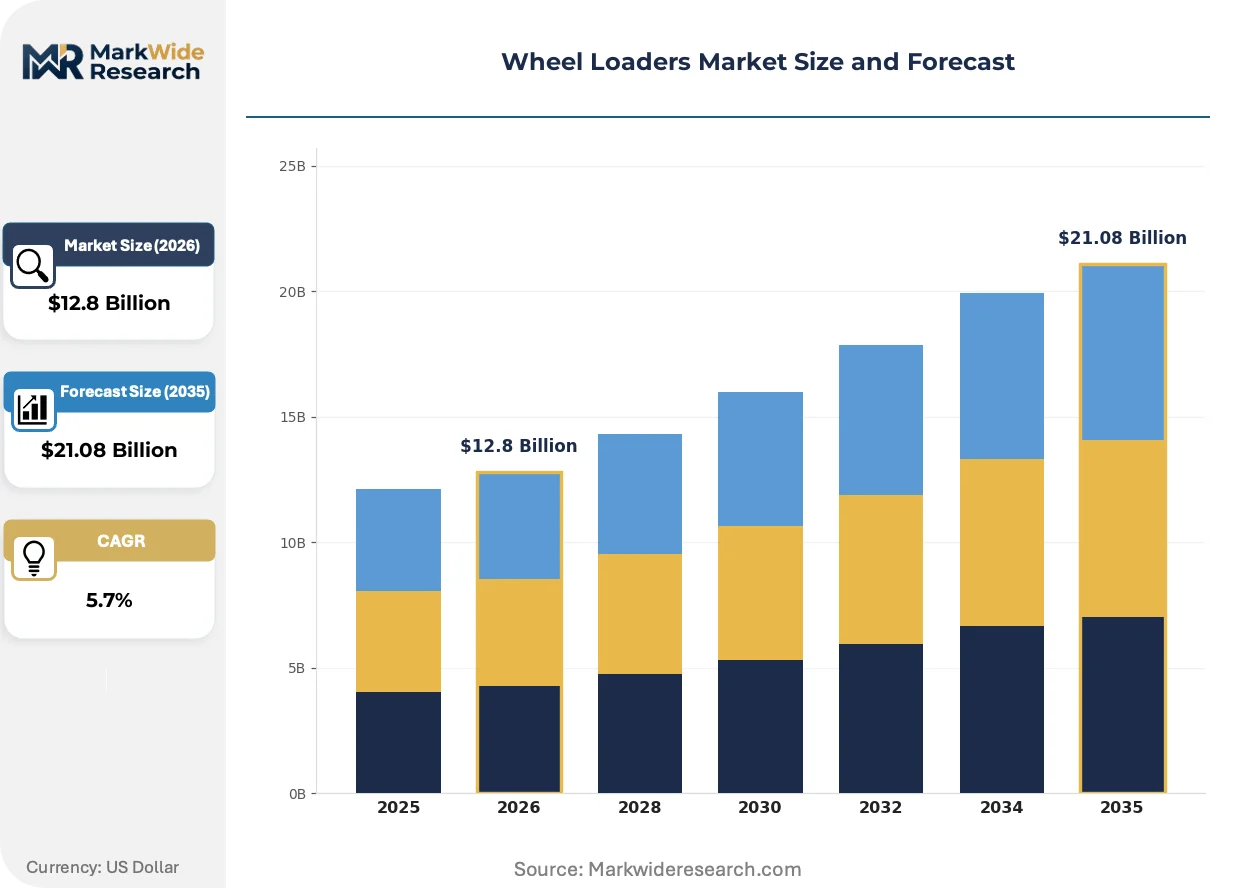
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Loaders Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Standard, Large, Heavy-Duty End User: Construction, Mining, Agriculture, Forestry Fuel Type: Diesel, Electric, Hybrid, Natural Gas Application: Material Handling, Road Construction, Earth Moving, Loading |
| Companies Covered | Deere & Company, JCB Ltd., Caterpillar Inc., Xuzhou Construction Machinery Group (XCMG), SANY Group, Komatsu Ltd., Liebherr Group, Kubota Corporation, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Loaders Market Strategic Shifts
Electrification pathways and automation integration are bifurcating the competitive landscape between premium technology leaders and cost-optimized volume producers.
Diesel-electric hybrid powertrains are supplanting conventional mechanical drivelines in the 20-50 metric ton operating load class. Mining contractors in Australia and Chile are specifying hybrid configurations for fuel efficiency in high-cycle loading operations. This technology compression is narrowing the addressable market for pure diesel platforms in heavy-duty segments.
EU Stage V particulate and NOx limits are forcing engine redesigns that favor integrated powertrain manufacturing over outsourced component sourcing. The regulation compresses time-to-market for new models while raising technical barriers for smaller assemblers. Compact and standard product categories face the steepest compliance cost escalation relative to their unit economics.
Service contract unbundling is fragmenting traditional dealer revenue models in North American and European markets. Fleet managers are separating maintenance agreements from equipment financing, pressuring distributor margins. This pattern is most visible in municipal and urban construction verticals where total cost of ownership transparency drives procurement decisions.
Wheel Loaders Market Segmentation
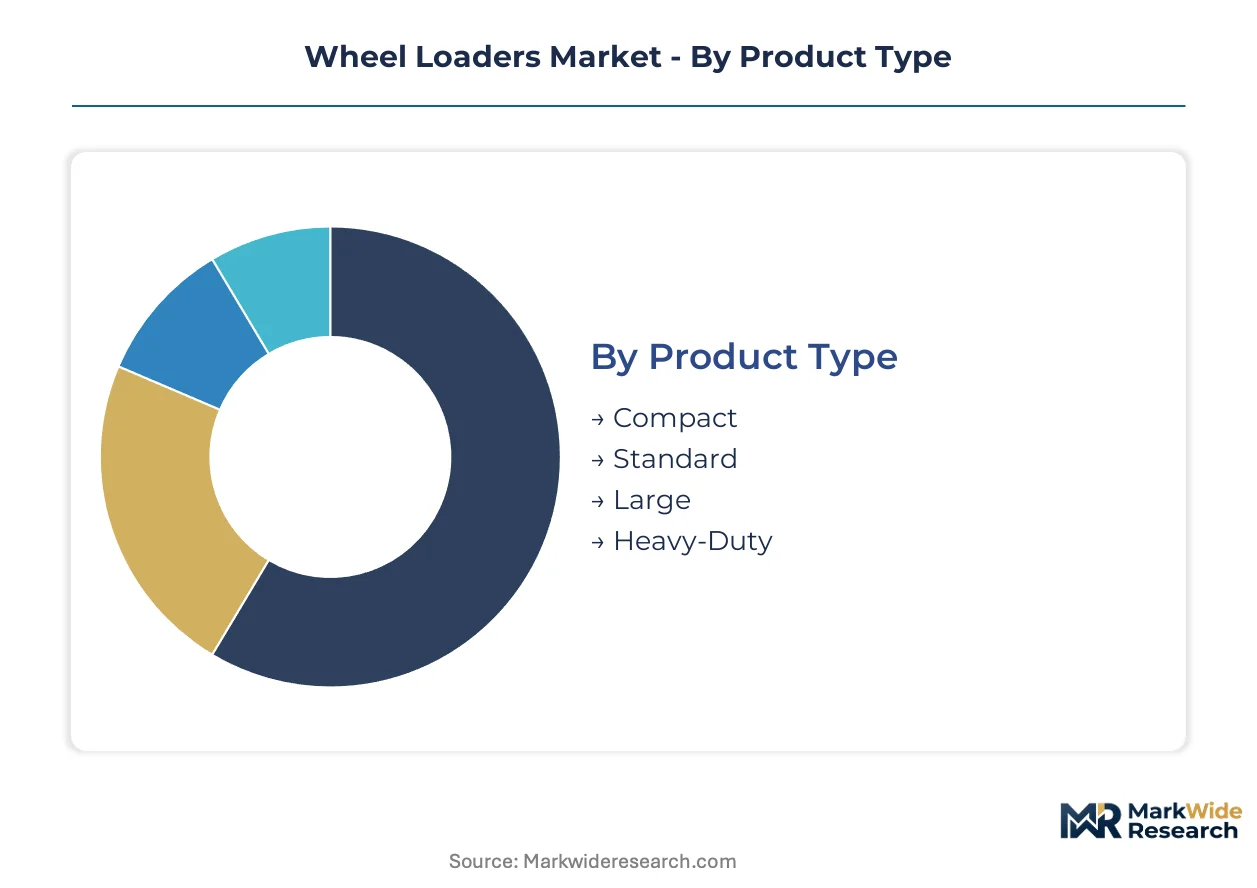
Wheel loader procurement channels diverge sharply by segment: rental fleets favor compact and standard units for urban job sites, while mining contractors negotiate direct OEM contracts for heavy-duty configurations. Understanding these channel dynamics illuminates where margin pools concentrate and which segments face the steepest compliance cost escalation.
Product Type:
Channel mix varies dramatically across size classes, with compact units flowing through dealer rental networks and heavy-duty machines sold through direct mining procurement channels.
- Compact:Operating loads under 5 metric tons serve urban construction and agricultural settings where maneuverability constraints dominate specification decisions. Demand clusters in China's inland infrastructure corridors and India's national highway construction zones as state-level contractors modernize fleets. Rental channels capture disproportionate volume here.
- Standard:The 5-20 metric ton range balances versatility with operating cost, anchoring municipal procurement and general construction applications. India's highway expansion and EU municipal tenders under Green Deal incentives drive replacement cycles. This segment faces acute margin pressure from after-treatment hardware costs relative to unit economics.
- Large:20-50 metric ton machines serve quarry operations and bulk material handling where cycle efficiency trumps capital cost sensitivity. Australian and Chilean mining operators specify these units for copper and iron ore extraction corridors.
- Heavy-Duty:Exceeding 50 metric tons, these configurations command premium pricing in autonomous mine operations where Intelligent Machine Control integration creates differentiation. Direct OEM relationships dominate procurement.
Standard units dominate installed base by unit volume. Heavy-Duty is where expansion concentrates as mining automation investments accelerate.
End User:
Cost tier stratification separates premium technology adopters from price-sensitive volume purchasers across end-use verticals.
- Construction:Municipal and urban contractors prioritize total cost of ownership transparency, unbundling service contracts from equipment financing. EPA Tier 4 Final compliance deadlines in North America force replacement cycles that favor certified equipment over retrofitting.
- Mining:Australian and Chilean operators are expanding heavy-duty fleets to replace aging equipment, specifying diesel-electric hybrid architectures for fuel efficiency in high-cycle loading operations. Automation suites command premium pricing here.
- Agriculture:Compact and standard units serve grain handling and livestock operations where seasonal utilization patterns favor rental or used equipment channels.
- Forestry:Specialized cab configurations and undercarriage protection differentiate this niche, with demand concentrated in Nordic and Canadian timber corridors.
Construction anchors unit shipments. Mining is where technology premiums expand most quickly.
Fuel Type:
Application requirements and infrastructure availability determine which powertrain architectures penetrate specific use cases.
- Diesel:Retains installed-base dominance across all operating load classes, though EPA Tier 4 Final and EU Stage V standards force engine redesigns and after-treatment hardware that compress margins. A limited supplier base controls compliant powertrain platforms, creating procurement bottlenecks.
- Electric:Grid-dependent configurations attract interest where on-site renewables or reliable charging infrastructure support logistics, primarily in municipal and indoor material handling applications. Residual-value risk persists in markets with fragmented charging networks.
- Hybrid:Diesel-electric architectures are gaining share fastest in the 20-50 metric ton class as mining contractors prioritize fuel efficiency. Powertrain engineering talent scarcity constrains development timelines.
- Natural Gas:Niche adoption in stationary or short-haul applications where fueling infrastructure exists, particularly in North American shale extraction regions with captive gas supply.
Diesel dominates installed base. Hybrid is where expansion concentrates as emission mandates tighten.
Application:
Customer type and project duration shape whether rental, lease, or purchase channels capture equipment deployment.
- Material Handling:Port expansion projects and warehouse construction drive demand for compact and standard units with quick-attach coupler systems. Cycle counts and operating hours favor rental fleet deployment.
- Road Construction:National highway projects in China and India concentrate demand for standard-capacity machines with GPS grading integration. State-level contractors represent underpenetrated demand in emerging markets.
- Earth Moving:Mass excavation contracts require heavy-duty configurations where payload measurement systems create productivity advantages. Direct OEM sales dominate this application.
- Loading:High-cycle mining and quarry operations specify hybrid powertrains and automation suites, with service contracts increasingly unbundled from financing arrangements.
Material Handling dominates rental channel volume. Road Construction is where public procurement incentives reshape competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing hubs dominate international supply, while import-dependent markets in Australia and Chile absorb heavy-duty units for mining expansion. Trade balances tilt toward surplus in production centers and deficit in resource-extraction economies.
China
Inland infrastructure corridors and port expansion projects concentrate demand for compact and standard wheel loaders. The Ministry of Ecology and Environment enforces National VI-equivalent off-road emission standards that tighten particulate limits. Xuzhou anchors production clusters where export pricing sustains aggressive international penetration.
United States
Municipal contractors and rental fleets face replacement cycles driven by EPA Tier 4 Final compliance deadlines. The Environmental Protection Agency certifies powertrain platforms that limit supplier options for smaller assemblers. Midwest construction markets and Texas shale regions absorb standard and heavy-duty configurations through dealer networks.
Australia
Copper and iron ore extraction corridors in Western Australia and Queensland drive fleet expansion for heavy-duty diesel-electric hybrid units. The Therapeutic Goods Administration parallel-import framework does not constrain mining equipment, though state-level environmental permits shape site-specific procurement. Pilbara Basin operations specify automation-integrated loaders for autonomous mine programs.
Chile
Atacama Desert copper mines and coastal port facilities require robust loading equipment for high-cycle material handling. The national mining regulator enforces progressive emission standards that accelerate hybrid adoption in new fleet acquisitions. Antofagasta and Calama industrial clusters concentrate operator demand for 20-50 metric ton class machines.
Germany
Municipal tenders under EU Green Deal procurement incentives weight lifecycle emissions in equipment selection. The Kraftfahrt-Bundesamt type-approval process for off-road machinery creates certification timelines that delay product launches. Bavarian and North Rhine-Westphalia construction consortiums pilot electric configurations where grid infrastructure supports charging logistics.
Wheel Loaders Market Competitive Environment
Listed leaders compete with private specialists across integrated powertrain control, with public companies leveraging capital markets for certification cost absorption while private firms concentrate on regional customization. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive engine manufacturing, construction equipment specialists with outsourced powertrain sourcing, and emerging electric-focused entrants. Consolidation pressure operates through M&A activity targeting automation software capabilities and strategic partnerships securing battery supply agreements.
Among diversified industrial conglomerates, Caterpillar Inc. and Deere & Company occupy positions exemplifying integrated powertrain manufacturing archetypes. Komatsu Ltd. and Volvo Construction Equipment sit within the automation-premium tier where Intelligent Machine Control suites create differentiation. Xuzhou Construction Machinery Group represents the export-volume archetype with production gravity concentrated in Chinese manufacturing clusters. SANY Group and JCB Ltd. exemplify regional-market specialists with structural positions in domestic procurement channels.
| Leading Market Players |
|---|
| Deere & Company |
| JCB Ltd. |
| Caterpillar Inc. |
| Xuzhou Construction Machinery Group (XCMG) |
| SANY Group |
| Komatsu Ltd. |
| Liebherr Group |
| Kubota Corporation |
| Volvo Construction Equipment |
| Others |
Value Chain & Pricing Dynamics
Ninety-day engine lead times for EPA Tier 4 Final certified powertrains concentrate procurement leverage among Caterpillar, Komatsu, and Deere, compressing margin pools for rental fleet operators while amplifying pricing power for integrated manufacturers with captive engine supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and after-sales service bundling, with EPA Tier 4 Final compliance creating a two-speed market. Cost compression in the standard tier is intensifying because after-treatment hardware adds fixed cost without proportional value capture. Municipal contractors exhibit highest price sensitivity, while mining operators prioritize total cost of ownership transparency over unit procurement cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane have elevated inbound logistics costs for European assemblers sourcing from Chinese component clusters. Supply concentrates in China, Germany, and Japan for axles, hydraulics, and electronic control modules. The chain draws from high-grade steel mills in South Korea and specialized tire manufacturers in Southeast Asia. Single-source vulnerability around EPA-certified engine platforms creates procurement bottlenecks. Distribution runs through dealer rental networks for compact units and direct OEM channels for heavy-duty mining configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as emission mandates splinter demand between compliance-heavy mature markets and cost-optimized emerging corridors.
For Market Incumbents: Secure backward integration into powertrain manufacturing to defend against engine supplier concentration risk. Expand certified engine capacity in North American and European production hubs before Tier 4 Final deadlines harden procurement bottlenecks. Prioritize automation software R&D to maintain premium pricing in mining contracts where Intelligent Machine Control creates differentiation. For New Entrants and Emerging Players: Lead with electric compact configurations in EU municipal tenders where Green Deal procurement incentives weight lifecycle emissions. India's national highway construction zones represent the most penetrable geography for standard-capacity equipment. Pursue telematics-enabled service unbundling as a go-to-market angle to capture maintenance revenue separate from equipment financing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core construction equipment divisions. Five-to-ten year viability hinges on electrification capital deployment capability. Monitor battery supply agreement announcements as the inflection signal for which OEMs can scale electric platforms beyond pilot deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Backward Integration | Captive engine manufacturing insulates Caterpillar and Deere from EPA certification bottlenecks affecting smaller assemblers. |
| Intelligent Machine Control Investment | Komatsu's automation suite commands premium pricing in Australian Pilbara Basin autonomous mine programs. |
| Battery Supply Agreement | Strategic partnerships with cell manufacturers determine which OEMs can scale electric wheel loaders beyond municipal pilots. |
| Service Contract Unbundling | Separating maintenance from financing pressures traditional dealer margins while creating standalone recurring revenue streams. |
| India Distribution Expansion | State-level contractor fleet modernization in highway construction zones offers volume growth for early entrants. |
Study Parameters
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across the primary research phase. Secondary validation drew from SEC 10-K filings, customs and trade data, EPA certification databases, and construction equipment rental fleet disclosures. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from reported revenue segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, fuel architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed shipment data and reported backlog trends. Mining automation investment cycles and municipal procurement incentive structures served as industry-specific forecast inputs.
Underlying assumptions cover stable emission enforcement timelines and continued mining capital expenditure commitment, with deviation risk concentrated in charging infrastructure buildout pace for electric segments and engine supplier consolidation dynamics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Fuel Sensor Market
Vehicle Components
HCV Axles Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Child Seats Market