
 Japan Indoor LBS Market | 2026-2036
Japan Indoor LBS Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Indoor LBS Market Intelligence
Market Context
Japan's transportation hub infrastructure is pivoting toward real-time passenger flow management and indoor wayfinding systems. NTT Docomo leverages its nationwide 5G infrastructure to deliver sub-meter positioning accuracy for dense urban environments. Hitachi anchors industrial deployments through its IoT platform integrations in factory and logistics settings. Google LLC competes on mapping data density, sustaining advantage through Street View-derived indoor cartography.
Technical Definition and Segment Structure
Japan Indoor LBS encompasses location determination technologies that calculate device position within enclosed structures using Wi-Fi signal triangulation, Bluetooth beacon proximity, RFID tag detection, or ultrasonic time-of-flight measurement to enable navigation, asset monitoring, and spatial analytics where satellite signals degrade. Bluetooth-based deployments command expanding share due to beacon hardware cost declines and Apple-Android ecosystem standardization, while Wi-Fi fingerprinting retains dominance in legacy building retrofits where infrastructure reuse reduces capital outlay. Mapping Solutions capture disproportionate margin pools as foundational data layers require specialized survey-grade capture and continuous refresh cycles.
Regulatory Framework and Outlook
METI's digital transformation guidelines mandate interoperability standards for smart city infrastructure, directly shaping procurement specifications for municipal indoor positioning projects. JIS standards govern electromagnetic emissions from dense beacon deployments in healthcare and educational settings, constraining hardware design choices. The Personal Information Protection Commission enforces location data anonymization protocols that elevate compliance costs for Location Analytics providers. Stakeholders must monitor evolving spectrum allocation decisions by the Ministry of Internal Affairs and Communications, as 6GHz Wi-Fi expansion would recalibrate technology cost-performance tradeoffs across all application segments.
Market Dynamics
METI's smart city directives are compressing deployment timelines for indoor positioning infrastructure across Japanese commercial districts. The regulatory push for digital interoperability is forcing technology vendors to standardize beacon protocols and mapping data formats ahead of municipal procurement cycles.
Growth Catalysts
- 5G Infrastructure Density:NTT Docomo's nationwide small cell rollout enables sub-meter positioning accuracy in dense urban environments. Transportation hubs in Tokyo and Osaka are retrofitting passenger flow systems to leverage this capability.
- Healthcare Facility Modernization:Hospital administrators deploy indoor navigation for patient wayfinding and asset tracking. METI's digital transformation guidelines mandate location-aware infrastructure in new public medical construction.
- Bluetooth Beacon Cost Decline:Hardware prices for proximity sensors have fallen below deployment thresholds for mid-sized retail and logistics operations. Apple-Android ecosystem standardization reduces integration friction for developers.
Market Restraints
- Legacy Wi-Fi Infrastructure Lock-in:Commercial buildings completed before 2018 contain aging access point architectures unsuited for fingerprinting-based positioning. Full hardware replacement cycles stretch capital recovery timelines.
- Personal Information Protection Commission Compliance:Location data anonymization protocols elevate operational costs for analytics providers. Continuous audit requirements consume engineering resources.
- Ultrasonic Time-of-Flight Limitations:Audio-based positioning systems suffer interference from HVAC noise and crowd density. Deployment remains restricted to controlled environments like museum galleries.
Strategic Opportunities
- Hokkaido and Kyushu Regional Expansion:Secondary urban centers lack mature indoor positioning infrastructure. Municipal governments in Sapporo and Fukuoka issue smart city tenders with localization requirements.
- Industrial IoT Convergence:Integration of indoor LBS with Hitachi's factory automation platforms creates predictive maintenance applications. Manufacturing facilities track mobile equipment and personnel safety zones simultaneously.
- 6GHz Wi-Fi Spectrum Allocation:Ministry of Internal Affairs and Communications deliberations on unlicensed band expansion would recalibrate cost-performance tradeoffs. Early certification positions vendors for infrastructure upgrade cycles.
Industry Challenges
- Survey-Grade Mapping Talent Scarcity:Specialized technicians capable of lidar-based indoor cartography command premium compensation. Training pipelines through technical universities remain underdeveloped.
- JIS Electromagnetic Emission Certification:Dense beacon deployments in healthcare settings require lengthy testing protocols. Product launch timelines extend six to nine months beyond initial engineering completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Indoor LBS Market |
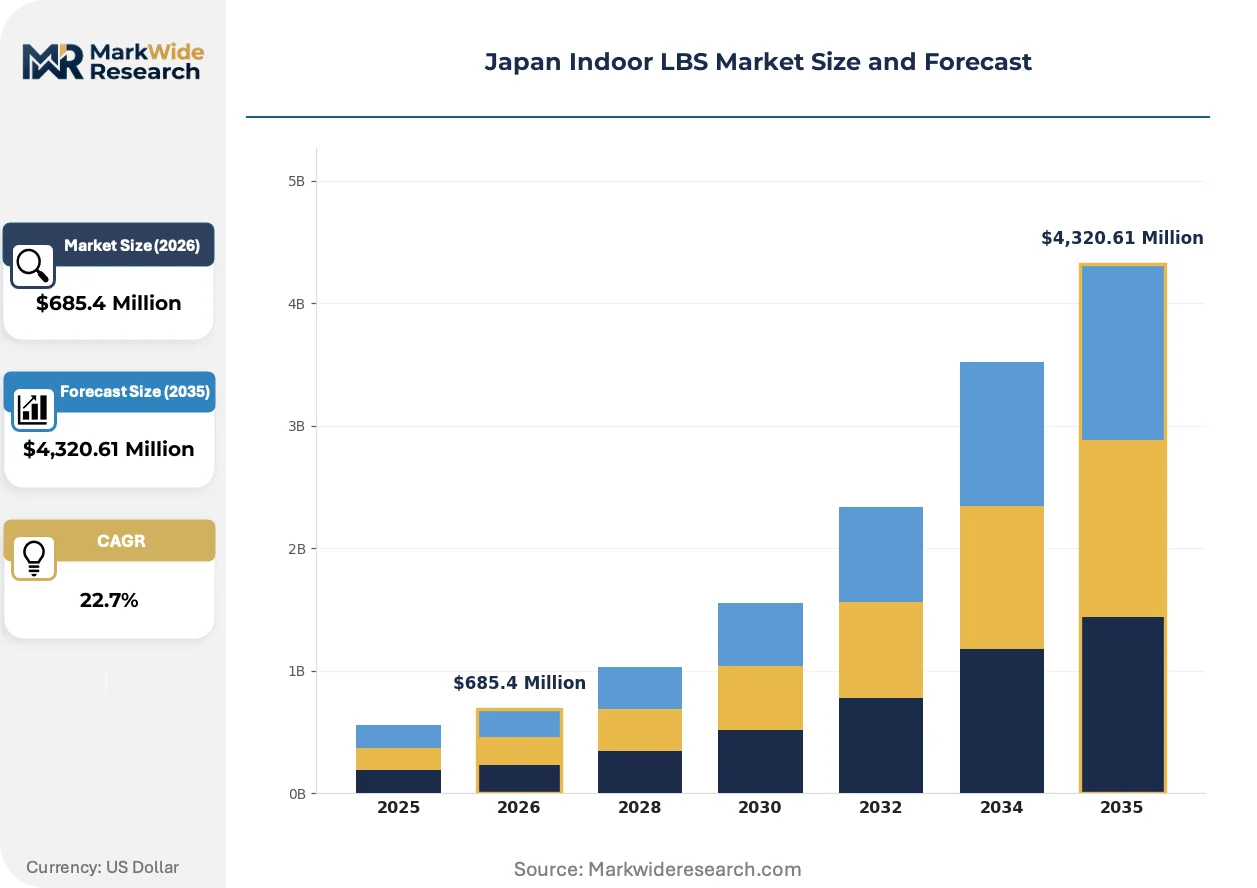
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,320.61 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, RFID, Ultrasound Application: Retail Navigation, Emergency Services, Asset Tracking, Smart Buildings End User: Retailers, Healthcare Providers, Transportation, Educational Institutions Solution: Mapping Solutions, Location Analytics, Navigation Tools, Proximity Marketing |
| Companies Covered | Google LLC, Hitachi, Ltd, Kokusai Kogyo Co., Ltd., Waveon Co., Ltd., AGOOP Corp., NTT Docomo, Inc., SoftBank, Rakuten, IndoorAtlas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Indoor LBS Market Strategic Shifts & Innovations
Technology convergence between positioning hardware and building management systems is redefining procurement specifications for Japanese infrastructure projects. Vendors now compete on platform integration depth rather than standalone accuracy metrics.
Ultra-wideband chipsets are modularizing across smartphone and IoT device categories. Automotive suppliers in Aichi Prefecture adopt these components for factory floor asset tracking. The technology is modularizing supplier relationships as semiconductor vendors bypass traditional system integrators to serve end-users directly.
METI's interoperability mandates for smart city infrastructure are reshaping procurement specifications for municipal indoor positioning projects. Vendors must demonstrate cross-platform data exchange capabilities to qualify for public tenders. Healthcare and educational facilities face the steepest compliance adjustments due to existing vendor lock-in.
Facility managers increasingly specify integrated service contracts bundling hardware deployment with continuous mapping refresh cycles. Traditional equipment-only sales channels lose share to managed service providers. Tokyo commercial real estate operators lead this transition, demanding uptime guarantees and accuracy SLAs.
Japan Indoor LBS Market Segmentation
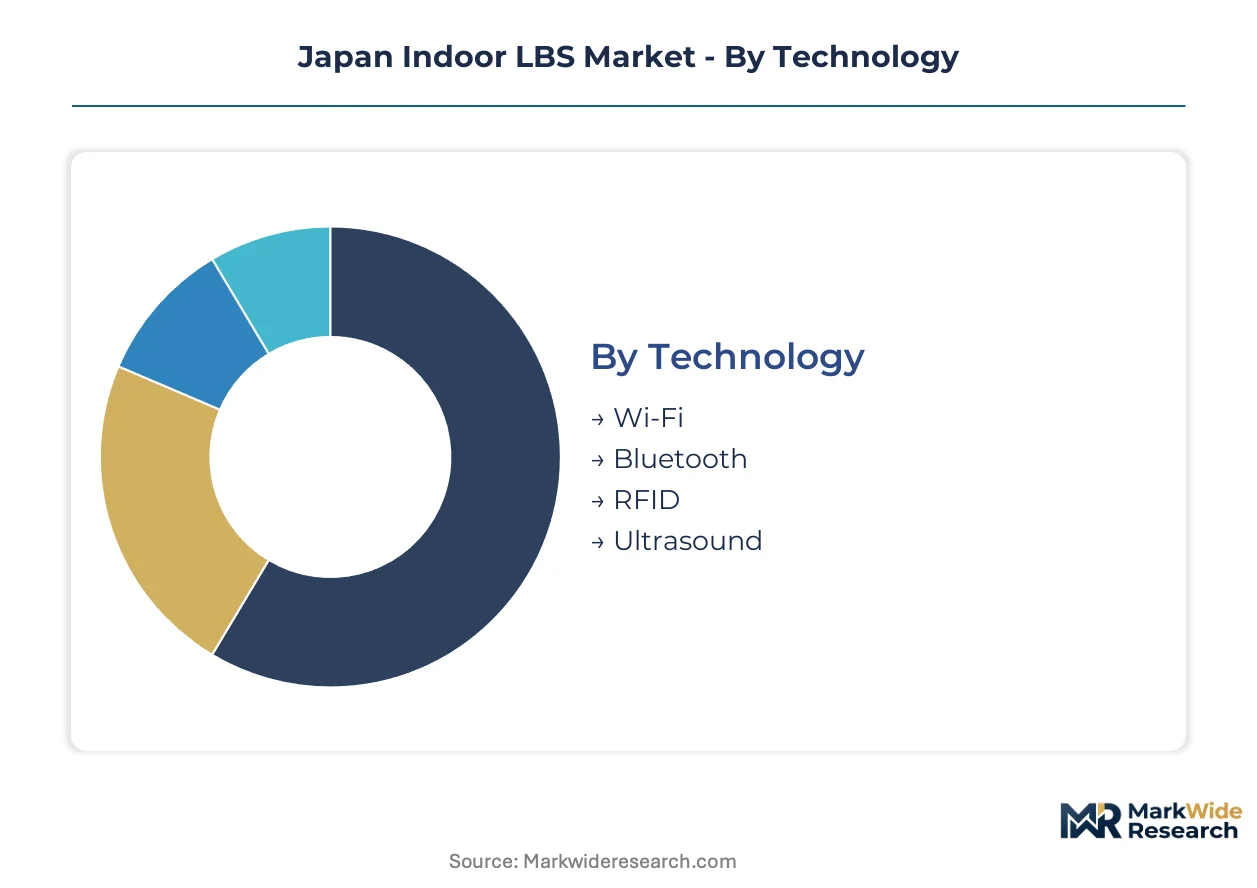
Technology selection in Japan's indoor LBS market hinges on infrastructure reuse economics and regulatory compliance timelines. Procurement patterns diverge sharply between legacy building retrofits and new smart city construction, creating distinct competitive arenas for vendors.
Technology:
Wi-Fi fingerprinting commands volume deployment due to existing access point infrastructure in commercial districts, while Bluetooth beacons capture premium positioning in precision-critical applications.
- Wi-Fi:Signal triangulation leverages existing enterprise access point infrastructure without hardware replacement. Tokyo and Osaka commercial districts favor this approach for passenger flow management in aging transportation terminals where capital budgets constrain full infrastructure overhaul.
- Bluetooth:Low-energy beacon networks deliver sub-meter accuracy through proximity-based positioning. Hospital administrators in metropolitan medical centers specify Bluetooth for asset tracking and patient wayfinding where precision justifies hardware investment.
- RFID:Passive and active tag systems enable zone-based location determination through electromagnetic field detection. Manufacturing facilities in Aichi Prefecture deploy RFID for inventory tracking where line-of-sight constraints limit optical alternatives.
- Ultrasound:Time-of-flight audio signaling provides positioning in controlled acoustic environments. Museum galleries and exhibition halls in Kyoto adopt this technology where electromagnetic interference from dense device populations degrades radio-based alternatives.
Mature deployment sits with Wi-Fi fingerprinting in legacy commercial retrofits. Newer deployment is concentrated in Bluetooth beacon networks for healthcare and smart building specifications.
Application:
Emergency services applications command regulatory priority under METI directives, while retail navigation drives volume through commercial real estate operator specifications.
- Retail Navigation:Indoor wayfinding systems guide shoppers through complex commercial environments using proximity-triggered directional prompts. Department store operators in Ginza and Shibuya deploy these systems to reduce customer service staffing for directional queries.
- Emergency Services:First responder positioning systems locate personnel and civilians within enclosed structures during crisis events. METI mandates require these capabilities in new public building construction above specified occupancy thresholds.
- Asset Tracking:Real-time location systems monitor mobile equipment and inventory through facility environments. Logistics warehouses in Kansai industrial corridors specify asset tracking for forklift fleet optimization and high-value inventory security.
- Smart Buildings:Integrated building management systems leverage positioning data for HVAC optimization, security routing, and space utilization analytics. Tokyo commercial real estate developers bundle these capabilities into Class A office specifications.
Regulatory mandates concentrate emergency services deployment in public infrastructure. Commercial return calculations are driving fastest expansion in smart building integrations.
End User:
Healthcare providers generate concentrated demand through METI-mandated modernization programs, while transportation operators deploy at scale across hub infrastructure.
- Healthcare Providers:Hospital systems deploy indoor LBS for patient navigation, staff coordination, and medical equipment location. Public medical construction guidelines mandate location-aware infrastructure in new facility builds.
- Transportation:Railway operators and airport authorities manage passenger flow and wayfinding across complex terminal environments. JR East and private railway companies in Tokyo retrofit legacy stations with positioning infrastructure.
- Retailers:Commercial operators leverage proximity marketing and shopper analytics to optimize floor layouts and promotional placement. Mid-sized retail chains in regional cities adopt beacon networks as hardware costs decline.
- Educational Institutions:Universities and research facilities track equipment and manage campus navigation for large student populations. Technical universities in Tokyo and Osaka pilot indoor positioning for laboratory safety zone enforcement.
Transportation infrastructure anchors volume deployment through hub retrofit programs. Healthcare represents the steepest expansion trajectory under regulatory modernization mandates.
Solution:
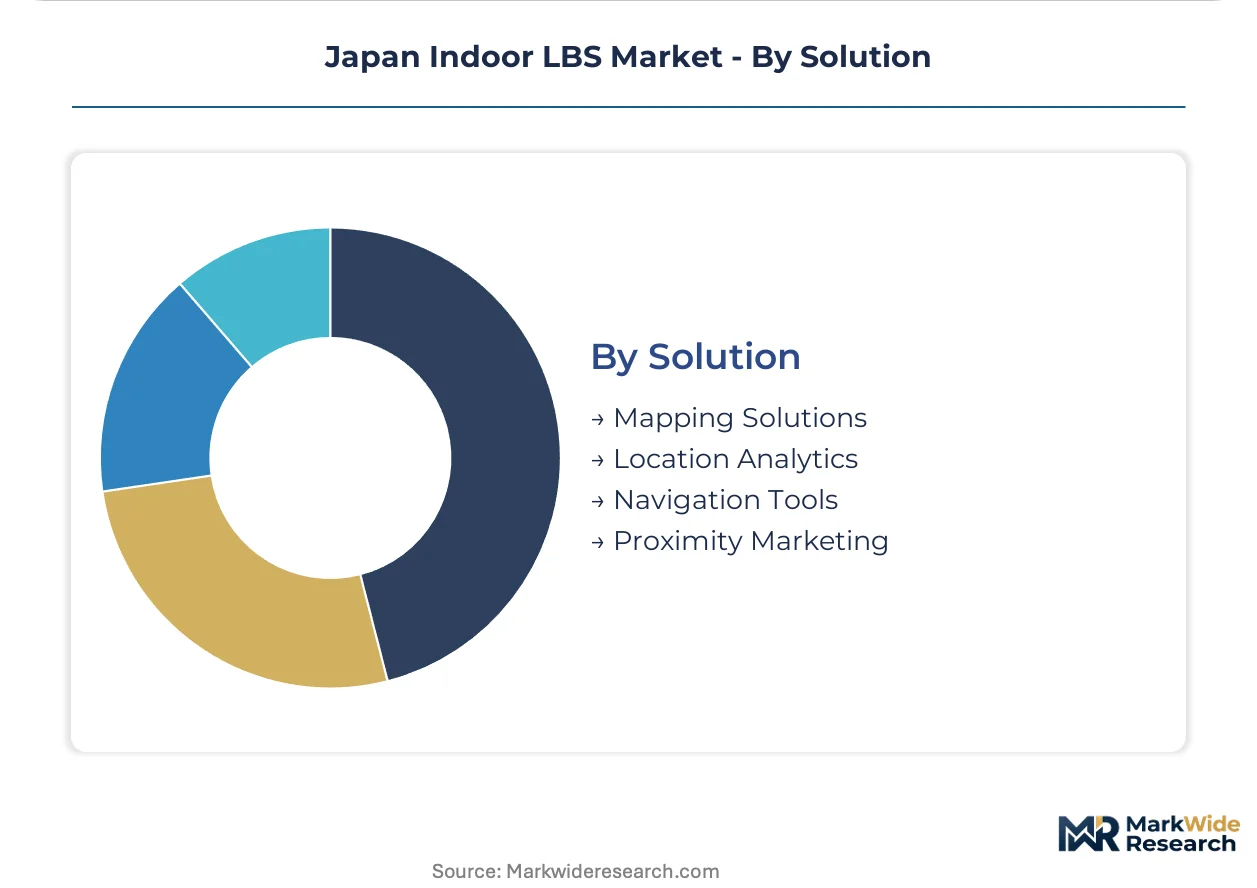
Mapping solutions capture foundational data layer margins through specialized capture requirements, while location analytics providers face elevated compliance costs.
- Mapping Solutions:Survey-grade indoor cartography creates foundational spatial data layers through lidar capture and vector processing. Specialized technicians command premium compensation for precision measurement in complex built environments.
- Location Analytics:Spatial data processing platforms derive behavioral insights from positioning traces and dwell patterns. Personal Information Protection Commission anonymization protocols elevate operational costs and audit requirements for analytics providers.
- Navigation Tools:Consumer-facing applications deliver turn-by-turn directions and point-of-interest discovery within enclosed structures. Mobile application developers integrate standardized beacon protocols to reduce cross-platform engineering overhead.
- Proximity Marketing:Triggered content delivery systems activate promotional messaging based on device proximity to specified locations. Retail operators in Fukuoka and Sapporo smart city districts pilot these capabilities for downtown commercial revitalization.
Navigation tools represent mature deployment through smartphone application integration. Mapping solutions are gaining share fastest as facility managers specify bundled hardware and data refresh contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Tokyo and Osaka concentrate indoor LBS deployment through accelerated depreciation allowances for smart building infrastructure. METI designates these districts as priority areas for digital transformation subsidies.
Kanto/Tokyo
Tokyo's transportation hub modernization drives concentrated demand for passenger flow management systems. JR East retrofits legacy stations with positioning infrastructure under METI smart city directives. The Marunouchi and Otemachi commercial districts anchor deployment through Class A office specifications bundling location-aware building management.
Kansai/Osaka
Osaka's healthcare facility expansion generates procurement for hospital navigation and asset tracking systems. METI digital transformation guidelines mandate location-aware infrastructure in new public medical construction. The Osaka Bay area industrial corridor hosts manufacturing pilots integrating indoor positioning with factory automation platforms.
Chubu/Nagoya
Automotive suppliers in Aichi Prefecture adopt ultra-wideband tracking for factory floor asset management. JIS electromagnetic emission standards govern dense beacon deployments in controlled industrial environments. The Nagoya metropolitan area concentrates logistics warehouse specifications for forklift fleet optimization through real-time location systems.
Kyushu
Fukuoka's smart city tenders specify indoor positioning requirements for downtown commercial revitalization. Municipal governments issue procurement with localization mandates for transportation and retail applications. The Kitakyushu industrial zone pilots integrated building management systems leveraging positioning data for space utilization analytics.
Hokkaido
Sapporo's municipal government issues smart city infrastructure tenders with indoor LBS specifications for public facilities. Secondary urban centers lack mature positioning infrastructure, creating deployment opportunities. The Shin-Sapporo district anchors regional adoption through new commercial construction incorporating wayfinding systems.
Japan Indoor LBS Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with telecommunications operators leveraging infrastructure ownership against pure-play technology vendors. The vendor base concentrates around platform integrators with existing enterprise relationships and mapping specialists with survey-grade capture capabilities. Two strategic archetypes dominate: infrastructure-leveraged service providers and precision-mapping technology developers. Competitive moves center on municipal procurement qualification and bundled service contract expansion.
Among Japan-based platform integrators, Hitachi, Ltd. and NTT Docomo, Inc. occupy positions reflecting infrastructure depth and telecommunications reach. Google LLC exemplifies the data-density archetype through mapping asset accumulation. These three companies represent distinct competitive vectors: industrial IoT convergence, 5G infrastructure leverage, and consumer-facing cartography scale.
| Leading Market Players |
|---|
| Google LLC |
| Hitachi, Ltd |
| Kokusai Kogyo Co., Ltd. |
| Waveon Co., Ltd. |
| AGOOP Corp. |
| NTT Docomo, Inc. |
| SoftBank |
| Rakuten |
| IndoorAtlas |
| Others |
Cost & Logistics Intelligence
Bluetooth beacon miniaturization and chipset integration are compressing hardware production costs while concentrating supplier leverage among semiconductor foundries in Taiwan and South Korea. This dual shift simultaneously expands addressable market tiers and tightens margin capture for downstream system integrators competing on bundled service contracts.
Pricing Analysis
Short lead-time premiums apply to survey-grade mapping engagements where specialized lidar technicians face scheduling constraints. Project-based pricing dominates system integration contracts bundling hardware deployment with continuous data refresh cycles. Price differentiation rests on JIS electromagnetic certification tier and after-sales SLA guarantees. Pricing pressure stems from beacon hardware commoditization as semiconductor vendors bypass traditional integrators. Mid-sized retail chains exhibit highest price sensitivity; healthcare facilities demonstrate lowest sensitivity due to regulatory mandate compliance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from telecommunications operators and industrial platform vendors. Component sourcing draws from Taiwan for UWB chipsets, South Korea for BLE modules, and domestic Japanese suppliers for JIS-certified beacon housings. Raw material dependencies include silicon wafers, lithium-ion cells for beacon power, and precision-grade optical components for lidar systems. Single-source vulnerability concentrates in Taiwan semiconductor fabrication. Distribution runs through specialized system integrators with METI procurement qualification and mapping specialists with survey-grade capture capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Survey-grade mapping technician scarcity props pricing power for qualified service providers. Capacity bottlenecks in certified hardware production constrain rapid scaling.
For Market Incumbents: Acquire specialized lidar mapping firms to secure technician pipelines and differentiate on data refresh capabilities. Integrate backward into beacon hardware production to offset semiconductor vendor disintermediation. METI interoperability mandates threaten vendor lock-in advantages; early certification investments defend municipal procurement positioning. For New Entrants and Emerging Players: Capture white-space in Sapporo and Fukuoka smart city tenders where incumbent presence remains thin. Target secondary urban center transportation authorities with retrofit-focused offerings lacking legacy infrastructure overhaul requirements. Partner with regional telecommunications operators for infrastructure co-deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integration acquisitions by industrial IoT conglomerates. Long-term viability favors mapping specialists with recurring data refresh contracts over hardware-only vendors. Watch Ministry of Internal Affairs and Communications 6GHz spectrum allocation decisions as inflection indicator for Wi-Fi-based positioning economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Hitachi's IoT convergence creates predictive maintenance applications for factory automation. |
| Mapping Specialist Acquisition | Lidar capture capabilities secure technician pipelines and bundled service contract expansion. |
| METI Procurement Qualification | Interoperability certification unlocks municipal smart city infrastructure tenders. |
| 6GHz Wi-Fi Spectrum Positioning | Early certification captures infrastructure upgrade cycles under Ministry deliberations. |
| Regional Smart City Expansion | Fukuoka and Sapporo tenders specify indoor LBS for commercial revitalization mandates. |
Research Approach
Document review covered METI policy directives, JIS electromagnetic emission standards, and telecommunications infrastructure disclosures, complemented by interviews with smart building facility managers, hospital procurement officers, beacon hardware engineers, and municipal planning officials. Secondary validation drew from NTT Docomo 5G deployment data, Google indoor mapping asset disclosures, and Hitachi IoT platform integration case studies. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts.
Historical deployment patterns cross-referenced against expert panel input on technology substitution timelines. Segmentation modeling spanned technology type, application vertical, end-user category, and solution component across the projection horizon. CAGRs derived from infrastructure investment trajectories, regulatory mandate compliance deadlines, and hardware cost decline curves. Industry-specific inputs included small cell density maps, hospital construction pipelines, and smart city tender specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum allocation decisions and semiconductor supply continuity. Forecasts reflect documented assumptions on 5G small cell rollout pace, METI directive enforcement consistency, and beacon hardware cost decline sustainability. Practitioners should monitor Ministry of Internal Affairs and Communications deliberations, Taiwan semiconductor foundry utilization rates, and METI smart city subsidy allocation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Folding Screen Mobile Phone Market
Others
GCC Shisha Tobacco Market
Others
Dried Egg Market
Others
CAR T Cell Therapy Market
Others
Bio-Imaging Technologies Market
Others
Australia Content Services Platform Market
Others
Tote Bags Market
Others
Toy Packaging Market
Others
Pickup Truck Market
Others
Pet Care Packaging Market
Others
Corn Fiber Market
Others
Coalescing Filter Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Military Sensors Software Market
Others
Europe Meditation Market
Others
Europe Air Separation Unit Market