
 Global Electronic Filters Market | 2026-2036
Global Electronic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Filters Market Analysis
The EU Green Deal is expanding compliance obligations across electronics supply chains, compelling filter manufacturers to eliminate hazardous substances from production processes. Entegris, Inc. leverages its materials science expertise to develop fluoropolymer membranes that meet evolving purity standards. Pall Corporation sustains its position through backward integration into specialty fiber production, ensuring consistent media quality for semiconductor-grade filters. Donaldson Company, Inc. competes by extending its industrial filtration technology into electronic cleanroom applications.
Electronic filters are frequency-selective circuits or components that attenuate unwanted signal components while permitting desired frequencies to pass, typically specified by cutoff frequencies, insertion loss measured in decibels, and roll-off steepness in dB per octave. These devices serve essential functions in signal integrity management across RF systems, power electronics, and data communication hardware. Passive filter architectures occupy the largest share of current volume due to their reliability and absence of power requirements, while digital filter implementations represent the fastest-expanding technology segment as software-defined radios and DSP-based signal chains displace analog alternatives. Band-pass configurations command premium positioning in telecommunications infrastructure, where precise frequency isolation determines system performance.
The EPA regulates hazardous air emissions from filter manufacturing facilities under the National Emission Standards for Hazardous Air Pollutants, while the FCC's equipment authorization requirements shape RF filter performance specifications for devices operating in licensed spectrum bands. Japan's METI enforces JIS standards for electromagnetic compatibility components, creating additional compliance layers for suppliers targeting automotive and industrial automation end users. Stakeholders must monitor evolving frequency allocation decisions by national regulators, as spectrum reassignments directly redefine filter performance requirements across telecommunications and aerospace applications.
Market Dynamics
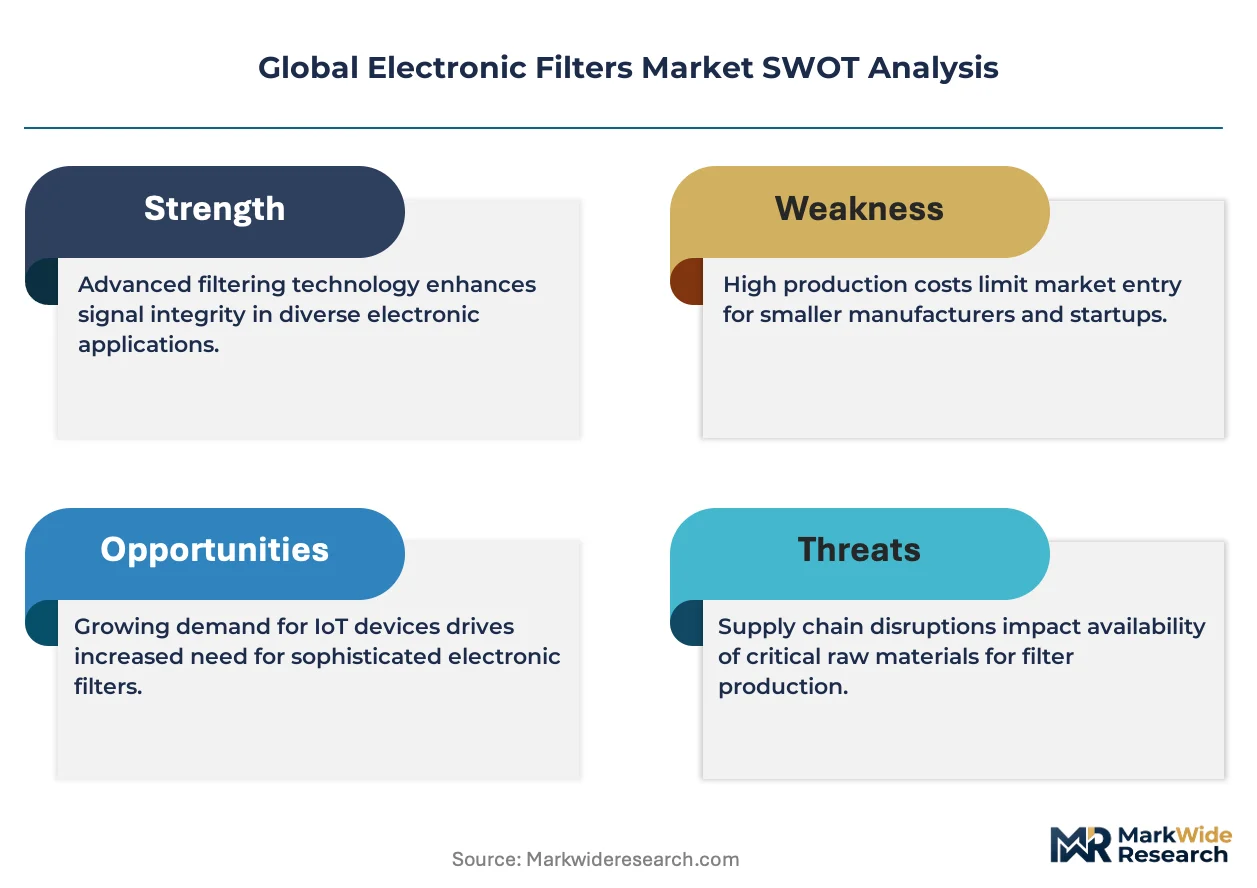
5G infrastructure deployment is compressing filter performance requirements across base station architectures, forcing manufacturers to balance insertion loss specifications against power handling capacity in millimeter-wave bands.
Growth Catalysts
- REACH and RoHS compliance mandates:European material restrictions are accelerating substitution of lead-based piezoelectric ceramics with barium titanate alternatives in ceramic filter production.
- Semiconductor fabrication expansion:China's domestic wafer fab construction is driving procurement of high-purity gas and liquid filtration systems for cleanroom process control.
- Surface acoustic wave technology:SAW filter architectures are capturing RF front-end slots in sub-6 GHz 5G handsets due to superior size-to-performance ratios.
Market Restraints
- Palladium and silver price volatility:Electrode material costs in multilayer ceramic capacitors and filters fluctuate with precious metal commodity markets, compressing margin stability.
- Japan-centered substrate supply:High-purity aluminum nitride and sapphire wafer production concentrates among Japanese specialty ceramic manufacturers, creating single-source vulnerability.
- Temperature coefficient limitations:Passive filter frequency drift in extreme thermal environments restricts deployment in aerospace and automotive underhood applications.
Strategic Opportunities
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives are attracting filter module assembly investments to serve emerging 5G network rollouts.
- Software-defined radio integration:Digital filter banks converging with FPGA platforms are opening programmable RF signal chains for military communications upgrades.
- Direct procurement from foundries:Filter OEMs are bypassing traditional distribution to establish captive supply agreements with Taiwan and South Korea semiconductor fabricators.
Industry Challenges
- Electromagnetic simulation expertise:Finite element method modeling for 3D filter structures requires specialized RF engineering talent that remains scarce outside established design houses.
- FCC equipment authorization timelines:RF filter certification for licensed spectrum devices faces extended review queues, delaying product launches in competitive telecommunications segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Filters Market |
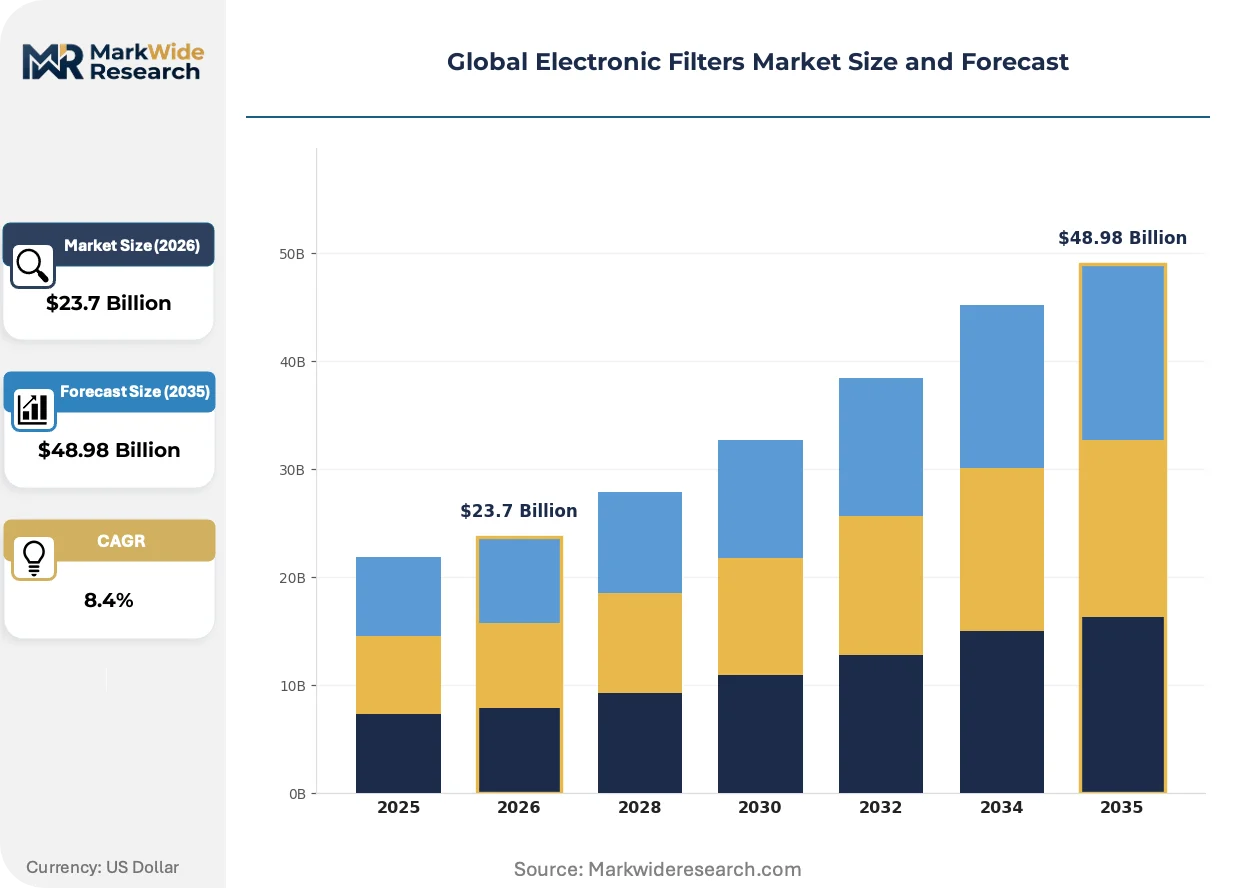
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Low-Pass, High-Pass, Band-Pass, Band-Stop Technology: Passive, Active, Digital, Analog Application: Telecommunications, Audio Processing, Signal Conditioning, RF Transmission End User: Consumer Electronics, Automotive, Industrial Automation, Aerospace |
| Companies Covered | Cobetter Filtration, Donaldson Company, Inc., Pall Corporation, Porvair PLC, Mott Corporation, Entegris, Inc., Parker Hannifin, Mann+Hummel, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Filters Market Emerging Trajectories
Filter technology is bifurcating between analog precision components for infrastructure and digital implementations for flexible consumer platforms, with material science advances bridging the performance gap.
Thin-film bulk acoustic resonator technology is integrating silicon substrate manufacturing with wafer-level packaging to achieve sub-millimeter form factors. Smartphone RF front-end module suppliers are adopting FBAR duplexers at accelerating rates for carrier aggregation architectures. This integration is compressing the addressable market for traditional ceramic discrete filters in premium handset tiers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in semiconductor etching processes, compelling filter manufacturers to validate membrane compatibility with fluorine-based chemistries. Industrial gas filtration suppliers are redesigning housing materials and seal compounds to meet tightened emission thresholds. Cleanroom operations in Germany and France are experiencing the most acute compliance pressure due to earlier national implementation schedules.
Consolidated procurement through OEM direct sourcing is displacing fragmented distributor relationships in high-volume electronics manufacturing. Contract manufacturers in Vietnam and Mexico are establishing technical qualification teams to evaluate filter suppliers without traditional channel intermediaries. This pattern is most visible in consumer electronics assembly where annual contract values justify dedicated supplier development resources.
Global Electronic Filters Market Segmentation
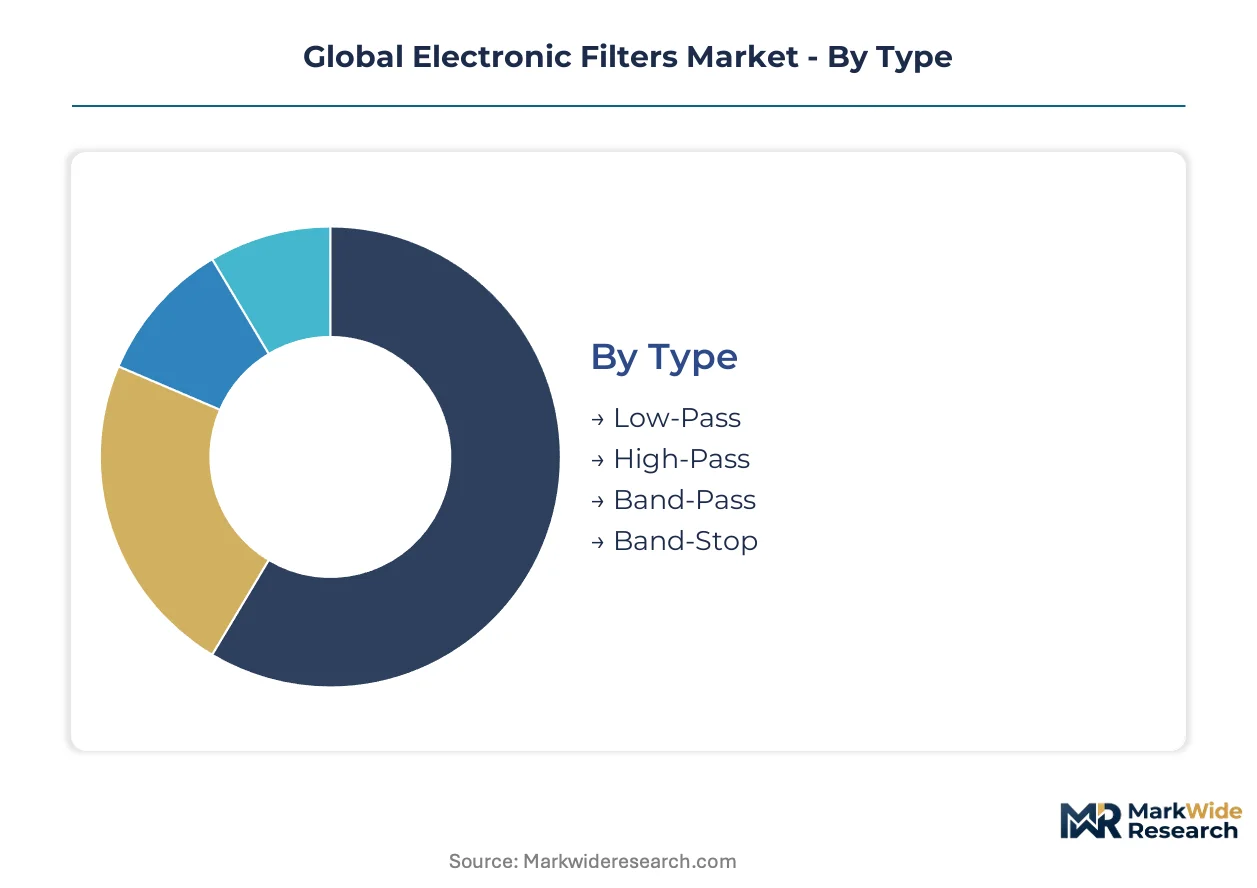
Electronic filter procurement decisions hinge on frequency response requirements, power handling thresholds, and integration complexity across divergent end-use environments. Buyers evaluate insertion loss specifications against thermal stability and form factor constraints to match filter architectures with system-level performance targets.
Type:
Frequency selectivity requirements determine filter topology selection, with cutoff precision and roll-off steepness driving cost-to-performance trade-offs in RF system design.
- Low-Pass:Attenuates frequencies above a defined cutoff threshold while passing lower spectral components with minimal insertion loss. Demand concentrates in power supply filtering for industrial motor drives and audio crossover networks, where harmonic suppression protects downstream circuitry from switching noise.
- Band-Pass:Isolates specific frequency bands through cascaded high-pass and low-pass responses, enabling precise channel selection in crowded spectrum environments. Telecommunications infrastructure deployment in China and Germany consumes premium variants for 5G base station duplexers, where adjacent channel rejection determines network capacity.
- High-Pass:Blocks DC and low-frequency components to protect sensitive RF stages from power supply drift and thermal noise coupling.
- Band-Stop:Rejects narrow interference bands without degrading passband performance, deployed in aerospace navigation systems for jammer mitigation.
Band-Pass leads on scale; Band-Stop leads on momentum.
Technology:
Power budget constraints and reconfigurability requirements split procurement between fixed analog implementations and programmable digital alternatives.
- Passive:Relies on inductor-capacitor-resistor networks without active amplification, delivering unconditional stability and zero quiescent power draw. Automotive underhood electronics and satellite hardware specify passive architectures for radiation tolerance and temperature resilience beyond semiconductor operational limits.
- Digital:Implements finite impulse response and infinite impulse response algorithms on DSP or FPGA platforms, enabling post-manufacture frequency reprogramming. Software-defined radio procurement for military communications in the US and South Korea is climbing the fastest as waveform agility requirements displace fixed-tuned analog front ends.
- Active:Integrates operational amplifiers with passive networks to achieve sharper roll-off and impedance buffering in compact footprints.
- Analog:Maintains dominance in cost-sensitive consumer electronics where continuous-time signal integrity outweighs flexibility requirements.
Passive dominates unit volume; Digital commands the steepest expansion trajectory.
Application:
Signal chain positioning determines filter specification stringency, with front-end RF stages demanding superior selectivity compared to baseband processing functions.
- Telecommunications:Encompasses base station duplexers, handset RF front ends, and optical network transceivers requiring sub-decibel insertion loss. 5G millimeter-wave deployment in Japan and the US drives procurement of temperature-compensated surface acoustic wave devices for carrier aggregation.
- RF Transmission:Covers broadcast transmitters, radar systems, and satellite uplink chains where power handling and intermodulation distortion define operational margins. Aerospace and defense programs in France and the UK specify cavity and waveguide filters for high-power radar and electronic warfare applications.
- Audio Processing:Deploys in professional mixing consoles, hearing aids, and consumer entertainment systems for equalization and crossover functions.
- Signal Conditioning:Prepares sensor outputs for analog-to-digital conversion in industrial control and medical instrumentation.
Telecommunications leads on scale; RF Transmission leads on momentum.
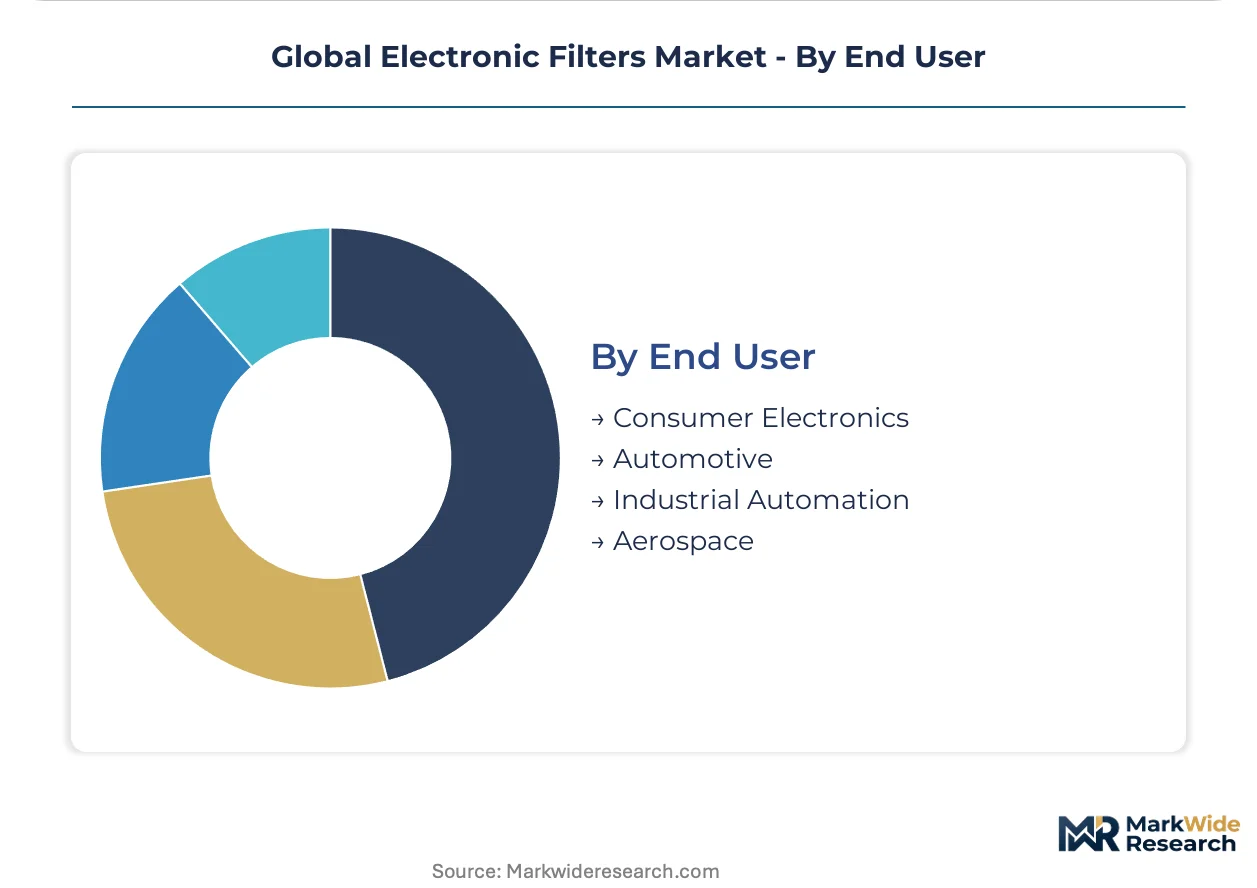
End User:
Reliability certification requirements and volume procurement patterns create distinct supplier engagement models across vertical markets.
- Consumer Electronics:Absorbs massive unit volumes in smartphones, tablets, and wearables where size constraints favor wafer-level packaged filters. Assembly operations in Vietnam and Mexico source multilayer ceramic and FBAR devices through direct foundry relationships to compress landed costs.
- Automotive:Mandates AEC-Q200 qualification for underhood and cabin electronics, with filter specifications hardened against vibration and thermal cycling. Electric vehicle inverter and onboard charger programs in Germany and China are gaining share fastest as electrification multiplies power electronics content per vehicle.
- Industrial Automation:Deploys filters in motor drives, programmable logic controllers, and process instrumentation for electromagnetic compatibility compliance.
- Aerospace:Requires space-grade screening and traceability for satellite payloads and avionics, with qualification cycles extending procurement lead times.
Consumer Electronics leads on scale; Automotive leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic filter manufacturing originated in post-war United States and Japan, where defense and telecommunications applications drove early ceramic and cavity filter development. Production subsequently dispersed across East Asian manufacturing clusters and European precision engineering centers.
United States
5G base station deployment and defense communications modernization sustain demand for high-performance RF filters. The FCC's equipment authorization requirements shape performance specifications for licensed spectrum devices. Austin and Boston metropolitan areas host design centers developing temperature-compensated surface acoustic wave devices for millimeter-wave applications.
China
Domestic semiconductor fabrication capacity expansion drives procurement of high-purity gas and liquid filtration systems for cleanroom environments. The Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility components. Yangtze River Delta clusters in Shanghai and Suzhou concentrate filter substrate manufacturing and module assembly operations.
Germany
Automotive electrification and industrial automation multiply filter content per vehicle and production line. The EU F-Gas Regulation phases down hydrofluorocarbon use in semiconductor etching processes, compelling membrane compatibility validation. Bavaria's Munich-Stuttgart corridor houses specialty ceramic manufacturers supplying high-purity aluminum nitride substrates.
Japan
Surface acoustic wave filter architectures capture RF front-end slots in sub-6 GHz 5G handsets due to superior size-to-performance ratios. METI enforces JIS standards for electromagnetic compatibility components. Kyushu and Nagoya industrial zones maintain concentrated production of high-purity aluminum nitride and sapphire wafers.
South Korea
Smartphone RF front-end module suppliers accelerate adoption of thin-film bulk acoustic resonator duplexers for carrier aggregation architectures. The national regulator enforces electromagnetic compatibility certification for wireless devices. Seoul Capital Area foundries establish direct procurement relationships with filter OEMs, bypassing traditional distribution channels.
Global Electronic Filters Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the electronic filters landscape, with integrated materials specialists facing off against assembly-focused module suppliers. The market structure exhibits moderate consolidation at the substrate and membrane level alongside fragmentation in application-specific module integration. Three archetypes dominate: materials science specialists controlling fluoropolymer and ceramic formulations, diversified filtration conglomerates leveraging cross-industry scale, and precision component houses serving aerospace and defense qualification requirements. Competitive intensity centers on backward integration into specialty fiber production and direct foundry supply agreements that compress channel costs.
Among North American materials specialists, Entegris, Inc. and Pall Corporation exemplify the vertically integrated archetype, while Donaldson Company, Inc. occupies a position bridging industrial filtration technology with electronic cleanroom applications. These entities represent contrasting strategic postures: captive control of membrane chemistry versus extension of established industrial platforms into semiconductor-grade environments.
| Leading Market Players |
|---|
| Cobetter Filtration |
| Donaldson Company, Inc. |
| Pall Corporation |
| Porvair PLC |
| Mott Corporation |
| Entegris, Inc. |
| Parker Hannifin |
| Mann+Hummel |
| 3M |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access for electronic filter manufacturers serving semiconductor cleanroom operations. Compliance-validated fluoropolymer membranes command substantial markups over standard industrial grades, while non-compliant suppliers face exclusion from German and French procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 automotive-qualified filters from industrial-grade and consumer-tier alternatives. Price differentiation hinges on certification grade and volume scale, with automotive underhood applications tolerating minimal price sensitivity. Cost compression in consumer electronics filter tiers is intensifying because smartphone OEMs are consolidating RF front-end module suppliers. Contract manufacturers in Vietnam exhibit the highest price sensitivity, while aerospace programs show the least.
Supply Chain Analysis
Single-source vulnerability sits with Japanese specialty ceramic manufacturers controlling high-purity aluminum nitride and sapphire wafer production. Geographic supply concentration centers on Japan, China, and Germany for substrate materials, with South Korea and Taiwan dominating FBAR device fabrication. Raw material dependencies draw from palladium and silver electrode stocks, fluoropolymer resin formulations, and high-purity ceramic powders. Tariff exposure on Chinese-manufactured multilayer ceramic components constitutes the primary structural risk. Distribution runs through direct foundry procurement agreements that bypass traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through backward integration into specialty fiber production and the premium-tier shift toward automotive electrification filters.
For Market Incumbents: Anchor defensive positioning through captive supply agreements with Taiwan and South Korea semiconductor fabricators, countering the threat of direct OEM procurement displacing distributor relationships. Invest in AEC-Q200 certification capacity to capture electric vehicle power electronics content expansion in Germany and China. For New Entrants and Emerging Players: Direct-to-foundry technical qualification platforms offer the most viable route into the market, bypassing established channel intermediaries. Target India's PLI scheme for telecom equipment manufacturing, where domestic 5G network rollouts create white-space demand for filter module assembly. Pursue software-defined radio integration partnerships with military communications upgrade programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for materials science specialists because substrate and membrane manufacturing exhibits moderate consolidation alongside fragmented module integration. Five-to-ten year viability favors vertically integrated players controlling fluoropolymer chemistry and ceramic formulations. Watch for FCC equipment authorization timeline compression as the signal indicating regulatory friction reduction and accelerated product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Production | Pall Corporation's captive media quality ensures consistent semiconductor-grade filter output. |
| Direct Foundry Supply Agreement | Seoul Capital Area foundries bypass traditional distribution to compress channel costs. |
| AEC-Q200 Certification Investment | Automotive electrification in Germany multiplies filter content per electric vehicle. |
| Fluoropolymer Membrane Development | Entegris leverages materials science to meet EU F-Gas Regulation purity standards. |
| Software-Defined Radio Platform Integration | Military communications upgrades in the US and South Korea displace fixed-tuned analog front ends. |
Methodological Framework
Multiple input streams — procurement director interviews, regulatory filing analysis, and trade flow reconciliation — were reconciled to construct market estimates. Primary discussions with RF design engineers, cleanroom operations managers, semiconductor procurement leads, and automotive Tier 1 supplier quality directors informed demand-side validation. Secondary sources drew from FCC equipment authorization databases, EPA NESHAP enforcement records, MIIT GB standard publications, and SEC 10-K filings from disclosed filter manufacturers. Bottom-up unit economics and top-down sectoral allocation were cross-checked for convergence.
Historical shipment trajectories were cross-referenced against panel-based growth assumptions across the analysis window. Segmentation modeling incorporated filter topology, technology architecture, application signal chain position, and end-user vertical. CAGRs were derived from slope-consistency tests against semiconductor fabrication capacity expansion timelines and 5G infrastructure deployment schedules. Temperature coefficient performance thresholds and millimeter-wave insertion loss specifications served as technology-specific forecast anchors.
Precious metal commodity volatility, spectrum reallocation decisions by national regulators, and cleanroom construction delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding REACH and RoHS compliance trajectory continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Japan Smart Home Market
Others
Vortexers Market
Others
Global Optical Comparator Market
Others
Mobile Social Networks Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Global Mobile Video Optimization Market
Others
GCC Shisha Tobacco Market
Others
South Asia Geosynthetics Market
Others
US Luxury Travel Market
Others
AI In Government And Public Services Market
Others
Global Hardware Acceleration Market
Others
Hardwood Market
Others
Smart Home Market
Others
United States Smart Homes Market
Others
Infant Fever Stickers Market
Others
Air Separation Plant Market