
 Middle East 3D Printing Construction Market | 2026-2036
Middle East 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East 3D Printing Construction Market Analytics
Aftermarket service revenue is fragmenting across the Middle East 3D printing construction landscape as hardware vendors compete for recurring maintenance contracts. COBOD International A/S leverages its open-source printer architecture to sustain dealer networks across the GCC. BESIX 3D anchors its position through captive engineering services tied to parent-group infrastructure projects. CyBe Construction B.V. differentiates by deploying mobile mixing units that reduce on-site material waste.
Middle East 3D printing construction deploys gantry-mounted or robotic-arm extrusion systems to deposit cementitious, metallic, or composite feedstocks in layered geometries, typically achieving compressive strengths of 30-60 MPa depending on binder chemistry and curing protocol. Its primary purpose is to compress project schedules, cut formwork costs, and enable complex architectural geometries impractical with conventional cast-in-place methods. Material extrusion currently leads technology deployment due to lower capital thresholds and compatibility with locally sourced concrete admixtures. Residential buildings represent the fastest-growing application segment as Gulf governments prioritize social housing delivery timelines. Government agencies command the deepest procurement budgets, though contractor-led adoption is widening as print-service providers amortize equipment costs across multiple projects.
Saudi Arabia's Saudi Building Code and the UAE's Dubai Municipality 3D Printing Strategy establish material certification pathways and structural approval frameworks that shape market access timelines. The SFDA and national standardization bodies in Qatar and Kuwait are developing construction-material testing protocols specific to additive manufacturing. Stakeholders must monitor how rapidly these codes converge on unified GCC-wide acceptance criteria for printed structural elements.
Market Dynamics
Geopolymer concrete formulation advances are compressing material certification cycles across Gulf sovereign housing programs, pulling capital from traditional precast infrastructure into extrusion-based construction systems.
Growth Catalysts
- Dubai Municipality 3D Printing Strategy:Mandatory adoption targets for government-backed residential projects create guaranteed offtake pipelines for certified print-service providers.
- Social housing delivery mandates:Saudi Arabia's affordable housing program compresses procurement timelines, favoring gantry systems that eliminate formwork lead times.
- Geopolymer binder chemistry:Local fly ash and slag sourcing reduces cement import dependency while meeting Saudi Building Code thermal performance requirements.
Market Restraints
- Specialized nozzle supply concentration:Precision extrusion hardware relies on European and East Asian component suppliers, exposing projects to freight cost volatility and customs clearance delays.
- SFDA material approval timelines:Structural element certification for novel concrete admixtures extends project planning horizons beyond traditional construction bid windows.
- Precast concrete substitution:Established precast yards in Qatar and Kuwait deliver competitive per-unit costs for standardized housing modules, limiting additive manufacturing to complex geometries.
Strategic Opportunities
- Kuwait's nascent regulatory framework:Absence of finalized 3D printing construction codes creates first-mover positioning for firms establishing local testing partnerships with the national standardization body.
- Retrofit and vertical extension applications:Robotic arm systems enable structural additions to existing building envelopes, opening commercial renovation contracts beyond greenfield residential.
- Digital twin integration:Convergence of BIM workflows with real-time extrusion monitoring allows design-to-fabrication compression for Dubai's architecturally complex hospitality projects.
Industry Challenges
- Structural engineer certification scarcity:Few professionals hold dual competency in additive manufacturing processes and Gulf building code compliance, inflating project supervision costs.
- Multi-material integration complexity:Combining metallic reinforcement with cementitious extrusion requires specialized welding protocols that exceed current contractor capability matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East 3D Printing Construction Market |
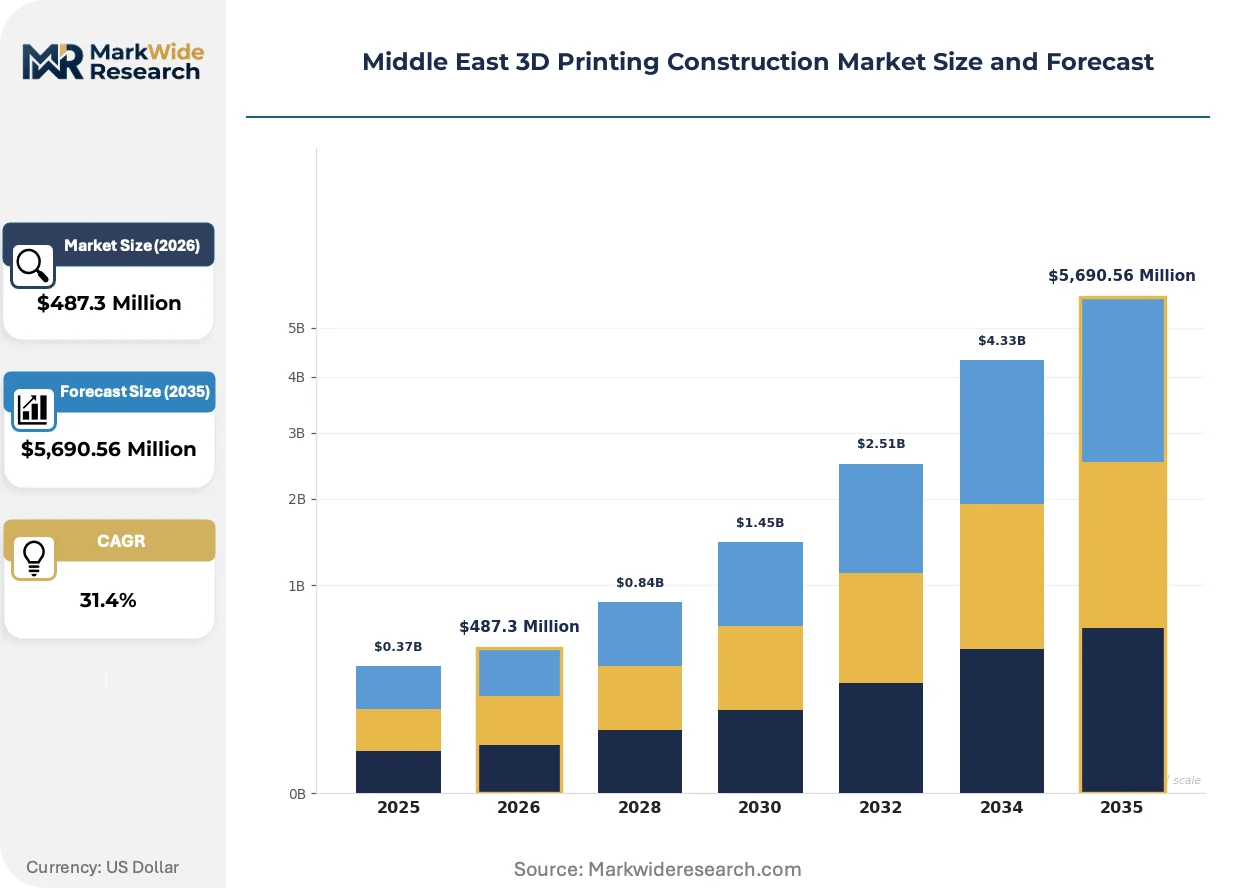
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $5,690.56 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Powder Bed Fusion, Binder Jetting, Material Extrusion Application: Residential Buildings, Commercial Structures, Infrastructure Projects, Artistic Installations Material Type: Concrete, Metal, Polymer, Composite End User: Contractors, Architects, Developers, Government Agencies |
| Companies Covered | ICON Technology, Inc., Winsun (Yingchuang Building Technique Co., Ltd.), COBOD International A/S, 3DXB Group, BESIX 3D (BESIX Group), CyBe Construction B.V., XtreeE, PERI 3D Construction GmbH, Apis Cor Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East 3D Printing Construction Market Evolving Landscape
Computational design-to-fabrication pipelines are collapsing traditional procurement hierarchies across Middle East construction, reconfiguring how sovereign developers source structural components.
Multi-axis robotic arm extrusion is virtualizing complex facade production for Dubai's hospitality and cultural landmark segments. Emaar and Aldar Properties are specifying freeform geometries that gantry systems cannot achieve, compressing architectural design-to-occupancy timelines by eliminating traditional mold fabrication. The technology is virtualizing what previously required artisanal precast or imported composite cladding.
Saudi Arabia's Saudi Building Code amendments are mandating seismic performance testing for printed structural walls, forcing material suppliers to submit geopolymer samples to SFDA-accredited laboratories before project mobilization. This regulatory tightening extends pre-construction phases but creates competitive moats for firms with established certification histories. Residential contractors in Riyadh and Jeddah are responding by pre-qualifying limited supplier rosters.
Developer procurement offices are unbundling design, material supply, and print execution into separate contract lots, fragmenting what were traditionally single-source EPC awards. This disintermediation is compressing vendor margins while expanding the addressable supplier base for specialized print-service providers. The shift is most visible in Abu Dhabi's Department of Municipalities and Transport housing tenders, where technical capability certifications now outweigh historical construction volume credentials.
Middle East 3D Printing Construction Market Segmentation
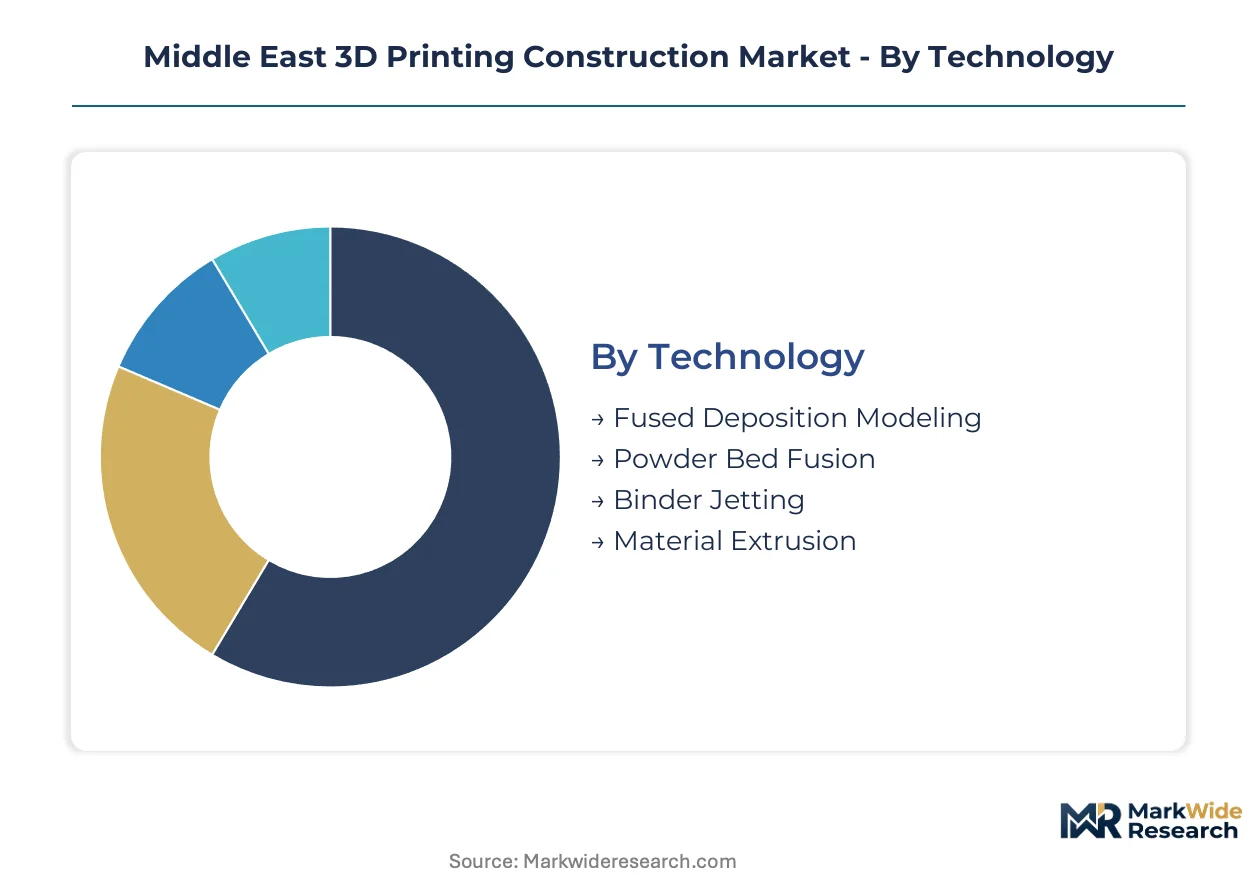
Technology selection in Middle East 3D printing construction determines capital deployment cycles, material compatibility, and regulatory approval pathways. Segment boundaries are blurring as gantry systems integrate robotic arms and multi-material capabilities reshape procurement specifications.
Technology:
Cost tier differentiates hardware acquisition thresholds and operational complexity across Gulf project portfolios.
- Material Extrusion:Gantry-mounted or robotic-arm systems deposit cementitious feedstocks in layered geometries, achieving 30-60 MPa compressive strength. Dubai's sovereign developers specify this technology for affordable housing compression targets, eliminating formwork lead times entirely.
- Binder Jetting:Powder-based binding processes create sand molds and metal prototypes with minimal material waste. Saudi industrial contractors deploy these systems for complex infrastructure components where geometric precision exceeds cast-in-place capabilities.
- Fused Deposition Modeling:Thermoplastic filament extrusion serves architectural visualization and non-structural mockups.
- Powder Bed Fusion:Laser-sintered metal production concentrates in high-performance structural connectors and reinforcement nodes.
Material Extrusion holds installed capacity. Binder Jetting is rotating up the share rankings.
Application:
Volume throughput varies dramatically by project type, dictating equipment utilization rates and amortization schedules.
- Residential Buildings:Multi-unit housing dominates current deployment as Saudi Arabia's affordable housing program compresses delivery timelines. Gantry systems print structural walls overnight, cutting conventional construction schedules by 50-70% in Riyadh and Jeddah developments.
- Commercial Structures:Office and retail shells require larger build envelopes and extended curing protocols for seismic compliance. Dubai's hospitality sector specifies freeform geometries that robotic arm extrusion achieves without traditional mold fabrication.
- Infrastructure Projects:Bridges, culverts, and utility housings demand load-bearing certification under amended Saudi Building Code seismic testing mandates.
- Artistic Installations:Sculptural and facade elements prioritize aesthetic complexity over structural performance, opening experimental contracts for multi-axis systems.
Residential Buildings anchor current throughput. Commercial Structures are climbing the fastest as hospitality developers specify geometrically complex envelopes.
Material Type:
Customer type determines material specification authority, with government agencies mandating performance standards that private developers may waive.
- Concrete:Geopolymer blends using local fly ash and slag reduce cement import dependency while meeting Saudi Building Code thermal performance requirements. SFDA-accredited laboratories now pre-qualify formulations before project mobilization, extending planning phases but creating supplier moats.
- Metal:Steel and aluminum extrusion concentrates in structural reinforcement nodes and connection hardware. Multi-material integration with cementitious systems requires specialized welding protocols that exceed current contractor capability matrices.
- Polymer:Thermoplastic applications remain limited to non-structural architectural elements and temporary formwork.
- Composite:Fiber-reinforced cementitious matrices enable thinner wall sections with equivalent load-bearing capacity.
Concrete dominates certified project pipelines. Composite formulations are gaining share fastest as thermal performance requirements tighten.
End User:
Margin capture concentrates with entities controlling design-to-fabrication workflows and certification authority.
- Government Agencies:Gulf sovereign housing programs command deepest procurement budgets and mandate technology adoption through regulatory frameworks. Dubai Municipality 3D Printing Strategy establishes mandatory targets that guarantee offtake pipelines for certified providers.
- Developers:Emaar and Aldar Properties unbundle traditional EPC contracts into separate design, material, and execution lots, fragmenting vendor relationships while expanding specialized print-service provider access.
- Contractors:Print-service providers amortize equipment costs across multiple projects, widening adoption beyond government-led initiatives.
- Architects:Computational design-to-fabrication pipelines collapse traditional procurement hierarchies, reconfiguring how structural components are sourced.
Government Agencies control certification gateways. Developers are rotating up the influence rankings as procurement offices unbundle contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers and material formulators cluster around sovereign housing programs in the Gulf Cooperation Council. Print-service providers locate near Dubai and Riyadh to compress mobilization timelines for government-backed residential contracts.
United Arab Emirates
Dubai's sovereign developers specify gantry systems for affordable housing compression targets. The Dubai Municipality 3D Printing Strategy mandates technology adoption thresholds that guarantee offtake pipelines. Emaar and Aldar Properties unbundle traditional EPC contracts into separate design and execution lots in Abu Dhabi.
Saudi Arabia
Riyadh and Jeddah developments deploy material extrusion systems to cut conventional construction schedules. The Saudi Building Code mandates seismic performance testing for printed structural walls through SFDA-accredited laboratories. NEOM's northwest construction zone experiments with multi-axis robotic arm systems for architecturally complex envelopes.
Qatar
Precast concrete yards in Doha deliver competitive per-unit costs for standardized housing modules. The national standardization body develops construction-material testing protocols specific to additive manufacturing. Lusail City's planned districts attract print-service providers seeking retrofit and vertical extension contracts.
Kuwait
Absence of finalized 3D printing construction codes creates positioning opportunities for firms establishing local testing partnerships. The national standardization body collaborates with international certification bodies to accelerate approval pathways. Kuwait City's municipal housing authority evaluates pilot projects for social housing delivery compression.
Middle East 3D Printing Construction Market Competitive Landscape
Hardware specialists and construction-integrated operators split the market along capability depth lines. The vendor base concentrates around gantry system manufacturers with established GCC dealer networks and print-service providers amortizing equipment across multiple sovereign contracts. Two strategic archetypes dominate: technology licensors with open-source architectures and captive engineering divisions of major infrastructure groups. Competitive moves center on local certification pre-qualification and unbundled contract lot positioning.
Among European hardware fabricators, COBOD International A/S and PERI 3D Construction GmbH exemplify the technology licensor archetype with modular printer architectures. CyBe Construction B.V. represents the mobile deployment specialist tier through on-site mixing capabilities. These anchors illustrate how geographic origin and organizational structure shape competitive positioning in a market where regulatory approval histories create supplier moats.
| Leading Market Players |
|---|
| ICON Technology, Inc. |
| Winsun (Yingchuang Building Technique Co., Ltd.) |
| COBOD International A/S |
| 3DXB Group |
| BESIX 3D (BESIX Group) |
| CyBe Construction B.V. |
| XtreeE |
| PERI 3D Construction GmbH |
| Apis Cor Inc. |
| Others |
Value Network & Pricing Analysis
Dubai's sovereign developer ecosystem anchors equipment procurement gravity, where gantry system manufacturers extract premium positioning through bundled certification support and localized dealer networks. Print-service providers amortize hardware costs across multiple government-backed residential contracts, compressing per-project capital recovery timelines while specialized nozzle suppliers in Europe and East Asia capture recurring aftermarket revenue streams.
Pricing Analysis
Aftermarket service contracts spanning precision nozzle replacement, calibration protocols, and extended warranty coverage drive lifetime value capture for hardware vendors. Three-tier pricing structure across premium-certified, standard-compliant, and economy-imported equipment tiers reflects SFDA pre-qualification status and local testing partnership depth. Cost compression in economy-tier gantry systems is intensifying as Chinese manufacturers establish UAE dealer networks. Government agencies exhibit lowest price sensitivity due to mandated adoption targets, while contractor-led print-service providers face acute margin pressure from unbundled contract structures.
Supply Chain Analysis
Geopolymer binder feedstocks draw from local fly ash and slag sourcing in Saudi Arabia, the UAE, and Qatar, reducing cement import dependency while meeting thermal performance mandates. Precision extrusion hardware depends on European and East Asian component suppliers, with specialized nozzle fabrication concentrated in Germany and Japan. Single-source vulnerability in robotic arm servo motors exposes projects to freight cost volatility and customs clearance delays. Distribution runs through captive engineering divisions of major infrastructure groups and independent print-service providers mobilizing for sovereign housing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as Gulf sovereign housing programs compress delivery timelines and pull capital from traditional precast infrastructure. Government-backed affordable housing mandates across the GCC create guaranteed offtake pipelines that de-risk equipment deployment.
For Market Incumbents: Harden certification moats by deepening SFDA-accredited laboratory partnerships before competitor formulations complete approval cycles. Expand captive engineering service capacity to capture unbundled design and execution contract lots. Defend against emerging Chinese hardware vendors by localizing dealer support networks in secondary GCC markets.
For New Entrants and Emerging Players: Kuwait's absence of finalized 3D printing construction codes represents the most penetrable entry point for firms establishing national standardization body testing partnerships. Retrofit and vertical extension applications in Qatar's Lusail City open commercial renovation contracts beyond saturated greenfield residential segments. Lead with mobile mixing unit deployment to differentiate on material waste reduction metrics.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification histories create irreversible supplier positioning in government procurement pipelines. Target print-service providers with established equipment amortization across multiple sovereign contracts and demonstrated SFDA pre-qualification track records. Monitor convergence timelines for unified GCC-wide acceptance criteria as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Pre-Qualification | Establishes supplier moats in Saudi Arabia's mandatory seismic testing framework for printed structural walls. |
| Mobile Mixing Unit Deployment | Reduces on-site material waste and differentiates print-service providers in competitive Dubai sovereign tenders. |
| Local Dealer Network Expansion | Compresses mobilization timelines for government-backed residential contracts across secondary GCC markets. |
| Digital Twin Integration | Converges BIM workflows with real-time extrusion monitoring for Dubai's architecturally complex hospitality projects. |
| Geopolymer Formulation Partnership | Secures fly ash and slag sourcing agreements to reduce cement import dependency under Saudi Building Code mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sovereign developer procurement officers, print-service provider operations directors, gantry system manufacturer sales executives, and SFDA-accredited laboratory technical leads. Secondary validation drew from Dubai Municipality regulatory filings, Saudi Building Code amendment documentation, GCC customs and trade data, and equipment supplier SEC disclosures. Bottom-up project pipeline aggregation and top-down sovereign housing program budget analysis were triangulated to establish market sizing.
Calibration against historical deployment trajectories in comparable construction technology adoptions anchored growth assumptions across the projection horizon. Segmentation modeling incorporated technology type, application vertical, material formulation, and end-user procurement authority. CAGRs were derived from equipment installed base expansion curves and material throughput per project archetype. Geopolymer certification cycle compression and robotic arm utilization rates in hospitality applications served as industry-specific forecast inputs.
Practitioners should monitor regulatory convergence timelines and geopolymer formulation approval velocities for early signals of competitive repositioning. Forecasts reflect assumptions regarding sustained sovereign housing program funding and stable European component supply chains. Material shifts in GCC-wide unified acceptance criteria adoption or sustained precision hardware supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East Location-Based Services Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Australia Content Services Platform Market
Others
Trusted Platform Module (TPM) Market
Others
Shear Testing Equipment Market
Others
Toy Packaging Market
Others
Digital Bass Processor Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Europe Virtual Reality Gaming Market
Others
Digital Supply Chain Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Cathode Battery Material Market
Others
UK Real Estate Hospitality Market
Others
Smart-Connected Power Plug Socket Market
Others
North America IT Device Market
Others
Basketball Apparel Market