
 Asia-Pacific Agricultural Enzymes Market | 2026-2036
Asia-Pacific Agricultural Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Enzymes Market Outlook
Chinese fermentation capacity expansions is realigning supply dynamics across the region. Novozymes A/S leverages its Copenhagen-developed enzyme libraries to dominate high-purity cellulase production for tropical soil conditions. BASF SE anchors its position through backward integration into strain development facilities in Nanjing. Sunson Industry Group Company Limited competes on manufacturing scale, operating one of Asia's largest solid-state fermentation plants for bulk protease output.
Asia-Pacific agricultural enzymes comprise protein-based biocatalysts—typically cellulase, amylase, protease, and lipase—produced through submerged or solid-state fermentation of fungal and bacterial strains, functioning to accelerate organic matter decomposition and nutrient mineralization in soils. Their primary commercial purpose centers on enhancing fertilizer use efficiency and reducing synthetic chemical loads in intensive cropping systems. Cellulase formulations command premium positioning in plantation agriculture across Indonesia and Malaysia, where oil palm residue recycling demands high enzymatic activity. Soil treatment applications generate the fastest-growing demand trajectory, driven by government-mandated soil health programs in India and Vietnam that subsidize biological input adoption.
China's Ministry of Agriculture and Rural Affairs (MARA) enforces GB standard compliance for microbial fertilizer registration, while India's Central Insecticides Board mandates bio-pesticide and bio-stimulant efficacy data before interstate commercialization. These frameworks elevate R&D barriers for new entrants and privilege established players with dedicated regulatory affairs teams. Stakeholders must monitor evolving strain patent landscapes and biosafety protocol harmonization across ASEAN member states to anticipate market access shifts.
Market Dynamics
China's GB standards for bio-stimulant registration and India's PLI scheme for agri-input manufacturing are elevating technical barriers across the Asia-Pacific agricultural enzymes market, privileging established players with dedicated regulatory affairs teams and backward-integrated strain development capabilities.
Growth Catalysts
- Soil Health Subsidies:Government-mandated soil health programs in India and Vietnam subsidize biological input adoption, accelerating recurring enzyme purchases in intensive wheat-rice systems across the Indo-Gangetic Plains.
- Fermentation Capacity Expansion:Chinese solid-state and submerged fermentation infrastructure is realigning regional supply dynamics, reducing import dependence for cellulase and protease formulations.
- Oil Palm Residue Recycling:Plantation agriculture across Indonesia and Malaysia demands high-activity cellulase formulations for organic matter decomposition, creating sustained demand for premium enzyme products.
Market Restraints
- Regulatory Friction:India's Central Insecticides Board mandates bio-stimulant efficacy data before interstate commercialization, extending product launch timelines for new entrants lacking dedicated regulatory infrastructure.
- Input Cost Volatility:Agricultural enzyme production depends on molasses and grain-based substrates subject to commodity price swings, compressing margins for bulk protease manufacturers operating at scale.
- Technical Limitation:Enzyme stability under tropical soil conditions—high temperature and humidity—remains inconsistent, limiting performance guarantees in Southeast Asian plantation applications.
Strategic Opportunities
- Vietnam's Mekong Delta:Underpenetrated rice-intensive regions present white space for soil treatment enzyme adoption as provincial agricultural extension services expand biological input demonstrations.
- Technology Convergence:Integration of enzyme formulations with precision irrigation systems enables targeted nutrient mineralization, appealing to commercial farms adopting sensor-based fertigation.
- ASEAN Harmonization:Biosafety protocol alignment across member states would streamline multi-country registration, reducing compliance overhead for regionally ambitious suppliers.
Industry Challenges
- Strain Patent Complexity:Navigating fungal and bacterial strain intellectual property across multiple jurisdictions creates licensing friction and litigation exposure for enzyme developers.
- Certification Timeline Compression:China's MARA registration process for microbial fertilizers demands extended field trial data, delaying revenue recognition for novel product introductions.
- Technical Talent Scarcity:Fermentation process engineering and enzymology expertise concentrates in established biotechnology clusters, constraining R&D scaling for mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Enzymes Market |
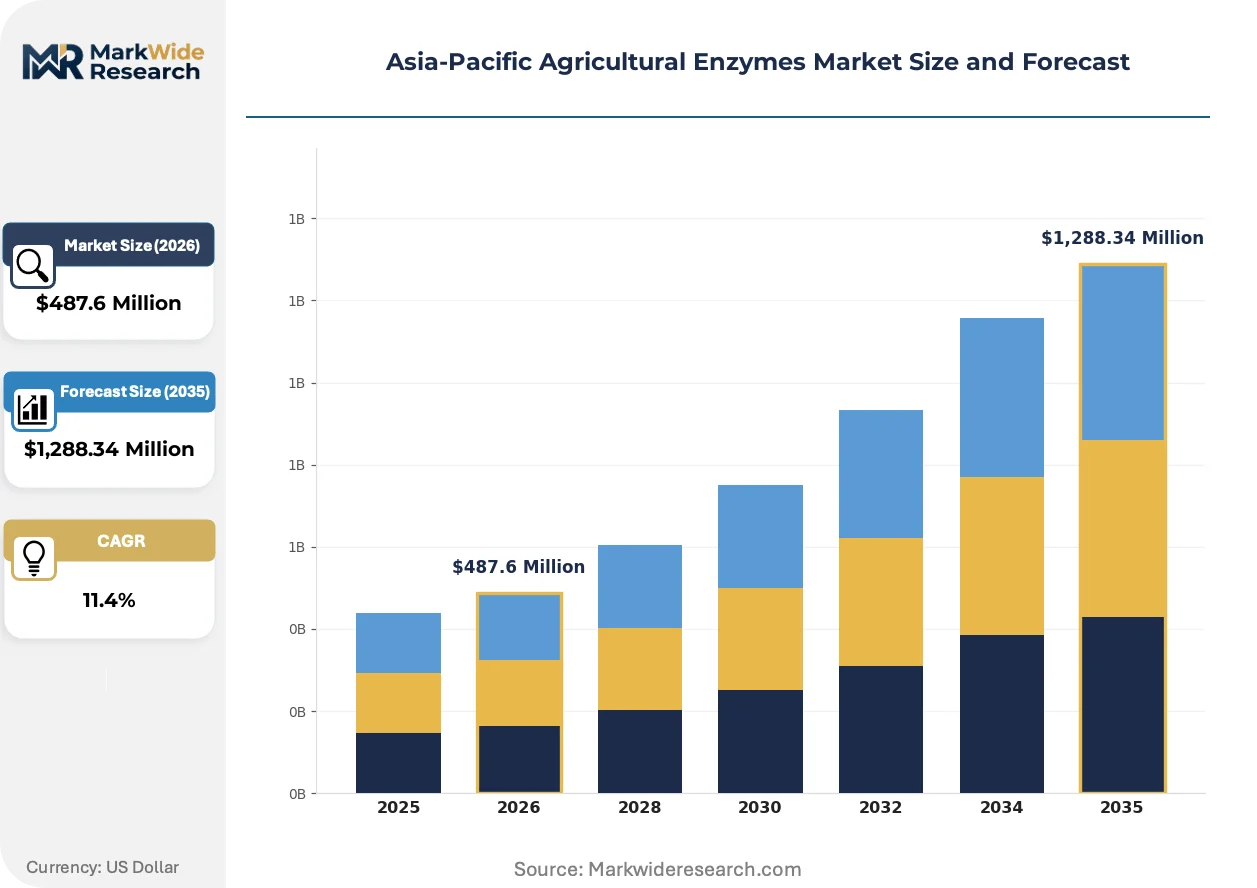
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulase, Amylase, Protease, Lipase End Use Industry: Agriculture, Horticulture, Organic Farming, Aquaculture Application: Soil Treatment, Crop Protection, Fertilizer Enhancement, Pest Control Distribution Channel: Online Retail, Direct Sales, Distributors, Agricultural Cooperatives |
| Companies Covered | Novozymes A/S, BASF SE, Syngenta AG, AB Enzymes, BioWorks Inc., Agrilife, Advanced Enzymes Technologies Limited, Amano Enzyme Inc., Sunson Industry Group Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Enzymes Market Strategic Shifts
Biotechnology advances and regulatory tightening are restructuring competitive positioning across the Asia-Pacific agricultural enzymes landscape, with formulation science and supply chain integration emerging as decisive capability differentiators.
CRISPR-guided strain optimization is rewriting enzyme production economics by accelerating fungal and bacterial strain development cycles. Commercial enzyme houses in China and India are adopting gene-editing platforms to enhance cellulase thermostability for tropical soil applications. This compression of R&D timelines is enabling faster response to plantation agriculture specifications.
China's MARA enforcement of GB standard compliance for microbial fertilizer registration is tightening product quality benchmarks across the region. Manufacturers must now demonstrate strain purity and enzymatic activity consistency through centralized testing protocols. This regulatory elevation privileges players with captive analytical laboratories and quality assurance infrastructure.
Specialty crop producers across Southeast Asia are consolidating procurement through agricultural cooperative networks rather than individual farm-level purchasing. These cooperatives negotiate volume-based enzyme supply contracts with technical support bundled, displacing traditional distributor intermediaries. The shift is most visible in Indonesia's oil palm smallholder collectives seeking integrated soil treatment programs.
Asia-Pacific Agricultural Enzymes Market Segmentation
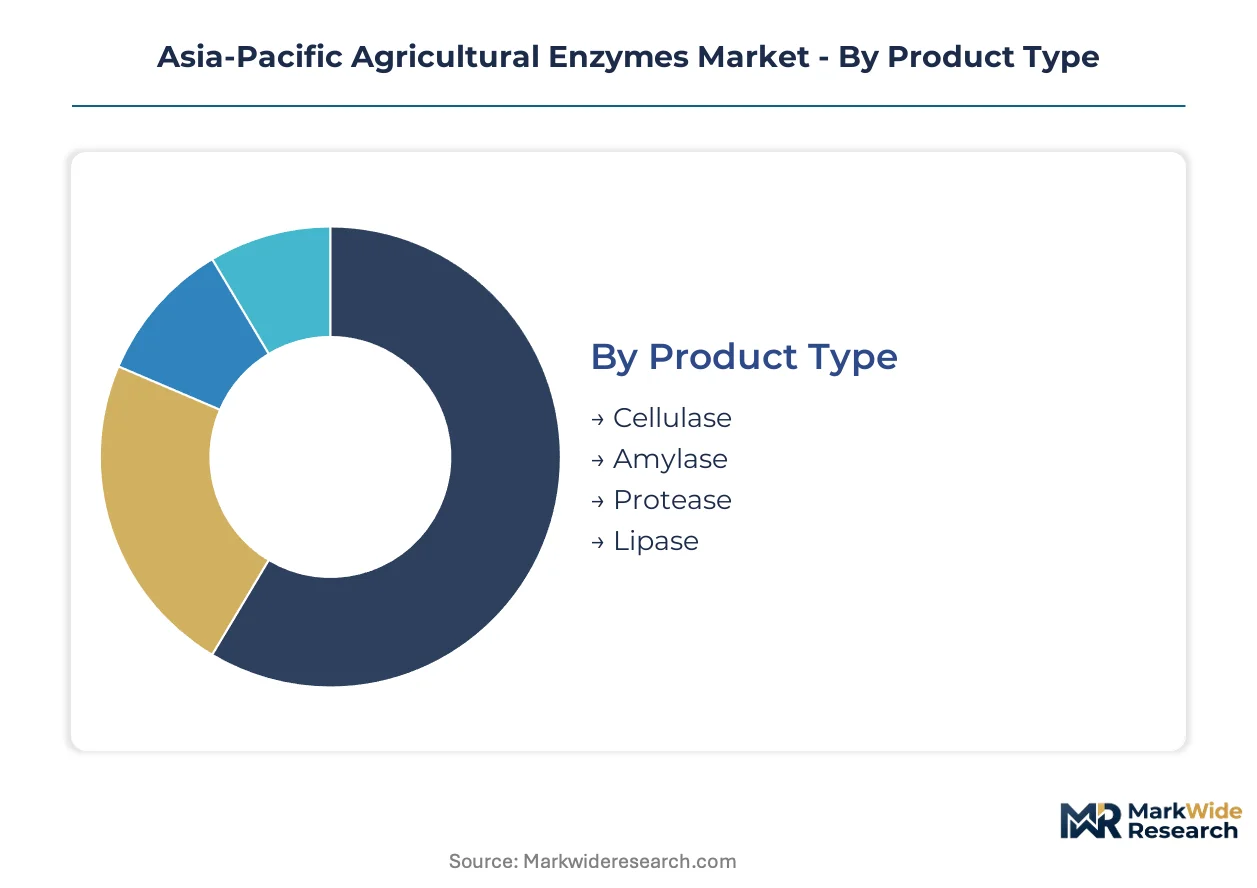
Product specifications, application intensity, and procurement channel preferences create distinct value pools across the Asia-Pacific agricultural enzymes landscape. Buyers prioritize enzymatic activity stability under tropical conditions, formulation compatibility with existing fertilizer programs, and regulatory registration status when selecting suppliers.
Product Type:
Commercial buyers differentiate enzyme investments based on substrate specificity requirements and residual activity duration in high-humidity soils.
- Cellulase:Complex enzyme systems hydrolyzing cellulose into glucose subunits, typically derived from Trichoderma and Aspergillus fermentation. Indonesian and Malaysian oil palm plantations concentrate demand for high-activity formulations capable of decomposing lignocellulosic biomass under 30-35°C soil temperatures. Premium positioning reflects thermostability engineering requirements for tropical performance guarantees.
- Protease:Protein-cleaving biocatalysts accelerating organic nitrogen mineralization from crop residues and animal manure. India's Indo-Gangetic Plains wheat-rice systems drive recurring bulk purchases, with state agricultural universities validating efficacy through multi-season field trials. Solid-state fermentation infrastructure in Shandong and Jiangsu provinces supplies cost-competitive feedstock-grade material.
- Amylase:Starch-degrading enzymes facilitating carbohydrate breakdown in composting applications and soil amendment programs.
- Lipase:Ester-bond hydrolyzing catalysts targeting lipid-rich organic waste streams in plantation agriculture residue management.
Cellulase leads on scale through plantation agriculture penetration; protease leads on momentum through Indian government soil health subsidy expansion.
End Use Industry:
Application intensity and regulatory compliance burdens vary sharply across buyer categories, with organic certification requirements and export market access driving premium formulation selection.
- Agriculture:Broadacre cereal and oilseed producers deploying enzymes for fertilizer use efficiency improvement and synthetic input reduction. Vietnam's Mekong Delta rice intensification zones represent underpenetrated expansion territory as provincial extension services expand biological input demonstrations. China's MARA microbial fertilizer registration mandates strain purity documentation for interstate commercialization.
- Organic Farming:Certified operations requiring enzymatic inputs meeting organic equivalency standards for residue decomposition and nutrient cycling. Australian Organic Certification and Indian NPOP accreditation create formulation specification divergences that complicate multi-country product strategies. Premium pricing reflects batch traceability and contaminant-free production protocols.
- Horticulture:Protected cultivation and high-value vegetable producers utilizing targeted enzyme applications for substrate conditioning.
- Aquaculture:Shrimp and finfish pond operators applying enzymes for water quality management and organic sediment reduction.
Agriculture dominates absolute volume through wheat-rice system penetration; organic farming climbs the fastest through certification-driven premium input substitution.
Application:
Performance validation requirements and subsidy eligibility criteria reshape procurement patterns across functional use cases.
- Soil Treatment:Direct soil incorporation for organic matter decomposition, structure improvement, and nutrient mineralization acceleration. India's Paramparagat Krishi Vikas Yojana subsidizes biological input adoption, creating recurring demand in Haryana and Punjab intensive cropping zones. Field trial data requirements under Central Insecticides Board regulations extend product launch timelines for novel formulations.
- Fertilizer Enhancement:Co-formulation with NPK and micronutrient products to improve nutrient release kinetics and root zone availability. Chinese compound fertilizer manufacturers integrate cellulase and amylase into controlled-release formulations for plantation agriculture export markets. Backward integration into strain development capabilities differentiates suppliers capable of customizing enzymatic activity profiles.
- Crop Protection:Enzyme-based biocontrol applications targeting pathogen cell wall degradation and induced systemic resistance.
- Pest Control:Chitinase and protease formulations disrupting insect and nematode physiological processes.
Soil treatment commands the largest installed base through government program adoption; fertilizer enhancement gains share fastest through co-formulation partnerships with major compound fertilizer producers.
Distribution Channel:
Procurement consolidation through cooperative networks and precision agriculture platform integration is restructuring traditional intermediary economics.
- Agricultural Cooperatives:Consolidated purchasing entities negotiating volume-based supply contracts with bundled technical support services. Indonesia's oil palm smallholder collectives displace traditional distributor intermediaries through integrated soil treatment program procurement. Cooperative agronomists specify enzymatic activity thresholds and application timing protocols.
- Direct Sales:Manufacturer-to-farm relationships for large-scale commercial operations requiring customized formulation development and on-site technical service. Australian broadacre grain producers and Thai sugarcane estates maintain direct supply agreements with fermentation houses capable of strain optimization for specific soil microbiome conditions.
- Distributors:Regional agrochemical wholesalers maintaining inventory and credit facilities for mid-scale farm customers.
- Online Retail:E-commerce platforms serving smallholder segments with standardized formulation packaging and digital agronomy content.
Agricultural cooperatives lead on volume concentration through collective procurement power; direct sales expands most quickly through commercial farm precision agriculture integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting fermentation capacity investments toward jurisdictions with streamlined biosafety protocols. Manufacturers calibrate facility location decisions against registration timeline compression and subsidy eligibility criteria.
China
Submerged fermentation infrastructure in Jiangsu and Shandong provinces supplies cellulase and protease formulations for domestic plantation agriculture and export markets. MARA enforces GB standard compliance for microbial fertilizer registration, elevating quality assurance requirements. Nanjing anchors backward-integrated strain development capabilities serving compound fertilizer co-formulation partnerships.
India
The Indo-Gangetic Plains wheat-rice systems generate recurring enzyme demand through state-subsidized soil health programs. The PLI scheme for agri-input manufacturing attracts fermentation capacity investments toward Gujarat and Maharashtra. Central Insecticides Board efficacy data requirements extend product launch timelines for interstate commercialization.
Indonesia
Oil palm plantation residue recycling drives premium cellulase consumption across Sumatra and Kalimantan. Smallholder collectives consolidate procurement through cooperative networks, displacing traditional distributor intermediaries. Jakarta-based agricultural extension services expand biological input demonstrations in underpenetrated estates.
Vietnam
Mekong Delta rice intensification zones present expansion opportunities as provincial authorities subsidize biological input adoption. Government-mandated soil health programs accelerate recurring enzyme purchases in intensive cropping systems. Ho Chi Minh City logistics corridors facilitate distribution to commercial farm operations adopting precision fertigation.
Thailand
Sugarcane estates in the Central Plains maintain direct supply relationships with fermentation houses for customized soil microbiome applications. Bangkok anchors regulatory affairs infrastructure navigating ASEAN biosafety protocol harmonization. Eastern Economic Corridor manufacturing zones attract enzyme formulation packaging investments serving regional export markets.
Asia-Pacific Agricultural Enzymes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty formulation niches requiring localized regulatory expertise. The market structure concentrates around fermentation-scale leaders with captive strain libraries and quality assurance infrastructure. Three archetypes dominate: multinational biotechnology houses with global enzyme portfolios, regional fermentation specialists leveraging solid-state infrastructure, and agricultural input conglomerates integrating biologicals into crop nutrition platforms. Competitive dynamics center on backward integration into strain development and cooperative network procurement consolidation.
Within the multinational tier, Novozymes A/S and BASF SE occupy positions exemplifying premium-tier enzyme supply through integrated R&D and regulatory affairs capabilities. Sunson Industry Group Company Limited represents the regional specialist archetype, anchoring manufacturing scale advantages in solid-state fermentation infrastructure. These three entities collectively illustrate the capability spectrum spanning global strain libraries, backward-integrated production, and bulk manufacturing efficiency.
| Leading Market Players |
|---|
| Novozymes A/S |
| BASF SE |
| Syngenta AG |
| AB Enzymes |
| BioWorks Inc. |
| Agrilife |
| Advanced Enzymes Technologies Limited |
| Amano Enzyme Inc. |
| Sunson Industry Group Company Limited |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MARA-registered and unregistered enzyme suppliers manifests simultaneously in pricing premiums of 15-25% and supply chain bifurcation toward captive analytical laboratories in Jiangsu and Shandong. This tiered market structure rewards backward-integrated manufacturers with strain development capabilities while compressing margins for bulk protease traders dependent on spot substrate purchases.
Pricing Analysis
Distributor margins absorb 12-18% of final enzyme formulation costs across cooperative procurement channels in Indonesia and Vietnam, though direct sales to Australian broadacre producers bypass this layer entirely. Three-tier pricing structure across premium, standard, and economy levels reflects enzymatic activity guarantees, thermostability engineering, and bundled technical support services. Pricing pressure stems from molasses and grain-based substrate commodity volatility, which squeezes solid-state fermentation operators in Shandong. State-subsidized soil health programs in Haryana and Punjab exhibit highest price sensitivity, while organic-certified operations in Australia accept premium positioning for contaminant-free production protocols.
Supply Chain Analysis
Skilled fermentation process engineers cluster disproportionately in Nanjing, Jiangsu province, and Pune, Maharashtra, anchoring regional supply concentration despite expanding capacity in Gujarat under India's PLI scheme. Production draws from fungal and bacterial strain libraries, molasses feedstock, and specialized bioreactor equipment, with single-source vulnerability concentrated in thermostable cellulase strain IP held by Copenhagen-developed enzyme houses. Distribution runs through agricultural cooperative networks displacing traditional wholesalers across Sumatra and Kalimantan, while Ho Chi Minh City logistics corridors service precision fertigation-integrated commercial farms in the Mekong Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through recurring enzyme purchases in intensive wheat-rice systems, where government-mandated soil health programs lock in biological input adoption cycles across the Indo-Gangetic Plains.
For Market Incumbents: Deploy captive regulatory affairs infrastructure to compress MARA and Central Insecticides Board registration timelines, defending against emerging regional fermentation specialists with solid-state scale advantages. Deepen backward integration into CRISPR-guided strain optimization capabilities to maintain thermostability performance guarantees under tropical conditions. Channel control through cooperative network procurement consolidation in Indonesia's oil palm smallholder collectives blocks price-sensitive new entrants. For New Entrants and Emerging Players: Agricultural extension service partnerships in Vietnam's underpenetrated Mekong Delta rice zones offer lowest competitive density for soil treatment enzyme trials. White space concentrates in precision irrigation-integrated fertigation applications where sensor-based nutrient mineralization protocols remain unstandardized. A technical service bundling go-to-market angle differentiates against commodity bulk protease suppliers from Shandong. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance overhead exceeds 15% of operating costs for mid-tier manufacturers lacking dedicated quality assurance infrastructure. Fermentation-scale specialists with captive strain libraries and MARA registration status represent prime acquisition targets over pure-play distributors. Monitor ASEAN biosafety protocol harmonization progress as inflection signal for multi-country registration cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Nanjing-based facilities enable customization for tropical soil thermostability requirements. |
| Cooperative Network Procurement Consolidation | Indonesian oil palm smallholder collectives displace traditional distributor intermediaries through volume contracting. |
| Regulatory Affairs Infrastructure Investment | Dedicated teams compress MARA microbial fertilizer registration timelines against competitor delays. |
| Precision Fertigation Technology Convergence | Sensor-based integration targets commercial farms in Ho Chi Minh City logistics corridors. |
| CRISPR-Guided Strain Optimization | Gene-editing platforms accelerate cellulase thermostability engineering for plantation agriculture specifications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, agricultural cooperative procurement heads, regulatory affairs specialists at enzyme houses, and extension service agronomists in Vietnam and Indonesia with secondary validation through MARA microbial fertilizer registration databases, India's Central Insecticides Board efficacy trial records, customs data on cellulase and protease trade flows, and ASEAN biosafety protocol harmonization documentation. Bottom-up facility capacity assessments and top-down subsidy program budget allocations were triangulated for demand sizing.
Segment-weighting approaches distributed value across enzymatic activity tiers, application intensity in wheat-rice versus plantation systems, and procurement channel structures. Modeling incorporated product type specifications, end-use industry compliance burdens, functional application subsidy eligibility, and distribution channel consolidation patterns. CAGRs were derived from installed base growth in intensive cropping zones and replacement cycle analysis for biological input programs. Forecast inputs included PLI scheme capacity addition timelines and provincial soil health program budget trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN biosafety harmonization delays and molasses feedstock commodity swings. Forecasts reflect documented assumptions on subsidy continuation and strain patent landscape stability. Practitioners should monitor MARA registration queue lengths and Indonesian cooperative procurement tender volumes for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America 3D Printing Construction Market
Others
Dental Ceramics Market
Others
UK 3D Printing Construction Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Reusable Wine Bags Market
Others
Rotary Evaporators Market
Others
Fresh Apples Market
Others
US Legal Services Market
Others
Thiamethoxam Market
Others
North America Cashew Market
Others
Gesture Recognition for Smart TV Market
Others
Latin America Contract Packaging Market
Others
Global Digital Market
Others
Digital Thermal Plates Market
Others
Europe Digital Experience Platform Market
Others
Nuclear Power Cables Market