
 Lightweight Compact Wheel Loader Market | 2026-2036
Lightweight Compact Wheel Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Compact Wheel Loader Market Outlook
CE marking under the EU Machinery Directive is collapsing the competitive field for non-compliant manufacturers seeking European access. Caterpillar Inc. leverages its integrated dealer network to control rental and contractor channels across mature markets. Kubota Corporation specializes in sub-50-horsepower segments where agricultural and landscaping buyers overlap. Volvo Construction Equipment anchors its position through telematics integration and connected fleet services.
A lightweight compact wheel loader is a rubber-tired earthmoving machine typically weighing under 12,000 pounds, engineered with articulated steering and hydrostatic or hybrid drivetrains for maneuverability in confined spaces. Its primary purpose centers on material handling, grading, and loading operations across urban construction sites, agricultural properties, and municipal maintenance yards where full-size equipment cannot operate efficiently. Diesel configurations still dominate installed base economics, yet electric product types are capturing disproportionate R&D allocation as battery energy density improves and on-site emissions restrictions tighten. Equipment rental end users represent the most margin-accretive channel, converting capital expenditure volatility into predictable fleet utilization revenue.
EPA Tier 4 Final regulations in the United States, EU Stage V standards administered by ECHA-aligned bodies, and Japan's METI energy-efficiency benchmarks collectively elevate engine compliance costs and filter maintenance burdens. These frameworks redirect buyer preference toward electric and hybrid alternatives that bypass aftertreatment complexity while satisfying urban jobsite access rules. Stakeholders must monitor battery supply chain localization policies and charging infrastructure buildouts as determinants of which powertrain segments achieve viable total cost of ownership parity.
Market Dynamics
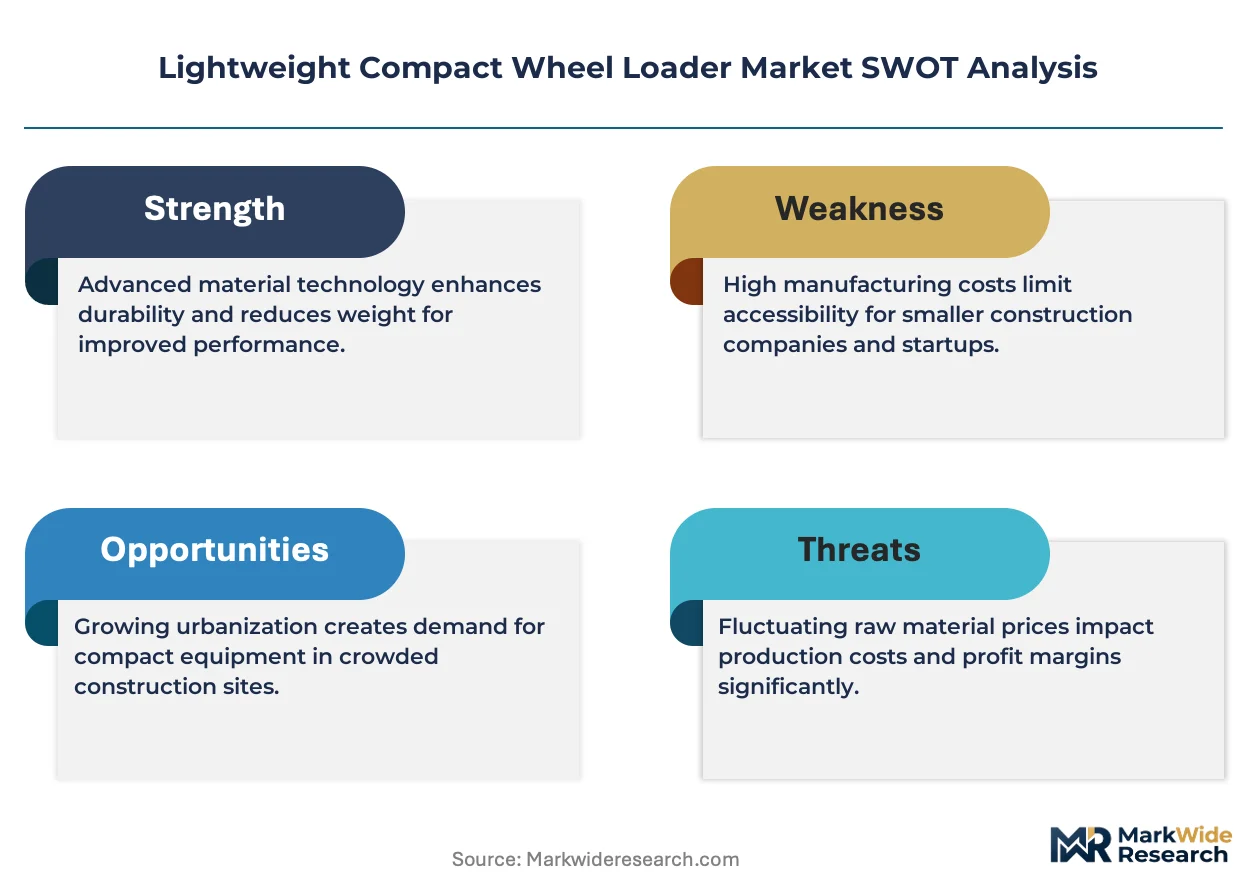
Electric powertrain migration is fragmenting established diesel-aftertreatment supply relationships as battery energy density improvements and urban emissions mandates rewrite equipment procurement criteria across municipal and rental fleet channels.
Growth Catalysts
- EPA Tier 4 Final compliance costs:Diesel aftertreatment complexity is redirecting capital toward electric alternatives that eliminate DEF systems and DPF maintenance burdens in United States urban construction zones.
- Municipal fleet electrification mandates:Cities across Germany and Japan are specifying zero-emission equipment for infrastructure maintenance contracts, creating guaranteed demand pools for battery-powered loaders.
- Telematics-enabled utilization tracking:Connected fleet services are allowing rental companies to price by actual machine hours rather than calendar periods, improving asset turnover metrics.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack manufacturing concentrates in East Asian production clusters, exposing European and North American OEMs to raw material logistics volatility and trade policy friction.
- Charging infrastructure gaps:Rural construction sites and agricultural properties lack the grid capacity or fast-charging hardware needed to support electric loader deployment at scale.
- Skilled technician scarcity:High-voltage system diagnostics and battery thermal management require training pipelines that vocational programs have not yet scaled to match equipment rollout timelines.
Strategic Opportunities
- EU Green Deal public procurement rules:Carbon footprint disclosure requirements for municipal contracts are creating preferential bidding status for electric equipment suppliers in European urban markets.
- Telematics-integrated predictive maintenance:Machine learning applied to hydraulic pressure and vibration sensor data is opening subscription revenue streams that decouple service income from parts sales.
- Sub-50-horsepower agricultural crossover:Landscaping contractors and small-scale farming operations in Japan represent an underserved segment where compact loader versatility overlaps with tractor replacement cycles.
Industry Challenges
- Battery thermal management in extreme climates:Cold-weather performance degradation and fast-charge cycle limitations complicate electric loader specification for Canadian and Nordic municipal snow removal operations.
- CE marking documentation burden:EU Machinery Directive technical file requirements and third-party conformity assessment timelines are extending product launch cycles for non-European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Compact Wheel Loader Market |
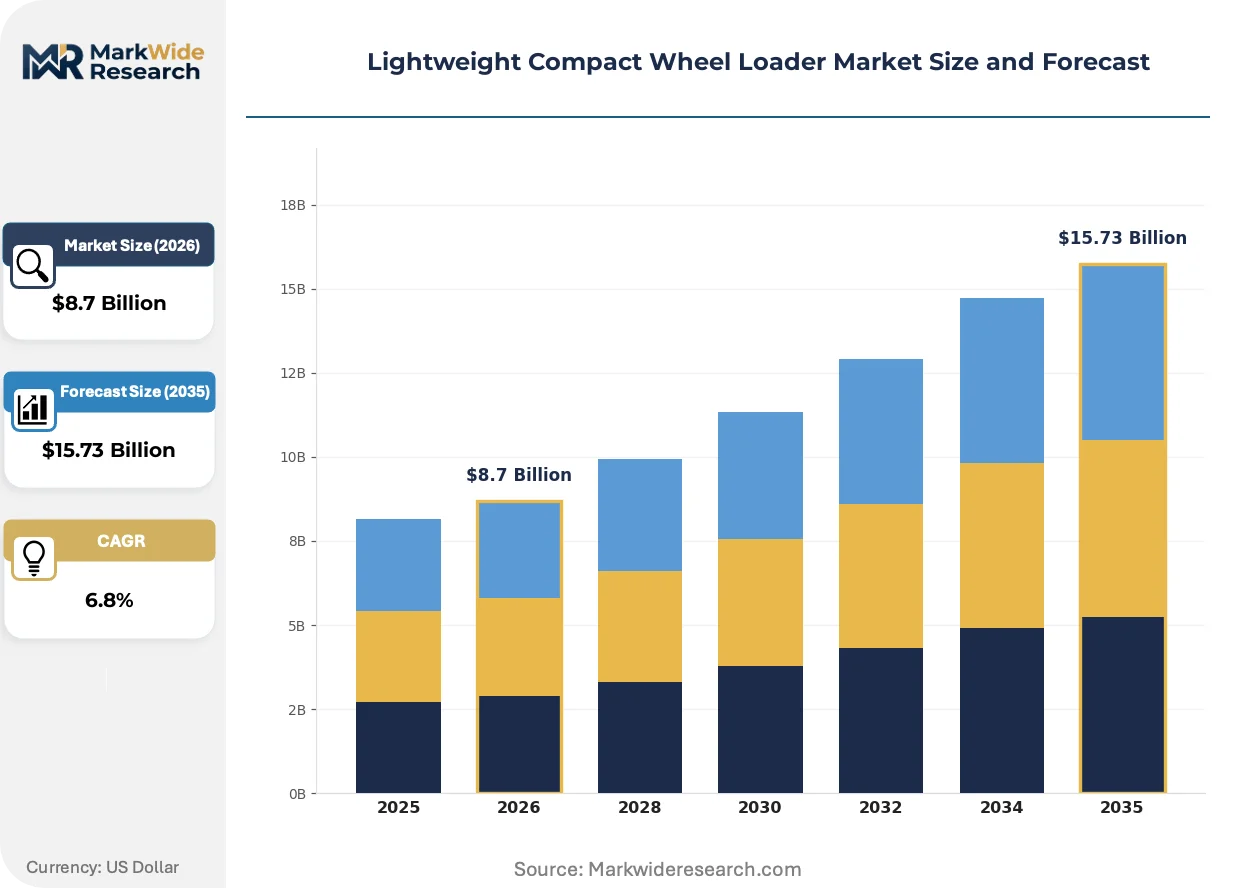
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Diesel, Hybrid Application: Construction, Landscaping, Agriculture, Demolition End User: Contractors, Farmers, Municipalities, Equipment Rental Size: Small, Medium, Large, Extra Large |
| Companies Covered | Bobcat Company, CNH Industrial N.V., Caterpillar Inc., Liebherr Group, J.C. Bamford Excavators Limited, Volvo Construction Equipment, Kubota Corporation, Doosan Infracore Co. Ltd., Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Compact Wheel Loader Market Strategic Shifts
Powertrain diversification is splitting equipment platforms into parallel development tracks as diesel refinement, battery-electric, and hydrogen fuel cell architectures compete for engineering resources and capital allocation.
Telematics integration is fragmenting fleet management software ecosystems as OEMs deploy proprietary platforms that lock operator data within branded environments. Rental companies and large contractors in the United States are demanding API interoperability to consolidate mixed-fleet visibility. This data siloing is compressing third-party fleet management software margins and forcing consolidation among independent platform providers.
EU Stage V emissions standards administered by ECHA-aligned bodies are mandating particulate matter and nitrogen oxide thresholds that diesel engines can only meet through complex aftertreatment systems. The industrial consequence is elevated total cost of ownership for sub-100-horsepower equipment that cannot amortize compliance costs across sufficient operating hours. Urban construction segments in German and French metropolitan zones are responding by accelerating electric pilot programs and rewriting municipal tender specifications.
Equipment-as-a-service contracting is displacing traditional capital purchase and finance lease structures among mid-sized earthmoving contractors. The rental channel is capturing this shift through multi-year managed fleet agreements that bundle maintenance, telematics, and upgrade rights. This procurement evolution is most visible in North American markets where contractor balance sheet constraints and interest rate volatility have compressed equipment ownership tenures.
Lightweight Compact Wheel Loader Market Segmentation
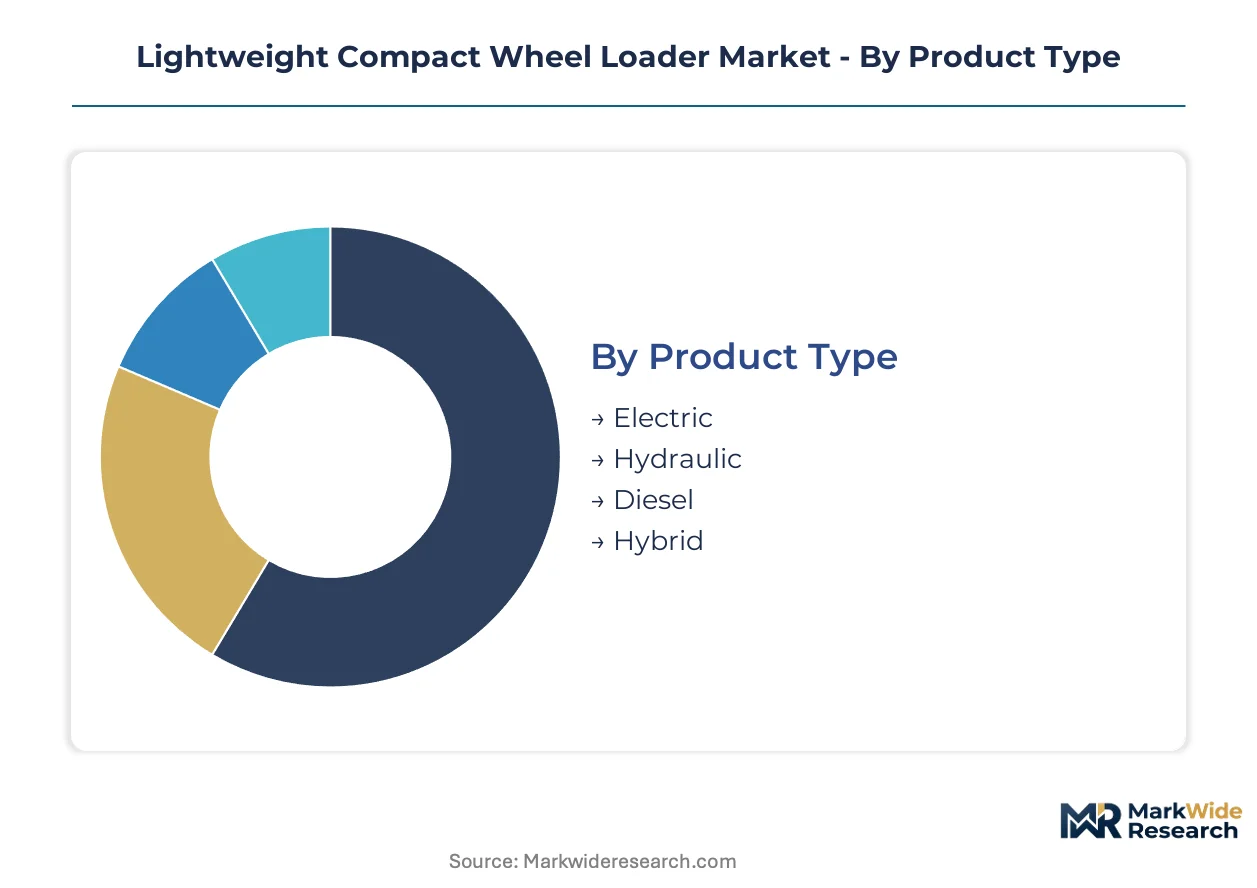
Segmentation in the lightweight compact wheel loader market reveals how powertrain technology, application intensity, and procurement channel economics fragment equipment specifications across municipal, agricultural, and rental demand pools. Understanding these splits enables OEMs to align R&D allocation with segments where battery-electric alternatives can achieve total cost of ownership parity fastest.
Product Type:
Domestic production clusters in Germany and Japan concentrate electric and hybrid platform engineering, while diesel variants flow through established export channels to North American rental fleets and emerging markets. Hydraulic systems retain regional manufacturing footprints tied to component supplier ecosystems.
- Electric:Lithium-ion battery packs with integrated thermal management deliver zero-emission operation for urban construction zones under EPA and EU Stage V restrictions. Municipalities in Germany and Japan are mandating electric specifications for infrastructure maintenance tenders, creating guaranteed demand pools that bypass diesel aftertreatment complexity.
- Diesel:Tier 4 Final and Stage V compliant engines with DEF injection and DPF regeneration systems dominate installed base economics across North American agricultural and rural construction applications. Equipment rental channels favor diesel for mixed-fleet deployment where charging infrastructure remains unavailable.
- Hydraulic:Open-center and load-sensing hydraulic architectures optimize lift capacity and breakout force for material handling intensity.
- Hybrid:Parallel diesel-electric configurations capture regenerative braking energy for intermittent duty cycles in landscaping and demolition segments.
Diesel commands the established base. The steepest expansion runs through electric platforms as battery energy density improvements and urban emissions mandates rewrite procurement criteria.
Application:
Application intensity determines frame durability specifications and attachment compatibility, with construction and demolition segments driving premium component sourcing while agriculture and landscaping prioritize versatility over extreme duty ratings.
- Construction:Urban building sites and road maintenance operations demand articulated steering precision and compact turning radii for material stockpiling and truck loading in confined spaces. German metropolitan infrastructure projects are specifying zero-emission equipment, accelerating electric loader penetration where diesel access restrictions apply.
- Landscaping:Turf-sensitive rubber tire configurations and low ground pressure designs serve golf course maintenance and residential property development. Japanese landscaping contractors represent an underserved crossover segment where compact loader versatility overlaps with tractor replacement cycles.
- Agriculture:Bale handling, feed mixing, and manure management applications require quick-attach systems compatible with forks, grapples, and buckets.
- Demolition:Reinforced cab structures and debris protection packages withstand impact loads and airborne particulate exposure.
Construction anchors volume concentration. Landscaping is climbing the fastest as aesthetic ground maintenance contracts expand across suburban development corridors.
End User:
Procurement channel economics split sharply between capital-owning contractors and farmers versus utilization-focused rental companies that convert equipment volatility into predictable fleet revenue streams.
- Equipment Rental:United States rental channels capture the most margin-accretive demand by bundling maintenance, telematics, and upgrade rights into multi-year managed fleet agreements. Telematics-enabled utilization tracking allows pricing by actual machine hours rather than calendar periods, improving asset turnover metrics.
- Municipalities:Public procurement rules across Germany, Japan, and the United States are expanding compact equipment fleets for urban infrastructure maintenance. EU Green Deal carbon footprint disclosure requirements create preferential bidding status for electric equipment suppliers in European urban markets.
- Contractors:Mid-sized earthmoving operations balance ownership tenures against balance sheet constraints and interest rate volatility.
- Farmers:Small-scale agricultural properties in Japan and the United States Midwest prioritize sub-50-horsepower segments where tractor replacement cycles create equipment turnover opportunities.
Equipment rental commands margin leadership. Municipal electrification mandates are gaining share fastest as cities rewrite tender specifications.
Size:
Weight class segmentation aligns with transport logistics constraints and jobsite access limitations, with sub-12,000-pound configurations dominating urban deployment where full-size equipment cannot operate efficiently.
- Small:Sub-6,000-pound operating weights enable trailer transport behind standard pickup trucks and access through residential gates and landscape pathways. Landscaping contractors in Japan and the United States deploy small-frame units for golf course and estate maintenance where ground disturbance minimization determines equipment selection.
- Medium:6,000-12,000-pound class anchors the core lightweight definition, balancing lift capacity with maneuverability in urban construction zones. Municipal fleets across German cities standardize on medium-frame electric units for street maintenance and snow removal operations.
- Large:12,000-18,000-pound configurations approach compact loader upper limits while retaining rubber-tired mobility advantages.
- Extra Large:Near-full-size specifications serve specialized material handling applications where wheel loader architecture outperforms skid-steer alternatives.
Medium size classes anchor fleet standardization. Small configurations are expanding most quickly as landscaping and residential construction channels deepen equipment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final compliance costs and EU Stage V emissions mandates are redirecting procurement capital toward electric alternatives in United States and German urban construction zones. Municipal electrification programs in Japan and infrastructure maintenance tenders across multiple geographies are creating guaranteed demand pools for battery-powered equipment.
United States
Equipment rental channels dominate demand concentration by bundling maintenance and telematics into multi-year managed fleet agreements. EPA Tier 4 Final regulations elevate diesel aftertreatment complexity and redirect capital toward electric loaders in metropolitan construction zones. Midwest agricultural properties and Sun Belt urban development corridors anchor diesel installed base economics.
Germany
Municipal fleet electrification mandates specify zero-emission equipment for infrastructure maintenance contracts in Berlin, Munich, and Hamburg metropolitan zones. EU Stage V standards administered by ECHA-aligned bodies filter non-compliant manufacturers from European market access. Bavarian and Baden-Württemberg engineering clusters concentrate electric platform development.
Japan
METI energy-efficiency benchmarks accelerate hybrid and electric powertrain development for domestic municipal fleets. Landscaping contractors and small-scale farming operations represent underserved crossover segments where compact loader versatility overlaps with tractor replacement cycles. Kanto and Kansai industrial corridors anchor domestic manufacturing concentration.
China
Dual carbon goals and MEE emissions frameworks redirect domestic OEM engineering resources toward electric platform development. Battery supply chain localization policies determine which powertrain segments achieve viable total cost of ownership parity. Yangtze River Delta manufacturing clusters concentrate lithium-ion cell production capacity.
India
PLI scheme incentives for automotive and industrial machinery electrification are stimulating domestic assembly capacity for compact equipment. BIS certification requirements and DGFT trade policies shape import substitution dynamics for sub-50-horsepower segments. Maharashtra and Gujarat industrial corridors anchor component supplier ecosystem development.
Lightweight Compact Wheel Loader Market Competitive Environment
Player mix skews toward integrated construction equipment conglomerates with captive dealer networks and specialized agricultural machinery crossovers leveraging sub-50-horsepower engineering heritage. Strategic archetypes include rental channel specialists bundling telematics and maintenance into managed fleet agreements, municipal procurement specialists optimizing for zero-emission compliance, and agricultural crossover players exploiting tractor replacement cycles. Dominant competitive moves center on telematics platform integration and electric powertrain platform development.
Among North American rental channel anchors, Bobcat Company and Caterpillar Inc. exemplify the integrated dealer network archetype controlling contractor procurement access. Volvo Construction Equipment represents the telematics-integrated services tier where connected fleet offerings compress third-party software margins. Kubota Corporation occupies the agricultural crossover position where sub-50-horsepower engineering heritage translates into landscaping and small-scale farming demand capture.
| Leading Market Players |
|---|
| Bobcat Company |
| CNH Industrial N.V. |
| Caterpillar Inc. |
| Liebherr Group |
| J.C. Bamford Excavators Limited |
| Volvo Construction Equipment |
| Kubota Corporation |
| Doosan Infracore Co. Ltd. |
| Komatsu Ltd. |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Machinery Directive gates both European market access qualification and price stratification across certification tiers, compressing margins for non-compliant manufacturers while enabling premium positioning for OEMs bearing full conformity assessment documentation.
Pricing Analysis
Certification level creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking completeness, EPA Tier 4 Final compliance status, and telematics bundling depth. Cost compression in economy diesel tiers is intensifying because rental channel procurement teams exploit fleet-scale purchasing power. Municipal buyers exhibit lowest price sensitivity due to electrification mandate compliance requirements, while independent contractors face acute margin pressure from interest rate volatility.
Supply Chain Analysis
Lithium-ion cell production concentration in China's Yangtze River Delta and South Korea's industrial corridors creates single-source vulnerability for battery pack assembly. European and North American OEMs draw from East Asian cathode material suppliers and German hydraulic component specialists for core drivetrain assemblies. Tariff exposure on finished battery packs and semiconductor shortages for telematics controllers generate supply chain friction. Distribution runs through captive dealer networks in mature markets and direct municipal procurement channels in electrification-leading geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through emissions compliance certification erects durable defensive moats, as EPA Tier 4 Final and EU Stage V documentation burdens lock out unqualified competitors from tender participation in high-value municipal segments.
For Market Incumbents: Shield dealer network relationships from telematics platform disintermediation by mandating API interoperability standards that prevent third-party fleet management software from capturing operator data. Accelerate backward integration into battery thermal management systems to secure supply continuity against East Asian cell production volatility. Prioritize CE marking technical file investment to maintain European municipal procurement access as conformity assessment timelines extend. For New Entrants and Emerging Players: EPA fast-track certification for electric powertrain variants offers accelerated market entry compared to diesel aftertreatment complexity. Japanese landscaping contractors and sub-50-horsepower agricultural crossover segments represent the most penetrable white space, as tractor replacement cycles create equipment turnover opportunities with limited incumbent specialization. Pursue equipment-as-a-service contracting models that bundle maintenance and telematics to bypass capital purchase barriers among mid-sized contractors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric platform development as battery engineering and thermal management R&D demands expand. Long-term viability favors OEMs with integrated dealer networks and captive telematics platforms that generate recurring service revenue. Acquisition targets should demonstrate CE marking competence and municipal fleet relationships. Monitor battery supply chain localization policy announcements as the critical inflection signal for total cost of ownership parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Development | EPA Tier 4 Final compliance costs redirect procurement capital toward zero-emission alternatives in urban zones. |
| Telematics Platform Integration | Connected fleet services lock operator data within branded environments, compressing third-party software margins. |
| CE Marking Certification Investment | EU Machinery Directive technical file requirements filter non-compliant manufacturers from European tender access. |
| Dealer Network Expansion | Captive distribution channels control rental and contractor procurement access across North American markets. |
| Battery Thermal Management R&D | Cold-weather performance optimization opens specification opportunities for Canadian and Nordic municipal snow removal. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment rental fleet managers, municipal procurement officers, OEM product development executives, and aftermarket service heads; and secondary validation through EPA regulatory filings, EU Stage V conformity assessment databases, customs trade records, and SEC 10-K equipment segment disclosures. Bottom-up triangulation across dealer inventory data and top-down reconciliation against national construction equipment registration statistics anchored volume estimates.
Across the projection horizon, the analytical framework modeled powertrain technology splits, application intensity tiers, procurement channel economics, and weight class specifications. CAGRs derived from segment-level growth rate reconciliation against macroeconomic construction activity indices and municipal capital expenditure patterns. Battery energy density improvement curves and charging infrastructure buildout timelines served as electric penetration scenario inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained emissions regulatory stringency and lithium-ion cost decline curves; material deviation in trade policy or raw material pricing would warrant model refresh. Practitioners should keep alternative scenarios live as battery supply chain localization policies and grid capacity expansion timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Cocoa Products Market
Others
Bulgur Market
Others
China Cloud Gaming Technology Market
Others
Human Enhancement Technology Market
Others
Digital Transformation of Maritime Freight Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Foldable Smartphone Market
Others
Safety Instrumented System (SIS) Market
Others
Heat Treatment Furnace Market
Others
Smart Plug Market
Others
Rotary Dial Machine Market
Others
Drum Motor Market
Others
Mobile Computer Cart Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Internet of Things Testing Market
Others
Global Aircraft Sensors Market