
 Canada Laser Hair Removal Market | 2026-2036
Canada Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Laser Hair Removal Market Insights
Aftermarket service revenue from laser handpiece refurbishment and calibration contracts is reshaping profitability structures for Canadian clinic operators. Alma Lasers leverages its integrated training academy model to sustain recurring revenue streams across Ontario and British Columbia. Candela Medical anchors its presence through authorized service centers that control spare parts distribution and warranty fulfillment. Cutera competes by specializing in dual-wavelength platforms that address diverse skin phototypes prevalent in Canada's multicultural patient base.
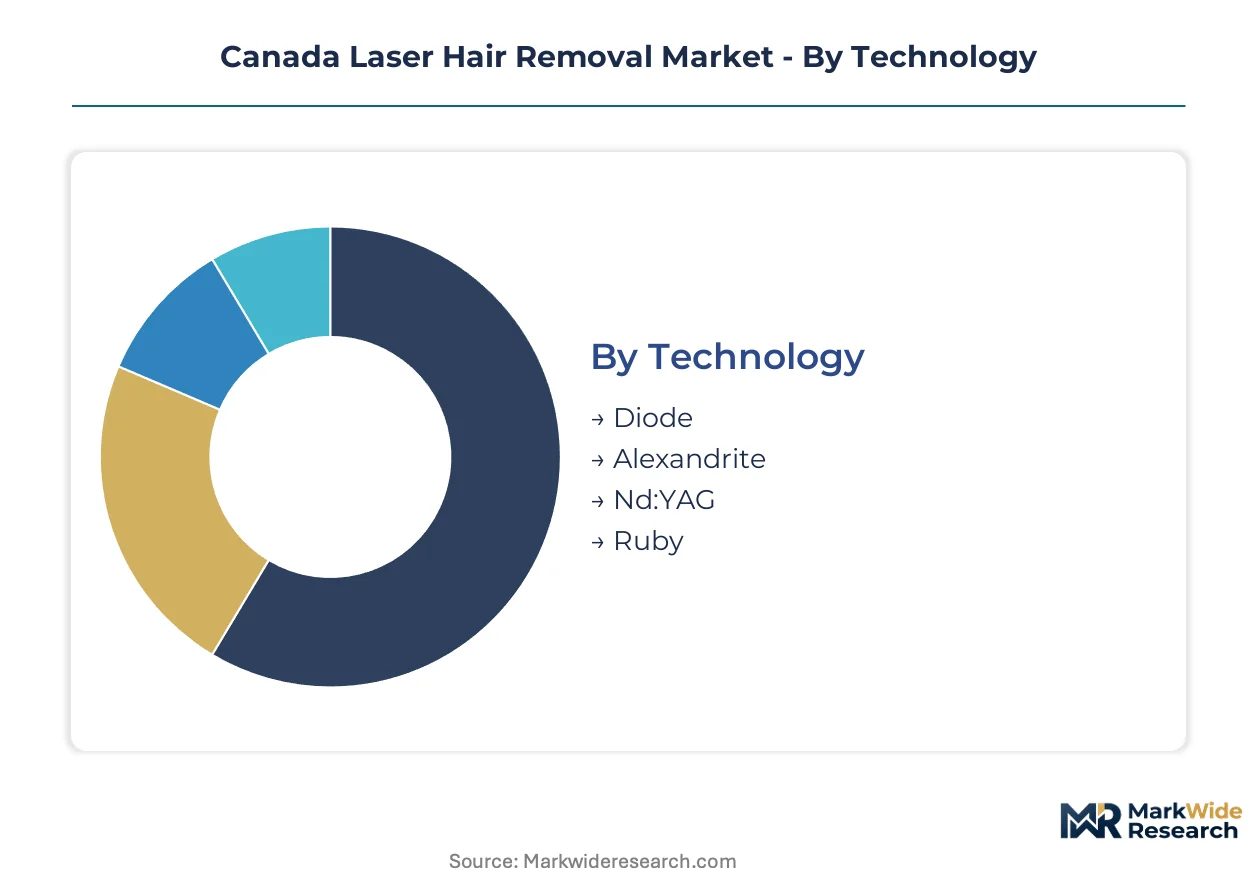
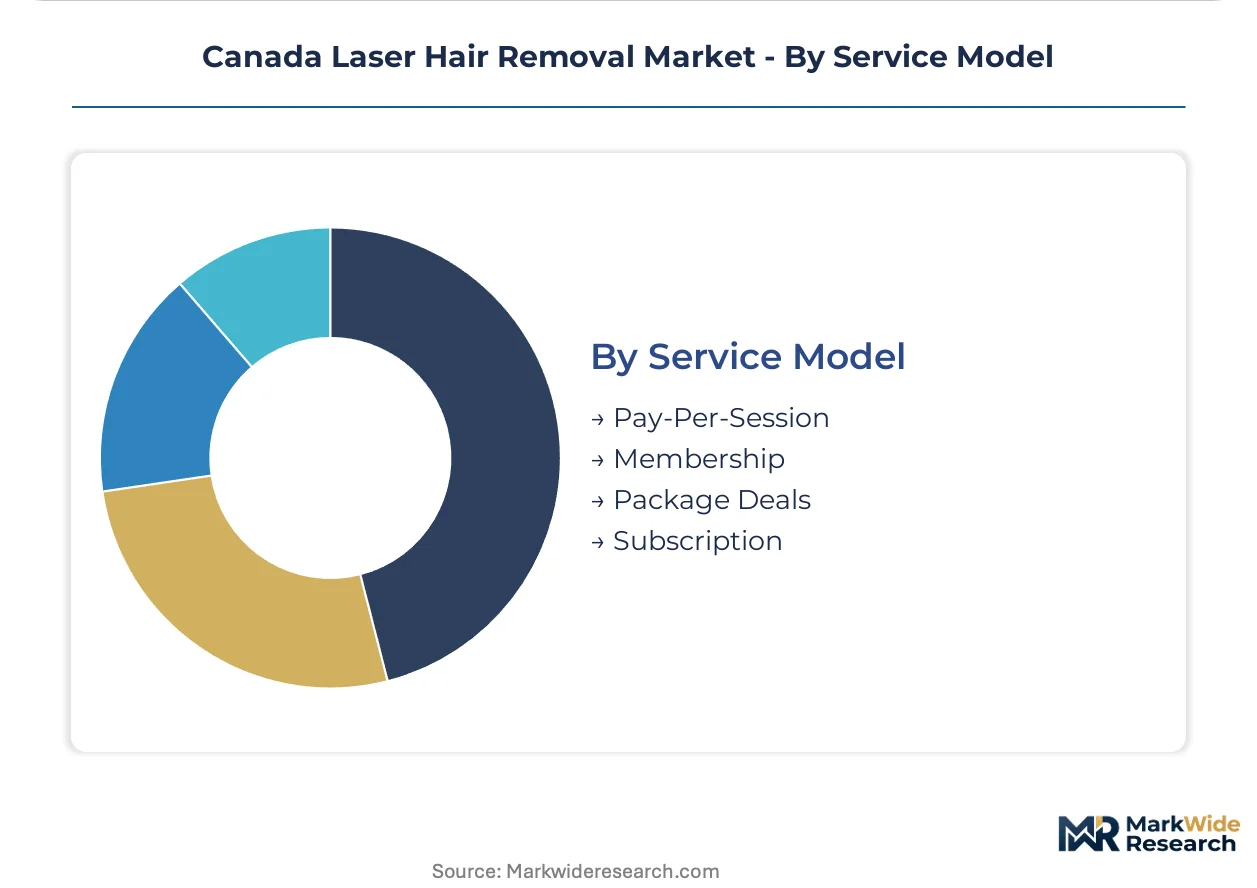
Laser hair removal employs selective photothermolysis, wherein melanin in the hair follicle absorbs concentrated light energy at wavelengths between 755 nm and 1064 nm to thermally disable the bulb without damaging surrounding dermal tissue. The technology segment spans diode, Alexandrite, Nd:YAG, and Ruby systems, with diode platforms dominating installed base volumes due to operational versatility across Fitzpatrick skin types I through VI. The end user dimension splits across salons, dermatology clinics, medical spas, and hospitals, with medical spas capturing the fastest expansion as provincial regulations in Alberta and Quebec permit non-physician operators under supervised protocols. The service model dimension encompasses pay-per-session, membership, package deals, and subscription structures, with subscription and membership offerings concentrating margin pools through predictable cash flow and reduced per-session acquisition costs.
Health Canada's Medical Devices Directorate governs laser classification, import licensing, and adverse event reporting for all energy-based aesthetic devices entering the Canadian market. Provincial colleges of physicians and surgeons in Ontario, British Columbia, and Alberta layer additional operator certification requirements that filter market access for device manufacturers and clinic chains. The Radiation Emitting Devices Act administered by Health Canada sets mandatory safety labeling and performance standards. Stakeholders must monitor evolving provincial scope-of-practice debates that could expand or restrict technician-operated laser procedures outside physician-directed settings.
Market Dynamics
Subscription-based service models are restructuring cash flow predictability across Canadian medical spas, compressing customer acquisition costs while locking in recurring revenue streams that alter capital deployment timelines for clinic operators.
Growth Catalysts
- Health Canada Class II/III device pathways:Clearer import licensing frameworks accelerate market entry for diode and Nd:YAG platforms, reducing regulatory friction for manufacturers targeting Ontario and British Columbia.
- Multicultural skin phototype demand:Canada's diverse patient base drives adoption of dual-wavelength systems capable of treating Fitzpatrick types I through VI without protocol switching.
- Provincial scope-of-practice expansion:Alberta and Quebec regulations permitting supervised non-physician operators widen addressable labor pools for medical spa chains.
Market Restraints
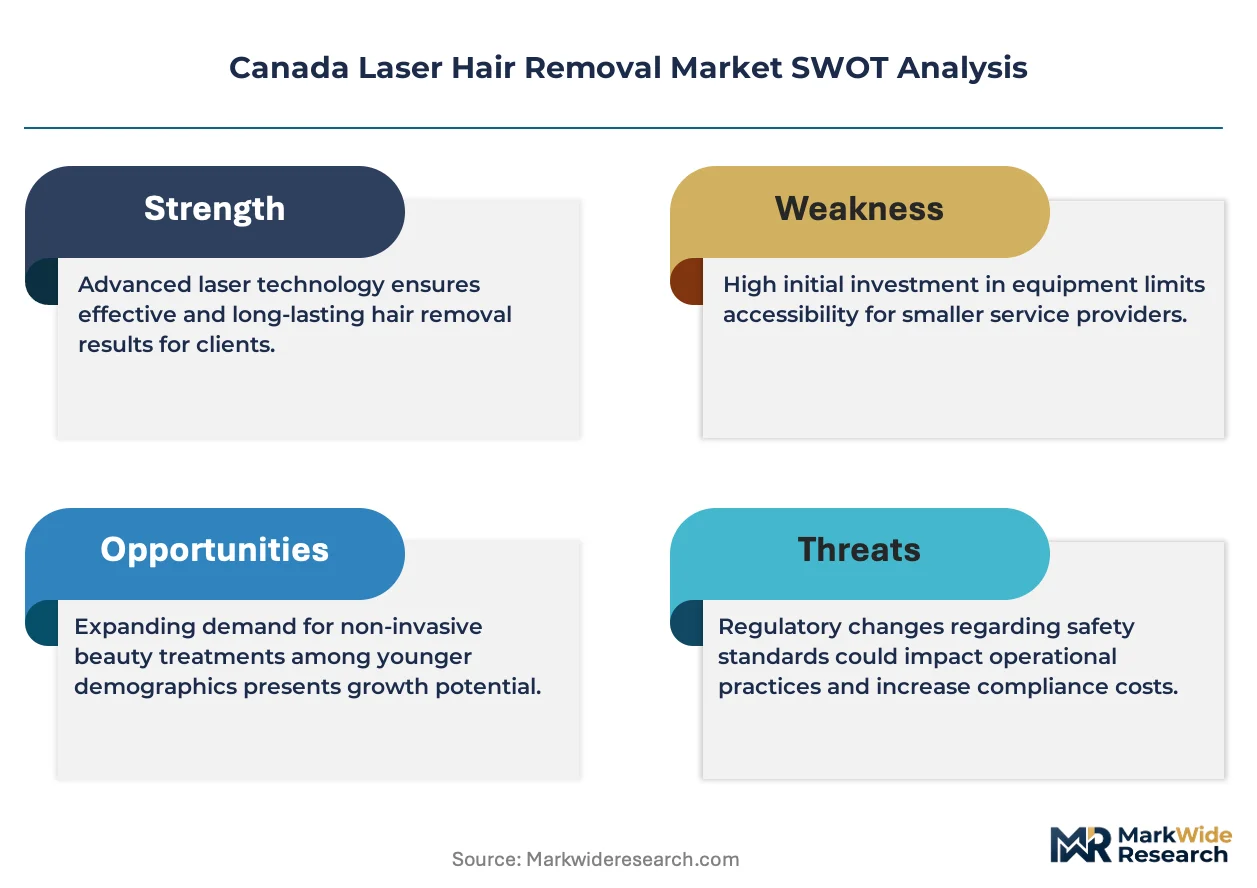
- Capital intensity of laser platforms:Diode and Alexandrite systems require substantial upfront investment, constraining independent salon entry and favoring consolidated clinic chains.
- Handpiece refurbishment bottlenecks:Limited authorized service centers in Prairie provinces create spare parts scarcity, extending equipment downtime for remote operators.
- IPL device substitution:Lower-cost intense pulsed light systems capture price-sensitive segments, pressuring pure laser providers in suburban and secondary markets.
Strategic Opportunities
- Atlantic Canada penetration:Halifax and Moncton medical spa density remains below national averages, presenting first-mover expansion potential for subscription-model operators.
- At-home device convergence:Clinic operators can capture value from FDA-cleared home-use diode adjuncts through hybrid treatment protocols and consumable supply chains.
- Indigenous community outreach:Federally funded health access programs create procurement channels for mobile laser services in remote northern jurisdictions.
Industry Challenges
- Laser safety officer certification timelines:Provincial college requirements in Ontario and British Columbia delay technician deployment, stretching onboarding cycles for expanding chains.
- Legacy electronic medical record integration:Aesthetic-specific practice management platforms lack standardized APIs, forcing costly custom middleware development for multi-location operators.
- Adverse event reporting complexity:Health Canada's mandatory incident documentation imposes administrative burdens that scale disproportionately for smaller independent clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Laser Hair Removal Market |
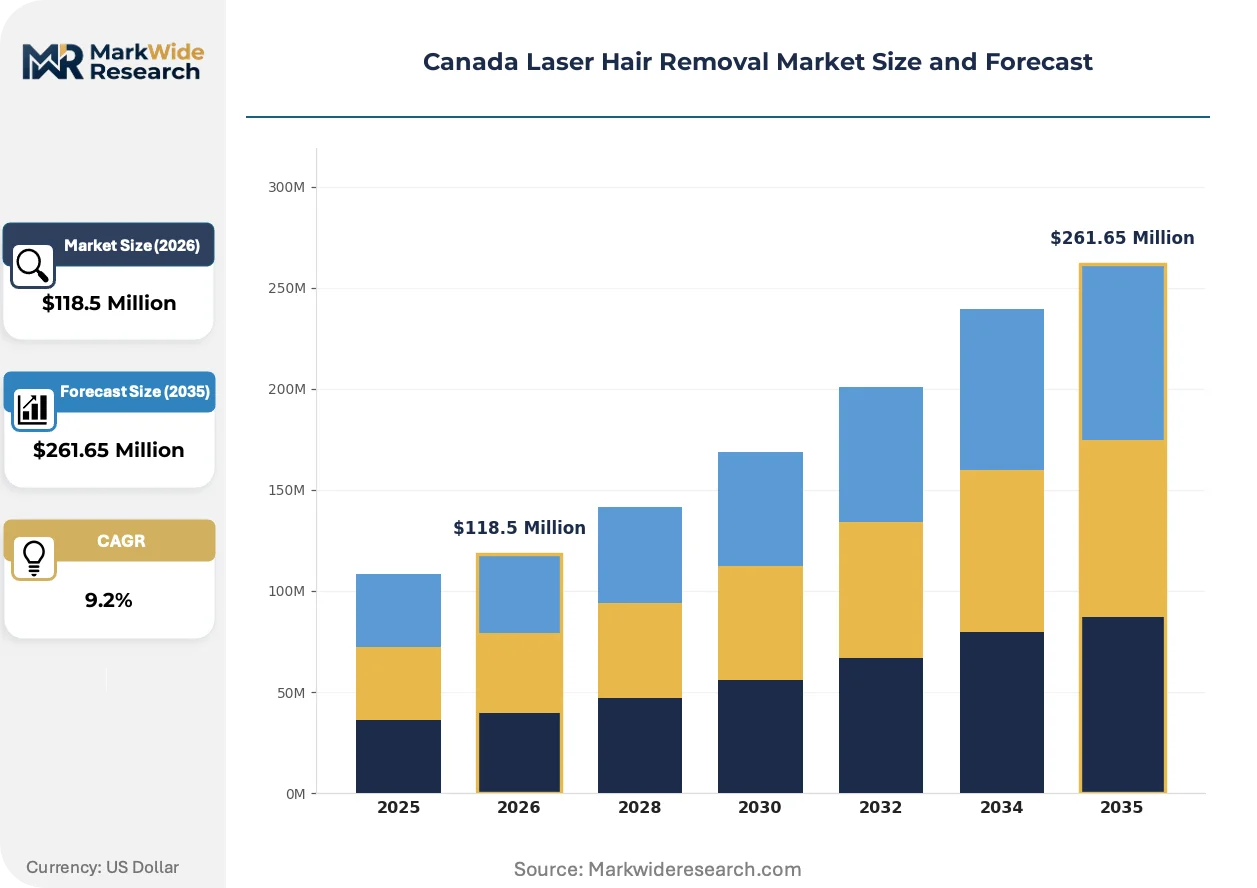
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $261.65 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Diode, Alexandrite, Nd:YAG, Ruby End User: Salons, Dermatology Clinics, Medical Spas, Hospitals Session Type: Full Body, Facial, Underarm, Bikini Line Service Model: Pay-Per-Session, Membership, Package Deals, Subscription |
| Companies Covered | Alma Lasers, Candela Medical, Cutera, Fotona, Lutronic, Venus Concept, Cynosure, Lumenis, Laser Clinics Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Laser Hair Removal Market Trends and Innovations
Hardware-software integration is redefining treatment precision and operational efficiency across Canadian aesthetic practices. Three interconnected developments are compressing traditional service delivery models.
Motion-tracking skin cooling technology is collapsing treatment time variability for high-density hair removal protocols. Medical spas in Toronto and Vancouver deploy these integrated diode systems to standardize session durations regardless of technician experience. The compression of per-procedure labor minutes enables higher daily patient throughput without expanding physical footprint.
Health Canada's Medical Devices Directorate is tightening adverse event reporting requirements for energy-based aesthetic devices through enhanced post-market surveillance mandates. Manufacturers must now submit real-world safety data quarterly rather than annually. Class III laser importers are responding by embedding cloud-connected usage logging to automate compliance documentation.
Membership bundling is displacing discrete session pricing across Alberta and Quebec medical spa chains. Consumers pre-commit to twelve-month treatment plans with automated monthly billing, replacing pay-per-visit models. This behavioral shift concentrates margin pools with predictable cash flows while reducing per-acquisition marketing spend for clinic operators in competitive urban corridors.
Canada Laser Hair Removal Market Segmentation
Segmentation in the Canada laser hair removal market reveals how technology choices, operator settings, and pricing architectures determine competitive positioning. Understanding these dimensions exposes where margin pools concentrate and which configurations Health Canada's device classifications favor.
Technology:
Mature diode platforms dominate installed volumes while emerging wavelengths reshape clinical versatility across Canadian multicultural patient bases.
- Diode:Operating at 800-810 nm wavelengths, these systems deliver consistent melanin absorption across Fitzpatrick skin types I through VI. Demand concentrates in Toronto and Vancouver medical spa chains seeking operational flexibility without protocol switching between patients.
- Alexandrite:The 755 nm wavelength offers superior efficacy on lighter skin phototypes through higher melanin selectivity. Alberta and Quebec operators deploy these platforms where supervised technician protocols expand addressable labor pools for high-volume practices.
- Nd:YAG:The 1064 nm wavelength penetrates deeper dermal layers with minimal epidermal absorption, serving darker skin phototypes prevalent in Canada's South Asian and Afro-Caribbean communities.
- Ruby:The original 694 nm laser technology retains niche applications for fine, light-colored hair on fair skin, primarily in legacy dermatology clinic installations.
Diode retains volume leadership; Nd:YAG holds the steepest expansion curve as multicultural demographic demand intensifies.
End User:
Cost tier stratification separates capital-intensive medical settings from leaner service operators, with regulatory scope-of-practice rules determining expansion trajectories.
- Medical Spas:Hybrid clinical-aesthetic environments combine physician oversight with technician-delivered protocols. Subscription bundling in Ontario and British Columbia compresses customer acquisition costs while locking recurring revenue.
- Dermatology Clinics:Physician-directed settings command premium pricing through medical credibility and complex case handling. Calgary and Montreal practices leverage Health Canada Class III device pathways for advanced combination therapies.
- Salons:Lower capital entry points attract independent operators, though limited to IPL or lower-classification lasers under provincial aesthetic regulations.
- Hospitals:Academic medical centers and tertiary facilities deploy lasers for hirsutism associated with endocrine disorders, accessing federal procurement channels.
Medical spas capture the fastest volume expansion; dermatology clinics maintain the highest per-session revenue premiums.
Session Type:
Application-specific protocols segment treatment complexity and pricing granularity, with facial precision commanding technical premiums over larger surface areas.
- Facial:Precision protocols around sensitive periorbital and perioral zones require smaller spot sizes and enhanced cooling integration. Vancouver operators report highest margin contribution from facial membership tiers.
- Full Body:Comprehensive treatment packages span multiple anatomical zones with standardized pricing. Toronto medical spa chains use these offerings to anchor annual subscription commitments.
- Underarm:High-frequency, low-complexity sessions attract first-time laser users through accessible entry pricing and minimal discomfort profiles.
- Bikini Line:Cultural sensitivity and privacy protocols differentiate service delivery, with Montreal operators developing specialized consultation frameworks for diverse community expectations.
Full body packages drive aggregate revenue volume; facial treatments deliver the steepest margin expansion per square centimeter treated.
Service Model:
Customer type preferences are restructuring cash flow architectures, with predictable billing cycles displacing transactional revenue recognition.
- Subscription:Automated monthly billing with twelve-month minimum commitments transforms patient relationships into recurring revenue streams. Alberta chains pioneered this model under permissive scope-of-practice regulations.
- Membership:Tiered access programs bundle laser services with complementary aesthetic treatments, concentrating lifetime value through cross-selling architectures.
- Package Deals:Prepaid multi-session bundles discount per-treatment pricing while accelerating cash conversion, favored by seasonal promotional cycles in secondary markets.
- Pay-Per-Session:Discrete transactional pricing retains relevance for trial users and intermittent maintenance clients, though per-acquisition economics pressure standalone operators.
Subscription models are gaining share fastest in urban corridors; package deals retain dominance in price-sensitive Prairie markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and British Columbia deploy diode platforms for multicultural skin phototype versatility, while Alberta and Quebec favor subscription bundling under permissive technician-operated protocols. Atlantic Canada lags in medical spa density but presents first-mover expansion corridors.
Ontario
Toronto's medical spa chains drive diode laser installations for Fitzpatrick I-VI coverage without protocol switching. Health Canada's Medical Devices Directorate Class II pathways accelerate import licensing for energy-based aesthetic devices entering through Pearson logistics corridors. The Greater Toronto Area concentrates subscription-model operators compressing customer acquisition costs through automated monthly billing.
British Columbia
Vancouver operators report highest margin contribution from facial membership tiers leveraging precision protocols around periorbital zones. Provincial college certification requirements for laser safety officers filter technician deployment timelines for expanding chains. The Lower Mainland anchors cloud-connected usage logging systems automating Health Canada adverse event documentation.
Alberta
Calgary dermatology clinics leverage Class III device pathways for advanced combination therapies commanding premium pricing. Scope-of-practice regulations permitting supervised non-physician operators widen addressable labor pools for high-volume practices. Edmonton medical spa density remains below Toronto levels, presenting expansion headroom for subscription-model entrants.
Quebec
Montreal operators develop specialized consultation frameworks addressing cultural sensitivity for bikini line protocols among diverse community expectations. Provincial regulations mirror Alberta's permissive stance on technician-delivered treatments under physician oversight. The Montreal metropolitan area captures faster subscription adoption than Prairie markets through twelve-month pre-commitment structures.
Atlantic Canada
Halifax and Moncton medical spa density sits below national averages with limited authorized service centers creating spare parts scarcity. Federal procurement channels for Indigenous health access programs create mobile laser service opportunities in remote northern jurisdictions. First-mover clinic chains target subscription-model deployment before competitive saturation accelerates.
Canada Laser Hair Removal Market Competitive Landscape
Capability concentration sits with integrated training academy models; scale advantage sits with authorized service center networks controlling spare parts distribution. The vendor base stratifies across three tiers: multinational platform manufacturers, regional clinic chains, and independent salon operators. Strategic archetypes include hardware-software integrators embedding motion-tracking cooling, subscription-model aggregators bundling aesthetic services, and aftermarket service specialists capturing refurbishment revenue. Competitive moves center on M&A consolidation of clinic chains and technology licensing partnerships for dual-wavelength platform deployment.
Among multinational platform manufacturers, Alma Lasers and Candela Medical occupy positions exemplifying divergent aftermarket strategies. Alma Lasers represents the integrated training academy archetype sustaining recurring revenue through Ontario and British Columbia education infrastructure. Candela Medical anchors the authorized service center model controlling warranty fulfillment and spare parts distribution. Cutera sits within the specialization tier addressing diverse skin phototypes prevalent in Canada's multicultural patient base through wavelength platform diversity.
| Leading Market Players |
|---|
| Alma Lasers |
| Candela Medical |
| Cutera |
| Fotona |
| Lutronic |
| Venus Concept |
| Cynosure |
| Lumenis |
| Laser Clinics Canada |
| Others |
Pricing and Supply Chain Analysis
Israeli and American diode laser component suppliers anchor upstream manufacturing, concentrating margin pools with medical spa chains in Toronto and Vancouver that lock in twelve-month subscription commitments. Health Canada Class II/III import pathways filter which platforms reach Canadian operators, creating tiered access that separates authorized service center networks from independent refurbishment channels.
Pricing Analysis
Long-term service contracts dominate Canadian clinic procurement, with twelve-month subscription bundles replacing spot-session pricing across Alberta and Quebec medical spa chains. Price differentiation rests on Health Canada device classification tier and bundled technician training depth, with Class III platforms commanding premiums over Class II equivalents. Cost compression in the salon tier intensifies as IPL substitution threats from lower-cost alternatives erode per-session margins. Independent operators in Prairie markets exhibit highest price sensitivity; consolidated chains in Ontario demonstrate lowest sensitivity due to recurring revenue predictability.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk for laser platform importers navigating cross-border medical device logistics. Manufacturing concentrates in Israel, the United States, and Germany for core diode and Nd:YAG systems, with Canadian clinics drawing from these hubs through Health Canada-licensed distributors. Critical dependencies include laser handpiece optics, cooling system compressors, and cloud-connected usage logging modules. Single-source vulnerability concentrates in authorized service center networks controlling spare parts distribution for Candela Medical and Alma Lasers platforms. Distribution runs through provincial medical device wholesalers to clinic chains, with direct manufacturer relationships reserved for high-volume multi-location operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPL device substitution at the salon tier threatens laser incumbents, demanding defensive positioning around clinical efficacy differentiation and subscription-model lock-in to preserve margin pools.
For Market Incumbents: Entrench subscription bundling architectures across Ontario and British Columbia to accelerate recurring revenue concentration and compress customer acquisition costs. Deepen backward integration into handpiece refurbishment capabilities to capture aftermarket service revenue from remote Prairie operators facing spare parts scarcity. Counter IPL substitution threats by emphasizing Health Canada Class III device credibility and dual-wavelength protocol versatility for multicultural skin phototypes. For New Entrants and Emerging Players: Pursue Atlantic Canada white-space expansion in Halifax and Moncton before competitive saturation accelerates, leveraging first-mover subscription model deployment. Target supervised technician-operated protocols under Alberta and Quebec scope-of-practice regulations to bypass physician-staffing constraints. Anchor go-to-market strategy around mobile laser service delivery for Indigenous health access programs accessing federal procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medical spa chains in Toronto and Vancouver seeking platform consolidation synergies. Long-term viability across the analysis window depends on subscription-model cash flow predictability and aftermarket service revenue capture. Monitor provincial scope-of-practice expansion debates as the signal indicating technician-delivered protocol addressability and labor pool scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Model Deployment | Twelve-month automated billing locks recurring revenue for Toronto medical spa chains. |
| Authorized Service Center Expansion | Candela Medical's spare parts control reduces equipment downtime for remote Prairie operators. |
| Dual-Wavelength Platform Investment | Cutera's Nd:YAG and Alexandrite versatility addresses Canada's South Asian and Afro-Caribbean patient base. |
| Cloud-Connected Compliance Logging | Health Canada's quarterly adverse event mandates drive embedded usage documentation adoption. |
| Training Academy Infrastructure | Alma Lasers' Ontario and British Columbia education hubs sustain recurring certification revenue. |
Research Methodology
The analysis maps diode, Alexandrite, Nd:YAG, and Ruby technology segments, each validated through medical spa operators, dermatology clinic directors, biomedical equipment procurement managers, and Health Canada regulatory consultants. Primary fieldwork combined structured interviews with secondary triangulation against Health Canada Medical Devices Directorate licensing databases, provincial college of physicians scope-of-practice filings, and clinic chain subscription pricing disclosures. Bottom-up equipment installation counts and top-down service revenue estimates were reconciled across the projection horizon.
Assumption sets held Health Canada Class II/III regulatory pathways stable while varying provincial scope-of-practice expansion scenarios across the modeling period. Segmentation dimensions modeled include technology wavelength, end-user setting, session type anatomical zone, and service model billing structure. CAGRs were derived from installed base growth trajectories and per-clinic revenue intensity trends, incorporating multicultural demographic demand curves and subscription adoption velocity as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational platform manufacturers would shift outcomes through captive service network expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Microcontroller Embedded Systems Market
Others
Binoculars Market
Others
Asia-Pacific Air Separation Unit Market
Others
Cat Dry Food Market
Others
North America Industrial Wearable Devices Market
Others
Global Smart Kitchen Market
Others
High Voltage Measuring Equipment Market
Others
Channel-In-A-Box (Ciab) Market
Others
Mobile Computing Devices Market
Others
North America Printed Signage Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Global on-Demand Laundry Service Market
Others
DIY Smart Home Market
Others
Fluorapatite Market
Others
Manometers Market
Others
Radar Speed Signs Market