
 Chip Card Scanners Market | 2026-2036
Chip Card Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Card Scanners Market Insights
Southeast Asia is reconfiguring regional manufacturing networks for chip card scanner assembly. Thales leverages its aerospace-grade security credentials to dominate high-assurance government ID applications. IDEMIA sustains biometric-integrated scanner development through dedicated R&D centers in France and Singapore. NXP Semiconductors anchors the semiconductor layer with secure element chips that power EMV and contactless authentication protocols.
Chip card scanners are electromechanical devices that read data from embedded integrated circuits in payment cards, government IDs, and access credentials, typically operating at 13.56 MHz for contactless communication and conforming to ISO/IEC 7816 standards for physical chip interfaces. These devices perform cryptographic authentication, data encryption, and transaction authorization across retail point-of-sale terminals, banking ATMs, and transit fare gates. Mobile scanners and integrated scanners lead volume deployment as merchants favor compact, software-upgradable terminals over fixed desktop units. EMV chip and contactless technologies capture the fastest expansion as magnetic stripe systems face obsolescence; biometric authentication represents the emerging margin pool where hardware suppliers command premium pricing for fingerprint and iris-integrated modules.
PCI Security Standards Council frameworks mandate encryption and tamper-resistance for all certified payment terminals, directly shaping scanner hardware design and firmware architecture. EBA guidelines in Europe enforce strong customer authentication for electronic payments, compelling banks to upgrade ATM fleets with dual-interface chip card readers. The EU AI Act introduces biometric data governance that will constrain facial-recognition scanner deployments unless vendors demonstrate compliance with fundamental rights impact assessments. Stakeholders must monitor regulatory divergence between PCI-DSS evolution and emerging AI governance to anticipate certification bottlenecks and redesign cycles.
Market Dynamics
EMV migration deadlines and contactless payment mandates are forcing merchants into accelerated terminal refresh cycles, compressing hardware replacement timelines from seven years to under four.
Growth Catalysts
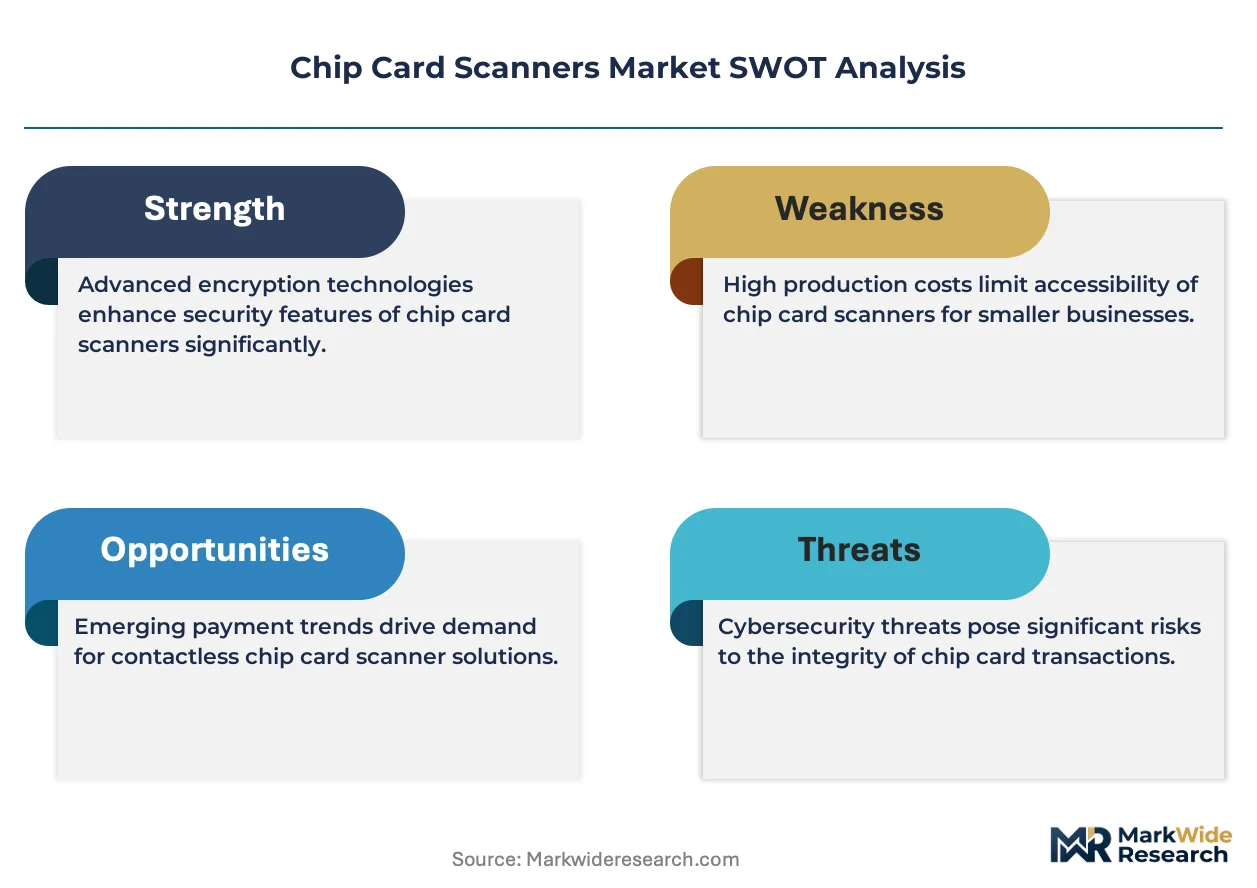
- PCI Security Standards Council certification mandates:Retailers must deploy tamper-resistant terminals to process card-present transactions, creating sustained hardware demand across merchant tiers.
- Contactless payment thresholds:Tap-to-pay transaction limits are rising in multiple jurisdictions, expanding addressable transaction volume for dual-interface readers.
- Transit authority modernization:Urban transport systems are replacing magnetic stripe fare gates with open-loop contactless acceptance, opening a specialized procurement channel.
Market Restraints
- Secure element supply concentration:Foundry capacity for certified smart card microcontrollers concentrates among a handful of semiconductor vendors, creating allocation risk during demand spikes.
- Copper and rare earth input costs:Antenna coil materials and electromagnetic shielding components face commodity price volatility that squeezes module margins.
- Biometric module technical limitations:Fingerprint sensor integration in outdoor payment terminals struggles with moisture and temperature extremes, constraining deployment latitude.
Strategic Opportunities
- India's digital payment infrastructure:The country's central bank push for card acceptance at tier-2 and tier-3 merchants creates whitespace for cost-optimized contactless readers.
- Healthcare access control convergence:Hospital systems are merging payment terminals with identity verification for patient check-in, opening integrated biometric-reader demand.
- EU AI Act biometric governance:Vendors that pre-certify facial-recognition modules against fundamental rights impact assessments will capture premium positioning in European government ID projects.
Industry Challenges
- Firmware security engineering talent scarcity:PCI-DSS certification requires specialized embedded cryptography expertise that outpaces graduate pipeline output.
- Legacy POS integration complexity:Merchants running on decade-old merchant management software face costly middleware development to enable chip card acceptance.
- Certification timeline compression:Laboratory queue bottlenecks for EMVCo and PCI testing extend product launch windows by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Card Scanners Market |
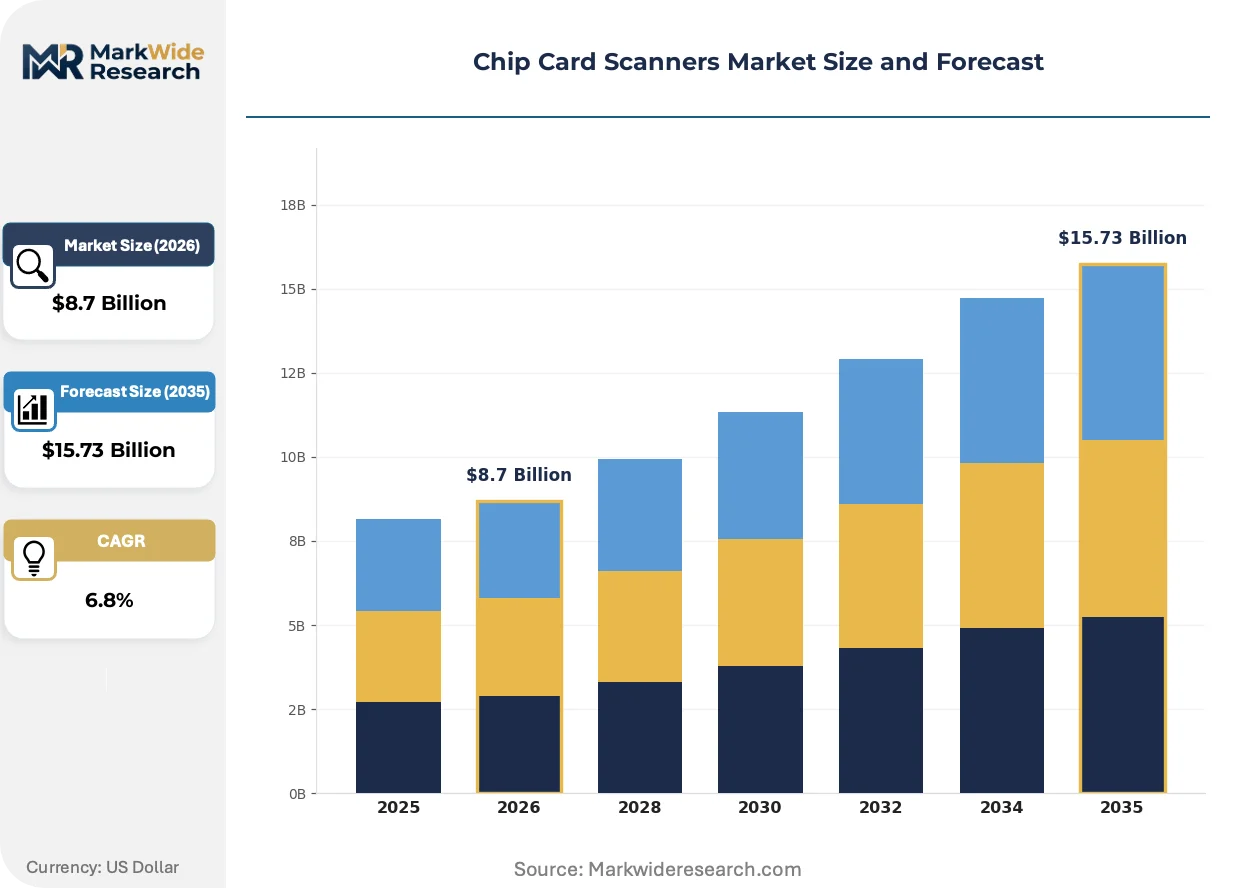
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
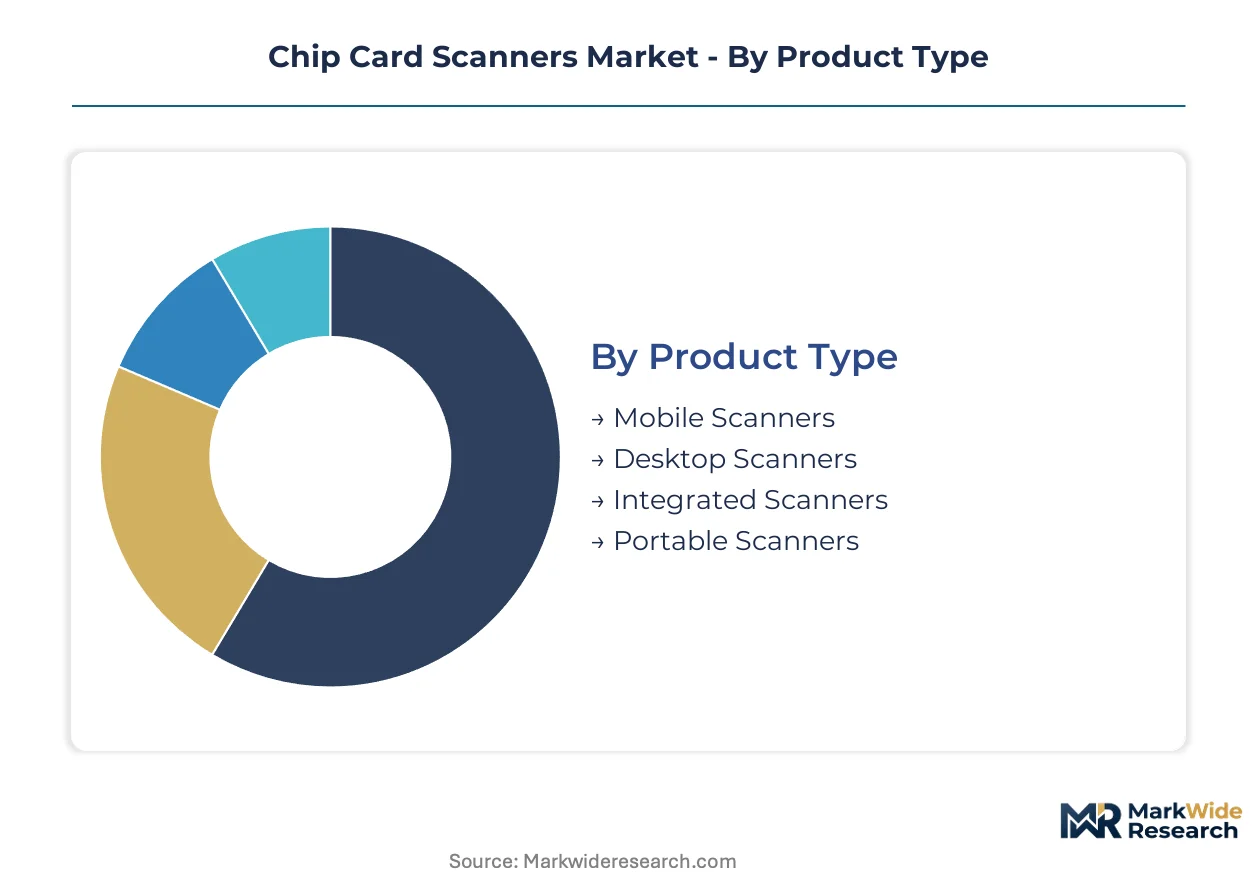
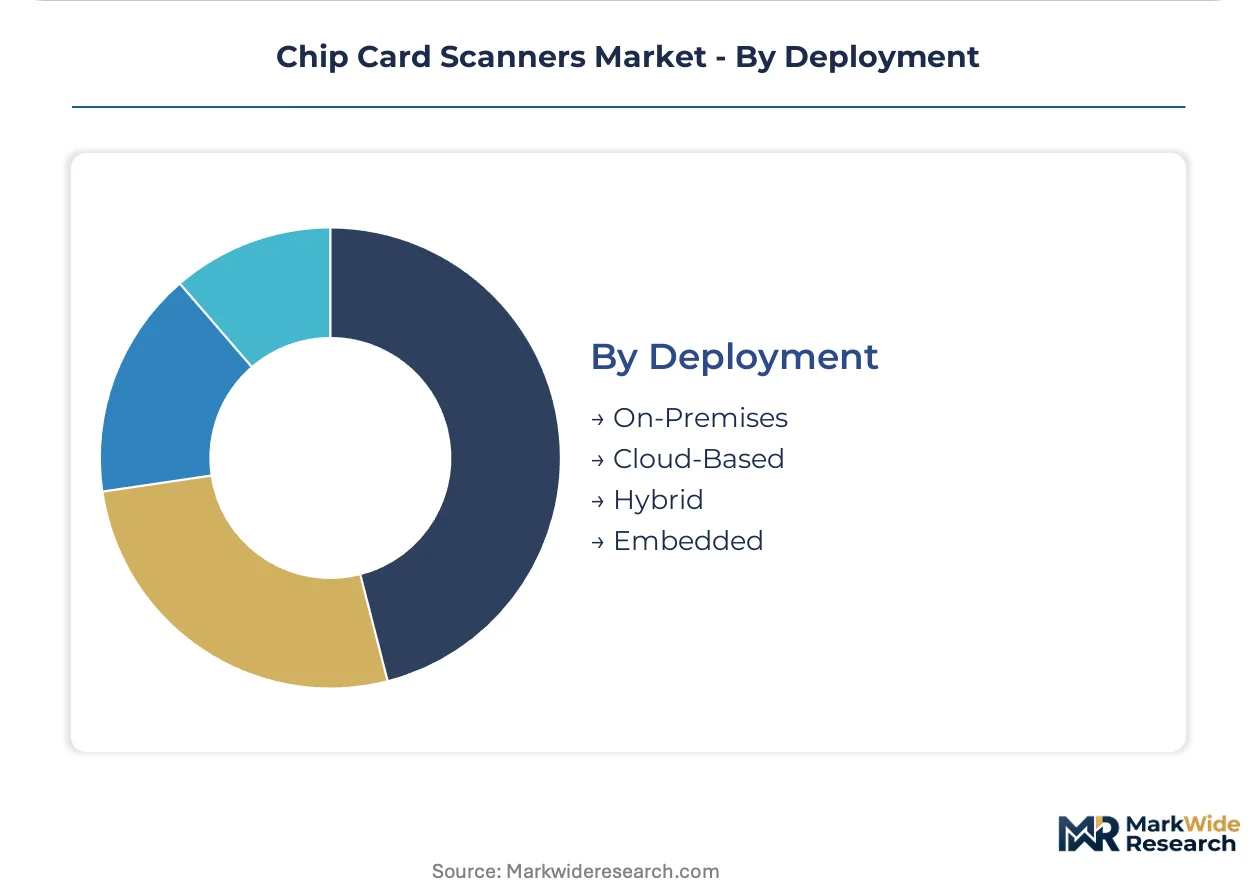
| Segmentation | Product Type: Mobile Scanners, Desktop Scanners, Integrated Scanners, Portable Scanners Technology: Magnetic Stripe, EMV Chip, Contactless, Biometric End User: Retail, Banking, Hospitality, Transportation Deployment: On-Premises, Cloud-Based, Hybrid, Embedded |
| Companies Covered | Thales, IDEMIA, Giesecke & Devrient, NXP Semiconductors, Infineon Technologies, STMicroelectronics, HID Global, CPI Card Group, Ingenico Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Card Scanners Market Trends and Innovations
Software-defined terminal architectures are decoupling payment acceptance from proprietary hardware, enabling merchant IT departments to manage fleets through cloud-based configuration rather than on-site technician visits.
SoftPOS technology is collapsing the distinction between dedicated payment terminals and general-purpose mobile devices. Android-based smartphones equipped with NFC antennas and certified secure execution environments are gaining merchant acceptance for low-volume transaction processing. This convergence is compressing addressable hardware volume in the micro-merchant segment while forcing traditional terminal vendors toward higher-assurance product tiers.
REACH restrictions on persistent organic pollutants are reshaping circuit board manufacturing for European-bound scanners. Substrate materials and flame-retardant compounds face reformulation requirements that extend validation cycles. Vendors serving EU markets are responding by dual-sourcing compliant component streams and accelerating design-for-recyclability programs to preempt extended producer responsibility mandates.
Merchant acquisition patterns are fragmenting as independent software vendors embed payment acceptance into vertical-specific SaaS platforms. Restaurant management systems, salon booking software, and fitness studio applications are bundling pre-certified reader hardware with subscription contracts. This channel shift is most pronounced in North American small-business segments, where buyers prioritize operational software integration over standalone terminal feature sets.
Chip Card Scanners Market Segmentation
Scanner manufacturers must align service infrastructure with product complexity. Mobile and integrated units demand rapid firmware update cycles, while biometric modules require specialized field calibration that reshapes margin structures across tiers.
Product Type:
After-sales service intensity varies dramatically by form factor. Desktop units need minimal intervention, whereas mobile fleets require continuous software maintenance and hardware refresh programs.
- Mobile Scanners:Battery-powered handheld terminals with cellular or Wi-Fi connectivity for field transactions. Quick-service restaurants and delivery fleets in the United States are consolidating procurement around Android-based units that support over-the-air configuration updates.
- Desktop Scanners:Fixed countertop readers with tethered power and Ethernet connectivity for high-volume checkout lanes. Demand concentrates among tier-1 retailers completing EMV compliance retrofits, though replacement cycles are lengthening as terminals reach end-of-life.
- Integrated Scanners:Multi-function terminals combining payment acceptance with receipt printing, barcode scanning, and customer-facing displays. Hospital cafeterias and campus bookstores favor these for consolidated vendor relationships.
- Portable Scanners:Compact Bluetooth-connected readers paired with tablets or smartphones for temporary pop-up locations. Festival vendors and construction site offices drive seasonal procurement spikes.
By volume, mobile scanners lead. By growth pace, integrated scanners are climbing the fastest as merchants seek consolidated hardware footprints.
Technology:
Cost tier stratification separates legacy infrastructure from next-generation authentication. Magnetic stripe occupies the economy position while biometric modules command certification premiums.
- Magnetic Stripe:Legacy card-reading technology using magnetically encoded data on plastic stripe substrates. Declining to maintenance-only replacement as PCI-DSS deadlines force chip migration at United States fuel pumps and ATMs.
- EMV Chip:Contact smart card readers conforming to ISO/IEC 7816 standards with cryptographic transaction authentication. Banking ATM fleets across Germany, France, and Italy are completing dual-interface upgrades under EBA strong customer authentication mandates.
- Contactless:NFC-enabled readers operating at 13.56 MHz for tap-to-pay transactions without physical card insertion. Transit authorities in London, Singapore, and New York are deploying open-loop acceptance at fare gates.
- Biometric:Fingerprint or iris-sensing modules integrated with payment authentication for high-assurance identity verification. Government ID enrollment centers in India and Saudi Arabia are procuring these for Aadhaar and national identity programs.
By installed base, EMV chip dominates. By expansion trajectory, contactless is gaining share fastest as tap-to-pay limits rise.
End User:
Application-specific requirements drive divergent procurement specifications. Retail prioritizes transaction speed while transportation demands environmental durability.
- Retail:Point-of-sale terminals for merchant checkout environments including grocery, apparel, and specialty stores. United States small businesses are shifting toward software-embedded payment acceptance through vertical SaaS platforms.
- Banking:ATM and branch counter readers for cash withdrawal, deposit, and account services. European banks are consolidating vendors around dual-interface readers that satisfy EBA authentication requirements.
- Hospitality:Property management system-integrated terminals for hotels, restaurants, and event venues. Cruise lines and resort chains are deploying portable scanners for poolside and room-service transactions.
- Transportation:Fare gates and onboard readers for mass transit, toll collection, and parking systems. Contactless open-loop acceptance is displacing closed-loop smart cards at metro systems in Seoul, Tokyo, and São Paulo.
By unit shipments, retail leads. By procurement value per unit, banking is expanding most quickly.
Deployment:
Customer type separates enterprise IT departments from merchant owner-operators with limited technical staff. Cloud and hybrid models reduce on-site expertise requirements.
- On-Premises:Locally managed terminals with dedicated server infrastructure and internal IT maintenance. Large United States retail chains with legacy ERP investments continue favoring this model for control over transaction routing.
- Cloud-Based:Terminals connecting to remote payment processors with browser-based management dashboards. Micro-merchants in India and Brazil are adopting these for zero upfront infrastructure costs.
- Hybrid:Split architectures with local transaction processing and cloud-based reporting or software updates. Mid-market franchises in the United Kingdom and Australia prefer this for business continuity during connectivity outages.
- Embedded:Readers integrated directly into kiosks, vending machines, or self-service terminals without standalone terminal housing. Unattended retail and electric vehicle charging networks are driving specialized procurement.
By merchant count, cloud-based leads. By transaction value processed, hybrid is climbing the fastest as mid-market chains upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCI Security Standards Council certification requirements anchor the United States as the dominant geography for chip card scanner deployment, with EMV compliance mandates forcing merchant terminal refreshes across retail banking and fuel pump networks.
United States
Small business merchants and quick-service restaurant chains drive scanner procurement as EMV migration deadlines compress replacement cycles. PCI-DSS mandates require tamper-resistant terminals for all card-present transactions. Atlanta and Dallas host major terminal assembly operations serving domestic distribution networks.
Germany
Banking ATM fleet upgrades dominate demand as institutions comply with EBA strong customer authentication guidelines. REACH restrictions on circuit board materials reshape manufacturing compliance for European-bound units. Frankfurt and Munich concentrate dual-interface reader development for cross-border banking networks.
China
Domestic payment infrastructure expansion and transit authority modernization fuel contactless reader deployment. MIIT standards govern secure element certification for terminal manufacturers. Shenzhen and Shanghai anchor semiconductor packaging and terminal assembly clusters serving Asia-Pacific markets.
India
RBI pushes for card acceptance penetration at tier-2 and tier-3 merchants, creating demand for cost-optimized contactless readers. BIS certification requirements structure hardware import and local assembly protocols. Bengaluru and Hyderabad host R&D centers developing biometric-integrated modules for Aadhaar enrollment applications.
United Kingdom
Mid-market franchise chains favor hybrid deployment models combining local transaction processing with cloud-based management. FCA consumer protection rules influence terminal security specifications for merchant acquirers. London concentrates fintech partnerships embedding payment acceptance into vertical SaaS platforms.
Chip Card Scanners Market Competitive Landscape
Diversified security conglomerates and specialized semiconductor suppliers split the market across hardware tiers. Consolidation concentrates around vendors with integrated secure element-to-terminal capabilities. Three archetypes dominate: aerospace-credential specialists, biometric-integrated platform developers, and chip-level authentication providers. Capacity expansion and strategic technology licensing represent the primary competitive vectors as vendors secure EMVCo and PCI certification queues.
Among European security conglomerates, Thales and IDEMIA exemplify the aerospace-credential specialist archetype, leveraging government ID program experience for high-assurance applications. NXP Semiconductors anchors the semiconductor layer as a Netherlands-based secure element supplier. These three occupy positions spanning the value chain from chip authentication through integrated terminal delivery.
| Leading Market Players |
|---|
| Thales |
| IDEMIA |
| Giesecke & Devrient |
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| HID Global |
| CPI Card Group |
| Ingenico Group |
| Others |
Pricing and Supply Chain Analysis
Secure element foundry capacity concentrates in Taiwan and South Korea, anchoring semiconductor costs that cascade through terminal manufacturing and compress margin pools at the module assembly tier. This upstream concentration forces scanner vendors toward certification-intensive product tiers where pricing power rests on EMVCo and PCI Security Standards Council credentials rather than commodity hardware economics.
Pricing Analysis
North American terminal pricing commands a 15-20% premium over Asia-Pacific equivalents due to PCI-DSS certification costs and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates biometric-integrated modules from dual-interface units and legacy EMV chip readers. Cost compression in the economy tier is intensifying because SoftPOS alternatives collapse dedicated hardware demand among micro-merchants. Tier-1 retailers with legacy ERP investments exhibit the lowest price sensitivity, while Indian tier-2 merchants drive aggressive procurement negotiations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard practice among terminal OEMs sourcing from Taiwanese secure element suppliers and Chinese antenna coil manufacturers. Semiconductor packaging draws from Taiwan, South Korea, and China, while electromagnetic shielding components rest on Japanese and German specialty metal suppliers. Single-source vulnerability in certified smart card microcontroller foundries creates allocation risk during demand spikes. Distribution runs through merchant acquirer channels in North America, direct OEM relationships in Europe, and government procurement frameworks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chip card scanners are transitioning from standalone hardware to software-defined payment platforms, with merchant IT departments now valuing cloud-configurable terminal fleets over fixed-function devices. This interoperability shift rewards vendors who decouple acceptance logic from proprietary hardware architectures.
For Market Incumbents: Build certification queue moats by securing priority laboratory slots at EMVCo and PCI Security Standards Council testing facilities. Defensive moves should concentrate on backward integration into secure element distribution agreements with NXP Semiconductors and Infineon Technologies, plus capacity addition in India to serve RBI-mandated tier-2 merchant expansion. SoftPOS erosion threatens the micro-merchant hardware tier.
For New Entrants and Emerging Players: Pursue biometric module white space in European government ID programs where EU AI Act pre-certification creates barrier-to-entry advantages. India's cost-optimized contactless reader segment offers the most penetrable geography given RBI infrastructure push and limited incumbent localization. A vertical SaaS partnership route through restaurant management and salon booking platforms bypasses direct merchant acquisition costs.
For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-to-terminal integrated vendors with captive secure element supply and PCI certification infrastructure. Long-term viability over the next decade hinges on software-defined terminal architecture transitions and biometric authentication margin expansion. Watch SoftPOS merchant acceptance rates as the inflection signal for hardware volume compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Backward Integration | Captive supply from NXP Semiconductors insulates margin against foundry allocation shocks. |
| Cloud-First Terminal Architecture | Software-defined platforms enable merchant IT departments to manage fleets remotely. |
| EU AI Act Pre-Certification | Fundamental rights impact assessments unlock premium positioning in government ID procurement. |
| India Localization Partnership | BIS-compliant assembly in Bengaluru addresses RBI tier-2 merchant infrastructure mandates. |
| Biometric Module R&D Expansion | Fingerprint-integrated readers capture premium pricing in Aadhaar and Saudi national ID programs. |
Research Methodology
Cross-validation between primary fieldwork with payment terminal OEMs and secondary validation through EMVCo certification databases anchors the qualitative findings. Terminal engineering directors, merchant acquirer procurement leads, PCI Security Standards Council certification managers, and semiconductor distribution specialists contributed structured interviews. Secondary sources include SEC filings from listed terminal vendors, customs trade data for secure element imports, PCI-DSS certified product registries, and banking ATM fleet upgrade announcements. Bottom-up unit shipment modeling triangulates against top-down payment transaction volume projections.
Calibration against historical EMV migration patterns and contactless payment adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions include product type, authentication technology, end-user vertical, and deployment architecture, with regional regulatory cluster as an additional modeling layer. CAGRs derive from terminal replacement cycle compression and transit authority modernization trajectories. Forecast inputs incorporate PCI-DSS deadline enforcement intensity and SoftPOS merchant penetration rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting merchant capital expenditure cycles or semiconductor foundry utilization rates would shift the trajectory. Forecasts reflect documented assumptions about EMV compliance enforcement and certification laboratory capacity. Regulatory acceleration in biometric data governance or supply disruption in certified secure element foundries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Supply Chain Risk Management Software Market
Others
North America Halal Food and Beverage Market
Others
Aerospace Software Testing Market
Others
Level Measuring Instrument Market
Others
Mobile Computer Cart Market
Others
Industrial Tablet PC Market
Others
UK 3D Printing Construction Market
Others
Rotary Dial Machine Market
Others
Latin America Video Conferencing Hardware Market
Others
High Voltage Measuring Equipment Market
Others
Africa 3D Printing Construction Market
Others
Global Animal Feed Protein Ingredients Market
Others
Egg Market
Others
Medical Simulation Market
Others
Crystal Growth Equipment Market
Others
Smart-Connected Power Plug Socket Market