
 Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market | 2026-2036
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market Outlook
Clinical-grade iPSC standards are unwinding research-only supply constraints across the Asia-Pacific. FUJIFILM Cellular Dynamics anchors Japanese production with vertically integrated differentiation platforms. Lonza dominates contract manufacturing for international pharma clients seeking GMP-compliant cell banks. Thermo Fisher Scientific extends its reagent ecosystem into CRISPR-edited iPSC workflows for Chinese biotechs.
Induced pluripotent stem cells are somatic cells reprogrammed to pluripotency through transcription factor introduction, typically yielding lines expressing OCT4, SOX2, KLF4, and c-MYC markers with teratoma formation potential as the functional pluripotency assay. Regenerative medicine applications command the largest application share as Japan's PMDA accelerates conditional approvals for iPSC-derived therapies. Drug development services represent the fastest-expanding segment as pharmaceutical companies outsource toxicity screening to specialized CROs. Cryopreserved delivery modes capture premium positioning due to extended viability guarantees for international shipment.
PMDA's regenerative medicine framework and Australia's TGA cell therapy guidelines shape product standards across the region, while China's NMPA clinical trial regulations determine market access timelines for domestic developers. CDSCO's evolving biologics pathway in India introduces additional compliance layers for imported cell lines. Stakeholders must monitor harmonization between national cell banking standards and evolving GMP requirements for commercial-scale iPSC manufacturing.
Market Dynamics
CRISPR-edited iPSC lines are compressing development timelines for cell therapies across the Asia-Pacific, forcing contract manufacturers to retool GMP facilities for gene-edited cell banks rather than conventional reprogrammed lines.
Growth Catalysts
- PMDA's conditional approval framework:Japan's regenerative medicine regulations accelerate commercial pathways for iPSC-derived therapies, reducing time-to-market for developers with qualified cell banks.
- Shanghai-Suzhou biotech corridor:Concentrated venture funding and CRO infrastructure in eastern China attracts CRISPR-edited iPSC projects from domestic and multinational sponsors.
- CDSCO's biologics pathway evolution:India's regulatory clarity on imported cell line trials opens access for contract research organizations serving international pharmaceutical clients.
Market Restraints
- Fetal bovine serum price volatility:Culturing media input costs fluctuate with livestock commodity markets, squeezing margins for high-volume iPSC expansion services.
- Japanese GMP facility concentration:Overreliance on Kobe and Osaka manufacturing clusters creates single-point vulnerability for regional cell bank supply.
- Teratoma assay duration:Functional pluripotency verification requires 8-12 week animal studies, blocking rapid batch release for time-sensitive clinical applications.
Strategic Opportunities
- Australian TGA cell therapy guidelines:Streamlined approval pathways for autologous iPSC products attract sponsors seeking faster first-in-human trial initiation than US or EU routes.
- South Korea's MFDS fast-track designation:Rare disease iPSC therapies qualify for priority review, creating regulatory arbitrage for developers with orphan indications.
- Cryopreserved shipment logistics:Specialized cold-chain distributors are building Asia-Pacific hub networks for viable cell line transport, replacing researcher hand-carry methods.
Industry Challenges
- GMP-grade reprogramming specialist scarcity:Qualified cell biologists capable of clinical-grade iPSC line generation command premium compensation, constraining facility expansion timelines.
- Master cell bank characterization backlog:Extended queue times at reference laboratories for karyotype and sterility testing delay manufacturing campaign starts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market |
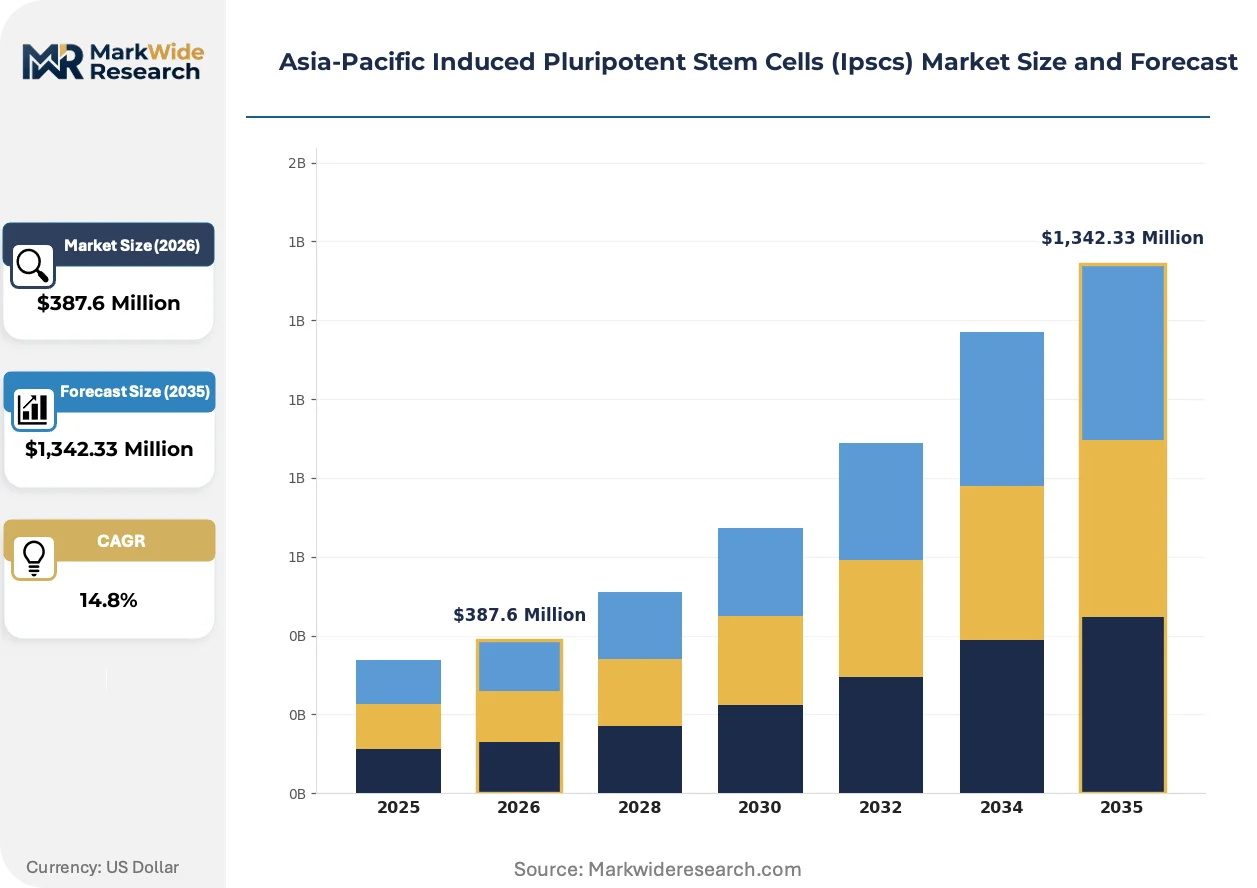
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,342.33 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Consumables, Equipment, Services Application: Regenerative Medicine, Drug Development, Toxicology Testing, Disease Modeling End User: Pharmaceutical Companies, Research Institutes, Biotechnology Firms, Academic Organizations Delivery Mode: Liquid, Lyophilized, Cryopreserved, Others |
| Companies Covered | FUJIFILM Cellular Dynamics, Inc., Thermo Fisher Scientific Inc., Lonza, REPROCELL Inc., Axol Bioscience Ltd., Evotec SE, Takara Bio Inc., Merck KGaA, Hopstem Biotechnology LLC., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market Strategic Shifts
Synthetic mRNA reprogramming protocols are replacing viral vector methods across the Asia-Pacific, altering supplier relationships and facility contamination control requirements.
Chemically defined feeder-free culture systems are displacing Matrigel-dependent expansion workflows in Japanese and Australian GMP facilities. CDMOs in Osaka and Melbourne report 40% faster batch turnaround after eliminating lot-to-lot variability from animal-derived substrates. The shift is compressing qualification timelines for international pharma clients seeking harmonized cell banks across multiple trial sites.
China's NMPA revised its cell therapy clinical trial regulations to require real-time adverse event reporting for gene-edited iPSC products. The mandate forces sponsors to build integrated pharmacovigilance systems rather than relying on periodic safety updates. Domestic biotechs in Suzhou are responding by embedding clinical data managers within manufacturing teams.
Pharmaceutical procurement departments are unbundling iPSC-derived toxicity screening from full-service CRO contracts. Large molecule developers in Tokyo and Seoul now contract directly with specialized iPSC laboratories for hepatocyte and cardiomyocyte panels, bypassing traditional toxicology service providers. The disintermediation is most pronounced among mid-cap sponsors with established internal DMPK capabilities.
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market Segmentation
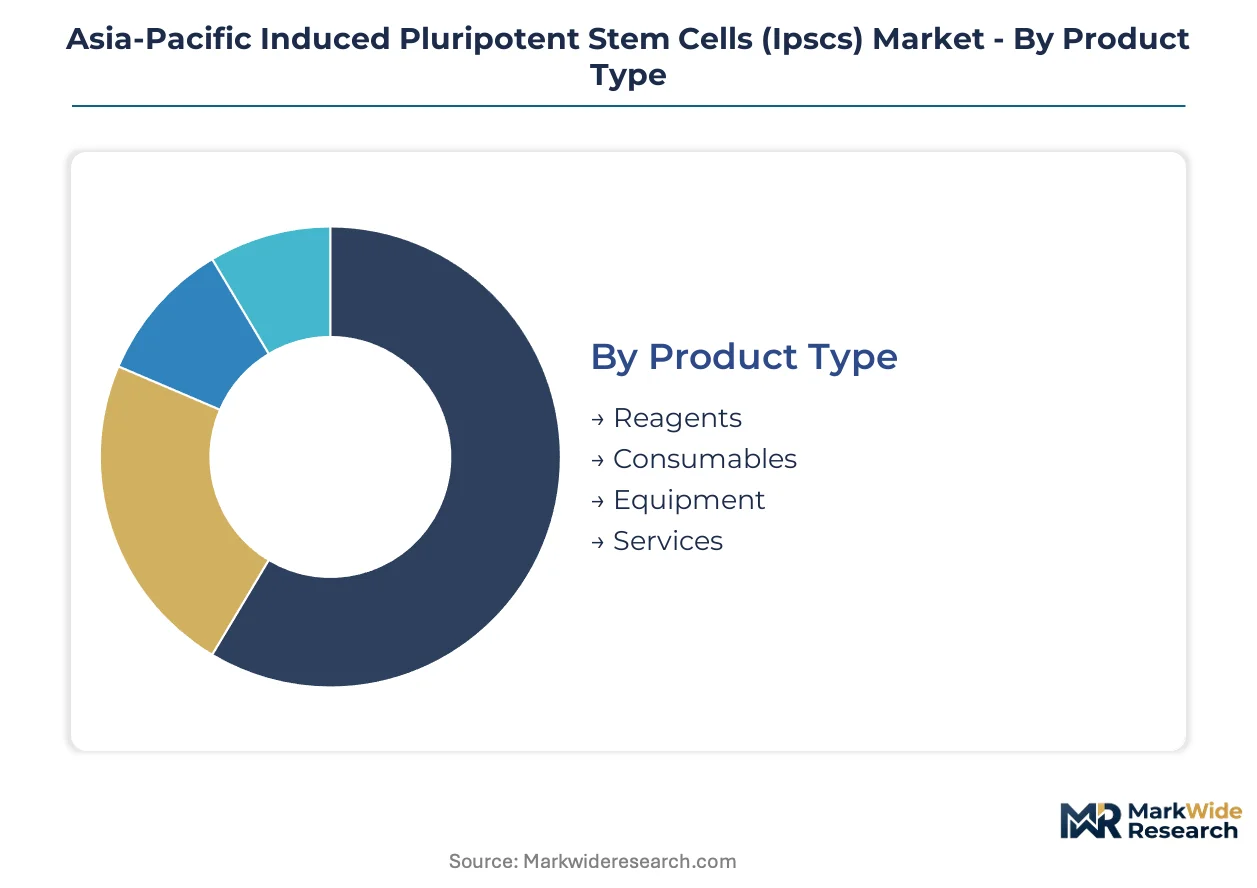
iPSC market segmentation reveals divergent margin profiles across product types and applications. Substitution pressures from synthetic biology tools and primary cell alternatives reshape competitive dynamics within each category.
Product Type:
Services face the strongest substitution threat as pharmaceutical sponsors bring reprogramming capabilities in-house, while reagent suppliers defend position through proprietary chemically defined formulations.
- Reagents:Chemically defined media formulations and reprogramming factor cocktails eliminate lot-to-lot variability from animal-derived components. Demand concentrates in Shanghai-Suzhou corridor biotechs seeking NMPA-compliant documentation for gene-edited iPSC workflows. PMDA's emphasis on traceable raw materials drives premium positioning for Japanese-sourced reagent bundles.
- Services:Contract reprogramming and differentiation services span GMP cell bank generation to CRISPR editing. Pharmaceutical companies in Tokyo and Seoul outsource master cell bank creation to CDMOs with PMDA or MFDS audit histories, compressing timelines for first-in-human filings.
- Consumables:Feeder-free culture vessels and matrix coatings from Osaka and Melbourne suppliers support chemically defined workflows.
- Equipment:Automated cell culture systems and high-content imaging platforms enable scale-out manufacturing for clinical-grade batches.
Reagents retain volume leadership; services hold the steepest expansion curve.
Application:
Cost tier differentiation separates validated therapeutic applications from exploratory research uses, with regulatory burden determining pricing power.
- Regenerative Medicine:Clinical-grade iPSC-derived therapies for macular degeneration and Parkinson's disease command premium pricing through PMDA conditional approvals. Japanese developers in Kobe cluster leverage established GMP infrastructure for commercial-scale manufacturing campaigns.
- Drug Development:Hepatocyte and cardiomyocyte panels for ADMET screening displace animal models in Tokyo and Seoul pharmaceutical R&D. Toxicology screening contracts fragment as sponsors contract directly with specialized iPSC laboratories rather than full-service CROs.
- Toxicology Testing:Organ-specific cytotoxicity assays using iPSC-derived cells support regulatory submission packages.
- Disease Modeling:Patient-specific iPSC lines recapitulate rare disease phenotypes for mechanistic studies.
Regenerative medicine captures the highest value per batch; drug development expands most quickly.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding integrated quality systems that academic organizations cannot replicate.
- Pharmaceutical Companies:Multinational sponsors in Tokyo and Seoul require harmonized cell banks across trial sites, driving demand for cryopreserved shipment logistics with extended viability guarantees. Unbundled procurement of iPSC-derived toxicity panels bypasses traditional CRO relationships.
- Research Institutes:Government-funded facilities in Tsukuba and Melbourne advance foundational reprogramming protocols with less stringent GMP requirements than commercial developers.
- Biotechnology Firms:Venture-backed Suzhou developers embed clinical data managers within manufacturing teams to satisfy NMPA real-time adverse event mandates.
- Academic Organizations:University laboratories in India and Southeast Asia rely on imported cell lines with CDSCO-compliant import documentation.
Pharmaceutical companies dominate contract value; biotechnology firms are gaining share fastest.
Delivery Mode:
Supply concentration in cryopreserved logistics creates margin premiums for specialized cold-chain distributors building Asia-Pacific hub networks.
- Cryopreserved:Vial-based frozen storage with controlled-rate freezing protocols extends viability guarantees to 24 months for international shipment. Osaka and Melbourne GMP facilities report 40% faster batch turnaround after eliminating animal-derived substrates from expansion workflows.
- Liquid:Fresh cell suspensions suit same-day regional delivery for time-sensitive applications.
- Lyophilized:Freeze-dried formulations reduce cold-chain burden for reagent components.
- Others:Emerging formats including microencapsulated cell beads for targeted delivery applications.
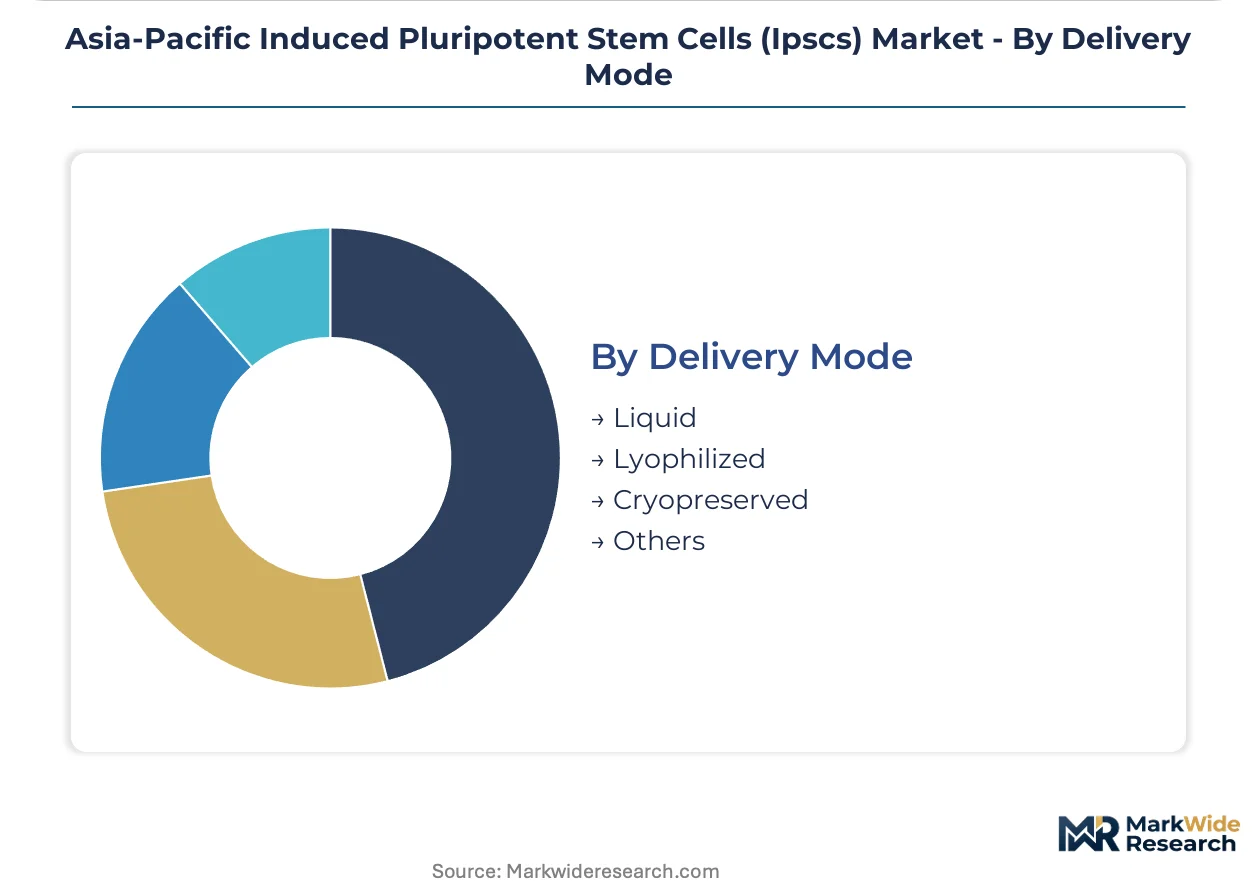
Cryopreserved retains volume leadership; lyophilized holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for clinical-grade iPSC lines exceeds export volumes across most of Asia-Pacific, with Japan and Australia as net suppliers and China, India, and South Korea as demand centers. Trade flows concentrate through specialized cold-chain logistics networks linking Osaka, Melbourne, and Shanghai.
Japan
PMDA's conditional approval framework for iPSC-derived therapies drives demand for GMP-compliant cell banks. Kobe and Osaka manufacturing clusters host vertically integrated differentiation platforms serving domestic and regional sponsors. FUJIFILM Cellular Dynamics anchors production capacity with feeder-free culture systems.
China
NMPA's real-time adverse event reporting mandate for gene-edited iPSC products accelerates pharmacovigilance infrastructure investment. The Shanghai-Suzhou biotech corridor concentrates venture funding and CRISPR-edited iPSC project pipelines. Domestic biotechs embed clinical data managers within manufacturing teams to satisfy regulatory timelines.
Australia
TGA's streamlined cell therapy guidelines attract sponsors seeking faster first-in-human trial initiation than US or EU routes. Melbourne GMP facilities report accelerated batch turnaround after eliminating animal-derived substrates. Cryopreserved shipment logistics hubs serve as regional distribution nodes for viable cell line transport.
South Korea
MFDS fast-track designation for rare disease iPSC therapies creates regulatory arbitrage for orphan indication developers. Seoul-based pharmaceutical sponsors contract directly with specialized iPSC laboratories for hepatocyte and cardiomyocyte panels. Toxicology screening contracts fragment as sponsors bypass traditional CRO relationships.
India
CDSCO's evolving biologics pathway introduces compliance layers for imported cell line trials. Academic organizations in Tsukuba-equivalent research zones rely on CDSCO-compliant import documentation for cell line access. Contract research organizations serving international pharmaceutical clients expand facility footprints to capture regulatory clarity benefits.
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market Competitive Environment
Concentration sits with vertically integrated Japanese manufacturers and Swiss-German contract manufacturing specialists. The vendor base stratifies across three tiers: GMP-certified cell bank generators, reagent and media formulators, and specialized differentiation service providers. Strategic moves center on backward integration into chemically defined raw material supply and capacity expansion in PMDA-audited facilities.
Within the integrated manufacturing tier, FUJIFILM Cellular Dynamics and Lonza exemplify divergent geographic anchoring strategies. Thermo Fisher Scientific occupies a position bridging reagent supply and CRISPR-edited workflow enablement for Chinese biotechs. REPROCELL Inc. and Takara Bio Inc. represent Japanese specialists with PMDA-aligned quality systems. Merck KGaA and Evotec SE anchor European contract research presence with Asia-Pacific facility networks.
| Leading Market Players |
|---|
| FUJIFILM Cellular Dynamics, Inc. |
| Thermo Fisher Scientific Inc. |
| Lonza |
| REPROCELL Inc. |
| Axol Bioscience Ltd. |
| Evotec SE |
| Takara Bio Inc. |
| Merck KGaA |
| Hopstem Biotechnology LLC. |
| Others |
Value Chain & Pricing Dynamics
Eight-to-twelve-week teratoma assay durations for functional pluripotency verification create inventory pressure that concentrates pricing power with GMP-certified cell bank generators in Japan and Australia, while forcing buyers toward cryopreserved shipment contracts with extended viability guarantees.
Pricing Analysis
Pharmaceutical companies anchor pricing structures around three-tier certification-grade differentiation across PMDA-audited, MFDS-aligned, and research-grade cell banks. Price differentiation rests on GMP compliance level and master cell bank characterization depth, with PMDA-conditional-approval-tier lines commanding premiums over TGA-compliant alternatives. Pricing pressure intensifies in contract reprogramming services as sponsors build in-house capabilities. Academic organizations in India exhibit highest price sensitivity, while Tokyo-based multinationals prioritize batch consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of fetal bovine serum and chemically defined media dominates procurement behavior given livestock commodity volatility and lot-to-lot qualification requirements. Supply concentrates in Japan, Australia, and Switzerland-Germany for clinical-grade cell banks, while China and India serve as demand centers with import dependence. Raw material dependencies include recombinant growth factors, synthetic mRNA reprogramming kits, and feeder-free matrix coatings. Single-source vulnerability sits with Kobe-Osaka manufacturing clusters for regional GMP capacity. Distribution runs through specialized cold-chain logistics hubs linking Melbourne, Osaka, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in pharmacovigilance integration and real-time adverse event reporting systems are expanding faster than hardware sales, as NMPA mandates force sponsors to embed clinical data managers within manufacturing teams.
For Market Incumbents: Consolidate differentiation platform capabilities through captive supply of chemically defined media formulations, eliminating animal-derived substrate variability that delays batch release. Add PMDA-audited cleanroom capacity in secondary Japanese locations to reduce Kobe-Osaka concentration risk. Lock in long-term reagent supply agreements with Shanghai-Suzhou biotechs before sponsors verticalize reprogramming workflows. For New Entrants and Emerging Players: Anchor in CDSCO-compliant import documentation services for Indian academic organizations and CROs serving international pharmaceutical clients. Target Australia's TGA-streamlined autologous iPSC trial pathways as the most penetrable regulatory arbitrage for first-in-human initiation. Lead with cryopreserved shipment logistics partnerships rather than manufacturing capacity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because conditional approval frameworks in Japan and South Korea create durable moats for GMP-certified incumbents. Prioritize acquisition targets with PMDA or MFDS audit histories and vertically integrated differentiation platforms. Watch for NMPA harmonization with international GMP standards as the signal that Chinese domestic players are becoming viable regional competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PMDA conditional approval pathways compress time-to-market for iPSC-derived therapies against standard biologics routes. |
| Regulatory Approval Pathway | MFDS fast-track designation for rare disease indications creates priority review arbitrage for orphan therapy developers. |
| Manufacturing Scale-Up | Feeder-free culture system adoption in Osaka and Melbourne facilities yields 40% faster batch turnaround. |
| Backward Integration | Chemically defined media formulation captivity eliminates lot-to-lot variability from fetal bovine serum commodity exposure. |
| Strategic Partnership | Cryopreserved shipment logistics hubs in Shanghai and Melbourne replace researcher hand-carry with viable cold-chain networks. |
Study Parameters
Desk research of PMDA regulatory filings, NMPA clinical trial databases, and CDSCO biologics pathway documentation preceded structured interviews with cell therapy manufacturing executives, regulatory affairs leads at Japanese CDMOs, pharmaceutical procurement directors in Tokyo and Seoul, and GMP facility quality managers across the Asia-Pacific. Primary fieldwork combined with secondary validation through SEC filings of listed reagent suppliers and trade data from regional customs authorities. Bottom-up cell bank volume estimates triangulated against top-down regenerative medicine market sizing.
Variance decomposition across product type, application, end user, and delivery mode segmentation dimensions drove analytical framework construction over the projection horizon. CAGRs derived from regression-based modeling of historical approval timelines, facility capacity expansion announcements, and sponsor pipeline progression rates. Forecast inputs incorporated PMDA conditional approval velocity, NMPA real-time reporting compliance costs, and MFDS fast-track queue depth.
Decision-makers should treat outputs as directional under assumptions of sustained PMDA framework stability and continued Shanghai-Suzhou venture funding concentration; material deviation would warrant model refresh. Forecasts reflect base-case regulatory harmonization trajectories and GMP facility utilization assumptions. Revision becomes warranted when CDSCO import pathway clarity crosses thresholds that shift CRO facility investment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aircraft Lighting Market
Others
Programmatic Display Market
Others
Canada Laser Hair Removal Market
Others
Brown Ht Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Military Image Intensifier Market
Others
Global Hydraulics Market
Others
Singapore Retail Market
Others
Paraffin Physical Therapy Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Industrial Air Pollution Control Solutions Market
Others
Edible Insects for Animal Feed Market
Others
Global Virtual Keyboard Market
Others
North America Industrial Wearable Devices Market
Others
Smart-Connected Power Plug Socket Market
Others
Global Molded Plastics Market