
 Deep Sea Mining Market | 2026-2036
Deep Sea Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Sea Mining Market Insights
Exploration licensing revenue is narrowing as contractors shift capital toward production equipment and offtake partnerships. The Metals Company leverages its nodule processing partnerships with onshore refiners to secure downstream access. Global Sea Mineral Resources anchors its position through exclusive exploration contracts granted by the International Seabed Authority. China Ocean Mineral Resources Research and Development Association dominates the Asia-Pacific contractor landscape with the largest allocated seabed area under contract.
Deep sea mining refers to the extraction of mineral deposits from the ocean floor at depths exceeding 200 meters, where polymetallic nodules containing nickel, cobalt, copper, and manganese accrete over millions of years on abyssal plains. These nodules typically range from 1 to 12 centimeters in diameter and serve as critical feedstock for battery cathodes and stainless steel alloys. Manganese nodules attract the majority of exploration investment due to their concentrated cobalt and nickel content, while robotic mining systems represent the fastest-evolving technology segment as operators seek to minimize sediment plume disturbance. Hydraulic suction methods retain mature deployment status among early contractors, though drum cutter configurations are gaining traction for crust extraction on seamount slopes.
The International Seabed Authority governs mineral activities in international waters through its Mining Code, while national regulators such as the EPA and NOAA oversee environmental compliance for US-affiliated operations. The ISA's pending exploitation regulations will determine royalty structures, environmental thresholds, and contractor liability frameworks that shape investment timelines. Stakeholders must monitor whether the ISA finalizes its regulatory framework before existing exploration contracts expire, as this timing will dictate which contractors transition to commercial production first.
Market Dynamics
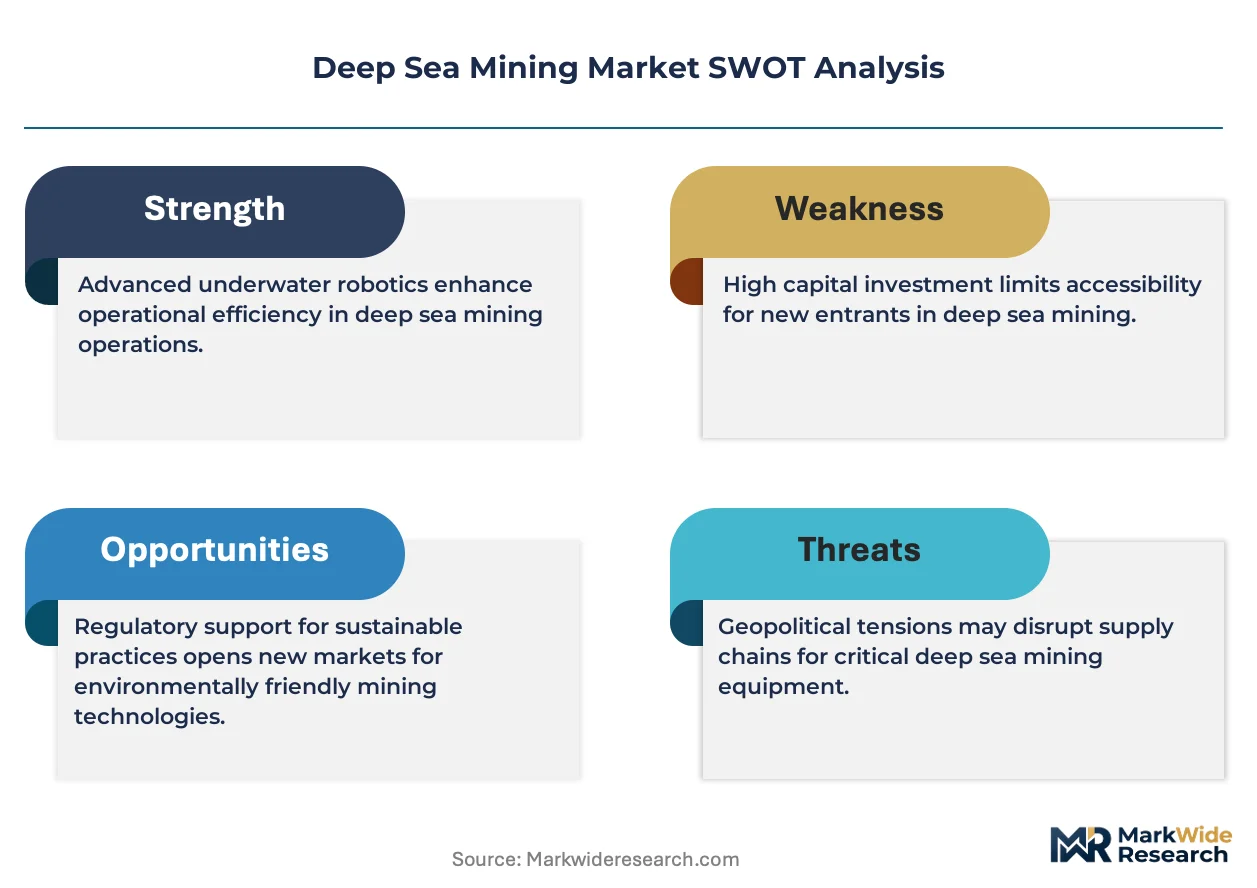
The International Seabed Authority's pending exploitation regulations are compressing investment timelines as contractors race to secure production equipment and offtake partnerships before exploration contracts expire.
Growth Catalysts
- Battery cathode demand:Electric vehicle manufacturers in East Asia are locking in polymetallic nodule supply chains to secure nickel and cobalt feedstock for high-energy-density cells.
- REACH compliance pressure:European battery producers face mandatory due diligence requirements for conflict minerals, redirecting sourcing interest toward ISA-governed seabed deposits.
- Hydraulic suction advancement:Refined pump configurations now extract nodules with 40% less sediment disturbance than first-generation prototypes.
Market Restraints
- Capital intensity barrier:Production vessel fabrication and robotic collector deployment require $500 million-plus committed capital before first ore lift.
- Single-source equipment risk:Specialized seabed crawler manufacturers concentrate in Norway and the United Kingdom, creating supply bottlenecks.
- Terrestrial substitution:Indonesian nickel laterite expansions and Congolese cobalt artisanal output compete directly for battery maker offtake.
Strategic Opportunities
- Indian Ocean expansion:The International Seabed Authority has allocated nine new exploration blocks in the Central Indian Ocean Basin to diversify beyond the Clarion-Clipperton Zone.
- Cobalt-free cathode compatibility:Lithium-iron-phosphate battery chemistries still require manganese, which nodules deliver at 2.5x terrestrial ore grades.
- EU Battery Regulation tailwind:Mandatory recycled content quotas and carbon footprint disclosure favor seabed-sourced metals with lower lifecycle emissions profiles.
Industry Challenges
- Deep-sea ecology expertise gap:Contractors lack sufficient benthic taxonomists and sediment plume modelers to complete environmental impact assessments.
- Collector-track standardization delay:Absence of unified interface specifications forces redundant engineering across robotic mining systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Sea Mining Market |
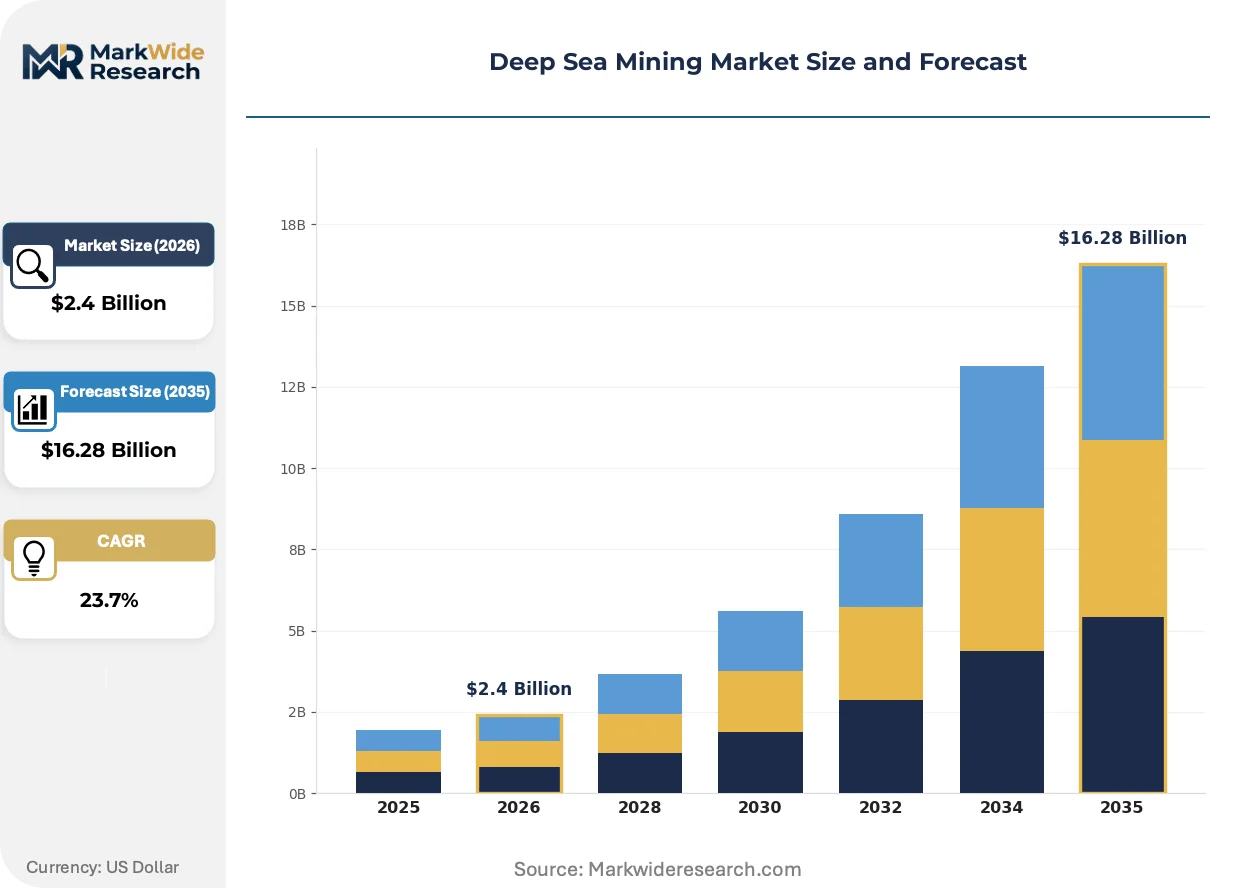
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Manganese Nodules, Polymetallic Sulfides, Cobalt-rich Crusts, Rare Earth Elements Mining Technology: Hydraulic Suction, Continuous Line Bucket, Cutter Suction, Drum Cutter, Robotic Mining Systems Application Sector: Electronics Manufacturing, Renewable Energy, Aerospace Components, Metal Processing Plants, Battery Production Operator Type: Specialized Mining Firms, Environmental Consultants, Marine Engineering Firms, Resource Exploration Agencies |
| Companies Covered | The Metals Company, Global Sea Mineral Resources, China Ocean Mineral Resources Research and Development Association, Nautilus Minerals, Ocean Minerals, Lockheed Martin Corporation, Kongsberg Gruppen, Transocean, Loke Marine Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Sea Mining Market Trends and Innovations
Seabed mining technology is converging with autonomous marine robotics and real-time environmental monitoring, shifting competitive advantage toward integrated system architects.
Autonomous seabed crawlers equipped with machine-vision nodule classification are rendering obsolete human-piloted remotely operated vehicles for deposit mapping. Contractors in the Clarion-Clipperton Zone are deploying these systems for pre-extraction site characterization. The shift compresses survey timelines from months to weeks while reducing surface vessel charter costs.
REACH's extended due diligence requirements for supply chain transparency are forcing battery producers to document mineral provenance through blockchain-tracked custody chains. German and French cathode manufacturers now require ISO 14001-certified extraction methods for all nickel and cobalt inputs. This regulatory pressure accelerates ISA contractor certification timelines and favors operators with established environmental baseline data.
Long-term offtake contracting is displacing spot market purchasing for critical battery metals as cathode producers seek supply security. Korean and Japanese battery makers are signing 10-year polymetallic nodule purchase agreements directly with ISA contractors. This procurement pattern shift concentrates negotiating power among integrated mining-to-metals consortia and marginalizes pure-play exploration firms.
Deep Sea Mining Market Segmentation
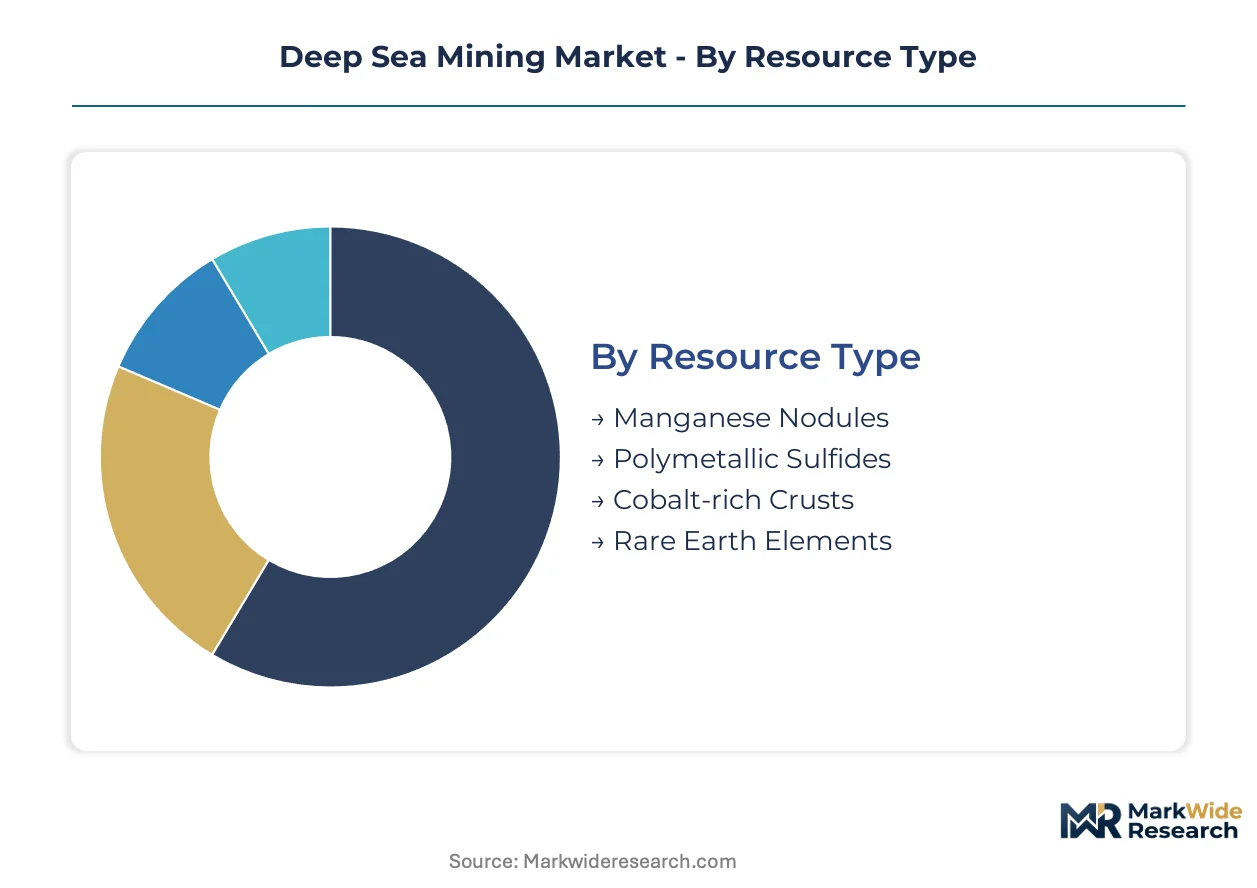
Segmentation in deep sea mining reveals where capital cycles fastest and where regulatory approval timelines create competitive moats. Resource type and mining technology segments turn over at radically different velocities, shaping contractor equipment procurement strategies.
Resource Type:
Manganese nodules cycle through exploration-to-production timelines fastest due to established metallurgical processing pathways, while cobalt-rich crusts face extended characterization periods on seamount slopes.
- Manganese Nodules:Spherical concretions containing nickel, cobalt, copper, and manganese distributed across abyssal plains at 4,000-6,000 meter depths. Korean battery cathode manufacturers concentrate procurement interest here due to standardized nodule composition reducing downstream refining complexity.
- Polymetallic Sulfides:Massive sulfide deposits formed at hydrothermal vent sites with elevated copper and zinc grades. Chinese state-backed contractors prioritize these deposits in the Indian Ocean Ridge where vent field mapping has accelerated.
- Cobalt-rich Crusts:Ferromanganese layers precipitated on seamount rock substrates containing high cobalt-to-land-ore ratios. Extraction requires precision cutting tools given hard substrate attachment.
- Rare Earth Elements:Deep ocean muds in Pacific Ocean zones with concentrated heavy rare earth distributions. Japanese exploration agencies have secured exclusive ISA blocks for these deposits.
Manganese nodules dominate installed base. Polymetallic sulfides are where expansion concentrates.
Mining Technology:
Equipment selection stratifies by sediment disturbance tolerance and seafloor topography, with hydraulic systems commanding premium pricing for low-impact extraction.
- Hydraulic Suction:Pump-based nodule lift systems using seawater jets to fluidize surface sediments. Norwegian equipment fabricators concentrate manufacturing capacity for these systems as contractors prioritize ISA environmental threshold compliance.
- Continuous Line Bucket:Mechanical bucket chains dragged across nodule fields for bulk collection. Deployed primarily in Chinese-contracted Clarion-Clipperton Zone blocks where sediment plume dispersion receives less regulatory scrutiny.
- Cutter Suction:Rotating cutter heads combined with suction pumps for consolidated sediment penetration. German marine engineering firms specialize in cutter torque specifications for varying substrate hardness.
- Drum Cutter:Rotating drum configurations with picks for cobalt crust extraction on sloped seamount terrain. Traction systems must maintain position on gradients exceeding 20 degrees.
- Robotic Mining Systems:Autonomous crawlers with machine vision for selective nodule harvesting and real-time grade assessment. Battery producers in Japan are driving fastest adoption for traceable, low-carbon feedstock certification.
Hydraulic suction commands the largest committed capital. Robotic mining systems are climbing the fastest.
Application Sector:
End-use demand clusters around cathode chemistry specifications, with high-nickel formulations pulling differentiated resource procurement.
- Electronics Manufacturing:High-purity manganese for ferrite components and capacitor-grade tantalum from processed nodules. Taiwanese semiconductor substrate producers represent concentrated demand.
- Renewable Energy:Permanent magnet rare earths for offshore wind turbine generators. European turbine OEMs are sourcing seabed-origin neodymium to satisfy EU Battery Regulation carbon footprint disclosure.
- Aerospace Components:Superalloy-grade cobalt and rhenium for jet engine turbine blades. US defense contractors prioritize ISA-governed sources for conflict mineral compliance.
- Metal Processing Plants:Bulk manganese for ferroalloy production and stainless steel feedstock. Chinese integrated steelmakers maintain offtake discussions with multiple ISA contractors.
- Battery Production:Nickel and cobalt for lithium-ion cathodes across NMC and NCA chemistries. Korean cell manufacturers are locking decade-long supply agreements directly with mining consortia.
Battery production anchors procurement volume. Renewable energy is gaining share fastest.
Operator Type:
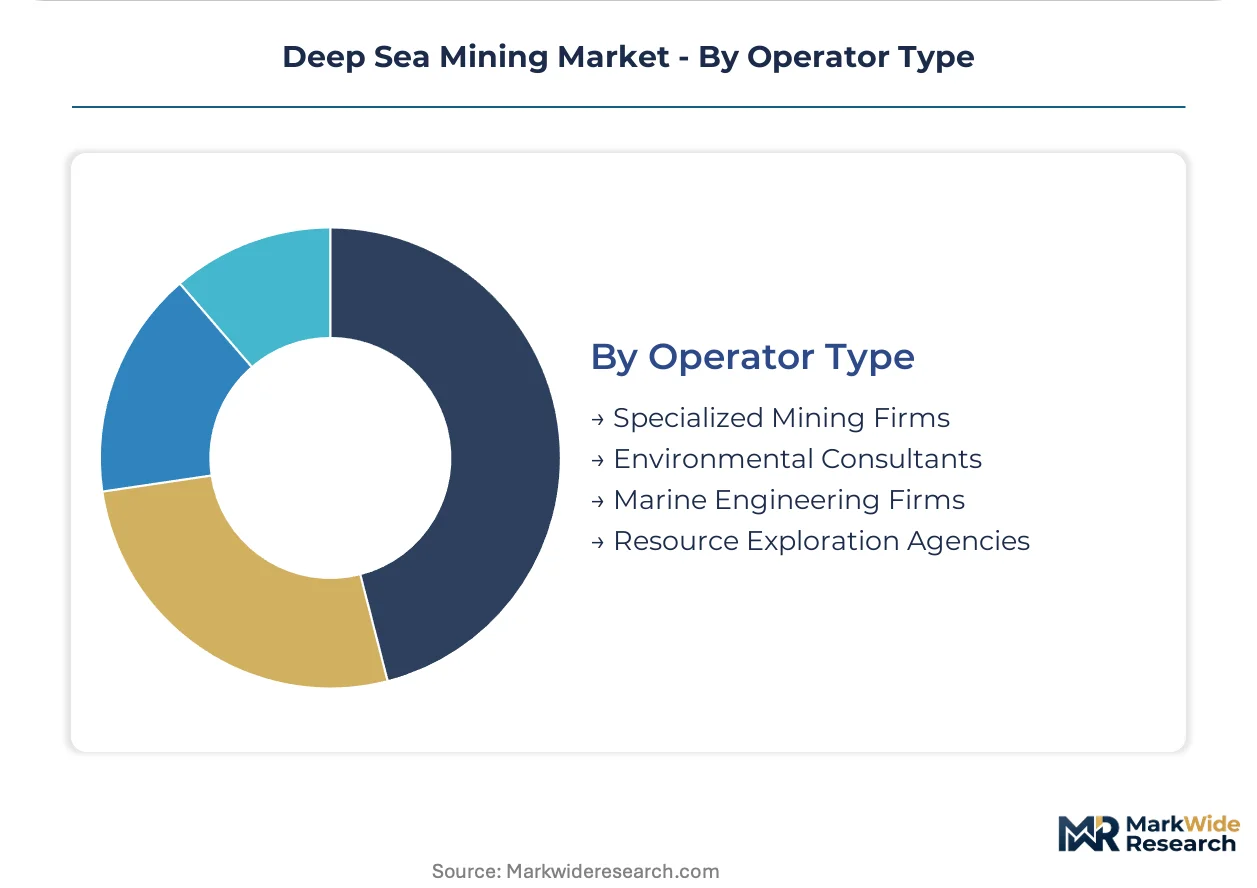
Contractor specialization determines regulatory navigation speed, with integrated marine engineering capabilities compressing environmental baseline completion timelines.
- Specialized Mining Firms:Pure-play seabed operators with ISA exploration contracts and processing partnerships. These entities carry full exploitation liability under pending ISA royalty frameworks.
- Environmental Consultants:Benthic ecology specialists conducting impact assessments and sediment plume modeling. Shortage of qualified taxonomists is extending study timelines.
- Marine Engineering Firms:System integrators combining crawler fabrication, riser design, and surface vessel specification. UK and Norwegian clusters dominate this capability.
- Resource Exploration Agencies:State-backed entities holding ISA-sponsored contracts for national strategic mineral security. China's COMRA holds the largest allocated seabed area.
Specialized mining firms dominate contracted production capacity. Marine engineering firms are where capability investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ISA exploration contracts cluster among contractors from five countries commanding the largest allocated seabed areas. National mineral security programs and battery supply chain mandates are accelerating permit timelines in East Asia and Northern Europe.
China
State-backed COMRA holds the largest single allocation of Clarion-Clipperton Zone blocks under ISA contract. The Ministry of Natural Resources coordinates seabed resource development with domestic battery cathode production targets. Qingdao hosts the country's primary deep-sea research vessel fleet and nodule processing pilot facilities.
Belgium
Global Sea Mineral Resources leverages its Brussels headquarters to anchor European regulatory engagement with the ISA. The federal government classifies seabed minerals under strategic raw materials legislation aligned with EU Battery Regulation compliance. Antwerp's port infrastructure positions the country for nodule import handling and intermediate processing.
United States
The Metals Company maintains its corporate base while pursuing ISA contractor partnerships for Pacific nodule access. NOAA and EPA oversight shapes environmental baseline requirements for US-affiliated operations. Seattle's marine robotics cluster supplies autonomous crawler components to multiple ISA contractors.
Norway
Kongsberg Gruppen anchors a national seabed equipment manufacturing ecosystem serving international contractors. The Norwegian Maritime Authority regulates vessel certification for harsh-environment mining operations. Bergen and Trondheim harbor specialized hydraulic pump and riser fabrication facilities.
South Korea
Korea Institute of Ocean Science and Technology holds exclusive ISA exploration rights in the Central Indian Ocean Basin. METI-aligned battery producers are negotiating decade-long nodule offtake agreements with polymetallic nodule contractors. Busan shipyards are fabricating production vessel hulls for contracted deployment.
Deep Sea Mining Market Competitive Landscape
Integrated mining consortia and pure-play exploration contractors split the market between production-ready capacity and regulatory optionality. The structure concentrates committed capital among five ISA-licensed operators with vessel construction underway. Strategic archetypes include state-backed resource agencies, marine engineering integrators, and battery-maker mining affiliates. Dominant competitive moves involve offtake partnership locking and production equipment pre-commitment ahead of ISA exploitation rule finalization.
Within the state-backed tier, China Ocean Mineral Resources Research and Development Association exemplifies national mineral security positioning through exclusive ISA block holdings. The Metals Company and Global Sea Mineral Resources occupy positions as Western-registered contractors pursuing integrated mining-to-metals pathways. These three entities represent divergent regulatory navigation strategies as the ISA exploitation framework crystallizes.
| Leading Market Players |
|---|
| The Metals Company |
| Global Sea Mineral Resources |
| China Ocean Mineral Resources Research and Development Association |
| Nautilus Minerals |
| Ocean Minerals |
| Lockheed Martin Corporation |
| Kongsberg Gruppen |
| Transocean |
| Loke Marine Minerals |
| Others |
Pricing and Supply Chain Analysis
Single-source equipment dependency on Norwegian and UK seabed crawler manufacturers compresses pricing power while amplifying tier spreads between integrated consortia and pure-play contractors, forcing procurement strategies toward long-term equipment pre-commitment or captive fabrication partnerships.
Pricing Analysis
The ISA's pending exploitation regulations dictate the pricing tier structure across contractor categories, separating integrated mining-to-metals consortia with secured offtake from pure-play exploration firms lacking downstream access. Price differentiation centers on environmental baseline certification status and guaranteed nodule delivery volumes, with Korean and Japanese battery makers paying premiums for ISO 14001-certified extraction methods. Cost compression in standard-grade feedstock runs through Indonesian nickel laterite competition and Congolese cobalt artisanal output. Spot-market purchasers show highest price sensitivity; integrated cathode manufacturers with decade-long supply agreements exhibit lowest.
Supply Chain Analysis
Seabed crawler fabrication and hydraulic pump manufacturing concentrate in Norway and the United Kingdom, with specialized riser components sourcing from German marine engineering clusters. Raw material dependencies span high-grade steel alloys, subsea electronics housings, and synthetic rope tensile systems. Single-source vulnerability in robotic collector track systems forces redundant engineering investments across contractors. Distribution runs through ISA-licensed operator networks directly to East Asian battery cathode producers, bypassing traditional mineral commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental monitoring and benthic impact assessment services attach faster than extraction hardware as contractors face mandatory sediment plume modeling and real-time ecological compliance requirements.
For Market Incumbents: Entrench position through backward integration into seabed crawler manufacturing and exclusive partnerships with Norwegian equipment fabricators, neutralizing single-source supply risk. Prioritize captive environmental consultancy capabilities to compress ISA environmental baseline completion timelines ahead of exploration contract expirations. For New Entrants and Emerging Players: Mid-tier marine engineering firms with autonomous robotics expertise represent the most penetrable entry point, particularly those serving adjacent offshore oil and gas sectors. Target white-space in Indian Ocean Basin exploration support services where ISA block allocations outpace contractor technical capacity. Lead with machine-vision nodule classification technology as differentiated capability anchor. For Investors and Strategic Acquirers: The market sits at a pre-regulatory-finalization phase that favors integrated mining-to-metals consortia with secured offtake and production equipment pre-commitment. Long-term viability centers on operators with demonstrated environmental baseline data and direct cathode manufacturer partnerships. Watch ISA exploitation regulation publication timing as primary inflection signal for first-mover production transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Production Equipment Pre-Commitment | Locks fabrication slots at Norwegian and UK marine engineering facilities before ISA rule finalization. |
| Long-Term Offtake Partnership | Korean and Japanese battery makers secure nodule supply chains bypassing terrestrial substitution competition. |
| Environmental Baseline Completion | ISA contractors with certified impact assessments gain first-mover advantage in exploitation licensing queue. |
| Backward Integration into Processing | Onshore refinery partnerships with The Metals Company model secure downstream metal access. |
| Autonomous Robotics Capability Acquisition | Machine-vision nodule classification compresses survey timelines and reduces surface vessel charter costs. |
Research Methodology
Cross-validation between primary interviews with ISA contractors, marine engineering executives, and battery cathode procurement leads anchors the qualitative findings, supplemented by secondary analysis of International Seabed Authority contract registries, exploration vessel deployment records, and East Asian offtake agreement disclosures. Bottom-up equipment procurement forecasts triangulate against top-down mineral demand projections from Korean and Japanese cell manufacturers.
Calibration against historical exploration-to-production timelines in comparable extractive industries shapes the analytical framework across the analysis window, modeling resource type, mining technology, application sector, and operator type dimensions. CAGRs derive from contracted production capacity buildouts and equipment delivery schedules. Forecast inputs include ISA regulatory publication timelines and East Asian battery cathode chemistry evolution toward high-nickel formulations.
Macroeconomic conditions sit as an overlay; deviation in battery electric vehicle penetration rates, terrestrial nickel laterite expansion pace, or ISA royalty structure severity would shift the trajectory. Cross-checking against International Energy Agency critical mineral demand benchmarks and seabed mining project development databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Injectable Nanomedicine Market
Others
Qatar Smartphone Market
Others
Duty Free Retail Market
Others
Folding Mobile Phone Market
Others
South Korea Smart Home Market
Others
Bitcoin Mining Servers Market
Others
8K Technology Market
Others
Residential Electrical Conduit Market
Others
Global Flexible PVC Films Market
Others
Gas Holders Market
Others
APAC Smart Home Market
Others
Smart Badge Market
Others
Air Separation Plant Market
Others
Smart Home Water Softener Market
Others
Reduced-Risk Products (Rrps) Market
Others
Consumer Video Feedback Software Market