
 Smart Home Platforms Market | 2026-2036
Smart Home Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Platforms Market Intelligence
Silicon Valley sensor fabs and Shenzhen electronics assemblers are restructuring capacity toward voice-activated control modules and edge-AI chipsets for residential gateways. Crestron anchors the luxury custom-installation channel with proprietary programming environments that lock in high-margin dealer networks. Ring competes through deep vertical integration into video doorbell hardware and subscription cloud storage, while SwitchBot extends its footprint via retrofit actuator designs that bypass full-system replacement costs.
Smart home platforms are software-hardware ecosystems that coordinate connected devices through protocol translation, automation scripting, and remote access interfaces, typically requiring sub-100-millisecond latency for real-time responsiveness and AES-256 encryption for data transit. Their primary purpose is to unify fragmented device ecosystems into interoperable environments for energy management, security monitoring, and ambient living optimization. Cloud-based deployment captures the dominant revenue share as homeowners prioritize over-the-air updates and remote diagnostics over local server maintenance. Smart security hardware generates premium margin pools due to recurring monitoring subscriptions, while Zigbee technology leads in mesh reliability for whole-home coverage despite Wi-Fi's ubiquity in single-point devices.
FCC Part 15 rules govern unlicensed radio emissions for Zigbee and Z-Wave devices in the United States, while the EU AI Act imposes risk-classification requirements on automated decision-making in residential energy platforms. These frameworks shape demand by mandating interoperability disclosures and cybersecurity certification before market access. Stakeholders must monitor whether emerging Matter protocol certification displaces proprietary walled gardens or reinforces brand-specific ecosystem loyalty through differentiated implementation layers.
Market Dynamics
The Matter protocol is compressing proprietary ecosystem lock-in by mandating cross-brand interoperability, forcing incumbents to open API layers while creating new margin pressure on hardware-only vendors.
Growth Catalysts
- Utility rebate programs:State-level demand-response incentives in the United States accelerate smart thermostat deployment through direct-install partnerships with regional power authorities.
- GDPR Article 25 compliance:European vendors are embedding privacy-by-design architectures that reduce cloud dependency and accelerate edge-gateway sales.
- Retrofit actuator economics:Battery-powered motorization modules eliminate electrical rewiring costs, expanding addressable stock to pre-1990s housing inventory.
Market Restraints
- Silicon supply concentration:Edge-AI chip fabrication depends on TSMC advanced-node capacity in Taiwan, creating single-source vulnerability for residential gateway processors.
- FCC Part 15 certification delays:Unlicensed spectrum device approvals average fourteen months, freezing product launch timelines for Zigbee and Z-Wave hardware.
- Wi-Fi mesh substitution:Consumer-grade mesh routers with Thread border routing functionality erode dedicated smart home hub value propositions at sub-hundred-dollar price points.
Strategic Opportunities
- India affordable housing stock:PLI scheme subsidies for domestic electronics manufacturing create localized production cost advantages for entry-level sensor modules.
- Health-monitoring convergence:Fall-detection radar and sleep-tracking environmental sensors merge aging-in-place and wellness verticals into unified ambient monitoring platforms.
- EU Green Deal renovation wave:Mandatory energy-performance certificates for rental properties create regulatory pull for integrated HVAC and lighting automation systems.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers with real-time operating system expertise delays edge-computing product roadmaps by six to nine months.
- Matter certification backlog:Connectivity Standards Alliance testing queue extends to twenty-two weeks, forcing vendors to choose between delayed launches or pre-certified module premiums.
- Legacy Z-Wave integration:Existing installed bases on 500-series chipsets require protocol translation gateways that add hardware cost and latency to unified control experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Platforms Market |
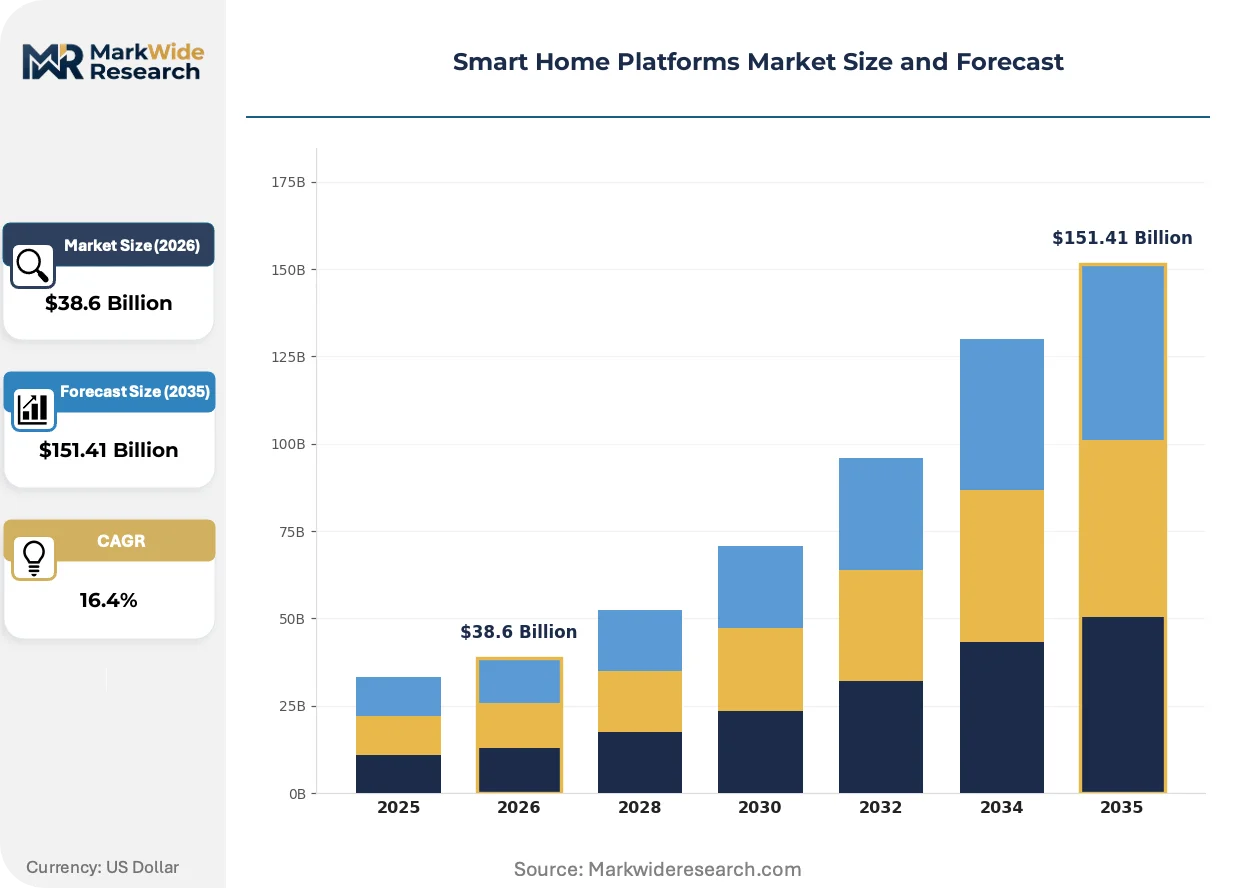
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Product Type: Smart Lighting, Smart Security, Smart HVAC, Smart Appliances User Type: Residential, Commercial, Industrial, Hospitality Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth |
| Companies Covered | Josh.ai, Ring, Control4, SwitchBot, SimpliSafe, Savant, Latch, Legrand | AV, Crestron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Platforms Market Strategic Shifts & Innovations
Protocol unification and edge-AI inference are redrawing competitive boundaries between cloud-centric subscription models and localized processing architectures that eliminate recurring fees.
Thread wireless mesh technology is absorbing the low-power device connectivity layer previously fragmented across Zigbee, Z-Wave, and proprietary RF implementations. Multi-family property developers in Germany and the Netherlands specify Thread-native hardware to simplify commissioning and reduce truck-roll maintenance costs. This absorption is compressing protocol licensing revenue for legacy radio-stack vendors while expanding silicon volume for IEEE 802.15.4 chipset suppliers.
The EU AI Act risk-classification framework imposes documentation and human-oversight requirements on automated energy-load-shifting algorithms that affect resident comfort or safety. Vendors must maintain technical files demonstrating conformity assessment for high-risk residential decision-making systems. French and German smart thermostat manufacturers are responding by localizing inference models on-device to avoid cloud-based classification triggers.
Property technology procurement teams now unbundle hardware purchase from installation and monitoring services, compressing traditional dealer margin stacks. Large multifamily operators in Texas and Florida negotiate direct volume contracts with Shenzhen ODMs, bypassing distribution layers that previously captured thirty to forty percent of equipment value. This disintermediation is most visible in Class-B apartment repositioning projects where CapEx discipline overrides brand preference for established control systems.
Smart Home Platforms Market Segmentation
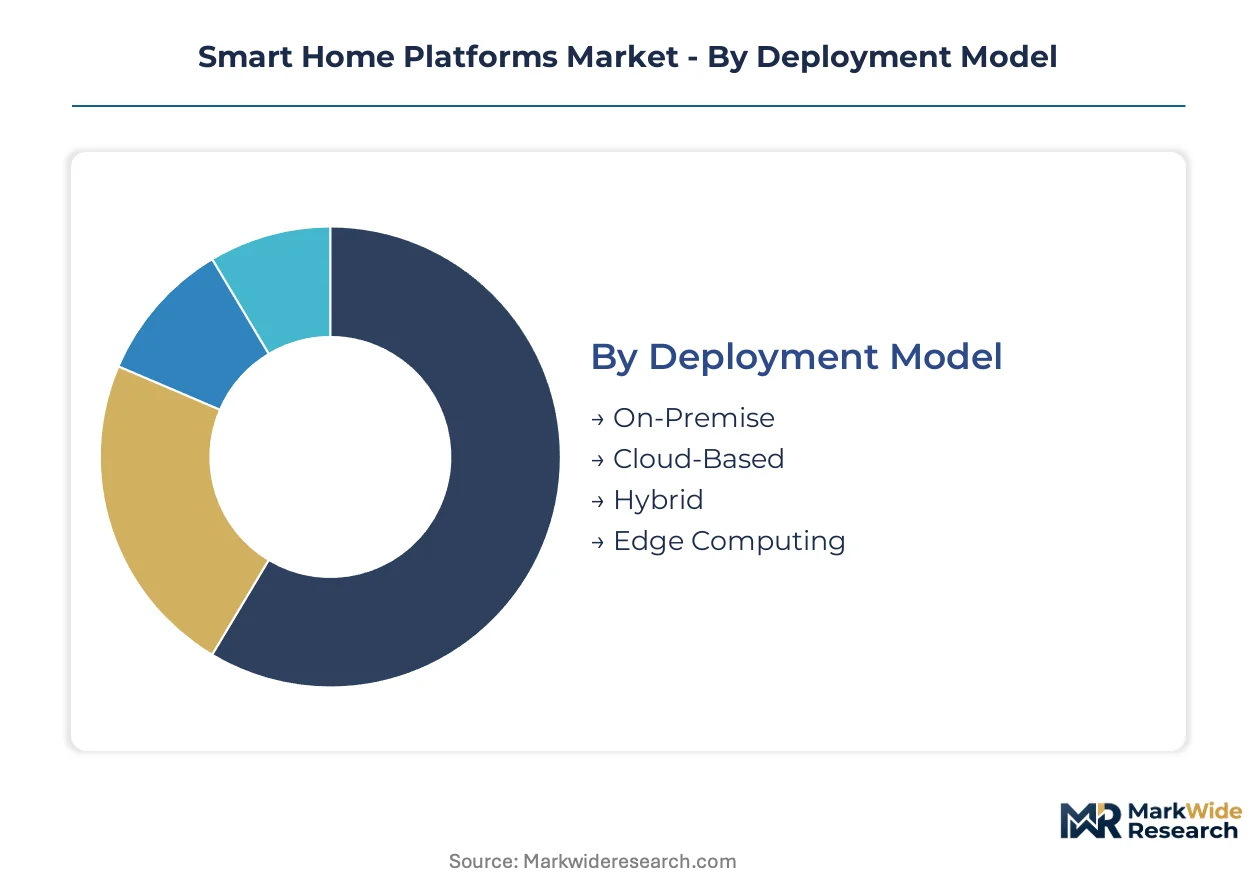
Smart home platform architectures fragment across deployment topologies, hardware categories, and connectivity standards. Each segmentation axis carries distinct margin profiles, regulatory exposure, and integration complexity that reshape vendor positioning.
Deployment Model:
Cloud-based deployment demands the heaviest upfront infrastructure investment—server farms, redundancy architecture, and cybersecurity certification—while edge computing shifts capital toward silicon design and on-device inference engines.
- Cloud-Based:Centralized orchestration layers host automation logic on vendor-controlled servers, enabling over-the-air updates and remote diagnostics. Demand concentrates in United States utility rebate programs where regional power authorities subsidize thermostat-to-grid connectivity. Recurring subscription revenue offsets infrastructure amortization.
- Edge Computing:Localized inference engines process sensor data without cloud transit, satisfying GDPR Article 25 data-localization mandates in Germany and France. European vendors prioritize this architecture to avoid EU AI Act risk-classification triggers for automated residential decision-making.
- Hybrid:Split processing between local gateways and cloud analytics balances latency sensitivity with computational intensity.
- On-Premise:Self-hosted server installations persist in luxury custom-installation channels where homeowners reject third-party data custody.
Cloud-based deployment absorbs the bulk of installed capacity; edge computing is expanding most quickly.
Product Type:
Application context determines which hardware categories command premium pricing versus commodity substitution—security systems lock in recurring monitoring fees while lighting faces LED commoditization.
- Smart Security:Video doorbells, motion sensors, and access control systems generate recurring monitoring subscriptions that sustain dealer network margins. Deep integration into cloud storage and AI-powered object detection creates switching costs. Demand clusters in United States suburban single-family construction and Texas multifamily Class-B repositioning projects.
- Smart HVAC:Thermostats and zone controllers anchor utility demand-response programs, with FERC-influenced state regulators mandating interoperability for grid-stabilization incentives. Load-shifting algorithms face escalating EU AI Act documentation requirements when affecting resident comfort.
- Smart Lighting:Fixture-agnostic control modules and retrofit actuators bypass electrical rewiring, expanding into pre-1990s European housing stock under EU Green Deal renovation mandates.
- Smart Appliances:White-goods connectivity remains fragmented across manufacturer-specific protocols, limiting cross-brand automation scripting.
Smart security captures the highest margin per unit; smart HVAC is climbing the fastest on regulatory energy-efficiency mandates.
User Type:
Customer procurement sophistication separates enterprise-grade specification from consumer impulse purchase—commercial buyers unbundle hardware from installation while residential markets favor bundled simplicity.
- Residential:Homeowners prioritize smartphone app continuity and voice-activated control modules, driving volume for Wi-Fi-connected point solutions. Matter protocol certification reduces ecosystem lock-in friction.
- Commercial:Office and retail property managers specify Thread-native hardware to reduce commissioning truck rolls, negotiating direct Shenzhen ODM contracts that bypass traditional distribution markups.
- Hospitality:Hotel chains demand guest-room automation with centralized energy management, prioritizing systems that integrate with legacy building management protocols.
- Industrial:Warehouse and logistics facilities apply smart platform architectures to environmental monitoring and access control, though this remains peripheral to core operational technology stacks.
Residential deployment dominates unit volume; commercial applications are gaining share fastest on property-technology procurement centralization.
Technology:
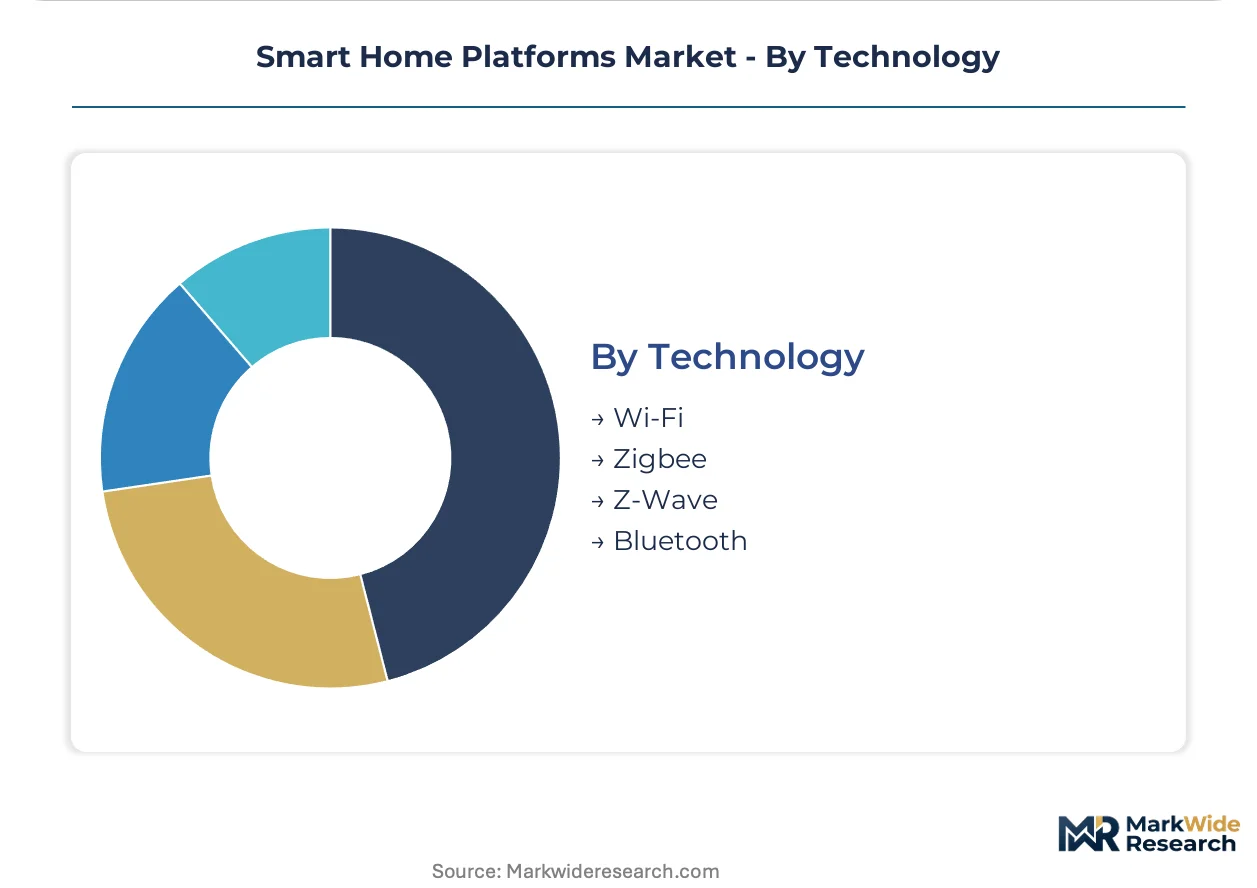
Radio-stack licensing economics and mesh reliability tradeoffs concentrate silicon purchasing power among IEEE 802.15.4 chipset suppliers while Wi-Fi ubiquity erodes dedicated hub value.
- Zigbee:Mesh networking protocol delivers whole-home coverage with sub-100-millisecond latency for real-time responsiveness. German and Dutch multifamily developers specify Zigbee-native hardware for reduced maintenance overhead. FCC Part 15 certification delays averaging fourteen months freeze product launch timelines.
- Wi-Fi:Single-point device connectivity leverages existing residential infrastructure, though power consumption limits battery-operated sensor applications. Consumer-grade mesh routers with Thread border routing functionality compress dedicated smart home hub pricing below hundred-dollar thresholds.
- Z-Wave:Sub-GHz spectrum penetration through walls sustains installed base loyalty, though 500-series legacy chipsets require protocol translation gateways that add hardware cost.
- Bluetooth:Low-energy implementations serve proximity-based device commissioning and wearable integrations, lacking whole-home mesh coverage.
Zigbee retains the deepest installed base; Thread absorption of the low-power layer is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley sensor fabs and Shenzhen electronics assemblers anchor the upstream supply base for voice-activated control modules and edge-AI chipsets. Cloud infrastructure clusters in Northern Virginia and Frankfurt am Main host the orchestration layers that coordinate multifamily portfolios. Regulatory divergence between FCC Part 15 spectrum rules and EU AI Act risk-classification requirements is fragmenting deployment architectures across jurisdictions.
United States
Utility-driven rebate programs in Texas and Florida accelerate smart thermostat deployment through direct-install partnerships with regional power authorities. FERC-influenced state regulators mandate interoperability for grid-stabilization incentives under demand-response frameworks. Northern Virginia data center clusters host cloud-based orchestration layers for residential property managers embedding smart platforms across Class-B apartment repositioning projects.
Germany
GDPR Article 25 compliance requirements push vendors toward edge-computing architectures with localized data processing in residential gateways. The EU AI Act imposes documentation and human-oversight requirements on automated energy-load-shifting algorithms affecting resident comfort. Bavarian industrial zones manufacture Thread-native hardware for multifamily developers seeking reduced commissioning truck-roll costs.
China
Shenzhen electronics assemblers restructure capacity toward edge-AI chipsets for residential gateways serving domestic and export markets. MIIT standards for IoT device cybersecurity shape certification requirements for Zigbee and Wi-Fi modules. Pearl River Delta manufacturing clusters produce retrofit actuator modules that bypass full-system replacement costs in aging housing stock.
India
PLI scheme subsidies for domestic electronics manufacturing create localized production cost advantages for entry-level sensor modules targeting affordable housing stock. The country's national electronics regulator mandates cybersecurity disclosure for connected home devices prior to market access. Maharashtra and Karnataka industrial corridors attract contract manufacturers assembling battery-powered motorization modules for pre-1990s housing inventory.
Netherlands
EU Green Deal renovation wave mandates create regulatory pull for integrated HVAC and lighting automation systems in rental properties. Eindhoven-based semiconductor designers supply IEEE 802.15.4 chipsets for Thread-native hardware specifications. Randstad metropolitan developers specify cloud-based orchestration layers to reduce operational expenditure across multifamily portfolios.
Smart Home Platforms Market Key Industry Players
Global majors compete with regional champions across protocol certification and installation channel control. The vendor base stratifies into three tiers: luxury custom-installation specialists with proprietary programming environments, mass-market hardware-software integrators with subscription cloud storage, and retrofit-focused actuator designers with battery-powered motorization modules. Dominant competitive moves include strategic partnerships with Shenzhen ODMs for direct volume contracts and technology licensing agreements to accelerate Matter protocol certification.
Within the luxury custom-installation tier, Crestron and Savant exemplify high-margin dealer network lock-in through captive programming environments. Ring and SimpliSafe occupy positions in the mass-market security vertical, anchoring recurring monitoring subscription models. SwitchBot represents the retrofit-specialist archetype, extending footprint via actuator designs that eliminate electrical rewiring costs in aging housing stock.
| Leading Market Players |
|---|
| Josh.ai |
| Ring |
| Control4 |
| SwitchBot |
| SimpliSafe |
| Savant |
| Latch |
| Legrand | AV |
| Crestron |
| Others |
Cost & Logistics Intelligence
Edge-AI chipset localization for residential gateways simultaneously compresses cloud-dependent subscription pricing and concentrates silicon purchasing power among Taiwan and South Korea foundries serving GDPR-compliant European deployments.
Pricing Analysis
Warranty and installation service bundling separates luxury custom-installation quotes from mass-market hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—Matter protocol compliance commands modest premiums over proprietary ecosystems. Cost compression in entry-level sensor modules intensifies because Shenzhen ODMs negotiate direct volume contracts with Texas multifamily operators. Commercial property managers exhibit highest price sensitivity through unbundled procurement, while luxury homeowners accept bundled premiums for dealer network continuity.
Supply Chain Analysis
Reverse-logistics flows for Z-Wave 500-series legacy hardware create refurbishment channels that extend chipset lifecycle value before Matter-native replacement. Component sourcing draws from Taiwan advanced-node fabrication, Shenzhen electronics assembly, and Bavarian Thread-native hardware manufacturing. Silicon supply rests on TSMC capacity concentration for residential gateway processors. Single-source vulnerability persists for edge-AI chip fabrication. Distribution runs through Shenzhen ODM direct contracts, bypassing traditional dealer markups in North American multifamily segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Home Platforms Market operates as a cost-of-compliance story where EU AI Act documentation requirements and GDPR Article 25 mandates erect barrier-to-entry moats favoring vendors with pre-certified edge-computing architectures.
For Market Incumbents: Anticipate Matter protocol certification backlog pressure by accelerating Connectivity Standards Alliance queue positioning before competitive displacement. Invest in captive edge-AI silicon design to reduce TSMC single-source exposure. Deepen Thread-native hardware specification control with German and Dutch multifamily developers to lock in reduced truck-roll maintenance contracts.
For New Entrants and Emerging Players: Pre-1990s European housing stock represents an underserved buyer archetype with unmet retrofit actuator demand under EU Green Deal renovation mandates. Battery-powered motorization modules bypass electrical rewiring barriers in aging inventory. Target India affordable housing segments through PLI scheme subsidized production partnerships with Maharashtra contract manufacturers.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays—backward integration into edge-AI chipset design or upstream control over IEEE 802.15.4 silicon supply. Long-term viability favors vendors with localized inference capabilities that sidestep EU AI Act risk-classification triggers. Monitor Matter protocol adoption velocity as inflection indicator for proprietary ecosystem displacement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-brand interoperability mandates compress proprietary lock-in while opening API layers for ecosystem expansion. |
| Edge-AI Chipset Localization | On-device inference satisfies GDPR Article 25 and EU AI Act compliance without cloud transit classification triggers. |
| Shenzhen ODM Direct Contracting | Volume procurement bypasses thirty-to-forty-percent distribution markups in Texas multifamily repositioning projects. |
| Thread-Native Hardware Specification | German and Dutch developers reduce commissioning truck rolls through simplified mesh commissioning protocols. |
| Battery-Powered Retrofit Actuator Expansion | Pre-1990s housing inventory access eliminates electrical rewiring cost barriers under EU Green Deal mandates. |
Research Approach
SEC filings, Connectivity Standards Alliance certification databases, and FERC demand-response program disclosures formed the secondary backbone for market sizing validation. Primary interviews with smart home platform engineering leads, multifamily property technology procurement officers, dealer network operators, and edge-AI semiconductor product managers informed deployment architecture preferences. Bottom-up unit shipment estimates triangulated against top-down utility rebate program expenditure data across United States state-level jurisdictions.
Historical trendline analysis of smart thermostat installation velocity and voice-activated control module shipment patterns anchored the projection framework. Segmentation modeling spanned deployment topology, hardware category, connectivity standard, and regional regulatory cluster dimensions. CAGRs derived from curve-fitting approaches applied to utility incentive program scaling trajectories and EU Green Deal renovation wave regulatory timelines. Forecast inputs incorporated Matter protocol adoption elasticity estimates and edge-computing gateway pricing erosion curves.
Revisions become necessary when TSMC capacity allocation shifts, FCC Part 15 certification timelines extend materially, or EU AI Act enforcement guidance tightens residential energy-load-shifting algorithm classifications. Forecasts reflect documented assumptions regarding Thread absorption velocity and Zigbee installed base loyalty decay. Practitioners should monitor Connectivity Standards Alliance testing queue duration and Shenzhen ODM contract pricing transparency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Social Networks Market
Others
Latin America Travel Retail Market
Others
Latin America 3D Printing Construction Market
Others
Rotary Union Market
Others
Subtilisin Market
Others
Smart Home Solutions Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Smart Home and Office Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Reinforcement Geosynthetics Market
Others
Super Computer Market
Others
Reusable Wine Bags Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Surgical Simulation Market
Others
Solar Animal Repeller Market
Others
Refractometer Market