
 South Korea Automotive LED Lighting Market | 2026-2036
South Korea Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive LED Lighting Market Insights
LED optics engineering talent scarcity is reorganizing supplier hierarchies as domestic automakers expand intelligent lighting programs. Hyundai Mobis leverages captive module integration to dominate headlamp assembly for Hyundai and Kia nameplates. Seoul Semiconductor sustains chip-level innovation through its WICOP platform, while LG Innotek competes on thermal management substrates for high-lumen density packages.
South Korea Automotive LED Lighting comprises solid-state illumination systems using semiconductor diodes emitting visible light when electrical current passes through a p-n junction, typically operating at forward voltages of 2.5–3.5V per chip with luminous efficacy exceeding 150 lm/W in premium automotive grades. Headlights command the largest value pool as adaptive driving beam systems displace static halogen and xenon architectures in mid-tier passenger vehicles. OLED technology for tail lamp signature lighting represents the fastest-expanding segment, though laser-based high-beam augmentation remains confined to flagship nameplates due to thermal and packaging constraints.
MFDS enforces automotive component safety certification under KMVSS, while KTL and KTC laboratories conduct photometric testing aligned with UN ECE R48 and R123 standards for road-legal LED installations. The Ministry of Environment's carbon neutrality roadmap pressures suppliers to reduce rare-earth phosphor dependence and adopt lead-free solder processes. Stakeholders must monitor KMVSS amendment cycles and OEM platform consolidation timelines to calibrate capacity and certification investments.
Market Dynamics
Adaptive matrix LED headlamp systems are compressing traditional static lighting architectures across South Korea's passenger vehicle tiers, forcing tier-1 suppliers to reconfigure optical engineering capabilities around real-time beam modulation software.
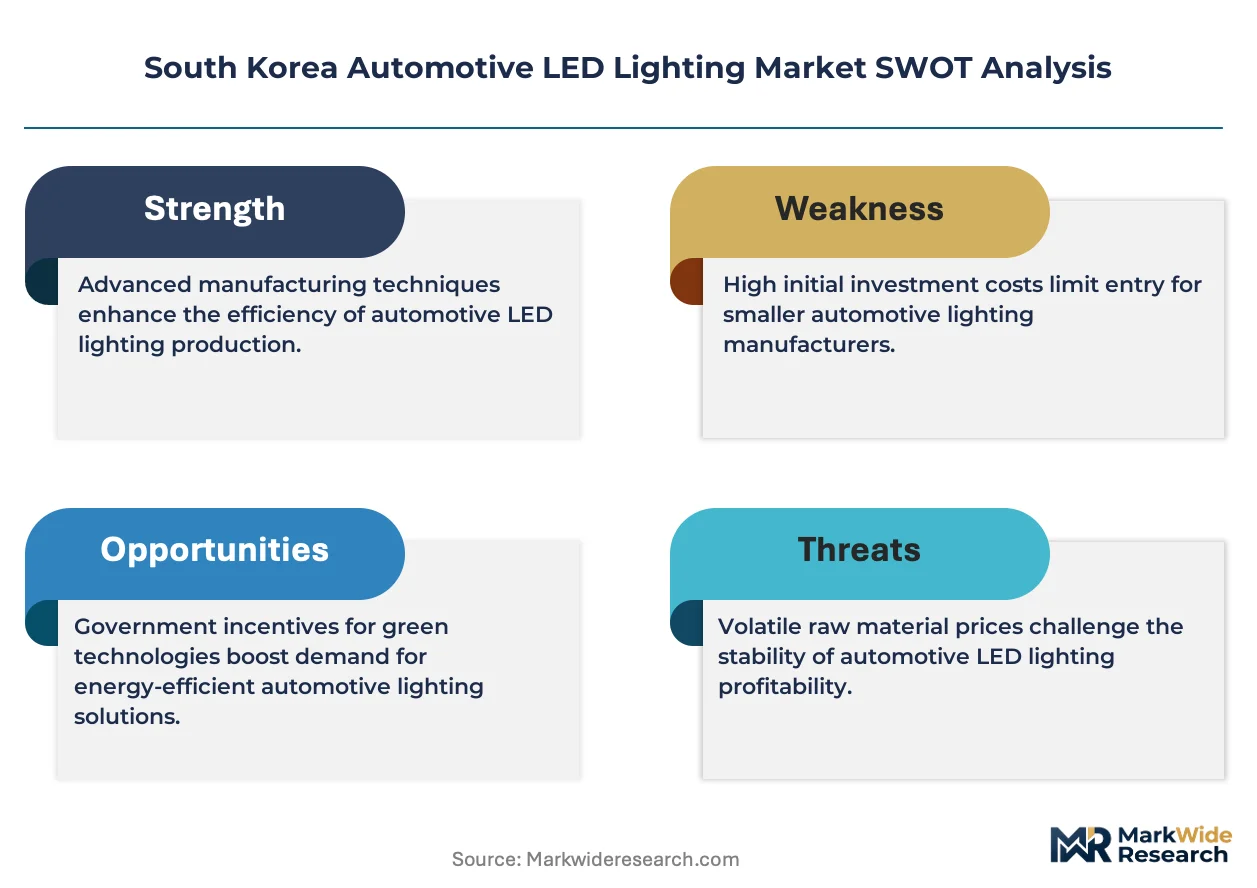
Growth Catalysts
- UN ECE R123 Harmonization:MFDS alignment with international adaptive driving beam standards accelerates OEM platform homologation timelines for intelligent headlamp systems.
- Seoul-Incheon Manufacturing Corridor Concentration:Hyundai Motor Group's integrated supplier ecosystem enables rapid prototype-to-production cycles for new LED module generations.
- OLED Tail Lamp Diffusion:Thin-film organic emitters enable signature lighting differentiation that commands premium pricing in domestic C-segment SUVs.
Market Restraints
- Rare-Earth Phosphor Supply Concentration:Dependence on external ceramic phosphor sources exposes South Korean packagers to input cost volatility and geopolitical supply interruptions.
- Thermal Management Complexity:High-lumen density LED arrays require aluminum nitride substrates and active cooling loops that inflate module BOM costs beyond halogen replacement parity.
- Laser Augmentation Packaging Constraints:Flagship vehicle laser high-beam systems face KMVSS photometric compliance barriers that limit volume deployment to ultra-premium nameplates.
Strategic Opportunities
- Busan-Ulsan Heavy Commercial Corridor:Underpenetrated LED retrofit demand in aging truck and bus fleets creates aftermarket volume for standardized headlamp replacement modules.
- Ministry of Environment Carbon Roadmap:Lead-free solder and reduced rare-earth mandates position domestic suppliers for preferential procurement under public fleet electrification contracts.
- LiDAR-Lighting Convergence:Integrated sensor-emitter modules combine adaptive beam control with autonomous perception, opening new value pools in advanced driver-assistance architectures.
Industry Challenges
- Optical Engineering Talent Scarcity:Compound semiconductor physics and freeform lens design expertise concentrates at Seoul National University and KAIST pipelines, constraining supplier scaling.
- KMVSS Amendment Cycle Uncertainty:Photometric testing protocol revisions at KTL and KTC laboratories compress certification timelines and require redundant pre-compliance investment.
- Legacy Platform Integration Friction:Intelligent lighting controller software must interface with decade-old vehicle network architectures, multiplying validation cycles for tier-1 integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive LED Lighting Market |
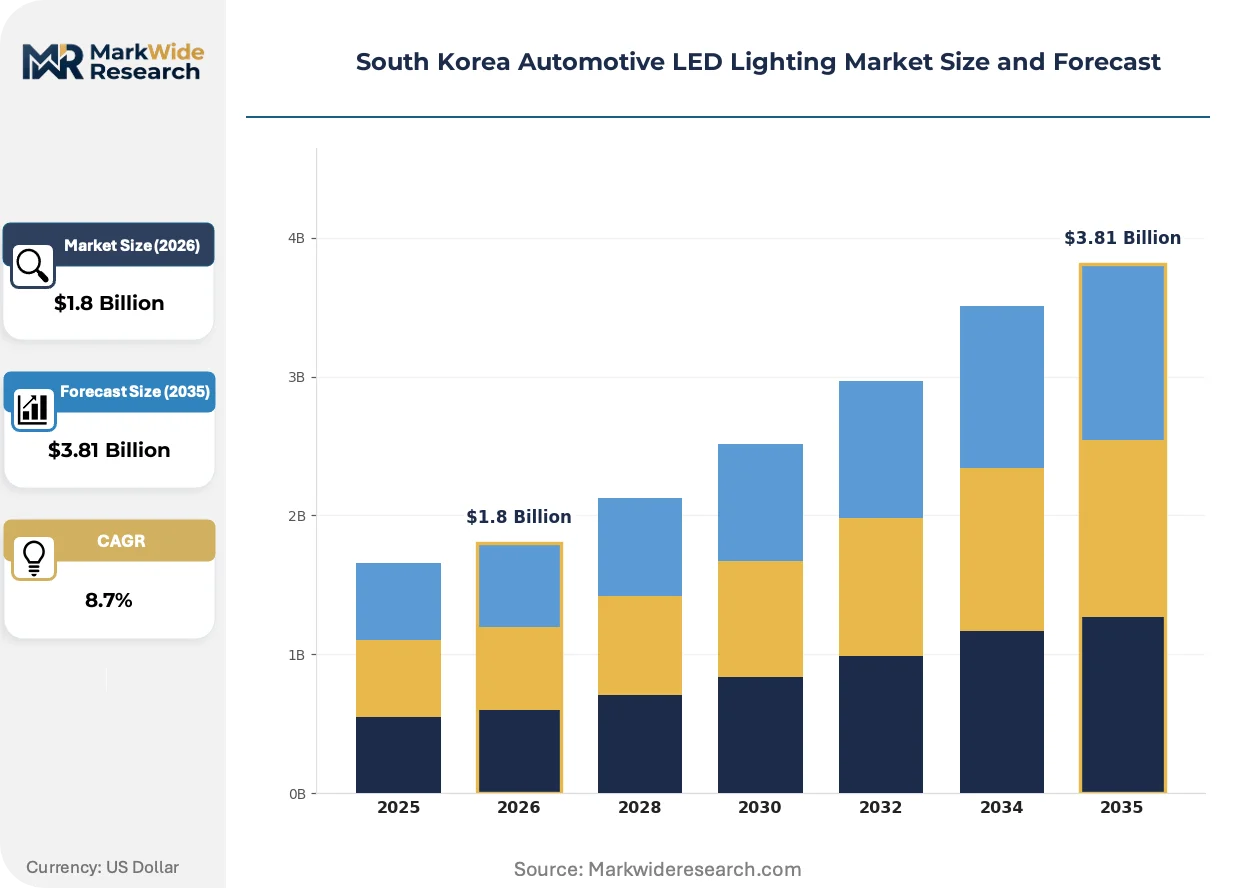
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Tail Lights, Fog Lights, Turn Signal Lights Technology: Halogen, Xenon, OLED, Laser End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Specialty Vehicles |
| Companies Covered | Hyundai Mobis Co., Ltd., Seoul Semiconductor Co., Ltd., LG Innotek Co., Ltd., Marelli Holdings Co., Ltd., Valeo S.A., Stanley Electric Co., Ltd., OSRAM GmbH, HELLA GmbH & Co. KGaA, Nichia Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive LED Lighting Market Trends and Innovations
Digital beam pattern control is fragmenting traditional headlamp value chains, separating optical hardware from software-defined illumination algorithms. Three convergent forces are restructuring competitive positioning.
Micro-LED pixel arrays are decomposing conventional reflector-and-lens headlamp architectures into software-programmable light engines. Domestic OEMs in the D-segment sedan category are adopting 10,000+ pixel density modules for glare-free adaptive high beams. This decomposition enables tier-1 suppliers to capture recurring software revenue streams alongside hardware shipments.
KMVSS revision cycles aligned with UN ECE R48 are tightening photometric compliance windows for road-legal LED installations. The Ministry of Environment's rare-earth reduction mandates are forcing phosphor formulation changes that alter color rendering indices. Premium passenger vehicle segments absorb these compliance costs through captive module integration, while aftermarket suppliers face margin compression from retesting requirements.
Buyer concentration around Hyundai Motor Group's platform consolidation is compressing supplier negotiation cycles and unbundling traditional lighting system procurement. Tier-1 integrators now compete for module-level contracts rather than complete headlamp assemblies, fragmenting historical supply relationships. This pattern concentrates in the Seoul metropolitan manufacturing cluster where platform commonality across Hyundai and Kia nameplates enables volume scaling.
South Korea Automotive LED Lighting Market Segmentation
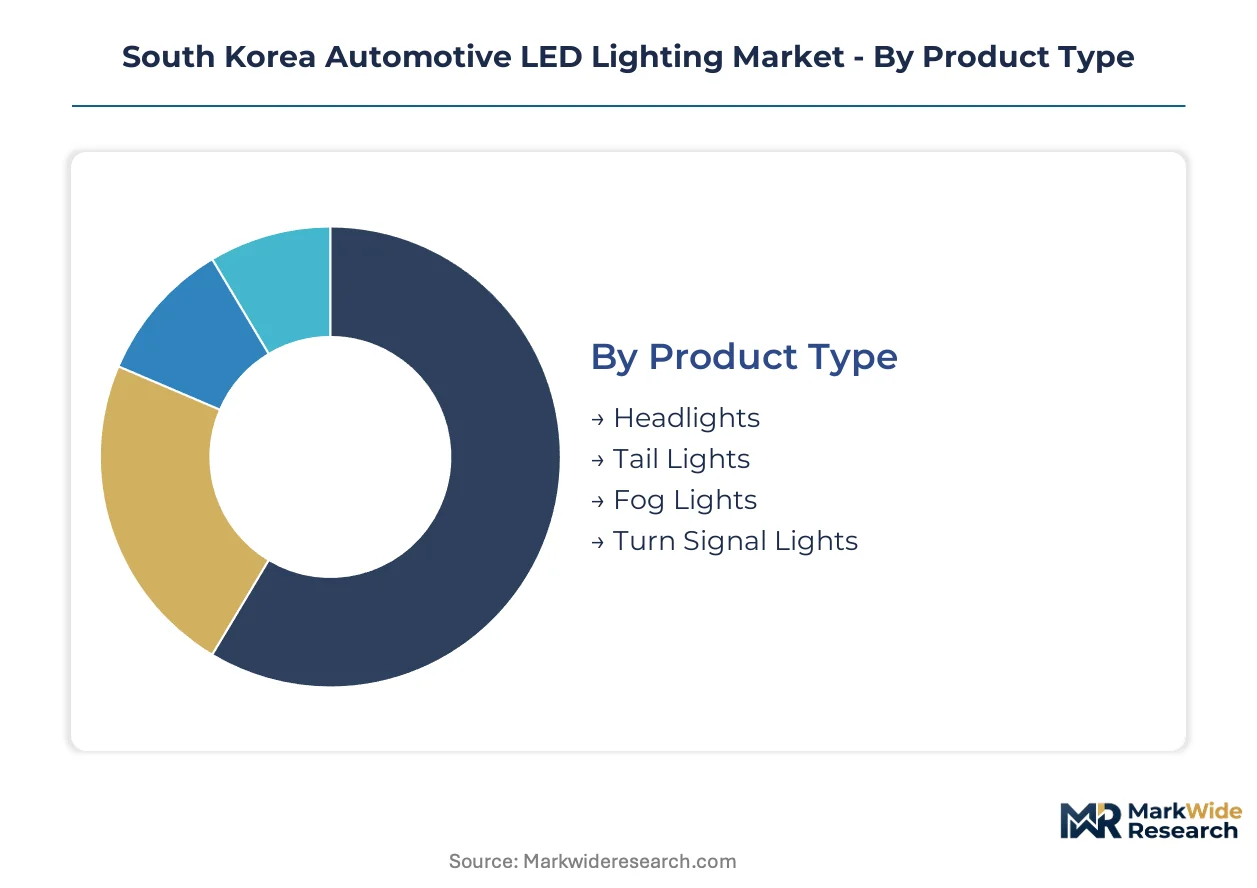
Segmentation in South Korea's automotive LED lighting market reflects divergent compliance burdens across KMVSS certification tiers and the concentration of intelligent lighting development within Hyundai Motor Group's platform architecture. Understanding these divides illuminates where procurement power concentrates and where aftermarket retrofit opportunities persist.
Product Type:
KMVSS photometric testing protocols impose stricter validation timelines on forward-facing illumination systems than rear or auxiliary lighting, reshaping supplier certification investments across the four product categories.
- Headlights:Adaptive matrix LED architectures operating at forward voltages of 2.5–3.5V per chip with luminous efficacy exceeding 150 lm/W dominate Seoul-Incheon manufacturing corridors. MFDS alignment with UN ECE R123 accelerates OEM platform homologation for intelligent driving beam systems in Hyundai and Kia D-segment nameplates.
- Tail Lights:OLED thin-film organic emitters enable signature lighting differentiation that commands premium pricing in domestic C-segment SUVs. Seoul semiconductor packagers are scaling phosphor-reduced formulations to meet Ministry of Environment carbon neutrality mandates while preserving color rendering indices.
- Fog Lights:Auxiliary beam modules face less stringent KTL photometric testing than primary headlamps, allowing faster certification cycles for tier-2 suppliers.
- Turn Signal Lights:Sequential LED indicators are displacing incandescent bulbs in mid-tier vehicle refreshes, with Busan-Ulsan heavy commercial fleets driving aftermarket replacement volume.
Headlights handle the majority of throughput; tail lights are the fastest mover on share.
Technology:
Cost tier stratification separates legacy incumbent technologies from emerging solid-state and coherent light sources, with thermal management requirements determining which segments achieve volume deployment.
- Halogen:Tungsten-filament technology constrained to entry-level vehicle trims and aging fleet retrofits where KMVSS grandfathering permits continued installation. Incheon aftermarket distributors maintain inventory for pre-2020 vehicle parc.
- Xenon:High-intensity discharge systems face displacement pressure from LED efficacy improvements, though HID persists in specific commercial vehicle configurations where beam throw distance outweighs energy efficiency.
- OLED:Organic electroluminescent panels enable thin-form-factor tail lamp designs with pixel-level addressability for dynamic turn signals. Domestic tier-1 integrators are securing module contracts for Hyundai Motor Group's electrified platform lineup.
- Laser:Coherent light augmentation for high-beam reach remains confined to ultra-premium nameplates due to KMVSS photometric compliance barriers and active cooling loop packaging constraints.
LED-based technologies command the dominant revenue position; OLED is expanding most quickly in premium applications.
End User:
Customer type determines procurement scale, with captive integration versus merchant supply creating divergent margin structures across the four end-user categories.
- OEMs:Hyundai Motor Group and Kia Corporation source intelligent lighting through platform-consolidated module contracts, compressing supplier negotiation cycles. MFDS safety certification requirements concentrate procurement authority at Seoul-Incheon headquarters.
- Aftermarket Providers:Independent distributors serve aging vehicle parc in Busan-Ulsan corridors where LED retrofit demand outpaces OEM replacement part availability.
- Vehicle Assemblers:Contract manufacturers for specialty and export markets require UN ECE R48-aligned components for international homologation.
- Tier-1 Suppliers:Hyundai Mobis leverages captive module integration to dominate headlamp assembly, while LG Innotek competes on thermal management substrates for external OEM contracts.
OEMs absorb the largest procurement volume; tier-1 suppliers are gaining share fastest through module-level unbundling.
Application:
Vehicle category dictates performance specifications and regulatory exposure, with passenger electrification programs diverging from commercial fleet replacement cycles.
- Passenger Vehicles:C-segment SUVs and D-segment sedans in the Seoul metropolitan cluster drive adaptive matrix LED adoption. KMVSS revision cycles aligned with UN ECE standards compress photometric compliance timelines for new model launches.
- Commercial Vehicles:Aging truck and bus fleets in the Busan-Ulsan corridor create underpenetrated LED retrofit demand for standardized headlamp replacement modules.
- Two-Wheelers:Motorcycle lighting faces less stringent KTL testing protocols, enabling faster aftermarket LED conversion but limiting intelligent feature penetration.
- Specialty Vehicles:Emergency and military applications require ruggedized optical assemblies with extended thermal operating ranges beyond standard automotive grades.
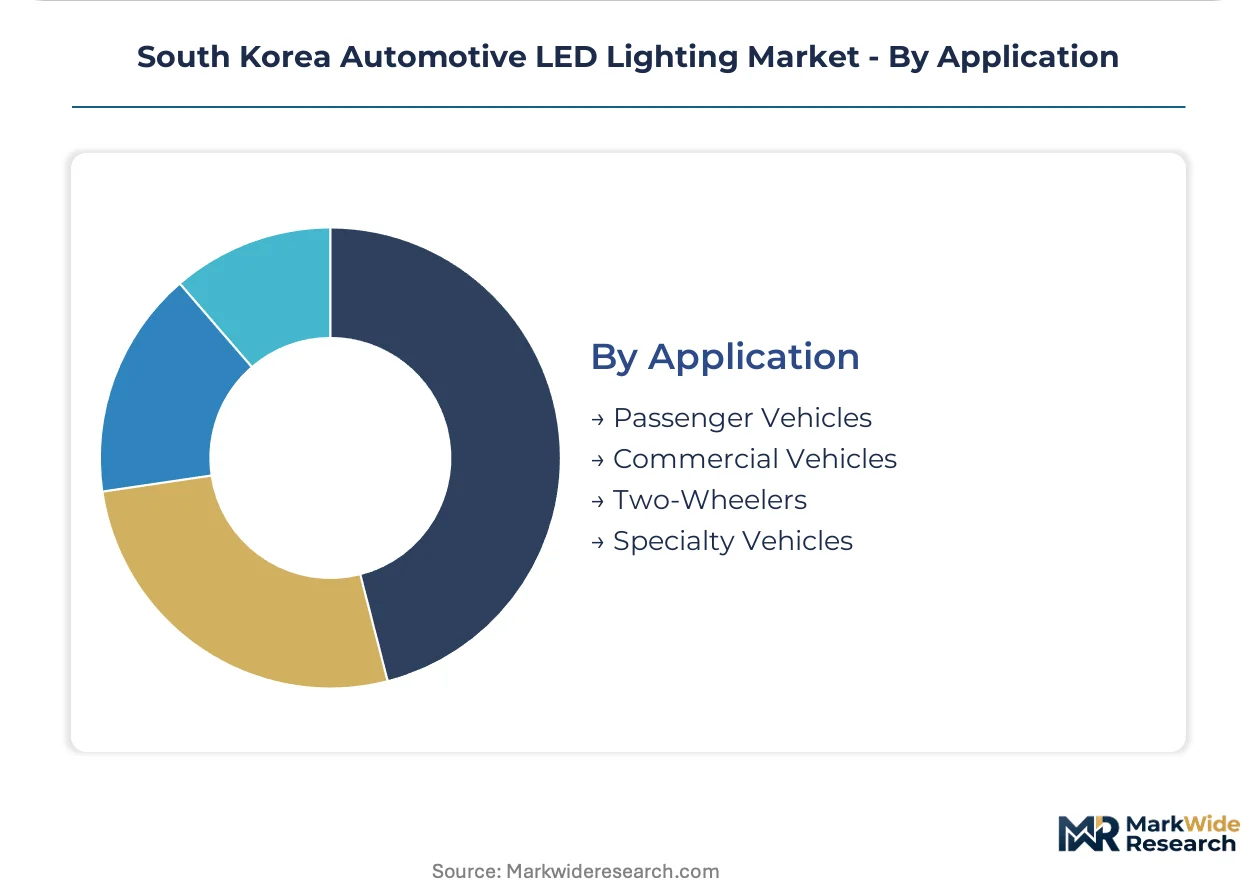
Passenger vehicles carry the dominant application share; commercial vehicles are climbing the fastest on retrofit-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's automotive LED lighting consumption concentrates in the Seoul-Incheon corridor where Hyundai Motor Group's integrated ecosystem dominates intelligent headlamp procurement. Busan-Ulsan heavy commercial corridors exhibit divergent demand patterns driven by aging fleet retrofit cycles rather than new platform integration.
Seoul Capital Area
Adaptive matrix LED headlamp development for Hyundai and Kia D-segment nameplates drives premium module demand. MFDS alignment with UN ECE R123 standards compresses photometric compliance timelines at KTL laboratories. Pangyo and Hwaseong R&D clusters host optical engineering talent pipelines from Seoul National University and KAIST.
Busan-Ulsan Corridor
Aging truck and bus fleets generate underpenetrated LED retrofit demand for standardized headlamp replacement modules. Ministry of Environment carbon neutrality mandates accelerate lead-free solder adoption in commercial vehicle lighting assemblies. Ulsan manufacturing complexes supply heavy-duty OEMs with UN ECE R48-aligned components for export homologation.
Daegu-Gyeongbuk
Specialty vehicle lighting for military and emergency applications requires ruggedized optical assemblies with extended thermal operating ranges. Regional suppliers focus on small-batch production of high-durability modules. Daegu-based fabricators serve defense procurement contracts outside standard automotive certification cycles.
Daejeon-Sejong
Government research institutes concentrate photometric testing infrastructure and standards development capabilities. KTC laboratories validate LED modules against KMVSS amendment cycles before commercial deployment. Sejong administrative complexes coordinate MFDS regulatory harmonization with international automotive lighting standards.
Gwangju-Honam
Two-wheeler LED conversion demand outpaces intelligent feature penetration due to less stringent KTL testing protocols. Aftermarket distributors serve motorcycle parc with faster certification cycles than passenger vehicle tiers. Honam regional suppliers specialize in auxiliary lighting modules for commercial vehicle retrofit segments.
South Korea Automotive LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South Korea's automotive LED lighting structure. Hyundai Mobis leverages captive module integration to dominate headlamp assembly for Hyundai and Kia nameplates, while tier-2 suppliers compete for unbundled component contracts. Two strategic archetypes define the competitive terrain: vertically integrated platform suppliers and specialized thermal management substrate fabricators. Dominant competitive moves include backward integration into chip-level manufacturing and strategic partnerships for LiDAR-lighting convergence modules.
Within the integrated platform tier, Hyundai Mobis Co., Ltd. and LG Innotek Co., Ltd. exemplify divergent strategic positioning. Hyundai Mobis anchors captive supply relationships through module-level integration for domestic OEM platforms. LG Innotek occupies a position emphasizing thermal management substrates for high-lumen density LED packages. Seoul Semiconductor Co., Ltd. represents the chip-level innovation archetype through its WICOP platform architecture. These three entities collectively illustrate how supplier hierarchies reorganize around optical engineering capabilities and intelligent lighting program expansion.
| Leading Market Players |
|---|
| Hyundai Mobis Co., Ltd. |
| Seoul Semiconductor Co., Ltd. |
| LG Innotek Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Valeo S.A. |
| Stanley Electric Co., Ltd. |
| OSRAM GmbH |
| HELLA GmbH & Co. KGaA |
| Nichia Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term module supply contracts between Hyundai Motor Group and tier-1 integrators lock in rare-earth phosphor access while capping price volatility for adaptive LED headlamp systems. This contract structure concentrates procurement leverage among Seoul-Incheon manufacturers and compresses margin negotiation windows for external packagers.
Pricing Analysis
Platform-consolidated offtake agreements dominate South Korea's automotive LED procurement, with Hyundai Mobis anchoring volume pricing through captive module integration. Price differentiation separates UN ECE R123-certified adaptive systems from standard static LED replacements, while aftermarket suppliers face margin compression from KTL retesting requirements. Cost compression in entry-tier halogen replacement segments intensifies due to Chinese import competition, though OEM captive buyers show limited price sensitivity for intelligent lighting content.
Supply Chain Analysis
Busan port congestion on ceramic phosphor inbound lanes from China and Taiwan elevates inventory carrying costs for domestic packagers. South Korea's LED module assembly draws from Taiwanese wafer foundries, Chinese phosphor ceramics, and Japanese aluminum nitride substrates, creating single-source vulnerability in rare-earth conversion materials. Distribution runs through Hyundai Motor Group's consolidated platform procurement at Seoul-Incheon headquarters, bypassing traditional tier-2 merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS alignment with UN ECE R123 is accelerating intelligent lighting adoption faster than supplier optical engineering capacity can scale, creating a high-growth disruption window. This regulatory inflection compresses homologation timelines and rewards early certification investments.
For Market Incumbents: Consolidate backward control over phosphor formulation capabilities to offset rare-earth supply concentration risk from Chinese ceramic sources. Deepen captive module integration with Hyundai Motor Group's electrified platform roadmap to defend against LG Innotek's thermal substrate advances in external OEM bidding.
For New Entrants and Emerging Players: Aftermarket software calibration services for legacy vehicle parc represent an underserviced layer where incumbents lack dedicated technical support infrastructure. Target Busan-Ulsan heavy commercial fleet retrofits with standardized KMVSS-compliant replacement modules, leveraging faster KTL certification cycles than passenger vehicle tiers permit.
For Investors and Strategic Acquirers: The market sits at a regulatory harmonization phase that favors chip-level technology specialists with WICOP-class platform architectures. Long-term viability hinges on LiDAR-lighting convergence capability development, with Seoul Semiconductor's optical integration pipeline serving as the signal to watch for autonomous perception module inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Beam Software Licensing | Enables tier-1 suppliers to capture recurring revenue beyond hardware shipments to Hyundai and Kia. |
| Phosphor-Reduced Formulation R&D | Positions domestic packagers for preferential procurement under Ministry of Environment carbon mandates. |
| LiDAR-Optical Module Integration | Combines adaptive beam control with autonomous perception for next-generation ADAS architectures. |
| Busan-Ulsan Aftermarket Distribution | Captures underpenetrated LED retrofit demand in aging truck and bus fleets outside OEM channels. |
| KMVSS Pre-Compliance Investment | Compresses photometric validation cycles at KTL laboratories ahead of amendment protocol releases. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 procurement directors, aftermarket distributors, and KTL laboratory certification specialists converged on the working assumptions for this analysis. Primary fieldwork combined structured interviews with secondary validation against MFDS regulatory filings, UN ECE homologation databases, vehicle production registries, and customs import records for rare-earth phosphor materials. Bottom-up module shipment estimates triangulated against top-down OEM platform content projections.
Segmentation dimensions modeled span product type, technology tier, end-user category, and vehicle application across the projection horizon. CAGRs derived from slope-log analysis of historical adoption curves and OEM platform rollout schedules, with specific inputs including adaptive headlamp penetration rates by vehicle class and OLED tail lamp content per vehicle for C-segment SUV nameplates.
Forecasts assume regulatory continuity in MFDS-KMVSS alignment with UN ECE standards; material policy shifts in photometric testing protocols or rare-earth import restrictions would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
United States Cigarette Market
Others
DIY Smart Home Market
Others
Global Smart Home Installation Service Market
Others
Underwater Communication System Market
Others
Moveable Water Tap Market
Others
Workstation Desktops Market
Others
Corn Fiber Market
Others
Brazil Cane Sugar Market
Others
Quadrant Scale Market
Others
India Smart Home Market
Others
Ambient Assisted Living and Smart Home Market
Others
Rotary Dial Machine Market
Others
Industrial Air Pollution Control Solutions Market
Others
Middle East Paper Making Machine Market
Others
5G Tester Market
Others
Storage Dewar and Dry Shipper Market