
 Fixed Satellite Services (FSS) Market | 2026-2036
Fixed Satellite Services (FSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Satellite Services (FSS) Market Intelligence
Managed services bundling is shifting how satellite capacity gets monetized, moving operators beyond raw transponder leases toward integrated network management. SES S.A. leverages its multi-orbit fleet to anchor premium enterprise contracts across maritime and government verticals. Viasat Inc. competes through high-throughput Ka-band architectures that sustain broadband margins in consumer and defense segments. Intelsat differentiates via software-defined satellite payloads that extend service flexibility without launching replacement spacecraft.
Fixed Satellite Services comprise the commercial provision of satellite bandwidth and connectivity through geostationary and non-geostationary constellations operating in designated radio-frequency spectrum allocations, typically delivering C-band, Ku-band, and Ka-band capacity for voice, video, and data transmission. Transponder leasing remains the largest revenue pool though managed services capture expanding margin as operators integrate ground infrastructure and network management. Ka-band technology leads growth trajectories for broadband and mobility applications while C-band retains structural importance for video distribution despite terrestrial 5G encroachment.
The FCC governs spectrum auctions and orbital slot coordination within the United States, directly influencing C-band clearing timelines and relocation cost structures for incumbent operators. EUTELSAT S.A. and other European operators navigate ITU filing requirements alongside EU Space Programme security standards that condition market access for government contracts. Stakeholders must monitor spectrum reallocation rulings, orbital debris mitigation mandates, and emerging direct-to-device satellite regulations that will reshape competitive positioning and capital deployment priorities.
Market Dynamics
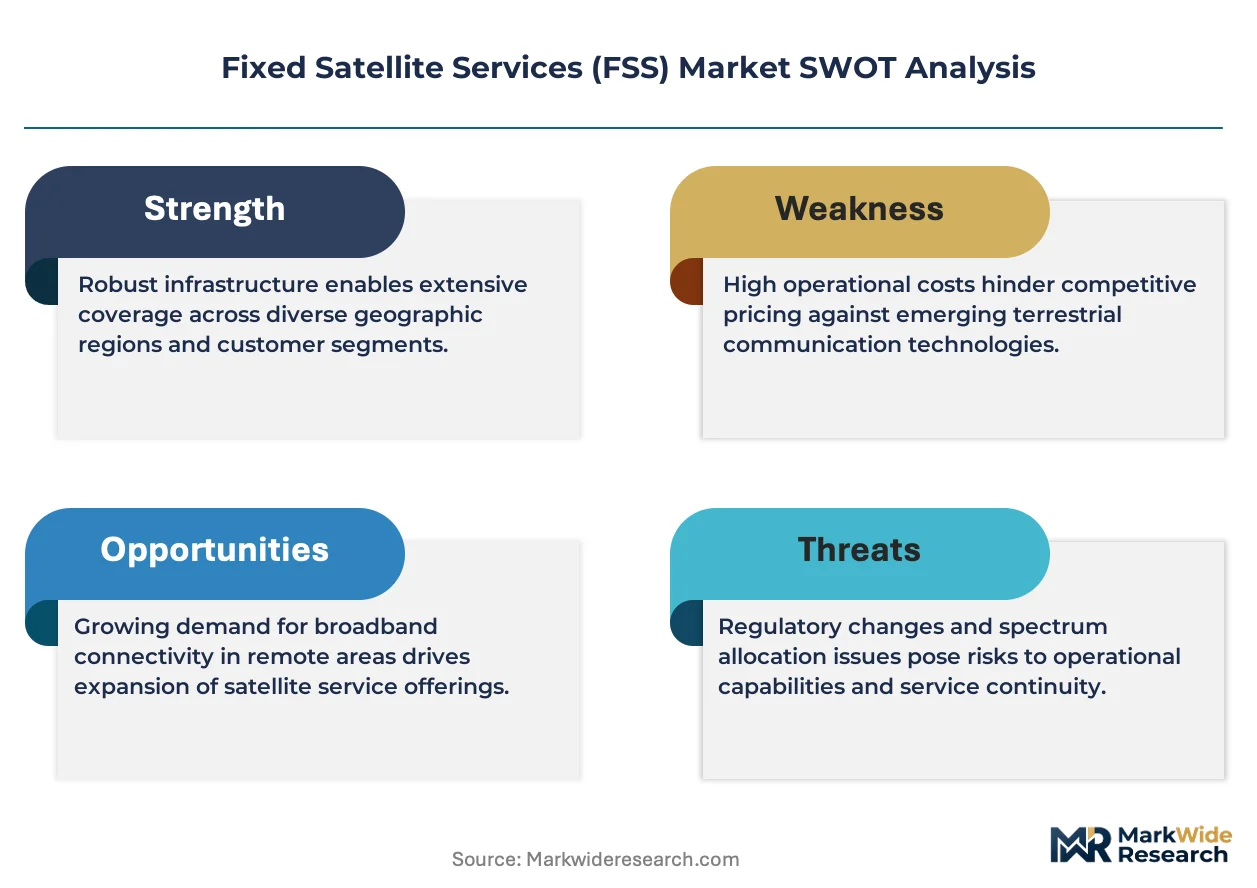
Spectrum reallocation mandates from the FCC are forcing incumbent operators to accelerate C-band clearing timelines while absorbing multi-billion dollar relocation costs, compressing available capacity and reshaping competitive positioning across geostationary and non-geostationary systems.
Growth Catalysts
- Enterprise maritime connectivity:Fleet digitization programs across container shipping and offshore energy are pulling dedicated Ka-band capacity for vessel operations and crew welfare services.
- FCC C-band auction proceeds:Relocation compensation frameworks are funding ground infrastructure upgrades that expand addressable markets for cleared spectrum holders.
- Saudi Arabia's National Transformation Program:Rural broadband mandates are directing government procurement toward satellite backhaul for unserved governorates.
Market Restraints
- Launch cost volatility:Geopolitical friction in Eastern Europe has destabilized propellant supply chains and ride-share mission availability, elevating per-kilogram payload economics.
- Terrestrial 5G encroachment:Mobile network densification in suburban corridors is eroding addressable fixed wireless access markets that satellite operators had targeted.
- ITU coordination delays:Orbital slot filing backlogs and interference disputes are extending time-to-market for new constellation deployments by 18-36 months.
Strategic Opportunities
- Direct-to-device integration:Partnerships between satellite operators and smartphone OEMs are opening consumer messaging and emergency services markets previously unreachable through traditional terminals.
- Brazil's Amazon connectivity gap:Regulatory carve-outs for indigenous territory communications are creating protected procurement channels for non-terrestrial networks.
- AI-driven network orchestration:Machine learning traffic prediction is converging with software-defined payloads to enable dynamic beam steering and spot-market capacity pricing.
Industry Challenges
- RF engineering talent scarcity:Specialist expertise in phased array antenna design and interference mitigation is concentrating among defense contractors, elevating recruitment costs for commercial operators.
- Legacy ground system integration:Hybrid architectures combining geostationary assets with low-earth orbit constellations require protocol translation layers that introduce latency and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Satellite Services (FSS) Market |
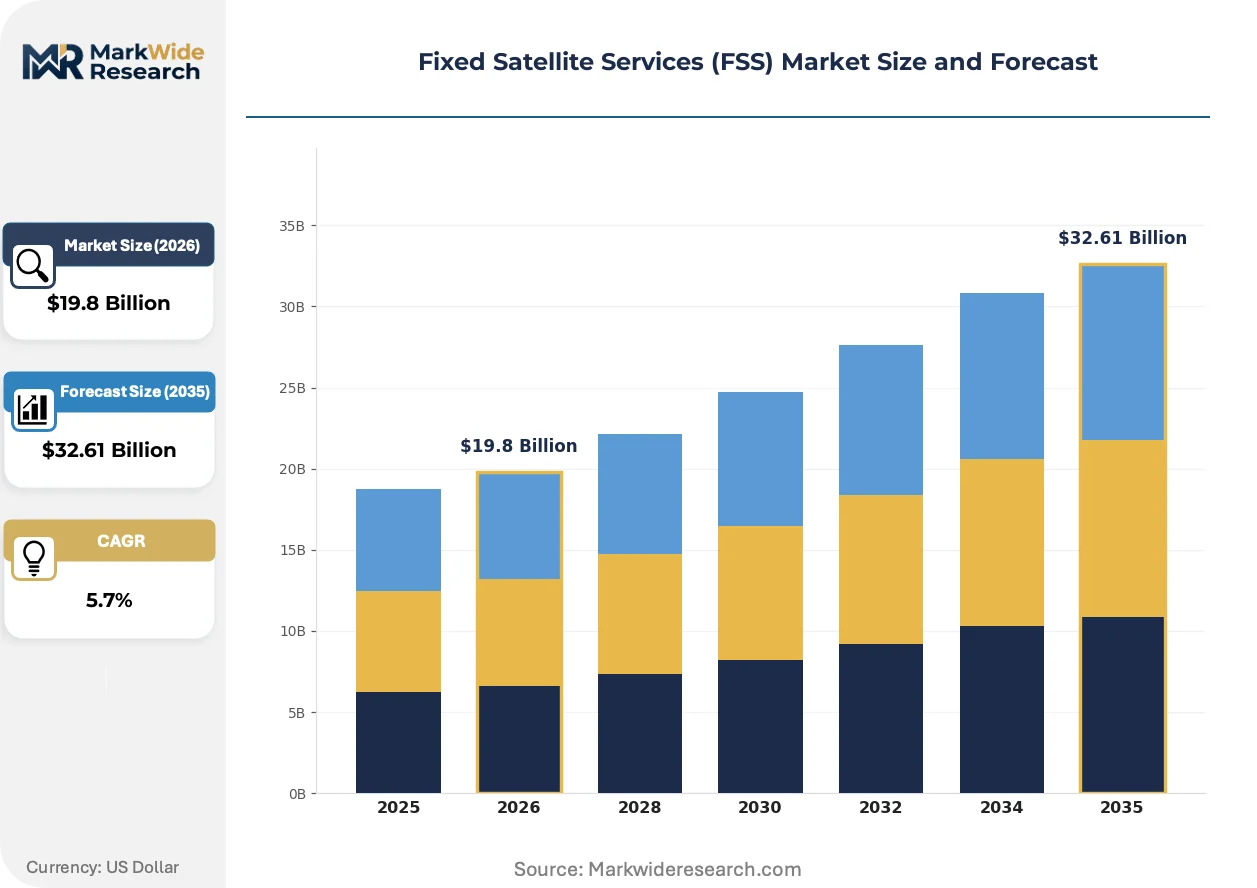
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transponder Leasing, Managed Services, Bandwidth Leasing, Direct-to-Home Application: Telecommunications, Broadcasting, Internet Access, Government Services End User: Telecom Operators, Broadcasters, Enterprises, Government Agencies Technology: C-Band, Ku-Band, Ka-Band, L-Band |
| Companies Covered | Hughes Network Systems, Inmarsat, SES S.A., Yahsat, China Satcom, Viasat Inc., Telesat, Intelsat, EUTELSAT S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Satellite Services (FSS) Market Strategic Shifts & Innovations
Payload digitization and ground segment virtualization are dissolving traditional boundaries between satellite manufacturing, launch services, and network operations, enabling new entrants to assemble capability stacks without vertical asset ownership.
Software-defined payloads with reprogrammable frequency plans and coverage footprints are converging with cloud-native ground infrastructure to let operators reconfigure satellite services in orbit rather than replacing spacecraft. Maritime and aviation integrators are adopting these flexible architectures fastest, compressing procurement cycles from 5-year transponder leases to annual managed service agreements. This convergence is enabling real-time capacity arbitrage across orbital regimes and reducing stranded asset risk for fleet operators.
REACH chemical restrictions and EU Space Programme security standards are conditioning market access for government contracts across European member states. Operators must now demonstrate supply chain traceability for satellite components and ground station hardware to qualify for institutional procurement. The defense and dual-use segments face the steepest compliance burden, with certification timelines extending 12-18 months for non-European payload suppliers.
Service unbundling is fragmenting traditional buyer relationships as enterprise customers separate space segment procurement from ground infrastructure and network management. Systems integrators and managed service providers are capturing margin that previously accrued to satellite operators, particularly in energy and mining verticals where private 5G networks require hybrid terrestrial-satellite backhaul. This pattern is most visible in Australia and Canada, where remote site operators prioritize single-vendor accountability over direct capacity contracts.
Fixed Satellite Services (FSS) Market Segmentation
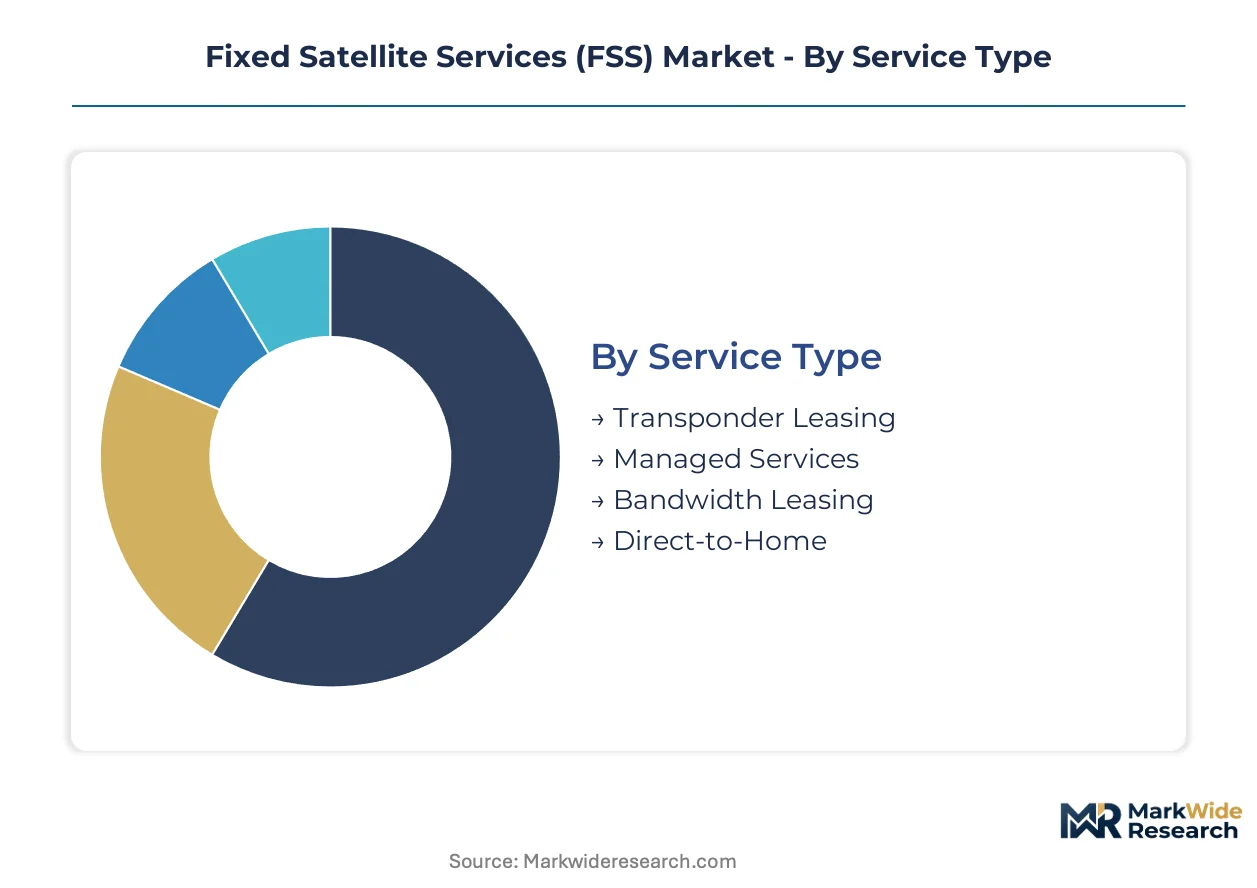
Segmentation in Fixed Satellite Services reveals how capacity monetization varies across technical architectures and customer procurement models. Understanding these divisions exposes where margin concentrates and which technology transitions are displacing legacy revenue streams.
Service Type:
Technology specifications define how satellite capacity reaches end customers and who controls the value chain.
- Transponder Leasing:Raw satellite capacity contracts where customers operate their own ground infrastructure and network management. Demand concentrates among broadcasters in Brazil and Saudi Arabia who maintain legacy video distribution networks amid C-band spectrum reallocation pressures.
- Managed Services:Integrated offerings bundling space segment with ground infrastructure, network operations, and service level guarantees. Maritime fleet operators across container shipping routes are pulling these contracts fastest as they digitize vessel operations and crew welfare platforms.
- Bandwidth Leasing:Partial transponder arrangements for customers needing dedicated but smaller capacity blocks. Telecom operators in remote governorates use these for cellular backhaul where fiber deployment is uneconomical.
- Direct-to-Home:Consumer satellite television distribution through small aperture terminals. Household penetration remains structurally important in rural United States markets beyond terrestrial broadband reach.
Mature deployment sits with Transponder Leasing. Newer deployment is concentrated in Managed Services.
Application:
End-use requirements shape frequency band selection and orbital architecture decisions.
- Telecommunications:Backhaul and trunking services connecting terrestrial networks across geographic gaps. Ka-band capacity is climbing fastest for this segment as mobile operators densify rural coverage.
- Broadcasting:Video distribution to cable headends, terrestrial transmitters, and direct-to-home platforms. C-band retains structural importance here despite FCC-mandated clearing timelines compressing available spectrum.
- Internet Access:Consumer and enterprise broadband delivery through very small aperture terminals. Demand is expanding most quickly in unserved regions where national connectivity programs direct government procurement.
- Government Services:Secure communications for defense, emergency response, and institutional networks. Dual-use procurement channels in Saudi Arabia and the United States favor operators with supply chain traceability certifications.
Established revenue sits with Broadcasting. Steepest expansion trajectory belongs to Internet Access.
End User:
Procurement sophistication and contract scale vary sharply across customer categories.
- Telecom Operators:Mobile and fixed-line carriers acquiring satellite backhaul for network extension. These customers are gaining share fastest as 5G rollout accelerates demand for rural site connectivity.
- Broadcasters:Television networks and content distributors requiring reliable video transmission. FCC C-band relocation timelines are forcing infrastructure reinvestment among United States incumbents.
- Enterprises:Energy, mining, and maritime companies operating remote sites and mobile assets. Systems integrators are capturing margin that previously accrued directly to satellite operators as these customers prioritize single-vendor accountability.
- Government Agencies:Civil and defense institutions with security-conditioned procurement requirements. EU Space Programme standards and REACH chemical restrictions are extending certification timelines for non-European suppliers.
Contract maturity sits with Broadcasters. Procurement transformation is concentrated among Enterprises.
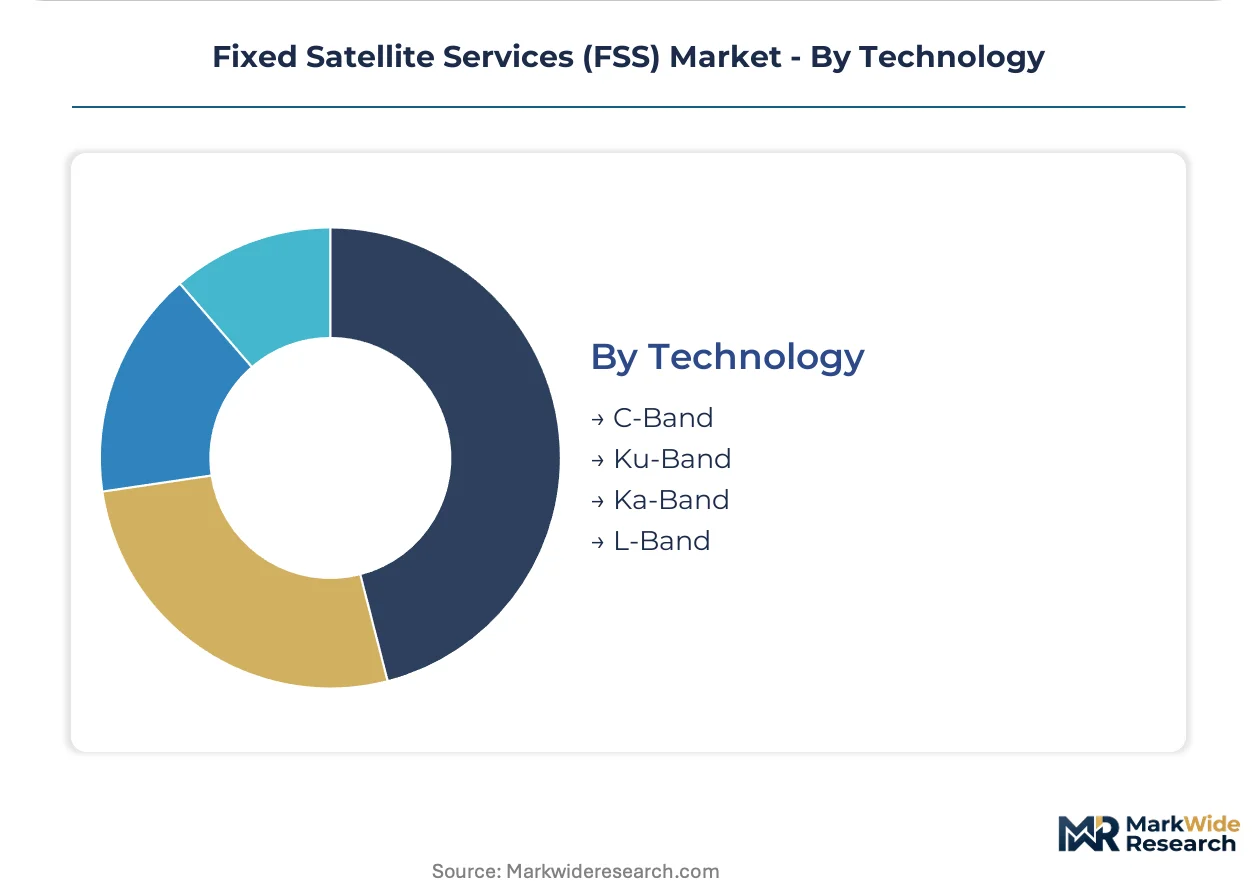
Technology:
Frequency band characteristics determine propagation performance, terminal economics, and regulatory exposure.
- C-Band:Lower frequencies with superior rain fade resistance and established ground infrastructure. Video distribution in the United States and Brazil depends on this spectrum despite FCC and national regulators reallocating portions for terrestrial 5G.
- Ku-Band:Mid-range frequencies balancing coverage footprint with terminal size. Enterprise very small aperture terminal networks across maritime and aviation applications favor this band for its proven ecosystem.
- Ka-Band:Higher frequencies enabling high-throughput spot beam architectures and smaller consumer terminals. Broadband and mobility applications are expanding most quickly here as high-throughput satellite constellations achieve scale.
- L-Band:Mobile satellite services for voice and narrowband data. Distinct from geostationary fixed services, this spectrum supports specialized government and emergency communications.
Legacy infrastructure sits with C-Band. Capacity growth is concentrated in Ka-Band.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fixed satellite capacity concentrates in operator headquarters nations while consumption spreads across maritime corridors and remote territories. The United States, Brazil, Saudi Arabia, Germany, and Japan anchor distinct demand patterns shaped by national connectivity programs and spectrum regulation.
United States
Maritime fleet digitization and rural broadband mandates pull Ka-band capacity through government procurement channels. The FCC governs C-band clearing timelines and relocation cost frameworks that reshape operator economics. Washington DC and El Segundo clusters host legacy operator headquarters managing orbital slot coordination.
Brazil
Amazon basin connectivity gaps and indigenous territory communications drive protected procurement channels for satellite backhaul. ANVISA and national telecom regulators carve spectrum allocations for non-terrestrial networks. São Paulo anchors systems integrator activity bundling satellite capacity for mining and energy verticals.
Saudi Arabia
National Transformation Program rural broadband mandates direct government procurement toward satellite backhaul for unserved governorates. SFDA and communications authority standards condition enterprise contract eligibility. Riyadh concentrates operator partnerships with domestic telecom carriers expanding coverage to remote governorates.
Germany
EU Space Programme security standards and REACH chemical restrictions extend certification timelines for payload suppliers seeking government contracts. ECHA and national space agency oversight conditions dual-use procurement access. Munich and Frankfurt clusters host ground segment engineering and network operations centers.
Japan
Maritime shipping lanes and aviation corridors through Asia-Pacific generate sustained Ka-band demand for vessel and aircraft connectivity. METI coordinates spectrum allocation with ITU filing requirements for regional orbital slots. Tokyo-Yokohama corridor concentrates satellite operator regional headquarters and maritime integrator partnerships.
Fixed Satellite Services (FSS) Market Key Industry Players
Top-tier vendors anchor integrated service portfolios, while mid-tier specialists concentrate on regional spectrum holdings and niche vertical applications. The vendor base stratifies across multi-orbit fleet operators, high-throughput satellite architects, and legacy geostationary incumbents navigating spectrum reallocation. Three archetypes dominate: full-service managed network providers, capacity wholesalers with software-defined payloads, and regional specialists leveraging protected orbital slots. Competitive moves concentrate on multi-orbit fleet integration and strategic partnerships with maritime and aviation integrators.
Within the multi-orbit service tier, SES S.A. and Viasat Inc. exemplify divergent technical strategies for enterprise and mobility markets. SES S.A. represents European-headquartered operators navigating EU regulatory frameworks, while Viasat Inc. anchors United States-based Ka-band architecture development. Intelsat occupies a position among legacy operators managing spectrum transition obligations and software-defined payload deployment.
| Leading Market Players |
|---|
| Hughes Network Systems |
| Inmarsat |
| SES S.A. |
| Yahsat |
| China Satcom |
| Viasat Inc. |
| Telesat |
| Intelsat |
| EUTELSAT S.A. |
| Others |
Cost & Logistics Intelligence
Maritime fleet operators and government procurement programs anchor pricing power for satellite operators, with long-term managed service contracts commanding premium rates over raw transponder leases while C-band clearing timelines compress spot-market availability.
Pricing Analysis
Price erosion across raw capacity tiers traces to terrestrial 5G encroachment in suburban corridors and software-defined payload deployment extending spacecraft service life without replacement launches. Three-tier pricing structure across premium managed services, standard bandwidth leases, and economy transponder contracts differentiates by service level guarantees and ground infrastructure bundling. Cost-down pressure on Ka-band broadband accelerates because high-throughput satellite constellations achieve manufacturing scale. Telecom operators in remote governorates exhibit highest price sensitivity, while defense agencies with security-conditioned procurement demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia's National Transformation Program and Brazil's indigenous territory communications carve-outs are reshaping ground station hardware sourcing toward local integrators. Satellite manufacturing concentrates in the United States, France, and Japan, with propulsion subsystem dependencies on Eastern European supply chains now disrupted by geopolitical friction. Launch services draw from Cape Canaveral, Kourou, and Tanegashima facilities, with single-source vulnerability in ride-share mission availability elevating per-kilogram payload economics. Distribution runs through maritime integrators in Tokyo-Yokohama and systems integrators in São Paulo bundling capacity for energy and mining verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital slot scarcity and spectrum reallocation timelines constrain deployable capacity, propping pricing power for cleared spectrum holders and multi-orbit fleet operators with coordinated ground infrastructure.
For Market Incumbents: Acquire software-defined payload capabilities and ground segment virtualization assets to defend against service unbundling by systems integrators capturing enterprise margin. Secure C-band clearing compensation frameworks to fund Ka-band capacity expansion. Deepen backward integration into phased array antenna design to offset RF engineering talent scarcity concentrating among defense contractors. For New Entrants and Emerging Players: AI-driven network orchestration platforms offer a technology-first wedge into maritime fleet digitization programs pulling annual managed service agreements. Target Brazil's Amazon connectivity gap where regulatory carve-outs protect non-terrestrial network procurement. Pursue direct-to-device partnerships with smartphone OEMs as the most penetrable consumer market entry vector. For Investors and Strategic Acquirers: The window for entry favors operators with multi-orbit fleet coordination and supply chain traceability certifications qualifying for EU Space Programme and Saudi government contracts. Long-term viability hinges on orbital slot holdings and software-defined payload deployment timelines. Watch FCC spectrum auction proceeds allocation as the signal indicating incumbent reinvestment capacity and competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Fleet Integration | SES S.A. leverages geostationary and medium-earth orbit assets to anchor premium enterprise contracts. |
| Software-Defined Payload Deployment | Intelsat extends spacecraft service flexibility without replacement launches amid C-band clearing timelines. |
| Direct-to-Device Partnership | Satellite operators unlock consumer messaging markets previously unreachable through traditional terminals. |
| Managed Services Bundling | Maritime integrators compress procurement cycles from five-year leases to annual agreements with SLA guarantees. |
| Ground Infrastructure Virtualization | Cloud-native architecture enables real-time capacity arbitrage across orbital regimes and spot-market pricing. |
Research Approach
Independent corroboration across satellite operator executives, maritime fleet technology officers, and government procurement directors underwrites the qualitative findings presented. Primary interviews with network operations managers at systems integrators, regulatory affairs leads at spectrum authorities, and ground segment engineers supplemented secondary validation from FCC spectrum auction records, ITU orbital slot filings, and national connectivity program procurement disclosures. Bottom-up capacity deployment tracking and top-down revenue aggregation triangulate market sizing across the analysis window.
Historical reference periods spanning pre-pandemic baseline through spectrum reallocation implementation anchor the forecast framework over the projection horizon. Segmentation dimensions modeled include service type, frequency band architecture, end-use application, and procurement channel structure. CAGRs derive from installed base evolution and replacement cycle timing. High-throughput satellite manufacturing scale and C-band clearing compensation disbursement schedules constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced constellation deployments, unforeseen launch failures, and regulatory acceleration of debris mitigation mandates. Forecasts reflect documented assumptions about spectrum coordination timelines and propulsion supply chain normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Maritime Satellite Communication Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Military Satellite Market
Satellite
Reconnaissance Satellite Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
United States Satellite Communications Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
Europe Satellite IoT Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Remote Sensing Satellite Market
Satellite
North America Satellite IoT Market
Satellite
Satellite Imaging Market
Satellite
Indonesia Satellite Communications Market
Satellite
Satellite Communication Equipment Market