
 Electric Propulsion Satellite Market | 2026-2036
Electric Propulsion Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Propulsion Satellite Market Analysis
Project finance and long-term satellite leasing arrangements are reshaping competitive entry in the electric propulsion satellite sector, allowing smaller operators to access high-performance Hall effect thrusters without full capital ownership. Northrop Grumman Corporation leverages its vertical integration across spacecraft bus manufacturing to sustain captive demand for in-house propulsion systems. Lockheed Martin Corporation anchors large government programs through specialized ion thruster production for deep space missions. Safran SA competes in the European supply chain with concentrated expertise in plasma-based propulsion subsystems.
Electric propulsion satellites utilize ionized propellant—typically xenon or krypton—accelerated through electrostatic or electromagnetic fields to generate thrust measured in millinewtons, enabling fuel-efficient orbital transfers and station-keeping over fifteen-plus year lifespans. Hall Effect Thrusters dominate commercial deployment due to their thrust-to-power ratio optimization for geostationary satellite repositioning. Communication Satellites represent the largest addressable application segment, though Deep Space Missions command premium pricing for specialized high-specific-impulse configurations.
FAA licensing requirements for commercial launch operations intersect with FCC orbital debris mitigation rules to shape propulsion system redundancy and end-of-life deorbit capabilities for U.S.-registered spacecraft. ESA's Clean Space initiative and REACH chemical restrictions constrain propellant selection and subsystem material composition across European supply chains. Stakeholders must monitor evolving ITU spectrum coordination timelines, as constellation deployment schedules directly determine electric propulsion procurement cycles and manufacturing capacity allocation.
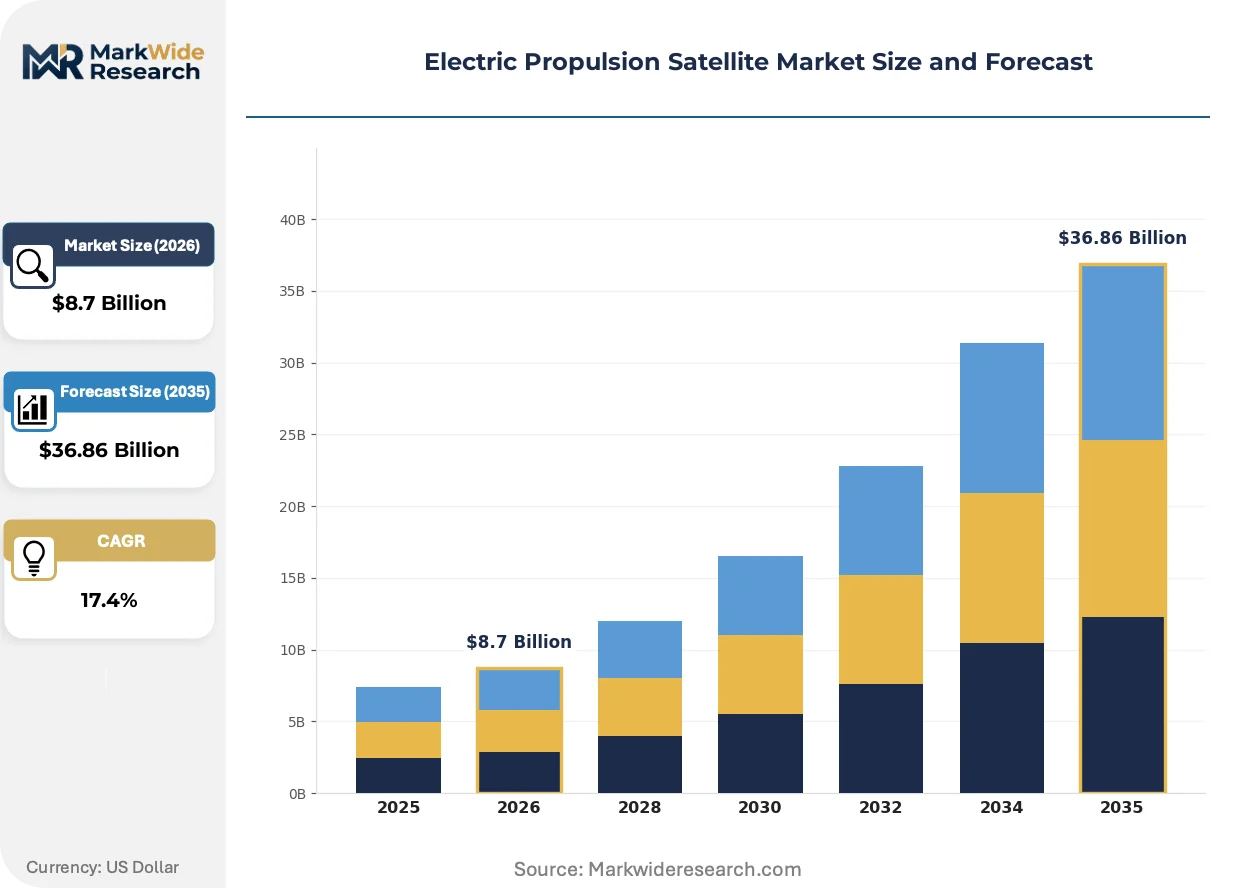
Market Dynamics
The shift from chemical to electric propulsion architectures is compressing satellite dry mass requirements while extending operational lifespans, fundamentally restructuring procurement economics for constellation operators and government programs alike.
Growth Catalysts
- FCC Orbital Debris Mitigation Rules:Mandated end-of-life deorbit capabilities and collision avoidance maneuvers increase demand for precision station-keeping thrusters on U.S.-registered spacecraft.
- LEO Constellation Deployment:Commercial broadband networks require hundreds of satellites with efficient orbital transfer capabilities, driving volume procurement of Hall effect thruster systems.
- Xenon Recovery and Recycling:Advances in closed-loop propellant processing reduce long-term operating costs for high-throughput electric propulsion platforms.
Market Restraints
- Xenon Supply Concentration:Rare gas extraction concentrates in Russia and Qatar, creating input cost volatility and geopolitical supply risk for thruster manufacturers.
- Hall Effect Thrust Density Limits:Millinewton-scale output constrains rapid orbital repositioning for time-sensitive military or emergency communications missions.
- ITU Spectrum Coordination Delays:International frequency allocation timelines extend constellation deployment schedules, deferring electric propulsion procurement commitments.
Strategic Opportunities
- India Constellation Programs:ISRO's commercial arm and private launch operators create untapped demand for cost-optimized electric propulsion on domestic and export satellites.
- Krypton Substitution:Lower atomic mass propellant alternatives enable reduced storage tank mass and simplified feed system architectures for small satellite platforms.
- Green Propulsion Mandates:ESA Clean Space initiative and REACH chemical restrictions accelerate plasma-based subsystem adoption across European supply chains.
Industry Challenges
- Plasma Physics Specialist Scarcity:Hall thruster design and testing requires rare expertise in computational plasma dynamics, constraining workforce expansion at subsystem suppliers.
- Qualification Timeline Compression:Rapid constellation deployment schedules conflict with traditional multi-year spaceflight heritage requirements for new thruster designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Propulsion Satellite Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ion Thrusters, Hall Effect Thrusters, Electrospray Thrusters, Arcjet Thrusters Application: Communication Satellites, Earth Observation Satellites, Deep Space Missions, Scientific Satellites End User: Government Agencies, Commercial Operators, Research Institutions, Military Organizations Deployment: On-Orbit Propulsion, Satellite Maneuvering, Orbital Transfer, Attitude Control |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, Thales Alenia Space, The Boeing Company, Airbus, Safran SA, L3Harris Technologies, Inc., OHB S.E., Aerojet Rocketdyne Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Propulsion Satellite Market Emerging Trajectories
Propulsion system architectures are converging with satellite bus manufacturing processes, blurring traditional boundaries between subsystem suppliers and prime contractors while enabling mass production economics previously unattainable in space hardware.
Hall effect thruster technology is hybridizing with chemical propulsion modules to create dual-mode systems that combine high-thrust chemical burns for rapid orbit raising with electric efficiency for long-duration station-keeping. LEO constellation operators are adopting these integrated packages to minimize time-to-revenue while maximizing operational lifespan. The approach is compressing supplier margins on standalone electric thrusters while expanding total addressable spend per spacecraft.
REACH chemical restrictions and ESA Clean Space guidelines are constraining propellant selection and subsystem material composition across European manufacturing chains. Suppliers must reformulate cathode assemblies and replace heritage coatings to maintain market access. Small satellite integrators in Germany and France face accelerated compliance timelines as constellation deployment schedules tighten.
Long-term satellite leasing and propulsion-as-a-service contracts are displacing traditional capital purchase models among commercial operators. Finance providers now bundle thruster performance guarantees with orbital slot access, transferring technical risk to subsystem vendors. This restructuring concentrates most visibly in U.S. constellation programs where Space Force and commercial buyers prioritize operational availability over hardware ownership.
Electric Propulsion Satellite Market Segmentation
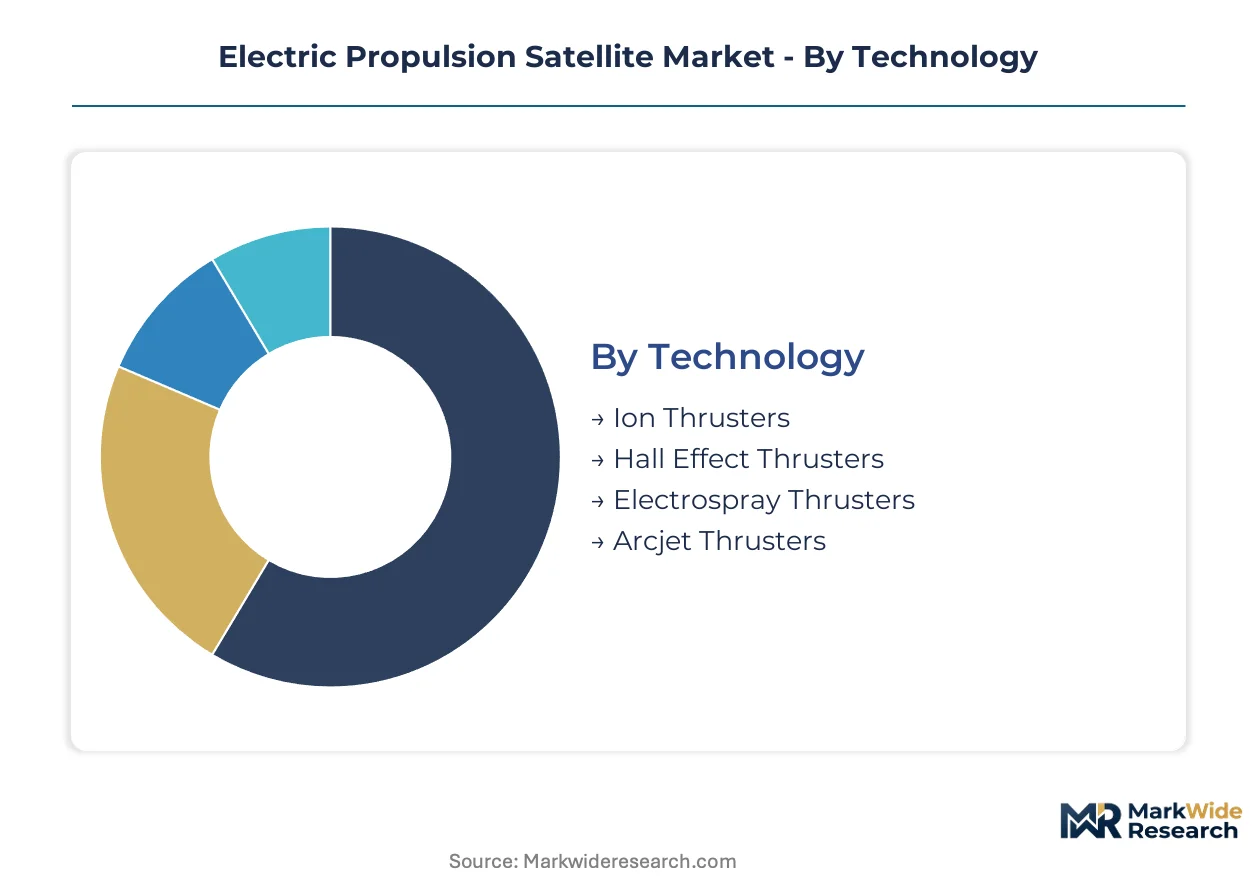
Segmentation in electric propulsion satellites reveals how thruster technology selection, orbital mission requirements, and procurement authority interact to determine subsystem specifications and supplier economics. Each dimension carries distinct engineering constraints and contracting patterns that shape manufacturing capacity allocation across the value chain.
Technology:
Cost tier differentiation separates heritage-qualified systems from emerging alternatives competing on specific impulse and propellant efficiency.
- Hall Effect Thrusters:These devices accelerate ions using crossed electric and magnetic fields, achieving thrust-to-power ratios optimized for geostationary station-keeping. Commercial operators in the United States specify Hall thrusters for LEO constellations requiring efficient orbital raising and repositioning capabilities.
- Ion Thrusters:Electrostatic acceleration of xenon ions delivers the highest specific impulse among flight-proven electric propulsion technologies. NASA deep space missions and ESA interplanetary probes anchor demand for gridded ion thruster systems despite extended qualification timelines.
- Electrospray Thrusters:Field emission of ionic liquids enables miniature thrust generation for CubeSat attitude control. Research institutions and emerging small satellite integrators drive prototype-to-flight transitions for this lower-maturity technology.
- Arcjet Thrusters:Resistive heating of hydrazine or ammonia propellant produces moderate specific impulse with simpler power processing units. Military organizations specify arcjet systems for missions requiring rapid thrust response unavailable from electrostatic alternatives.
Hall Effect Thrusters hold installed capacity. Ion Thrusters is rotating up the share rankings in deep space applications.
Application:
Application segmentation maps mission duration, orbital environment, and payload mass to thruster duty cycle requirements and redundancy specifications.
- Communication Satellites:Geostationary platforms require continuous station-keeping over fifteen-plus year lifespans with minimal propellant expenditure. Commercial operators prioritize Hall thruster configurations that maximize transponder revenue per kilogram of launch mass.
- Deep Space Missions:Interplanetary trajectories demand extremely high specific impulse for gravity assist maneuvers and extended cruise phases. Government agencies procure specialized ion thruster systems with multi-decade operational heritage for flagship science missions.
- Earth Observation Satellites:Sun-synchronous orbit maintenance and constellation phasing require moderate thrust precision. Commercial remote sensing operators balance electric propulsion mass savings against rapid revisit time requirements.
- Scientific Satellites:Formation flying and drag compensation missions utilize micro-newton precision thrusters. Research institutions specify custom propulsion architectures for technology demonstration and fundamental physics experiments.
Communication Satellites command procurement volume concentration. Deep Space Missions is climbing the fastest on a value-per-unit basis.
End User:
Customer type determines contracting structure, technical specification authority, and acceptable heritage requirements for thruster qualification.
- Government Agencies:NASA and ESA programs fund technology development and flight demonstration with multi-year procurement cycles. These buyers mandate extensive ground testing and on-orbit validation before operational deployment.
- Commercial Operators:Constellation developers prioritize rapid production scale and cost reduction over individual unit heritage. SpaceX and Amazon's Project Kuiper negotiate volume pricing with thruster suppliers for hundred-plus unit commitments.
- Research Institutions:University and laboratory missions accept higher technical risk for access to novel propulsion concepts. These end users drive electrospray and iodine-based thruster maturation through hosted payload opportunities.
- Military Organizations:The United States Space Force and allied defense agencies require radiation-hardened systems with rapid maneuver capability. Classified mission profiles demand domestic supply chain provenance and anti-tamper manufacturing controls.
Government Agencies hold installed capacity. Commercial Operators is gaining share fastest through constellation deployment acceleration.
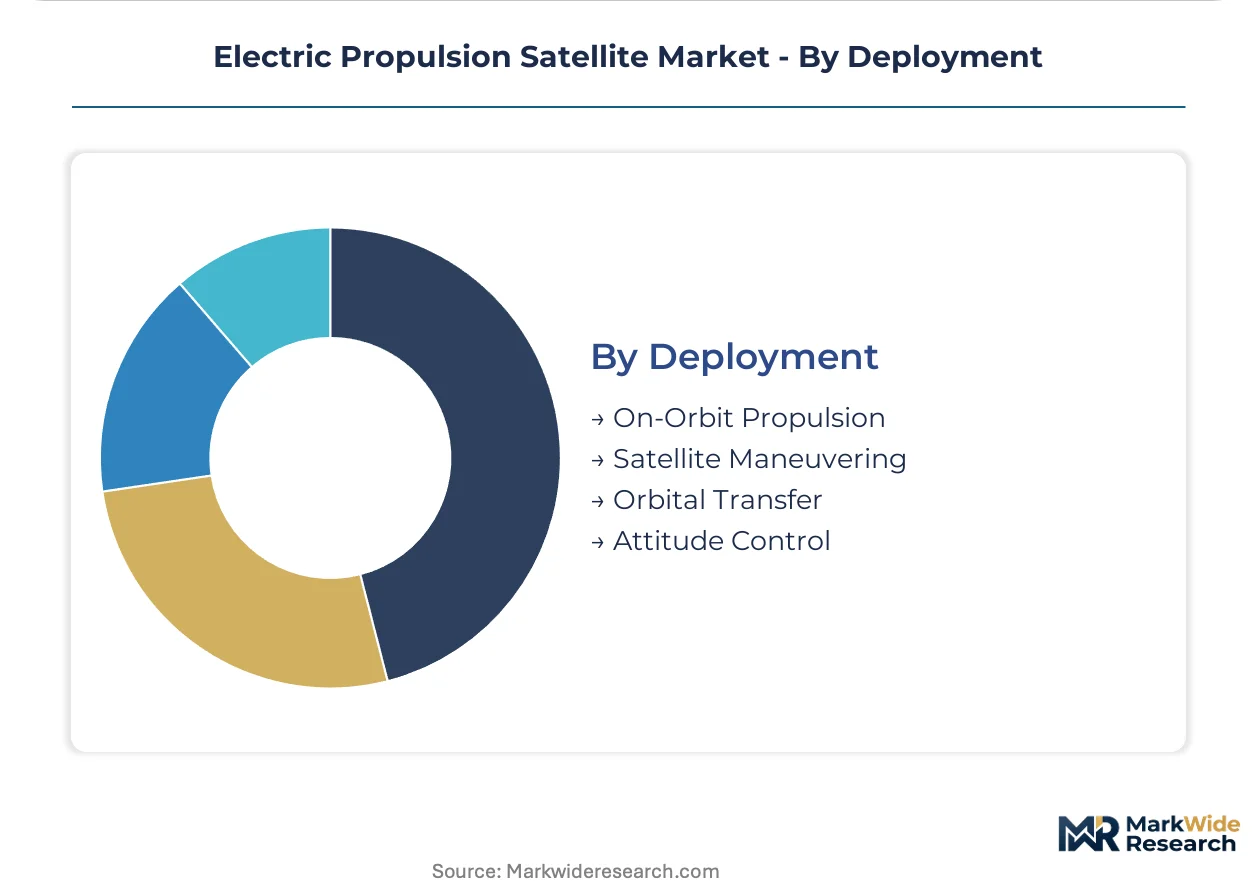
Deployment:
Functional role within the spacecraft mission profile determines thrust magnitude, duty cycle, and failure mode tolerance specifications.
- Orbital Transfer:Low-thrust spiral trajectories from deployment orbit to operational altitude maximize payload mass fraction. Commercial broadband constellations specify electric propulsion for this phase to reduce launch vehicle requirements.
- On-Orbit Propulsion:Station-keeping and collision avoidance maneuvers demand high reliability over extended operational lifespans. Geostationary satellite operators contract for propulsion system availability guarantees spanning fifteen years or more.
- Satellite Maneuvering:Constellation phasing and plane change operations require predictable thrust vectoring. LEO operators schedule these maneuvers during off-peak hours to minimize service interruption.
- Attitude Control:Precision pointing and momentum management utilize dedicated thruster clusters or shared propulsion resources. Small satellite platforms increasingly integrate attitude and orbit control functions to reduce subsystem count.
On-Orbit Propulsion holds installed capacity. Orbital Transfer is expanding most quickly with LEO constellation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement channels while European suppliers absorb compliance cost premiums from REACH chemical restrictions. This asymmetry shapes manufacturing location decisions and thruster qualification strategies across supplier networks.
United States
Space Force constellation programs and commercial broadband deployments anchor procurement volume for Hall effect thruster systems. FCC orbital debris mitigation rules mandate end-of-life deorbit capabilities, embedding propulsion redundancy requirements into spacecraft specifications. Los Angeles aerospace clusters concentrate prime contractor engineering resources alongside thruster subsystem suppliers.
Germany
Small satellite integrators in Bavaria and Baden-Württemberg drive demand for krypton-compatible thruster miniaturization. ESA Clean Space initiative constraints on propellant selection accelerate plasma-based subsystem reformulation across domestic supply chains. Munich-area research institutions anchor electrospray thruster maturation through hosted payload partnerships.
France
ArianeGroup launch economics and geostationary satellite manufacturing sustain demand for high-specific-impulse ion thruster configurations. REACH chemical restrictions constrain cathode assembly material selection, forcing coating replacement in heritage designs. Toulouse aerospace clusters concentrate plasma physics specialist expertise for next-generation thruster development.
Japan
METI-funded technology demonstration missions and commercial Earth observation constellations expand electric propulsion adoption beyond traditional government science programs. Domestic rare gas procurement constraints drive interest in iodine-based propellant alternatives. Nagoya-area industrial clusters integrate thruster manufacturing with precision spacecraft component supply chains.
India
ISRO's commercial arm and emerging private launch operators create procurement scale for cost-optimized Hall thruster configurations. BIS certification requirements for space-grade subsystems shape supplier qualification timelines for domestic and export markets. Bengaluru aerospace clusters concentrate satellite integration capabilities alongside propulsion subsystem engineering resources.
Electric Propulsion Satellite Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower margin capture. The supplier base organizes into three tiers: prime contractors with captive propulsion divisions, independent thruster manufacturers, and materials/precision component suppliers. Consolidation pressures concentrate among mid-scale thruster specialists facing constellation volume demands. Competitive moves center on backward integration into propellant processing and strategic partnerships with launch service providers.
Within the vertically integrated tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify platform manufacturers with captive propulsion capabilities. Safran SA occupies a position among European specialists concentrated in plasma-based subsystem supply. These three anchors represent divergent strategic postures: domestic prime contractor control, government program anchoring, and regional supply chain concentration.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Thales Alenia Space |
| The Boeing Company |
| Airbus |
| Safran SA |
| L3Harris Technologies, Inc. |
| OHB S.E. |
| Aerojet Rocketdyne Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Xenon supply concentration in Russia and Qatar generates input cost volatility that compresses margin spreads between heritage-qualified Hall thrusters and emerging krypton alternatives while forcing constellation operators toward long-term propellant offtake contracts.
Pricing Analysis
Commercial constellation operators anchor a contract-based long-term offtake pricing structure where volume scale and flight heritage duration determine tier placement. Price differentiation rests on NASA/ESA qualification status and vertical integration depth, with unqualified systems facing severe cost compression as LEO deployment accelerates. Government agencies show least price sensitivity due to mission-critical redundancy requirements, while emerging small satellite integrators drive aggressive procurement negotiations.
Supply Chain Analysis
Specialized foundries in the United States, France, and Germany hold captive capacity for Hall thruster discharge channel manufacturing and magnetic circuit assembly. The supply chain draws from xenon and krypton extraction facilities, precision ceramic suppliers, and radiation-hardened power processing unit fabricators. Single-source vulnerability concentrates in Russian rare gas export channels. Distribution runs through prime contractor integration facilities with limited direct subsystem procurement by end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
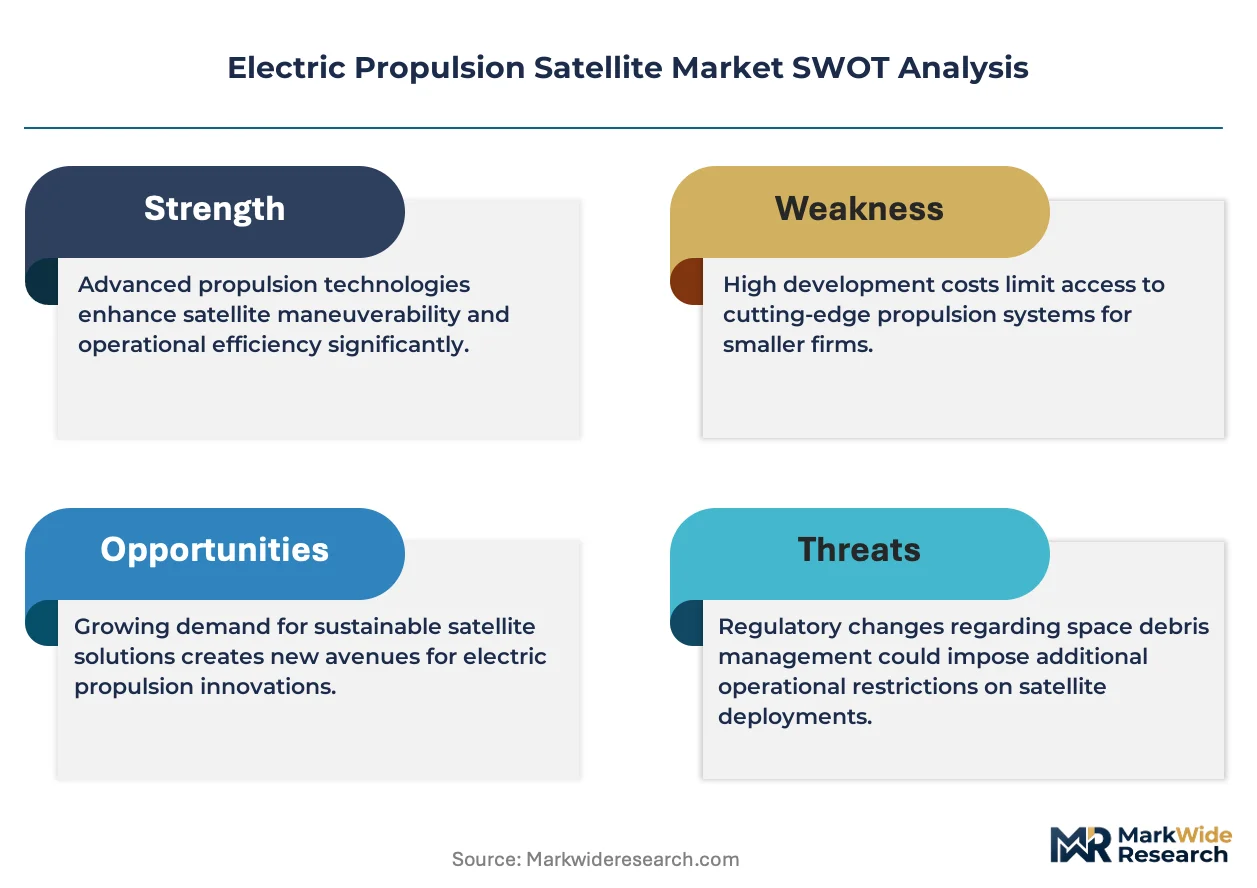
Technology fragmentation between heritage ion thrusters, commercial Hall systems, and emerging electrospray architectures creates specialized supplier niches as constellation operators diversify propulsion risk across multiple qualified vendors.
For Market Incumbents: Build captive propellant processing capabilities to lock in supply security against Russian export disruption. Northrop Grumman and Lockheed Martin should deepen in-house production of cathode assemblies and power processing units to defend margin position from emerging krypton-specialist entrants. ESA Clean Space compliance investments represent a critical certification lever for European market retention. For New Entrants and Emerging Players: Small satellite integrators in India and Japan represent the most penetrable entry point for cost-optimized krypton-compatible thruster configurations. ISRO's commercial procurement expansion and METI-funded technology demonstration missions offer qualified reference opportunities without heritage barriers. A propulsion-as-a-service go-to-market model transfers technical risk while accelerating customer acquisition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale thruster specialists with plasma physics workforce depth and constellation volume contracts. Long-term viability hinges on dual-mode chemical-electric system capabilities spanning rapid orbit raising and station-keeping. Watch for krypton substitution rate acceleration as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Processing | Lockheed Martin's captive xenon recycling reduces Russian supply exposure for Space Force missions. |
| Krypton-Compatible Thruster Development | Safran's plasma subsystem reformulation addresses REACH restrictions while lowering tank mass for Airbus small satellites. |
| Dual-Mode Propulsion System Integration | Thales Alenia Space hybrid packages compress time-to-revenue for Amazon Project Kuiper orbital deployment. |
| Plasma Physics Specialist Acquisition | L3Harris workforce expansion targets computational dynamics expertise for next-generation Hall thruster scaling. |
| Long-Term Propulsion-as-a-Service Contracts | Finance providers bundle Boeing thruster guarantees with orbital slot access for commercial operator risk transfer. |
Methodological Framework
Initial hypotheses were tested against primary input from satellite bus engineering directors, constellation program procurement leads, plasma physics research faculty, and FCC licensing specialists and refined through secondary validation against NASA mission databases, ESA Clean Space technical reports, FCC orbital debris mitigation filings, and customs trade data for rare gas imports. Bottom-up unit economics for thruster production and top-down constellation deployment schedules were triangulated to anchor market sizing.
Demand-supply balance across the analysis window integrated technology segmentation by thruster type, application mission profile, end-user contracting structure, and regional regulatory framework. CAGRs were derived from production capacity expansion announcements and procurement pipeline visibility. Forecast inputs incorporated ITU spectrum coordination timelines and Space Force budget authorization patterns without year-specific assumptions.
Practitioners should monitor xenon price volatility, REACH chemical restriction expansion, and constellation bankruptcy filings for early signals of forecast revision. Quarterly review of propellant spot markets and ITU filing acceleration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Satellite Signal Meter Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Optical Satellite Communication Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
North America Military Satellite Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Europe Satellite Connectivity Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
US Satellite Connectivity Market