
 Vehicle Mounted Satellite Communication Station Market | 2026-2036
Vehicle Mounted Satellite Communication Station Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Mounted Satellite Communication Station Market Insights
Software-defined radio architectures paired with electronically steerable flat-panel antennas is rewriting how vehicle mounted terminals achieve acquisition speed and multi-orbit handoff. Thales Group leverages its European defense electronics heritage to anchor high-assurance military contracts across France and neighboring states. L3Harris Technologies, Inc. sustains engineering intensity in ruggedized waveform processing, while Viasat Inc. competes on broadband throughput density for mobile platforms. Iridium Communications Inc. differentiates through persistent L-band coverage that dominates polar and oceanic routes where geostationary links falter.
A vehicle mounted satellite communication station integrates a stabilized antenna subsystem, RF transceiver chain, and modem/router assembly onto a mobile platform to establish two-way broadband links with geostationary, medium-earth, or low-earth orbit constellations. Terminal specifications typically span 0.6-meter to 2.4-meter reflector diameters or flat-panel equivalents, with transmit power ranging from 4W to 200W depending on orbital target and data rate requirements. Ku-Band terminals retain the largest installed base due to mature space segment availability and balanced rain-fade performance, though Ka-Band configurations are gaining share where high-throughput satellites deliver concentrated spot beams. Defense Forces represent the deepest margin pool given classified waveform requirements and multi-year program structures, while Emergency Responders constitute the fastest-growing end user category as civil agencies replicate military interoperability standards.
The Federal Communications Commission governs commercial terminal type acceptance and orbital slot coordination within the United States, while the European Telecommunications Standards Institute publishes harmonized EN norms that shape CE marking paths for cross-border European procurement. Military operators face additional National Security Agency and NATO STANAG encryption mandates that filter vendor eligibility and sustain premium pricing for certified suppliers. Stakeholders must monitor spectrum reallocation proceedings and emerging low-earth orbit constellation interoperability standards to preserve platform relevance across evolving space segment architectures.
Market Dynamics
Electronically steerable flat-panel antennas are compressing acquisition timelines from minutes to seconds while collapsing the physical footprint of vehicle-mounted terminals, forcing incumbent reflector manufacturers to retool production lines or cede tactical vehicle contracts.
Growth Catalysts
- FCC Ka-Band Certification Acceleration:The Federal Communications Commission's streamlined type-approval pathways for commercial Ka-band terminals are compressing vendor entry timelines and expanding certified supplier pools for expeditionary platforms.
- NATO STANAG Interoperability Mandates:Allied defense procurement offices are requiring waveform compatibility across member-state vehicle fleets, creating multi-year program visibility for certified subsystem vendors.
- Software-Defined Radio Architectures:Open-standard modem platforms are enabling single-terminal multi-orbit connectivity, reducing spare-part logistics burdens for mobile command posts.
Market Restraints
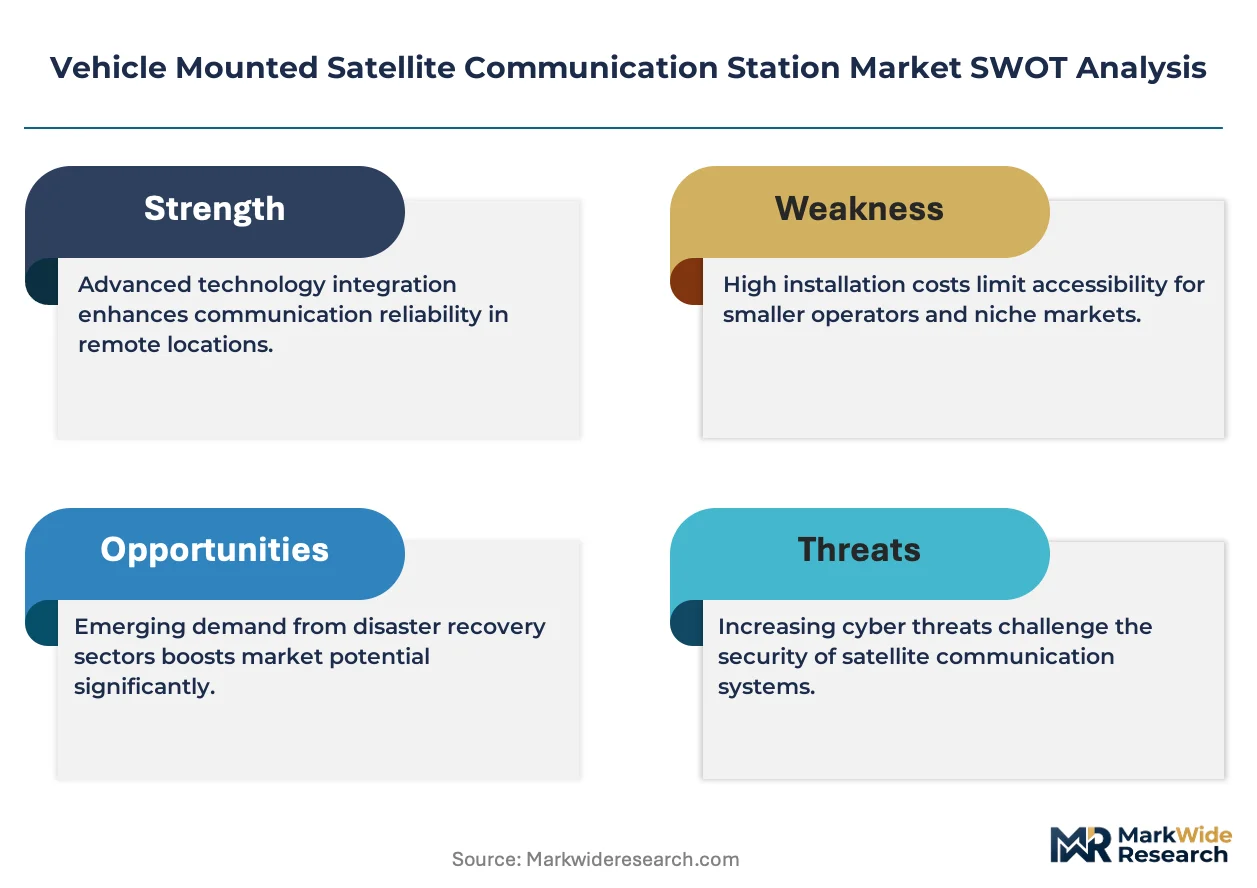
- Gallium Nitride Supply Concentration:High-power RF amplifier fabrication depends on specialized foundry capacity concentrated in East Asian manufacturing clusters, exposing lead-time volatility for ruggedized transmit chains.
- NSA Encryption Certification Bottlenecks:National Security Agency Type-1 certification timelines extend 18-24 months, filtering vendor eligibility and sustaining premium pricing tiers for incumbent suppliers.
- Geostationary Rain-Fade Limitations:Ku-band and Ka-band links experience service degradation above 50mm/hour precipitation rates, constraining all-weather reliability claims in tropical deployment zones.
Strategic Opportunities
- LEO Constellation Interoperability Standards:Emerging low-earth orbit handoff protocols are opening white space for dual-orbit terminals that bridge geostationary capacity with polar route coverage.
- Emergency Responder Civil Procurement:Federal Emergency Management Agency interoperability grants are replicating military waveform standards for state-level mobile command vehicles.
- Flat-Panel Manufacturing Scale Economics:Consumer aviation terminal demand is driving printed circuit antenna substrate volumes that vehicle-mounted suppliers can leverage for cost-down trajectories.
Industry Challenges
- RF Engineer Talent Scarcity:Phased-array calibration and thermal management expertise concentrates in defense-aerospace labor pools, constraining hiring velocity for commercial terminal divisions.
- Multi-Orbit Integration Complexity:Modem firmware must simultaneously track geostationary, medium-earth, and low-earth orbit ephemeris data, expanding software validation matrices and field-test requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Mounted Satellite Communication Station Market |
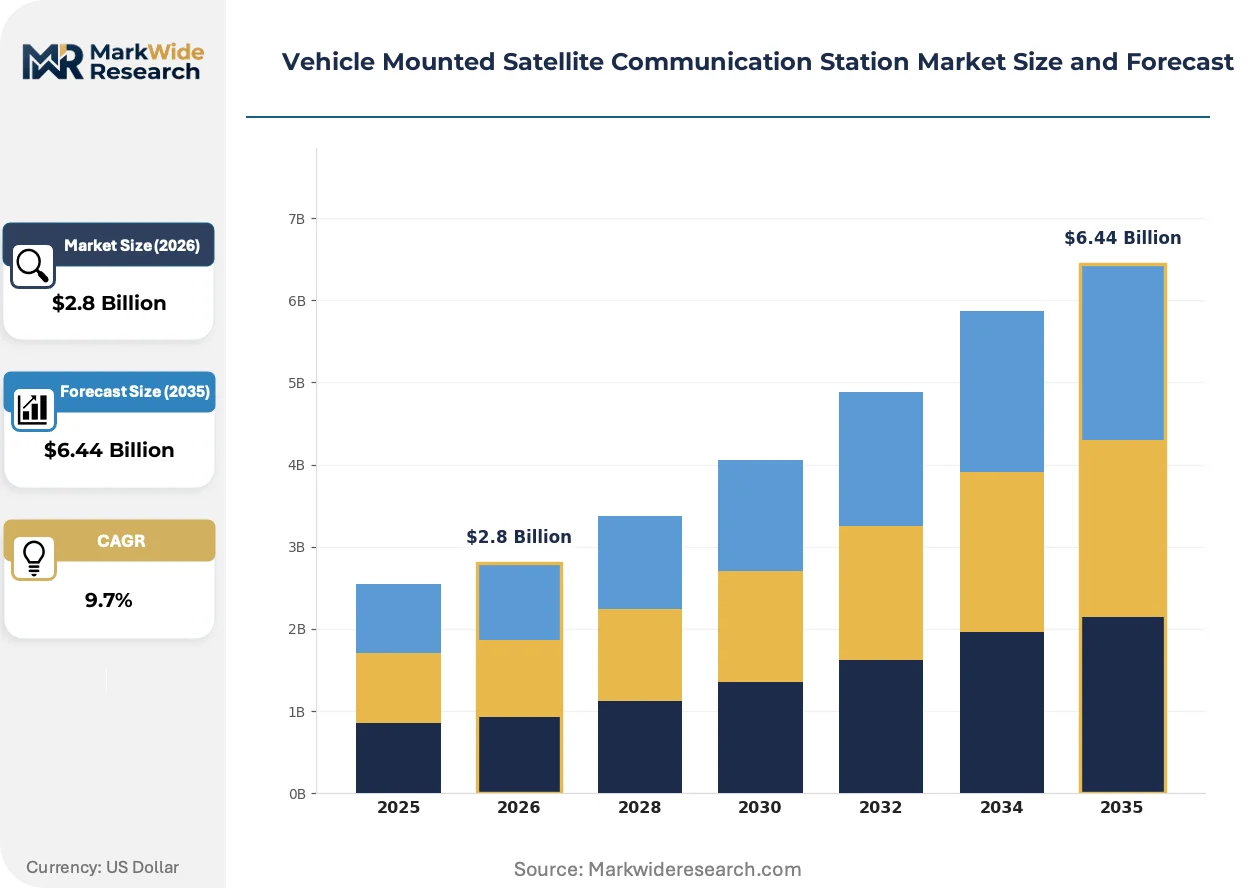
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Mounted, Portable, Mobile Truck, Trailer Based, Airborne Technology: Ka-Band, Ku-Band, X-Band, C-Band, S-Band End User: Defense Forces, Emergency Responders, Media Broadcasters, Telecommunications Operators, Scientific Research Organizations Deployment Mode: Land, Maritime, Aerial, Remote Expedition Sites |
| Companies Covered | Garmin Ltd., Iridium Communications Inc., Globalstar Inc., Cobham SATCOM, Inmarsat Global Limited, Thales Group, L3Harris Technologies, Inc., Viasat Inc., Hughes Network Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Mounted Satellite Communication Station Market Trends and Innovations
Vehicle-mounted SATCOM terminals are transitioning from single-orbit, single-frequency hardware stacks toward software-reconfigurable multi-orbit platforms. This architectural pivot is compressing vendor differentiation timelines and reshaping procurement evaluation criteria.
Phased-array antenna electronics is virtualizing the RF front-end by replacing mechanical gimbals with solid-state beam steering. Marine Corps expeditionary units are field-testing these configurations for rapid acquisition in contested electromagnetic environments. The technology is virtualizing the traditional stabilized pedestal supply chain, compressing vendor margins on mechanical subassemblies.
The European Telecommunications Standards Institute's harmonized EN 303 980 framework is mandating uniform electromagnetic compatibility testing across member states. Terminal manufacturers must now design for a single CE marking pathway rather than country-specific approvals. Ka-band flat-panel configurations face the steepest compliance redesign burden given their higher power density and spurious emission profiles.
Defense procurement offices are unbundling terminal hardware from long-term service contracts, shifting risk to vendors for waveform software updates and encryption key management. This disintermediation is compressing recurring revenue streams for traditional integrators. United States Army Program Executive Office Command, Control, Communications-Tactical is piloting this model for armored vehicle SATCOM modernization tranches.
Vehicle Mounted Satellite Communication Station Market Segmentation
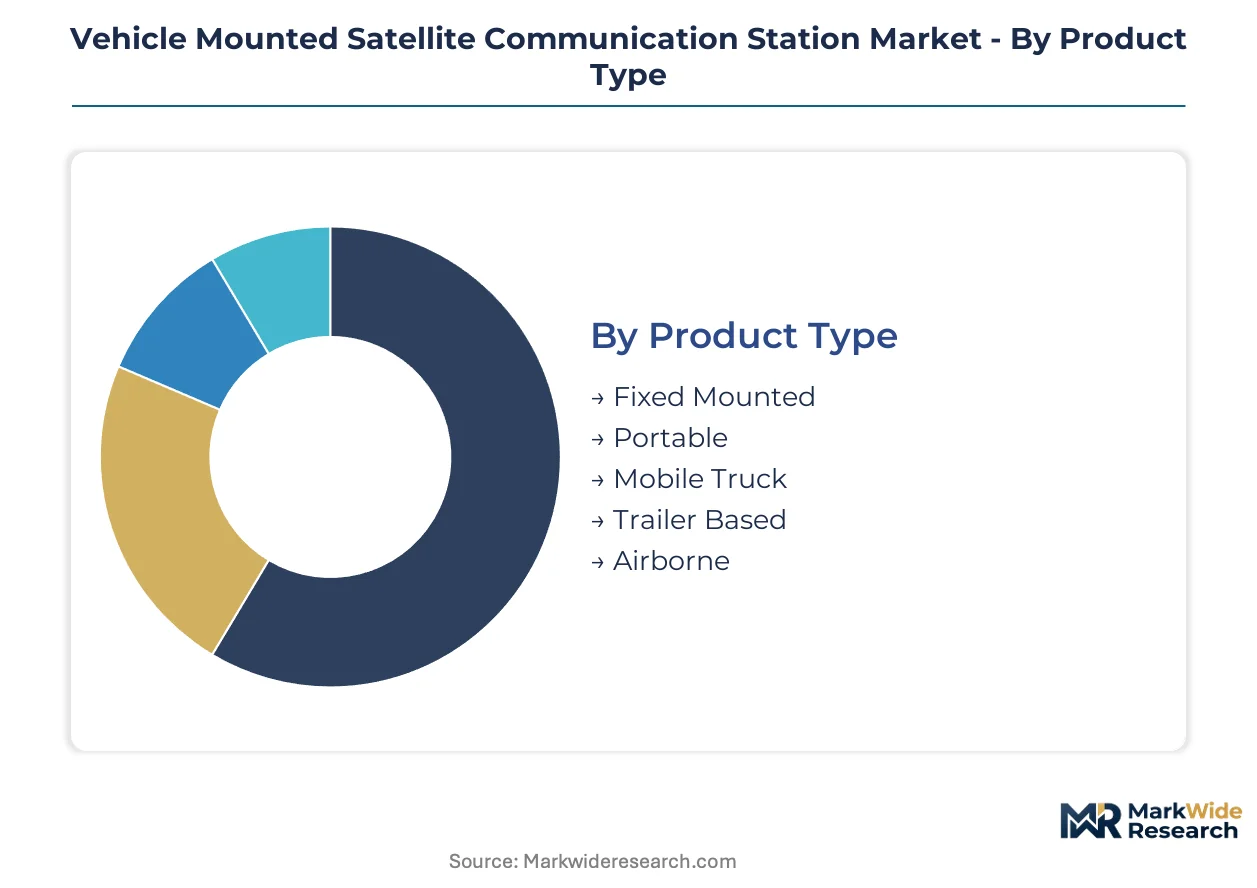
Vehicle-mounted SATCOM procurement splits across terminal mobility classes, frequency bands, and mission profiles. Each dimension shapes antenna stabilization requirements, RF power budgets, and waveform certification paths differently.
Product Type:
Mobility tier determines integration complexity, from permanently installed units to rapidly deployable expeditionary configurations.
- Fixed Mounted:Permanently integrated terminals with stabilized pedestals bolted to vehicle chassis. Defense Forces in the United States anchor procurement through Army and Marine Corps armored vehicle modernization programs demanding hardened electromagnetic protection.
- Portable:Man-packable terminals under 25kg for dismounted operations. Emergency Responders in California and Florida are standardizing these for wildfire and hurricane mobile command centers requiring rapid site establishment.
- Mobile Truck:Transit-case terminals rack-mounted in tactical vehicles. Commercial broadcasters deploy these for live event coverage where Ku-band satellite trucks require quick frequency coordination.
- Trailer Based:Self-contained systems on towable platforms with onboard power generation. Scientific Research Organizations in Alaska and Antarctica leverage these for polar expedition connectivity where infrastructure is absent.
- Airborne:Terminals certified for rotary-wing and fixed-wing platforms. Special operations aviation units drive demand for low-drag flat-panel configurations.
Fixed Mounted holds installed capacity. Portable is rotating up the share rankings.
Technology:
Frequency band selection trades throughput density against atmospheric resilience and spectrum licensing costs.
- Ka-Band:High-throughput spot beams deliver broadband density above 10 Mbps in compact apertures. The FCC's streamlined type-approval pathways are accelerating vendor certification for commercial expeditionary platforms.
- Ku-Band:Mature space segment availability and balanced rain-fade performance sustain the largest installed base. Telecommunications Operators in rural Texas and Montana specify these for backhaul resilience where fiber is uneconomical.
- X-Band:Military-allocated spectrum with inherent interference protection. Defense Forces require NSA Type-1 certified modems that filter vendor eligibility to a handful of cleared suppliers.
- C-Band:Lower frequency allocation with superior rain penetration. Maritime deployment modes favor these for all-weather reliability in tropical precipitation zones.
- S-Band:Narrowband voice and low-data messaging. Emergency Responders replicate military interoperability standards for resilient narrowband backup when broadband fails.
Ku-Band holds installed capacity. Ka-Band is climbing the fastest.
End User:
Customer type shapes margin structure through certification requirements, contract duration, and waveform classification levels.
- Defense Forces:Classified waveform requirements and multi-year program structures command premium pricing. NATO STANAG interoperability mandates are creating multi-year visibility for certified subsystem vendors across member states.
- Emergency Responders:Federal Emergency Management Agency interoperability grants are replicating military standards. State-level mobile command vehicle procurement in Texas, Florida, and California is expanding fastest.
- Media Broadcasters:Uncompressed video backhaul demands low-latency Ka-band links. Live sports and election coverage drive peak demand for rapid-deployment truck terminals.
- Telecommunications Operators:Network restoration and rural backhaul applications. Cellular infrastructure hardening programs in hurricane-prone coastal zones are standardizing vehicle-mounted backup.
- Scientific Research Organizations:Polar and oceanic route coverage where geostationary links falter. L-band persistence from low-earth orbit constellations dominates this niche.
Defense Forces hold installed capacity. Emergency Responders is rotating up the share rankings.
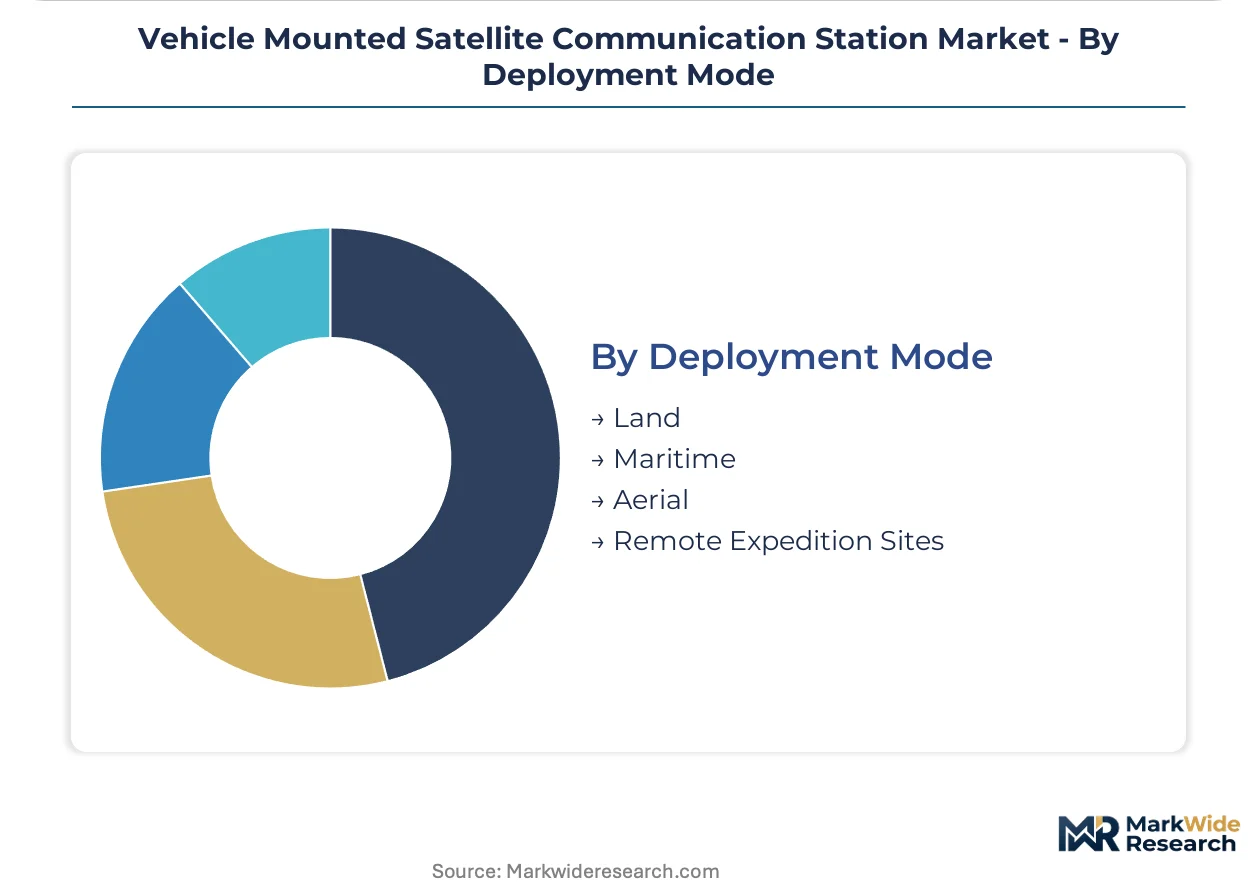
Deployment Mode:
Operational environment dictates antenna stabilization performance, environmental sealing, and platform integration standards.
- Land:Ground vehicle integration dominates procurement volume. The Army Program Executive Office Command, Control, Communications-Tactical pilots hardware-service unbundling for armored vehicle modernization.
- Maritime:Shipboard and small-craft terminals require gyro-stabilized pedestals. Ka-band flat-panels face steep compliance redesign for salt-spray and vibration profiles.
- Aerial:Rotary-wing platforms demand low-drag conformal antennas. Marine Corps expeditionary units field-test phased-array configurations for rapid acquisition in contested electromagnetic environments.
- Remote Expedition Sites:Generator-dependent operations beyond grid infrastructure. Alaska and Antarctica scientific stations drive demand for trailer-based autonomous power systems.
Land holds installed capacity. Remote Expedition Sites is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German defense electronics exports flow into NATO procurement channels across France, Poland, and the Baltic states, establishing a trans-European supply corridor for tactical vehicle terminals.
United States
Army and Marine Corps modernization programs drive expeditionary network procurement through the Program Executive Office Command, Control, Communications-Tactical. The FCC's streamlined Ka-band type-approval pathways compress vendor entry timelines for commercial expeditionary platforms. Huntsville, Alabama anchors defense electronics manufacturing clusters where ruggedized terminal integration occurs.
Germany
Bundeswehr vehicle fleet upgrades prioritize NATO STANAG waveform interoperability for cross-border tactical connectivity. The European Telecommunications Standards Institute's EN 303 980 framework mandates uniform electromagnetic compatibility testing for CE marking. Munich-Stuttgart industrial corridors concentrate precision antenna fabrication for armored vehicle integration.
France
Direction Générale de l'Armement procurement emphasizes sovereign satellite communication capabilities for deployed forces. ANSM cybersecurity mandates filter vendor eligibility for classified military waveform deployments. Toulouse aerospace clusters host flat-panel antenna research programs for rapid satellite acquisition.
United Kingdom
Strategic Command's integrated operating concept drives mobile SATCOM requirements for expeditionary command vehicles. Ministry of Defence encryption certification timelines extend procurement cycles for Type-1 certified suppliers. Farnborough-Portsmouth defense technology corridors concentrate waveform processing engineering talent.
Japan
Ministry of Defense mobility enhancement initiatives prioritize vehicle-mounted terminals for southwestern island defense. METI industrial standards shape domestic supplier qualification for dual-use satellite communication equipment. Nagoya industrial zones manufacture stabilized antenna pedestals for maritime patrol vehicle integration.
Vehicle Mounted Satellite Communication Station Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers, producing a bifurcated structure where defense primes capture multi-year program contracts while component suppliers penetrate commercial expeditionary segments. The vendor base stratifies between waveform-certified integrators and antenna subsystem specialists. Two strategic archetypes dominate: vertically integrated defense electronics conglomerates and flat-panel technology disruptors. Competitive moves center on hardware-service contract unbundling and multi-orbit modem platform development.
Within the defense electronics tier, Thales Group and L3Harris Technologies, Inc. exemplify waveform-certified integrators anchoring NATO and United States military procurement channels. Viasat Inc. occupies a position bridging commercial broadband density with tactical platform requirements.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Iridium Communications Inc. |
| Globalstar Inc. |
| Cobham SATCOM |
| Inmarsat Global Limited |
| Thales Group |
| L3Harris Technologies, Inc. |
| Viasat Inc. |
| Hughes Network Systems LLC |
| Others |
Pricing and Supply Chain Analysis
Gallium Nitride foundry concentration in East Asian manufacturing clusters exposes terminal vendors to lead-time volatility that compresses margin buffers across premium and standard tiers while forcing dual-sourcing investments into supply chain architecture.
Pricing Analysis
Mechanical gimbal terminals carry 40-60 percent premiums over flat-panel equivalents due to legacy defense program amortization, while next-generation phased-array configurations command price premiums for rapid acquisition speed. Three-tier pricing structure across NSA Type-1 certified, NATO STANAG compliant, and commercial unclassified levels separates defense procurement from emergency responder segments. Cost compression in commercial Ka-band terminals is intensifying because FCC streamlined approval pathways expand certified supplier pools. Emergency responder agencies exhibit highest price sensitivity due to FEMA grant dependency, while defense programs demonstrate lowest sensitivity given classified waveform mandates.
Supply Chain Analysis
Tariff exposure between United States and China dominates RF amplifier sourcing decisions for terminal manufacturers serving federal procurement channels. High-power Gallium Nitride fabrication draws from Taiwan, Japan, and South Korea foundry networks, while precision antenna machining rests on German and Japanese industrial equipment bases. Single-source vulnerability concentrates in specialized phased-array calibration equipment tethered to defense-aerospace labor pools. Distribution runs through prime contractor integration facilities in Huntsville, Alabama and Munich-Stuttgart corridors before reaching end-user platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phased-array calibration expertise and NSA Type-1 certification infrastructure constitute scarce capabilities that gate vendor eligibility and sustain incumbent pricing power across defense procurement tiers.
For Market Incumbents: Build certification moats through accelerated NSA Type-1 and NATO STANAG waveform investments that filter competitor eligibility for multi-year defense programs. Flat-panel technology disruptors threaten mechanical gimbal incumbents with acquisition speed advantages; counter through backward integration into Gallium Nitride amplifier design to secure supply priority during foundry allocation cycles. For New Entrants and Emerging Players: Mid-market commercial Ka-band terminals for state-level emergency responder vehicles represent the most penetrable entry point given FEMA interoperability grant standardization and compressed FCC certification timelines. Target civil agencies replicating military waveform standards in Texas, Florida, and California mobile command centers. Pursue channel partnerships with vehicle integrators already serving defense prime subcontractors to bypass direct certification barriers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors flat-panel antenna specialists with software-defined radio platforms over legacy mechanical pedestal manufacturers. Long-term viability over the coming decade hinges on multi-orbit modem capabilities bridging geostationary and low-earth orbit constellations. Watch for LEO constellation interoperability standard finalization as the inflection signal triggering consolidation toward dual-orbit terminal vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Modem Platform Development | Software-defined architectures enable single-terminal connectivity across geostationary, medium-earth, and low-earth orbit constellations. |
| NSA Type-1 Certification Acceleration | Eighteen-month approval timelines filter vendor eligibility and sustain premium pricing tiers for cleared suppliers. |
| Flat-Panel Manufacturing Scale Partnerships | Consumer aviation terminal demand drives printed circuit antenna substrate volumes that reduce vehicle-mounted unit costs. |
| Hardware-Service Contract Unbundling | Army Program Executive Office C3T pilots shift risk to vendors for waveform updates and encryption key management. |
| Gallium Nitride Supply Diversification | Dual-sourcing investments into Taiwan and South Korea foundries mitigate lead-time volatility for ruggedized transmit chains. |
Research Methodology
Desk research of FCC terminal type-approval databases, NATO STANAG specification repositories, and defense procurement disclosure records preceded structured interviews with Army Program Executive Office C3T acquisition officers, Marine Corps Systems Command SATCOM program managers, commercial satellite operator network engineers, and flat-panel antenna subsystem engineering directors. Secondary validation drew from SEC 10-K filings of publicly traded terminal manufacturers, ETSI harmonized standard documentation, and customs trade data for RF component import flows. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Forecast assumptions held fixed the current FCC Ka-band regulatory framework and NATO STANAG interoperability mandate timelines while varying low-earth orbit constellation deployment schedules and Gallium Nitride foundry capacity expansion rates across the projection horizon. Segmentation modeling spanned terminal mobility class, frequency band, end-user mission profile, and regional procurement authority. CAGRs derived from logistic diffusion curves fitted to historical defense modernization program adoption patterns, with satellite capacity pricing trajectories and phased-array cost-down curves as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in defense budget sequestration scenarios or semiconductor equipment capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding constellation interoperability standard ratification and encryption certification backlog clearance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Operation Service Market
Satellite
North America Satellite Manufacturing Market
Satellite
Military Satellite Market
Satellite
United Kingdom Satellite Communications Market
Satellite
North America Mobile Satellite Services Market
Satellite
Earth Observation Satellite Market
Satellite
Satellite Photography Service Market
Satellite
Spain Satellite Imagery Services Market
Satellite
LEO and GEO Satellite Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
France Satellite Imagery Services Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Global Satellite Modem Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
M2M Satellite Communication Market
Satellite
Eastern Europe and North Africa Satellite Communication Market