
 Urban Autonomous Air Mobility Market | 2026-2036
Urban Autonomous Air Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Autonomous Air Mobility Market Analysis
Certified commercial-grade autonomy standards are reorganizing competitive hierarchies in urban air mobility. Joby Aviation leverages extensive flight-test data accumulation to sustain FAA certification momentum. EHang Holdings anchors commercial deployment through operational permits in multiple Asian jurisdictions. Volocopter GmbH differentiates via targeted European city partnerships for integrated vertiport networks.
Urban autonomous air mobility comprises pilotless electric vertical take-off and landing (eVTOL) aircraft operating within controlled low-altitude corridors, typically below 500 meters, utilizing distributed electric propulsion with redundancy margins exceeding single-point-of-failure thresholds for passenger safety. These vehicles serve on-demand intra-urban transit, medical logistics, and emergency response missions where ground infrastructure congestion limits conventional service velocity. eVTOL configurations currently lead development investment, while hybrid architectures capture interest for extended-range cargo routes. Navigation systems represent the fastest-growing technology segment as detect-and-avoid algorithms mature for uncrewed operations. Passenger transport applications concentrate margin pools through premium pricing on high-density corridors.
FAA, EASA, and CAAC collectively shape market access through divergent airworthiness certification timelines and operational approval frameworks. FAA Part 135 adaptations and EASA SC-VTOL special conditions directly determine which vehicle designs achieve commercial service entry. Stakeholders must monitor regulatory harmonization progress between jurisdictions to align fleet deployment strategies with certification reciprocity developments.
Market Dynamics
Certification reciprocity negotiations between FAA, EASA, and CAAC are compressing commercial entry timelines while fragmenting fleet deployment strategies across jurisdictions with divergent airworthiness validation requirements.
Growth Catalysts
- FAA Part 135 Adaptations:Operational certification pathways for autonomous passenger transport are accelerating airworthiness approvals in the United States.
- Vertiport Infrastructure Deployment:Dedicated takeoff and landing facilities in Germany and China are establishing corridor networks for commercial route validation.
- Distributed Electric Propulsion:Redundant motor architectures are achieving failure-tolerance thresholds required for uncrewed passenger operations.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing dominates in China, creating single-source vulnerability for cell production.
- Detect-and-Avoid Technical Limitation:Non-cooperative traffic sensing in degraded visual environments remains unresolved for dense urban corridors.
- EASA SC-VTOL Certification Friction:Special conditions for pilotless operations impose extended validation cycles exceeding conventional rotorcraft timelines.
Strategic Opportunities
- Medical Logistics Routes:Organ transport and emergency supply missions in the United States command premium pricing with lower certification barriers than passenger service.
- Low-Altitude Traffic Management Convergence:Integration of UTM platforms with existing ATM systems is creating first-mover advantages for corridor operators.
- Hybrid-Electric Range Extension:Turbogenerator architectures are capturing cargo applications beyond battery-electric endurance limits.
Industry Challenges
- Flight Control Software Certification:Formal methods verification for autonomy algorithms requires specialized aerospace software engineering talent pools that remain shallow.
- Vertiport Real Estate Assembly:Urban land acquisition for multi-rotor landing facilities demands capital commitments ahead of revenue validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Autonomous Air Mobility Market |
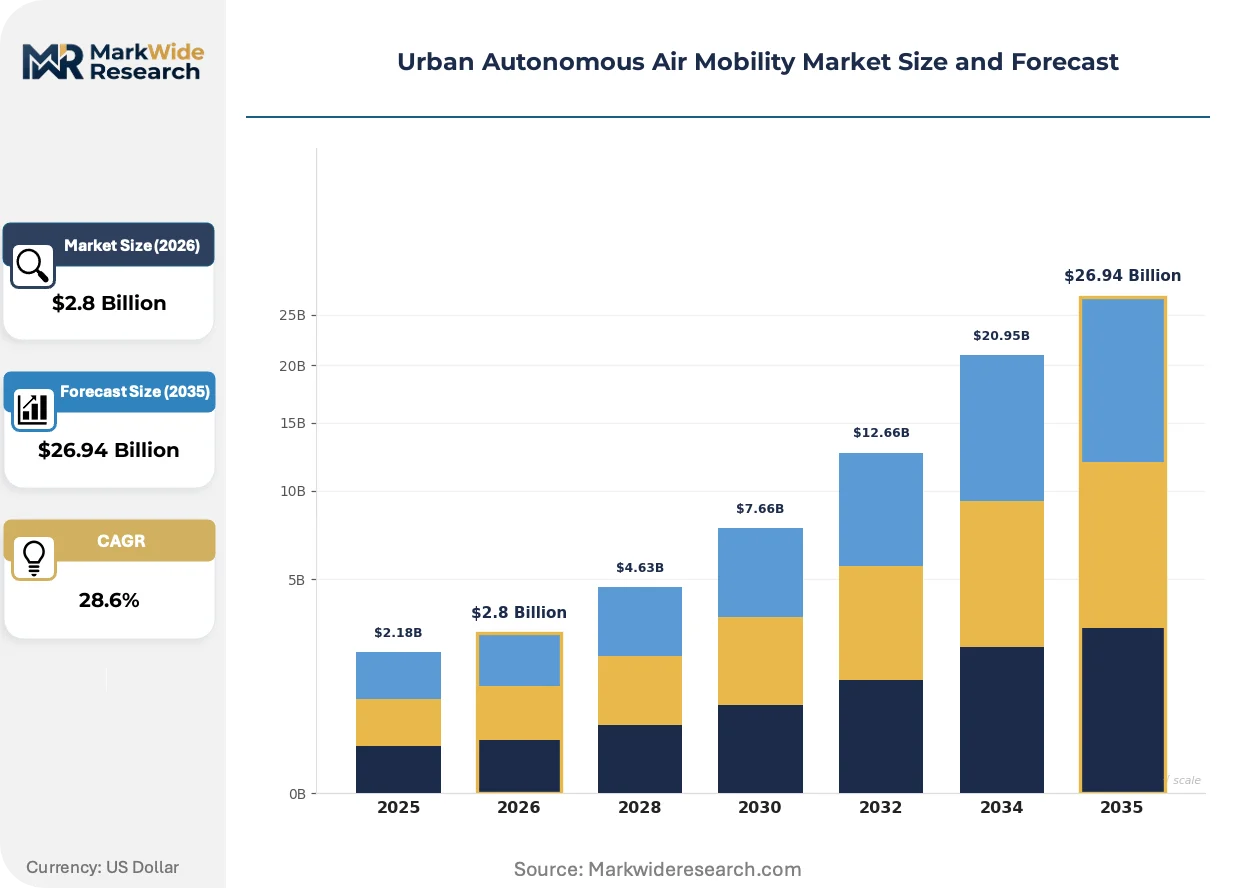
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: eVTOL, Fixed-Wing, Hybrid, Multirotor Technology: Flight Control Systems, Navigation Systems, Communication Systems, Power Management Application: Passenger Transport, Cargo Delivery, Emergency Services, Surveillance End User: Government Agencies, Logistics Providers, Private Companies, Ride-Hailing Services |
| Companies Covered | Joby Aviation, Airbus SE, EHang Holdings, Lilium Aviation, Volocopter GmbH, Archer Aviation, Wisk Aero LLC, Eve Air Mobility, Vertical Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Autonomous Air Mobility Market Emerging Trajectories
Urban air mobility architectures are pivoting from crewed transitional designs toward native autonomy, with navigation and propulsion systems converging around uncrewed operational requirements rather than retrofitting piloted platforms.
Optical detect-and-avoid sensors fused with radar returns are supplanting cooperative transponder dependence for uncrewed separation assurance. Logistics operators in Germany are deploying these sensor stacks for beyond-visual-line-of-sight cargo trials. The shift is compressing minimum equipment lists and reducing certification surface area for autonomous type certificates.
EASA SC-VTOL special conditions for pilotless passenger transport are mandating fault-tolerant flight control architectures with no single point of failure. Vehicle manufacturers are redesigning actuator and power distribution layouts to satisfy these requirements. European city network operators are prioritizing designs pre-validated against these conditions for 2028 service entry.
Asset-light fleet access models are displacing direct ownership for early commercial operators. Ride-hailing platforms in China are contracting capacity from certified operators rather than acquiring airframes. This pattern concentrates capital risk with manufacturers while accelerating passenger-facing service deployment.
Urban Autonomous Air Mobility Market Segmentation
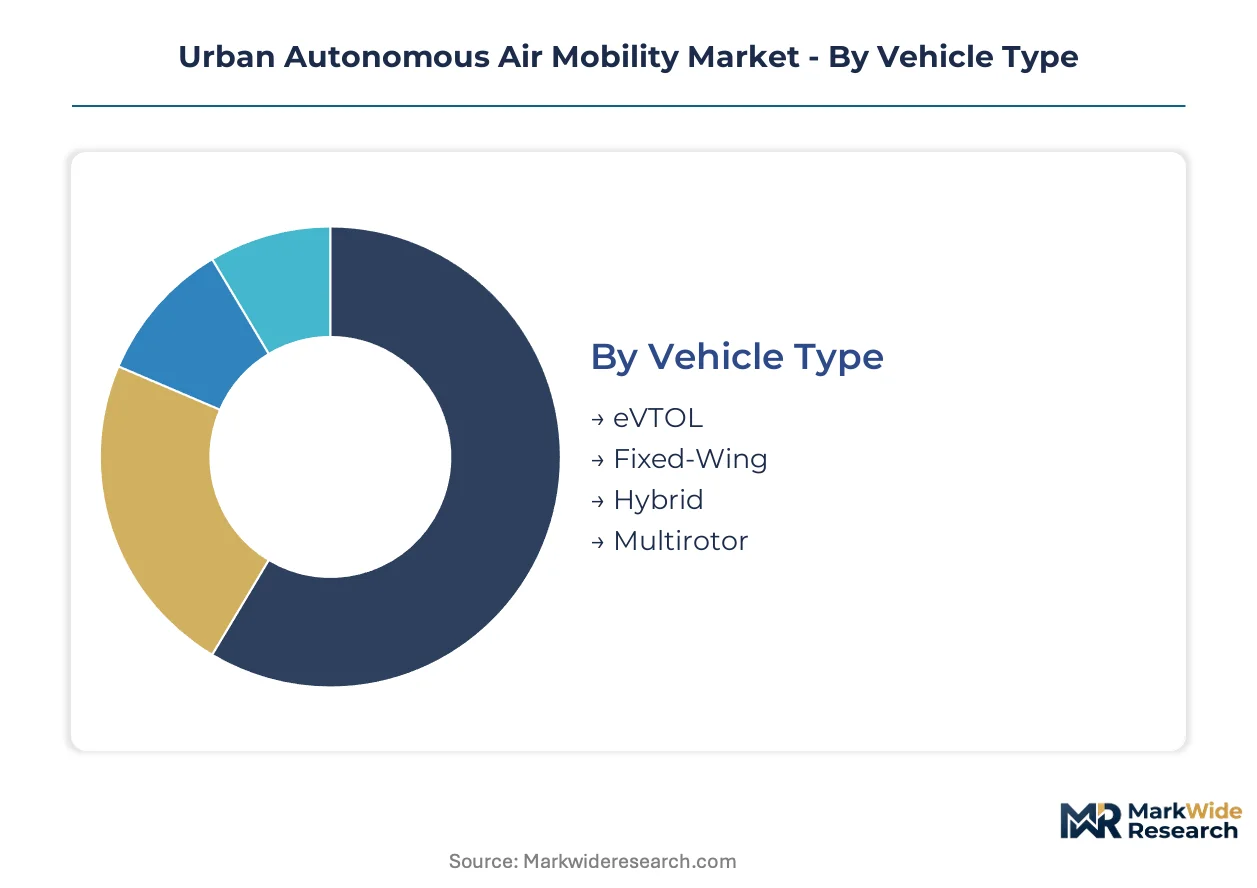
Segmentation in urban autonomous air mobility reveals how capital allocation and regulatory approval timelines concentrate across vehicle architectures and operational missions. Manufacturers align development roadmaps with specific technology-application combinations that offer clearer certification pathways or higher unit economics.
Vehicle Type:
Margin pools concentrate in configurations achieving FAA Part 135 or EASA SC-VTOL validation first, as airworthiness certification unlocks commercial revenue.
- eVTOL:Electric vertical take-off and landing architectures dominate development investment through distributed electric propulsion with redundant motor layouts. Demand concentrates in United States metropolitan corridors where Joby Aviation and Archer Aviation pursue FAA type certification, driven by premium passenger transport pricing on high-density routes.
- Hybrid:Turbogenerator-electric configurations extend operational range beyond battery-electric limits for cargo missions. Germany and China are validating hybrid designs for medical logistics and emergency supply routes where endurance thresholds exceed pure-electric capabilities.
- Fixed-Wing:Lift-plus-cruise designs optimize energy efficiency for longer inter-urban corridors.
- Multirotor:Simple mechanical architectures serve surveillance and light-cargo applications with lower certification complexity.
The dominant share belongs to eVTOL, while hybrid is closing the gap fastest.
Technology:
Development spending tilts toward systems that reduce human-in-the-loop dependencies and satisfy uncrewed operational safety requirements.
- Navigation Systems:Detect-and-avoid algorithms fused with optical and radar sensing enable beyond-visual-line-of-sight operations in dense urban airspace. Germany's logistics operators are deploying these sensor stacks for cargo trials in controlled low-altitude corridors, constrained by degraded-weather performance limitations.
- Flight Control Systems:Fault-tolerant architectures with no single point of failure satisfy EASA SC-VTOL special conditions for pilotless passenger transport. European manufacturers redesign actuator layouts to meet these requirements, prioritizing designs pre-validated for 2028 service entry.
- Communication Systems:Low-latency links integrate with UTM platforms for traffic coordination.
- Power Management:Battery thermal runaway containment and fast-charging protocols address lithium-ion supply concentration risks.
Navigation Systems command the largest technology spend, with Flight Control Systems expanding most quickly as certification deadlines approach.
Application:
Revenue per mission varies sharply by payload type and operational risk classification, with medical and emergency applications commanding premium pricing.
- Passenger Transport:On-demand urban mobility services target high-density corridors with vertiport-to-vertiport routing. United States ride-hailing platforms are contracting capacity from certified operators rather than acquiring airframes, concentrating capital risk with manufacturers while accelerating passenger-facing deployment.
- Emergency Services:Organ transport and medical supply missions benefit from lower certification barriers than passenger service and command premium pricing. United States hospital networks are establishing dedicated routes for time-critical deliveries.
- Cargo Delivery:Last-mile logistics applications leverage uncrewed operations with reduced regulatory scrutiny compared to human transport.
- Surveillance:Government and infrastructure monitoring missions utilize multirotor platforms for persistent observation.
Passenger Transport holds the dominant revenue position, while Emergency Services is gaining share fastest through regulatory arbitrage.
End User:
Procurement authority and fleet scale determine contract structures, with asset-light models displacing direct ownership among early commercial operators.
- Ride-Hailing Services:Mobility platforms in China are pioneering capacity-contracting models that shift airframe ownership risk to manufacturers while accelerating service launch. These arrangements concentrate demand forecasting and pricing power with passenger-facing brands.
- Logistics Providers:Express delivery networks in Germany are validating autonomous cargo corridors through partnerships with vertiport operators and UTM platform providers.
- Government Agencies:Public safety and defense applications drive surveillance and emergency response procurement with dedicated budget lines.
- Private Companies:Corporate shuttle services and executive transport represent emerging demand from high-net-worth individuals and technology sector employers.
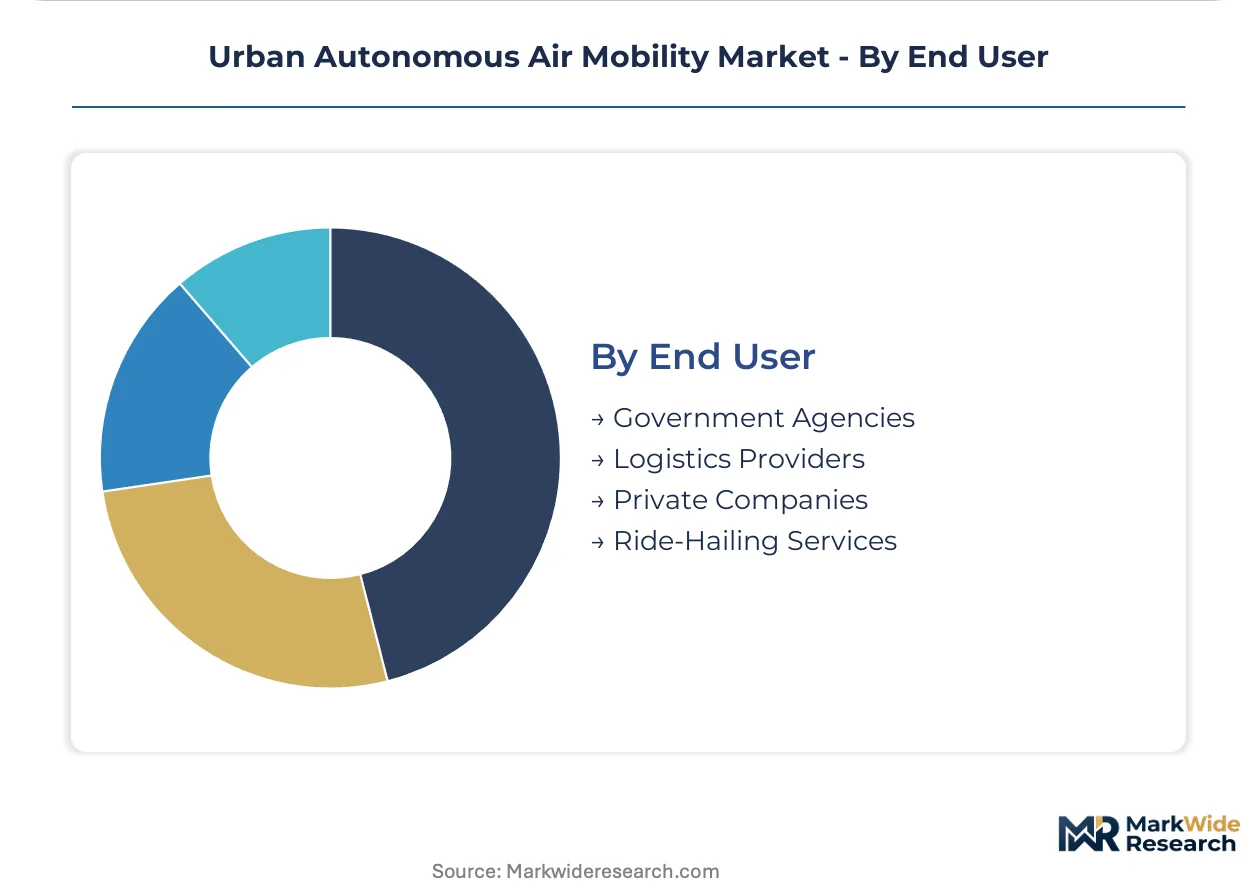
Ride-Hailing Services represents the largest end-user category, with Logistics Providers climbing the fastest as cargo certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cathode material processing for lithium-ion cells concentrates in China, creating supply-side dependencies that manufacturers in the United States, Germany, and Japan must navigate through diversified sourcing strategies and alternative chemistry investments.
United States
FAA Part 135 operational certification pathways are accelerating airworthiness approvals for pilotless passenger transport. The agency's type certification backlog for eVTOL designs is compressing through dedicated review teams. Joby Aviation and Archer Aviation anchor development clusters in California, where flight-test data accumulation supports regulatory momentum.
Germany
EASA SC-VTOL special conditions are mandating fault-tolerant flight control architectures for commercial service entry. Vertiport infrastructure deployment in Munich and Stuttgart is establishing corridor networks for route validation. Volocopter GmbH leverages these regulatory frameworks to prioritize designs pre-validated against European pilotless operation requirements.
China
CAAC operational permits are enabling commercial deployment ahead of Western certification timelines. Low-altitude traffic management system integration in Shenzhen and Guangzhou is creating controlled corridors for beyond-visual-line-of-sight operations. EHang Holdings anchors multiple Asian jurisdictions through operational permits that bypass extended airworthiness validation cycles.
Japan
METI funding programs for urban air mobility infrastructure are accelerating vertiport planning in Osaka and Tokyo. The country's aviation regulator is harmonizing detect-and-avoid standards with FAA and EASA frameworks to enable future certification reciprocity. Domestic manufacturers are prioritizing sensor fusion technologies for dense urban environments.
United Arab Emirates
General Civil Aviation Authority fast-track permits are positioning Dubai as an early deployment market for pilotless cargo and passenger trials. NEOM's planned autonomous mobility infrastructure in Saudi Arabia is creating cross-border corridor opportunities. Logistics operators are validating sensor stacks for desert-environment performance ahead of European and North American regulatory approvals.
Urban Autonomous Air Mobility Market Vendor Landscape
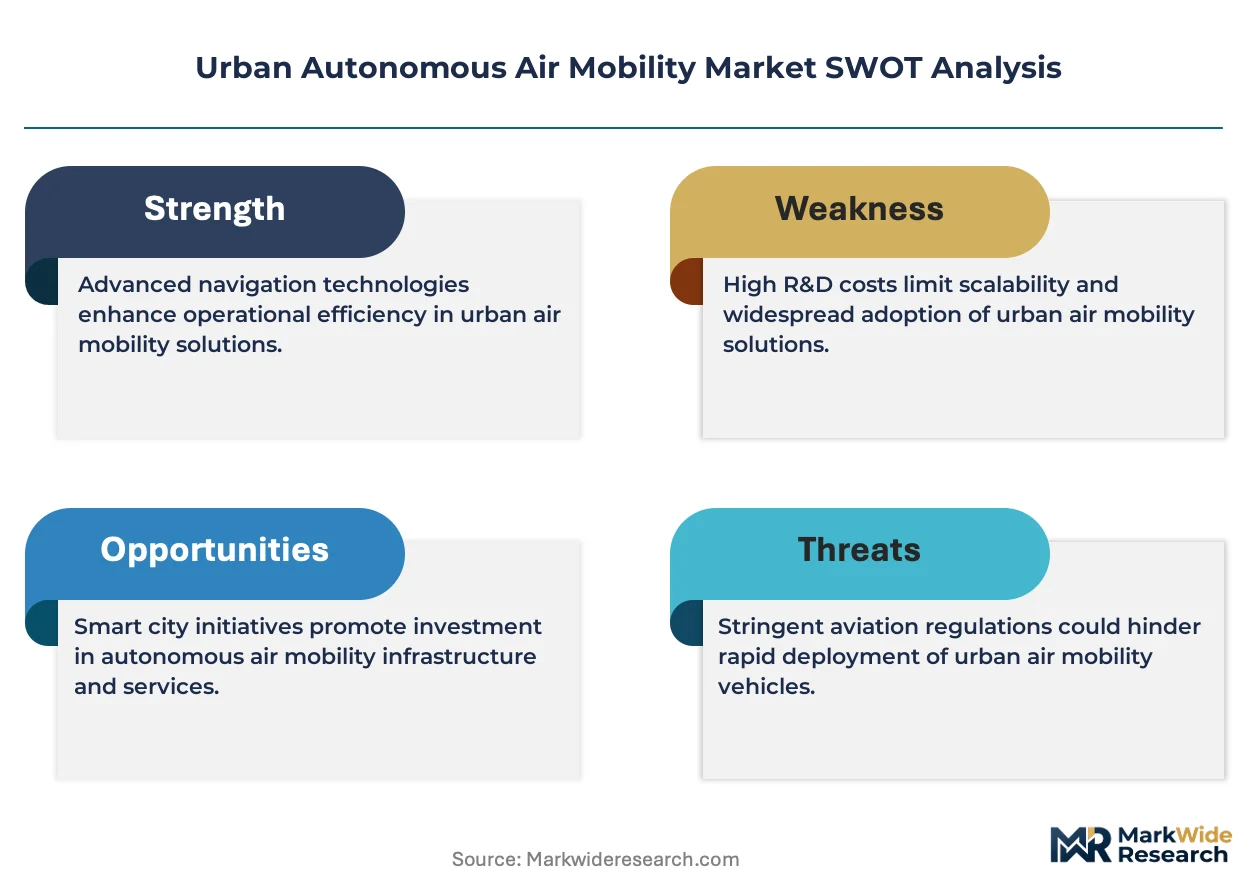
Technology leadership and cost leadership are held by different player archetypes, with certification-first developers commanding premium positioning while manufacturing-scale specialists capture production efficiencies. The market structure is consolidating around three tiers: airframe-integrated system developers, component technology licensors, and fleet-operating service platforms. Strategic differentiation clusters around FAA/EASA/CAAC certification reciprocity alignment, distributed electric propulsion redundancy architectures, and asset-light fleet access models. Dominant competitive moves include strategic partnerships with vertiport real estate developers and technology licensing agreements for detect-and-avoid sensor fusion.
Within the certification-priority tier, Joby Aviation and Archer Aviation exemplify United States-based developers pursuing FAA type validation through extensive flight-test programs. Volocopter GmbH anchors the European vector with EASA SC-VTOL pre-validation strategies. EHang Holdings occupies a distinct position through CAAC operational permits that enable revenue generation ahead of Western regulatory timelines.
| Leading Market Players |
|---|
| Joby Aviation |
| Airbus SE |
| EHang Holdings |
| Lilium Aviation |
| Volocopter GmbH |
| Archer Aviation |
| Wisk Aero LLC |
| Eve Air Mobility |
| Vertical Aerospace |
| Others |
Supply Flow & Price Mechanics
Ninety-day battery cell lead times from cathode processors in China compress manufacturer working capital cycles while anchoring pricing power with integrated cell suppliers commanding premium contract terms. FAA Part 135 certification timelines in the United States and EASA SC-VTOL validation cycles in Germany create divergent cost-to-market pathways that stratify procurement economics across jurisdictions.
Pricing Analysis
FAA Part 135 dictates the pricing tier structure across the urban autonomous air mobility landscape, separating pre-certified development units from revenue-service aircraft. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, flight-test data maturity, and after-sales support bundling. Cost compression in standard-tier manufacturing is intensifying because lithium-ion cell supply contracts face renegotiation pressure from ride-hailing fleet operators in China. Logistics providers in Germany exhibit highest price sensitivity due to thin cargo margins, while emergency medical networks in the United States show lowest sensitivity given mission-critical time premiums.
Supply Chain Analysis
Strait of Malacca transit routes for lithium carbonate feedstock underpin cathode precursor flows that feed cell manufacturing concentrated in China, South Korea, and Japan. Distributed electric propulsion architectures draw from rare-earth magnet processors in China, silicon carbide wafer foundries in Germany, and composite airframe weavers in the United States. Single-source vulnerability in Chinese cathode material refining exposes manufacturers to export license restrictions. Distribution runs through vertiport real estate developers assembling multi-rotor landing facilities ahead of revenue validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban autonomous air mobility sits in early-cycle expansion as FAA Part 135 operational certification pathways unlock pilotless passenger revenue ahead of prior projections. Asset-light fleet contracting models in China concentrate adoption velocity with passenger-facing platforms rather than airframe ownership.
For Market Incumbents: Compound certification-first positioning by accelerating flight-test data accumulation against EASA SC-VTOL special conditions before European rivals achieve pre-validation. Deepen upstream control over lithium-ion cell supply through offtake agreements with South Korean cathode processors to defend against Chinese export restriction threats. Anchor vertiport real estate partnerships in Germany and the United States to lock corridor access ahead of competitor fleet deployment. For New Entrants and Emerging Players: Lead with medical logistics route validation in the United States where lower certification barriers than passenger service create faster revenue paths. Target emergency organ transport networks and hospital supply chains as the most penetrable application segment. Pursue sensor fusion technology licensing agreements with established German logistics operators to bypass direct airframe development capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates spinning off urban air mobility divisions amid portfolio rationalization pressure. Frame five-to-ten-year viability around certification reciprocity convergence between FAA, EASA, and CAAC frameworks enabling fleet scale economics. Watch for detect-and-avoid algorithm validation milestones in degraded visual environments as the critical inflection signal separating viable autonomy stacks from developmental dead-ends.| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Secures corridor access for FAA Part 135 route validation in United States metropolitan clusters. |
| Detect-and-Avoid Sensor Fusion Licensing | Accelerates EASA SC-VTOL compliance timelines through validated optical-radar integration stacks. |
| CAAC Operational Permit Expansion | Unlocks revenue generation in Shenzhen and Guangzhou ahead of Western certification reciprocity. |
| Hybrid-Electric Range Extension Development | Captures cargo applications beyond battery-electric endurance limits in German medical logistics. |
| Asset-Light Fleet Contracting Model | Concentrates capital risk with manufacturers while accelerating passenger service deployment in China. |
Methodological Framework
The analysis maps eVTOL configurations, hybrid architectures, navigation systems, and flight control technologies, each validated through certification engineers, vertiport developers, ride-hailing platform strategists, and lithium-ion supply specialists. Primary interviews with FAA certification leads, EASA flight test directors, CAAC operational permit officers, and German logistics procurement heads combined with secondary validation against FAA type certification filings, EASA SC-VTOL special condition documents, CAAC operational bulletins, and vertiport infrastructure investment disclosures. Bottom-up fleet deployment projections and top-down market size estimates underwent cross-triangulation to reconcile manufacturer delivery commitments with operator revenue assumptions.
Consistency checks validated volume and value outputs against external benchmarks including disclosed flight-test hour accumulation rates, announced vertiport construction timelines, and reported lithium-ion cell supply contract values. The analytical framework modeled vehicle type, technology segment, application mission, and end-user procurement authority dimensions across the projection horizon. CAGRs derived from segment-level adoption curves weighted by certification timeline probability distributions. Industry-specific forecast inputs included distributed electric propulsion redundancy architecture penetration and detect-and-avoid algorithm technical readiness levels.
Underlying assumptions cover sustained lithium-ion cell supply availability, regulatory harmonization progress between FAA and EASA frameworks, and vertiport real estate assembly completion rates, with deviation risk concentrated in Chinese cathode material export restrictions and degraded-weather detect-and-avoid performance limitations. Practitioners should keep alternative scenarios live as certification reciprocity negotiations and low-altitude traffic management system integration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Hang Glider Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Flying Taxi Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Global Flying Cars Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Air Transport USM Market
Air Mobility
Middle-East and Africa Military Aviation Market