
 Global LEO Satellite Market | 2026-2036
Global LEO Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Global LEO Satellite Market Outlook
Subscription-based managed connectivity is expanding as the dominant commercial model in low Earth orbit operations. Space Exploration Technologies Corp. leverages its vertically integrated launch stack to control cost structures across deployment cycles. OneWeb anchors European broadband coverage through its polar-orbiting constellation architecture. Planet Labs PBC specializes in daily Earth imaging cadence that differentiates its data products from geostationary alternatives.
A low Earth orbit satellite operates at altitudes between 160 and 2,000 kilometers above Earth's surface, utilizing orbital periods of roughly 90 to 120 minutes that enable low-latency signal transmission for real-time applications. Communication Satellites command the largest revenue share within product type categories as constellation operators monetize bandwidth contracts with maritime and aviation clients. Shared Launch deployment models are gaining structural traction by reducing per-unit insertion costs through rideshare programs. CubeSats represent the fastest-expanding technology tier among university and commercial research programs seeking rapid orbital access.
The FCC governs U.S. spectrum licensing and orbital debris mitigation requirements that directly shape constellation design parameters. ITU coordination procedures enforce international frequency allocation rules that constrain market entry timelines for new operators. ESA regulatory frameworks in Europe mandate end-of-life deorbiting protocols that increase satellite engineering complexity. Stakeholders must monitor evolving national space traffic management policies that will determine operational scalability across competing jurisdictions.
Market Dynamics
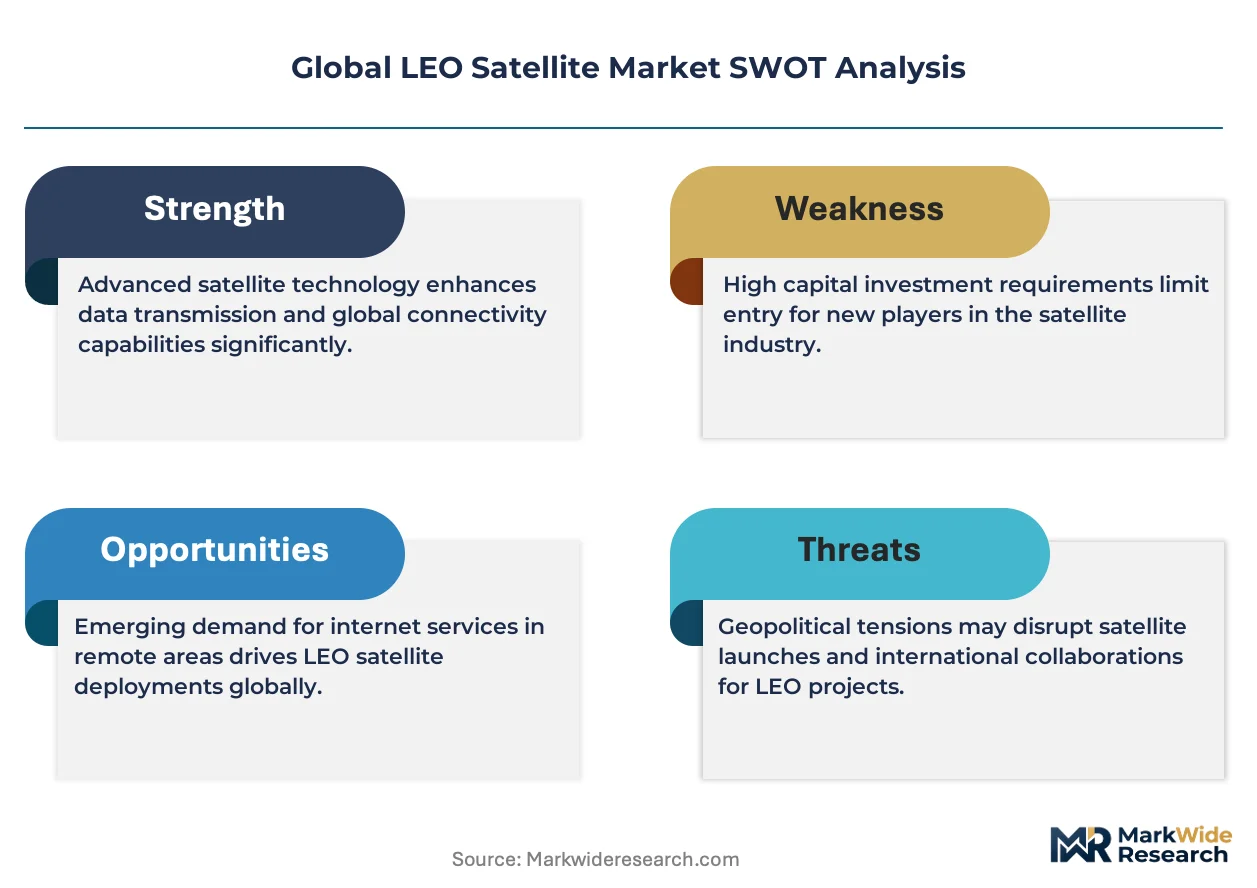
The LEO satellite market is being fundamentally restructured by spectrum scarcity and orbital slot competition, as national regulators impose stricter coordination requirements that extend deployment timelines and favor incumbent operators with established ITU filings.
Growth Catalysts
- Rural broadband mandates:Universal service obligations in the United States, United Kingdom, and India are forcing telecommunications incumbents to source satellite backhaul for unserved territories.
- FCC Part 25 licensing reforms:Streamlined market access procedures for non-geostationary systems are accelerating constellation authorization timelines for qualified applicants.
- Laser inter-satellite links:Optical cross-connect technology is eliminating ground station dependency for polar coverage, reducing latency and operational expenditure for maritime and aviation clients.
Market Restraints
- Launch capacity bottlenecks:Heavy reliance on a concentrated set of Western and Chinese launch providers creates schedule risk and pricing volatility for constellation deployment.
- ITU coordination delays:International frequency allocation procedures impose multi-year review windows that freeze market entry for new spectrum applicants.
- Debris mitigation compliance:ESA-mandated end-of-life deorbiting protocols and NASA collision avoidance standards add engineering mass and propulsion system cost to satellite designs.
Strategic Opportunities
- Defense and intelligence procurement:NATO member states and Five Eyes partners are expanding classified bandwidth contracts for tactical communications and signals intelligence.
- Internet of Things integration:Convergence between LEO constellations and terrestrial LPWAN networks is creating hybrid connectivity solutions for agricultural and logistics monitoring.
- Remote sensing analytics:Synthetic aperture radar and hyperspectral imaging payloads are opening subscription-based Earth observation services for insurance and commodity trading verticals.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in phased array antennas and software-defined radios is concentrating among defense contractors and a limited pool of commercial operators.
- Ground segment integration complexity:Legacy teleport infrastructure requires expensive retrofitting to interoperate with proliferating non-geostationary constellations using diverse waveforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LEO Satellite Market |
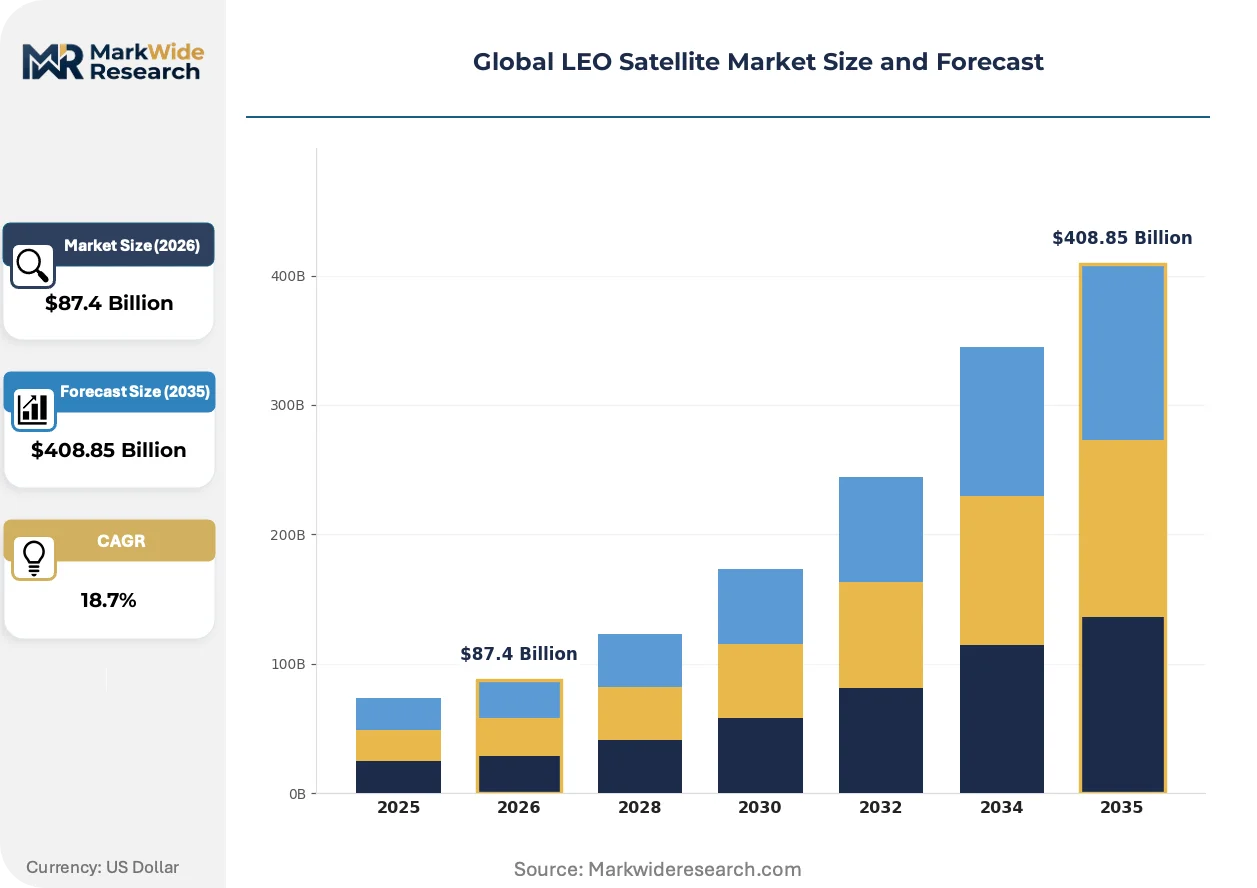
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $408.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Satellites, Earth Observation Satellites, Navigation Satellites, Research Satellites Deployment: Dedicated Launch, Shared Launch, In-Orbit Servicing, Reusable Systems End User: Aerospace Industry, Telecommunications, Government Agencies, Research Institutes Technology: Active Satellite Networks, Passive Satellite Systems, CubeSats, Hybrid Systems |
| Companies Covered | China Aerospace Science and Technology Corporation, Thales Alenia Space, Space Exploration Technologies Corp., OneWeb, Planet Labs PBC, Lockheed Martin Corporation, Northrop Grumman, Eutelsat S.A., Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LEO Satellite Market Strategic Shifts
Orbital manufacturing and on-orbit servicing capabilities are emerging as the next capability frontier, while regulatory frameworks race to catch up with autonomous collision avoidance and satellite-to-satellite refueling operations.
Software-defined payloads are rewriting how satellite operators reconfigure bandwidth allocation and coverage footprints without physical hardware replacement. Maritime shipping lines and commercial airlines are adopting these flexible terminals to maintain connectivity across polar routes previously unserved by geostationary systems. The technology is compressing refresh cycles from decade-long satellite replacement to quarterly firmware updates.
REACH chemical restrictions and the EU Green Deal sustainability criteria are mandating design-for-demise materials and propellant selection in European-registered satellites. Manufacturers must now substitute conventional hydrazine with less toxic green propulsion alternatives and document supply chain carbon intensity. Small satellite builders in Germany and France are responding by restructuring supplier relationships to qualify compliant component vendors.
Enterprise buyers are consolidating vendor relationships around integrated connectivity-as-a-service contracts that bundle terminals, bandwidth, and network management into single-source agreements. Systems integrators and maritime fleet operators are displacing piecemeal procurement of ground equipment and transponder leases. This pattern is most pronounced in Singapore and the United Arab Emirates, where port authorities and flag registries are mandating unified satcom standards for vessel certification.
Global LEO Satellite Market Segmentation
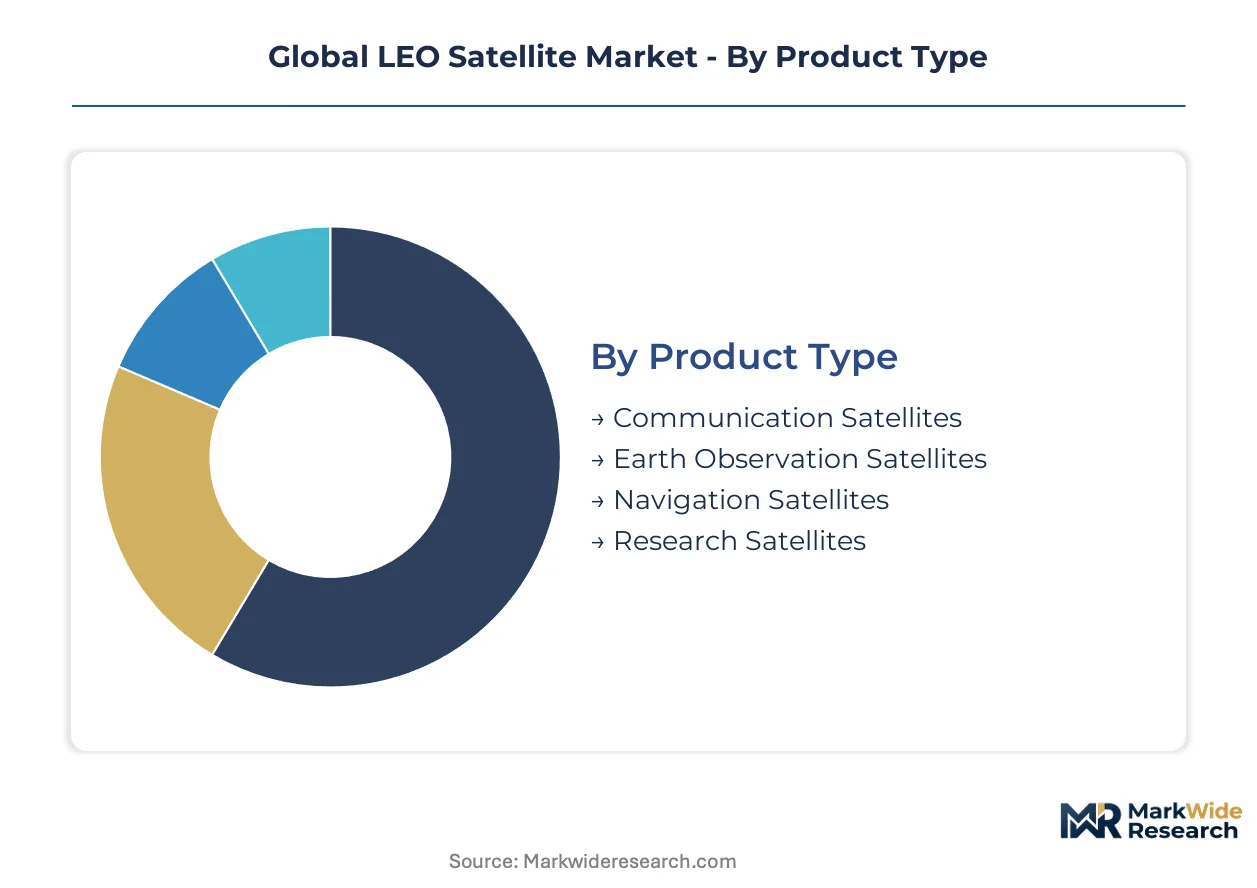
LEO satellite procurement decisions hinge on payload flexibility, launch economics, and orbital lifecycle management. Buyers evaluate trade-offs between dedicated mission assurance and rideshare cost efficiency across constellation planning cycles.
Product Type:
Payload specifications determine insurance premiums, launch mass allocations, and ground station compatibility requirements for fleet operators.
- Communication Satellites:These platforms carry phased array antennas and software-defined radios for broadband relay. Maritime shipping operators in Singapore and commercial aviation routes over the North Atlantic concentrate procurement here, driven by FCC Part 25 licensing reforms that streamlined non-geostationary authorizations.
- Earth Observation Satellites:Synthetic aperture radar and multispectral imagers capture daily revisit cadence for agricultural monitoring. Insurance underwriters in London and commodity trading desks in Chicago anchor demand, constrained by ESA-mandated end-of-life deorbiting protocols that add propulsion system mass.
- Navigation Satellites:Precision timing payloads augment terrestrial GPS augmentation networks.
- Research Satellites:University consortiums and national space agencies deploy these for ionospheric and climate science missions.
Communication Satellites leads on scale; Earth Observation Satellites leads on momentum.
Deployment:
Launch modality selection reflects risk tolerance and constellation deployment velocity requirements.
- Dedicated Launch:Single-manifest missions guarantee orbital insertion parameters and schedule certainty. Defense agencies in the United States and classified bandwidth contractors in the United Kingdom prioritize this mode, absorbing premium pricing to meet tactical communications deadlines.
- Shared Launch:Rideshare aggregators distribute fixed launch costs across multiple payloads. University CubeSat programs in Germany and commercial IoT constellation builders in India concentrate here, capitalizing on SpaceX Transporter and ISRO PSLV secondary payload availability.
- In-Orbit Servicing:Robotic refueling and life extension missions are emerging for high-value assets.
- Reusable Systems:Falcon 9 booster recovery and emerging Starship architectures reshape unit economics.
Dedicated Launch commands the premium tier; Shared Launch is climbing the fastest.
End User:
Budget authority and mission criticality shape procurement channel selection and contract structuring.
- Aerospace Industry:Satellite manufacturers and subsystem suppliers constitute the upstream demand base. Boeing and Airbus Defence and Space operations in Toulouse and El Segundo drive component procurement, responding to NASA collision avoidance standards that elevate tracking subsystem requirements.
- Telecommunications:Rural broadband mandates in the United States, United Kingdom, and India force incumbents to source satellite backhaul. Verizon and BT Group procurement teams negotiate managed connectivity contracts spanning terminal, bandwidth, and network management bundles.
- Government Agencies:National space programs and defense ministries fund sovereign constellation capabilities.
- Research Institutes:Climate science and astronomy missions access orbital capacity through academic partnerships.
Telecommunications dominates volume; Government Agencies shows the steepest expansion trajectory.
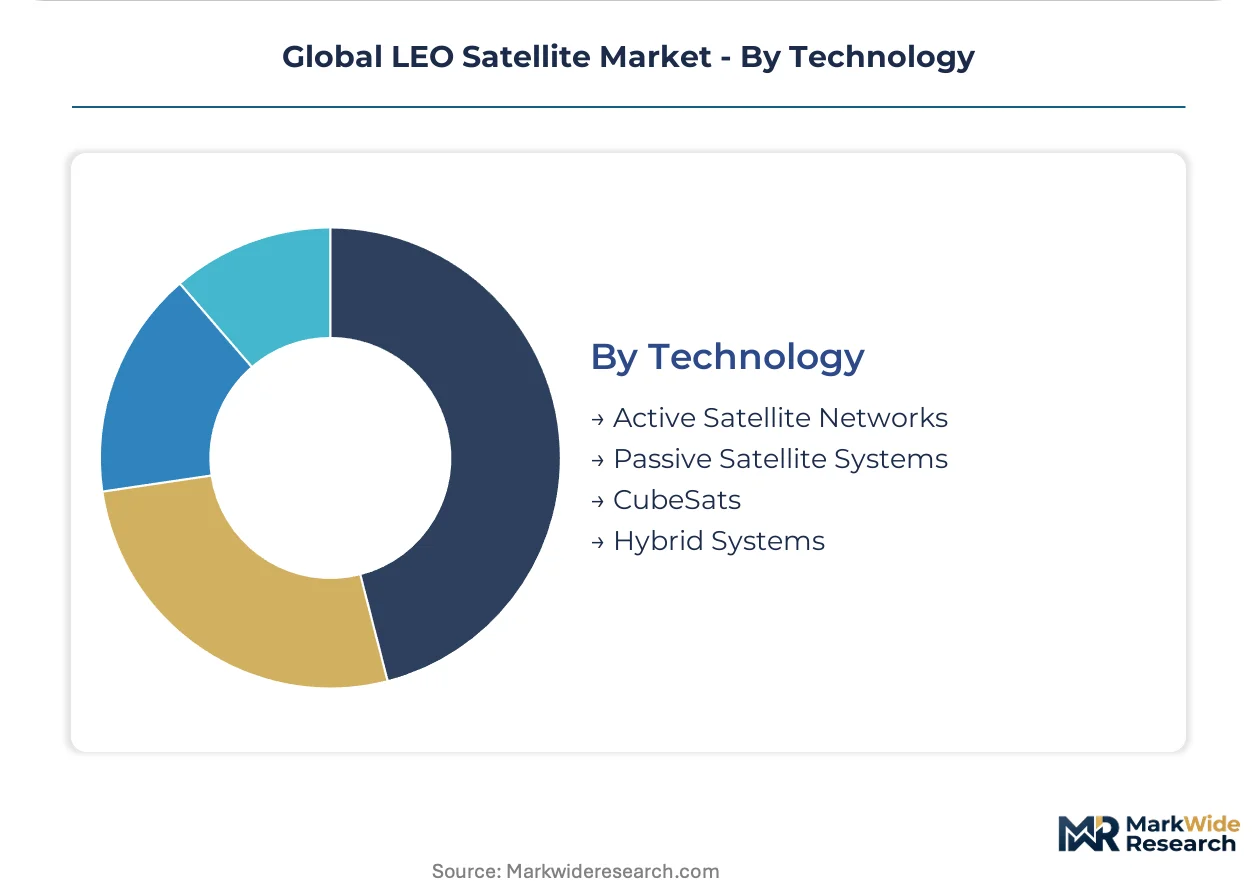
Technology:
Network architecture choices determine latency performance, manufacturing scalability, and regulatory compliance pathways.
- Active Satellite Networks:Laser inter-satellite links and onboard processing enable mesh routing without ground station handoffs. SpaceX Starlink and Amazon Kuiper architectures exemplify this approach, eliminating polar coverage gaps for maritime clients operating across the Southern Ocean.
- CubeSats:Standardized 10x10x10 cm form factors accelerate university and commercial research access. TU Berlin and Spire Global operations leverage this tier, though REACH chemical restrictions and EU Green Deal sustainability criteria mandate green propulsion substitutions.
- Passive Satellite Systems:Reflective or transponder-based architectures without active power generation serve specific mission profiles.
- Hybrid Systems:Combinations of active and passive elements optimize for mixed mission requirements.
Active Satellite Networks leads on scale; CubeSats leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's constellation deployment pace exceeds that of European counterparts, while the United States maintains regulatory primacy through FCC spectrum governance. National space programs across five major economies are restructuring procurement around sovereign bandwidth security and debris mitigation compliance.
United States
Defense procurement from the Pentagon and classified bandwidth contracts from intelligence agencies drive constellation demand. FCC Part 25 licensing reforms streamline non-geostationary authorizations for qualified applicants. The Space Coast cluster in Florida hosts vertical launch integration facilities where SpaceX and United Launch Alliance coordinate deployment schedules.
China
State-owned enterprises and commercial operators pursue sovereign broadband coverage independent of Western infrastructure. MIIT spectrum allocation procedures and national space traffic management policies constrain foreign market participation. The Wenchang Satellite Launch Center in Hainan coordinates heavy-lift missions for constellation deployment alongside the Jiuquan facility in Gansu.
United Kingdom
BT Group procurement teams negotiate managed connectivity contracts to satisfy universal service obligations in rural territories. UK Space Agency funding supports domestic launch capability development at SaxaVord and Spaceport Cornwall. The Harwell Science and Innovation Campus in Oxfordshire concentrates satellite manufacturing and ground segment engineering talent.
Germany
Automotive and maritime industries source satellite backhaul for connected vehicle and vessel tracking applications. REACH chemical restrictions and EU Green Deal sustainability criteria mandate green propulsion substitutions in satellite designs. The Bremen-Ottobrunn industrial corridor hosts Airbus Defence and Space manufacturing alongside OHB System AG operations.
India
Rural broadband mandates from the Department of Telecommunications force incumbent operators to source satellite backhaul for unserved territories. ISRO's PSLV and GSLV launch services offer rideshare capacity to commercial constellation builders. The Sriharikota spaceport in Andhra Pradesh coordinates deployment missions while Bengaluru's aerospace cluster concentrates subsystem engineering expertise.
Global LEO Satellite Market Competitive Environment
Top-tier vendors anchor sovereign constellation programs, while mid-tier specialists concentrate on component subsystems and regional connectivity services. The vendor base stratifies across vertically integrated launch-stack operators, phased-array manufacturers, and Earth observation data aggregators. Two strategic archetypes dominate: state-affiliated enterprises leveraging national procurement preferences, and commercial operators monetizing managed connectivity subscriptions. Competitive moves center on launch cost reduction through reusable systems and spectrum portfolio accumulation through ITU coordination filings.
Among state-affiliated enterprises, China Aerospace Science and Technology Corporation exemplifies the sovereign capability archetype through integrated launch and satellite manufacturing operations. Space Exploration Technologies Corp. and OneWeb occupy positions at the commercial connectivity frontier, representing contrasting approaches to constellation architecture and market access strategy. These three entities illustrate the competitive tension between national security-driven procurement and commercial service expansion.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| Thales Alenia Space |
| Space Exploration Technologies Corp. |
| OneWeb |
| Planet Labs PBC |
| Lockheed Martin Corporation |
| Northrop Grumman |
| Eutelsat S.A. |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
Rural broadband mandates from the United States, United Kingdom, and India are forcing telecommunications incumbents to reconfigure procurement specifications around managed connectivity bundles, compelling satellite manufacturers to absorb green propulsion compliance costs while repositioning pricing tiers around service-level guarantees rather than hardware transponder leases.
Pricing Analysis
Capacity additions in China's constellation manufacturing base are reshaping price floors for standardized satellite buses and phased array subsystems. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with price differentiation driven by ITU filing priority dates and launch manifest certainty. Cost compression in the economy tier is intensifying because rideshare aggregators are consolidating secondary payload demand. Government agencies show least price sensitivity due to mission assurance requirements, while university CubeSat programs exhibit highest elasticity.
Supply Chain Analysis
Photovoltaic cell supply rests on Chinese wafer producers, German substrate specialists, and Japanese precision coating operations. Satellite manufacturers draw from gallium arsenide solar arrays, software-defined radio chipsets, and green propulsion thrusters. Single-source vulnerability concentrates in radiation-hardened processor fabrication. Distribution runs through systems integrators who bundle terminal hardware with bandwidth subscriptions for maritime and aviation fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global LEO Satellite Market represents a late-cycle quality story where procurement committees are consolidating vendor relationships around integrated connectivity-as-a-service contracts that bundle terminals, bandwidth, and network management into single-source agreements with stringent debris mitigation compliance.
For Market Incumbents: To counter launch capacity bottlenecks from concentrated Western and Chinese providers, anchor procurement relationships through long-term reusable launch agreements and deepen backward integration into phased array manufacturing. Prioritize ITU coordination filing accumulation as a defensive moat against spectrum scarcity. For New Entrants and Emerging Players: Laser inter-satellite link technology offers a technology-first wedge into polar maritime routes previously unserved by geostationary infrastructure. Target agricultural IoT monitoring in India and remote sensing analytics for London insurance underwriters. Pursue university consortium partnerships for rapid flight heritage accumulation. For Investors and Strategic Acquirers: Asymmetric upside sits with component subsystem specialists holding software-defined payload expertise and green propulsion qualification. Long-term viability hinges on regulatory compliance scalability across FCC, ESA, and MIIT jurisdictions. Watch for ITU filing acceleration as inflection indicator for constellation deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Launch Stack Integration | SpaceX Falcon 9 recovery operations compress unit economics for constellation deployment cycles. |
| ITU Spectrum Portfolio Accumulation | Priority filing dates determine market access timelines for non-geostationary operators. |
| Green Propulsion Transition | REACH chemical restrictions mandate hydrazine substitution in European-registered satellites. |
| Laser Inter-Satellite Link Deployment | Optical cross-connect eliminates ground station dependency for polar maritime coverage. |
| Managed Connectivity Bundling | Singapore port authorities mandate unified satcom standards for vessel certification compliance. |
Study Parameters
Multiple input streams — constellation operator procurement leads, FCC licensing attorneys, launch manifest coordinators, and ground segment engineers — were reconciled against secondary validation from FCC Part 25 filings, ESA debris mitigation reports, ITU coordination databases, and satellite manufacturing trade data. Bottom-up unit economics modeling and top-down market sizing triangulation anchored volume and value estimates.
Historical deployment trajectories were cross-referenced against expert panel assessments across product type, deployment modality, end user, and technology segmentation dimensions. CAGRs were derived from growth rate reconciliation across the modeling period. Industry-specific forecast inputs included launch cadence projections and spectrum allocation timeline assumptions.
The model holds under stable regulatory coordination procedures; deviation in ITU processing delays or launch provider consolidation would shift deployment velocity assumptions. Forecasts reflect documented assumptions about rural broadband mandate enforcement and debris compliance standardization. A small set of named triggers — launch capacity expansion, spectrum reform acceleration, and sovereign constellation program announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Bus Market
Satellite
India Satellite Communication Market
Satellite
Europe Small Satellite Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Middle East Satellite Communications Market
Satellite
Europe Military Satellite Market
Satellite
Indonesia Satellite Communications Market
Satellite
India Satellite Connectivity Market
Satellite
ASEAN Satellite Communications Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
LEO Satellite System Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Europe Satellite Connectivity Market