
 Russia Satellite Communications Market | 2026-2036
Russia Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Satellite Communications Market Insights
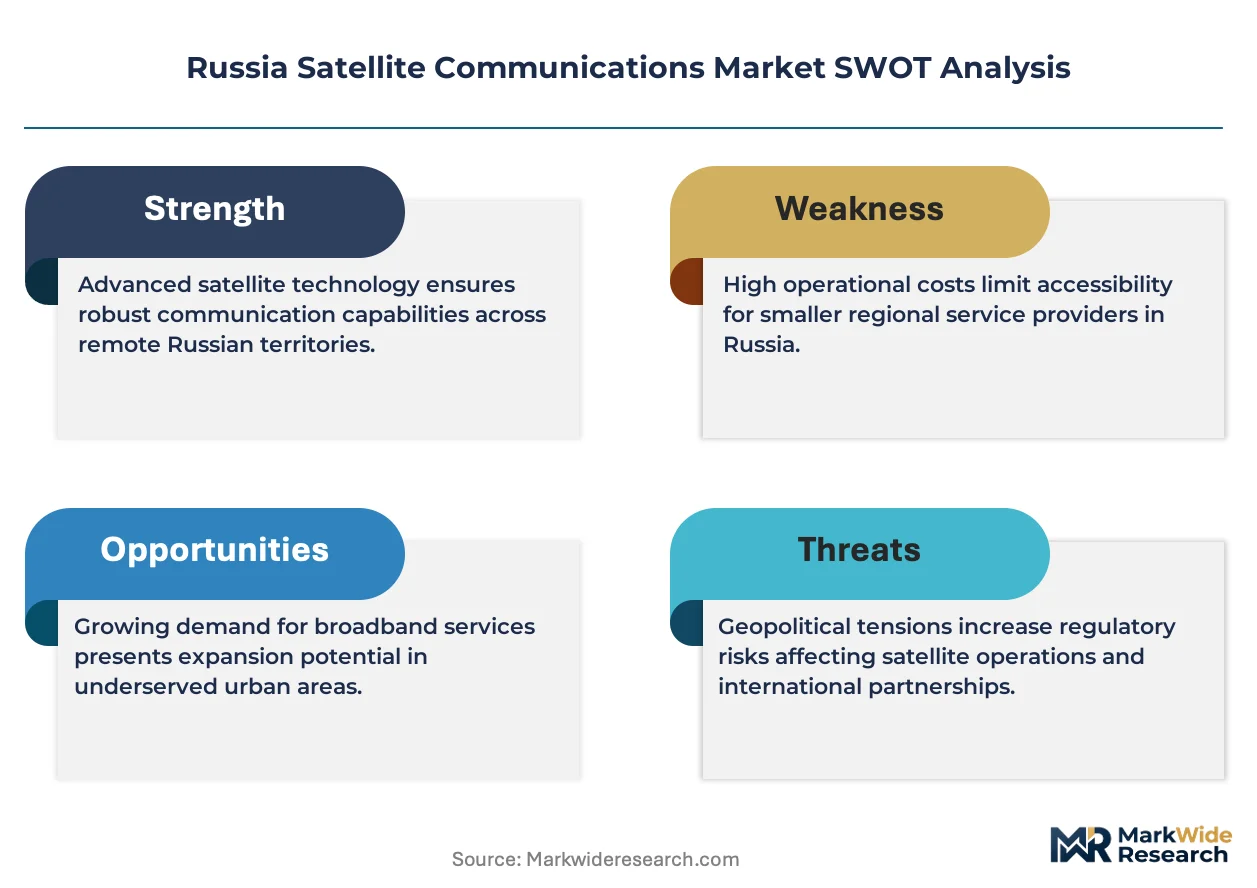
Ku-band and Ka-band high-throughput specifications is reorganizing procurement priorities across Russian satellite operators. RSCC leverages its orbital slot portfolio and federal backbone contracts to sustain nationwide coverage dominance. AltegroSky GC anchors regional connectivity through its teleport network in Siberia and the Far East. JSC Gazprom Space Systems specializes in energy-sector satellite links, controlling pipeline monitoring traffic that demands low-latency uptime guarantees.
Russia satellite communications encompasses ground stations, space segments, and user terminals operating across C-band through Ka-band frequencies, with geostationary platforms historically providing the backbone for television broadcast and government backhaul. Low Earth Orbit constellations are now displacing legacy geostationary architectures for defense and maritime mobility use cases where reduced latency proves critical. Broadcasting applications retain the largest revenue pool among service types, though data transmission for remote Arctic operations represents the fastest-expanding margin segment. Government and defense buyers command premium pricing tiers through classified procurement channels, while agriculture applications remain nascent with scattered pilot deployments.
Roscosmos coordinates orbital registration and launch licensing, while the Ministry of Digital Development enforces frequency allocation and cybersecurity compliance for satellite operators under national communications law. These frameworks restrict foreign constellation access and mandate domestic ground infrastructure, effectively reserving market access for Russia-registered entities and their joint ventures. Stakeholders must monitor whether proposed spectrum reassignments for 5G terrestrial networks will encroach on satellite downlink bands, as this collision threatens link budgets for existing services.
Market Dynamics
The Russian satellite communications sector is restructuring around orbital slot scarcity and frequency sovereignty enforcement, with Roscosmos licensing requirements tightening operational standards and domestic ground infrastructure mandates reserving market access for Russia-registered entities.
Growth Catalysts
- Arctic maritime mobility demand:Northern Sea Route shipping volumes are expanding year-round navigation windows, creating pull for low-latency LEO connectivity that geostationary platforms cannot deliver.
- Federal backbone procurement:Ministry of Digital Development frequency allocation rules under national communications law mandate secure command networks for defense applications, generating premium bandwidth contracts.
- Ka-band high-throughput migration:Satellite operators are reconfiguring orbital assets to capture data transmission revenue from remote energy infrastructure monitoring.
Market Restraints
- Launch capacity concentration:Dependence on Baikonur and Vostochny cosmodromes creates scheduling bottlenecks for constellation deployment timelines.
- Import substitution costs:Domestic manufacturing requirements for ground station electronics under trade restriction protocols inflate terminal procurement budgets versus global supply alternatives.
- Spectrum encroachment risk:Proposed 5G terrestrial reassignments threaten satellite downlink bands, compressing link budgets for existing C-band services.
Strategic Opportunities
- Far East regional connectivity:Siberian teleport infrastructure gaps present white space for integrated ground-segment operators serving extractive industries.
- Agricultural pilot scaling:Precision farming applications in the Black Earth region remain underpenetrated, with scattered IoT deployments ready for constellation service bundling.
- Cybersecurity compliance services:Ministry of Digital Development certification mandates create adjacent revenue streams for domestic encryption and network hardening providers.
Industry Challenges
- LEO-GEO integration complexity:Hybrid network architectures demand new gateway coordination protocols that legacy ground station operators lack expertise to deploy.
- Orbital mechanics talent scarcity:University pipeline deficits in astrodynamics and spectrum engineering constrain constellation planning velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Satellite Communications Market |
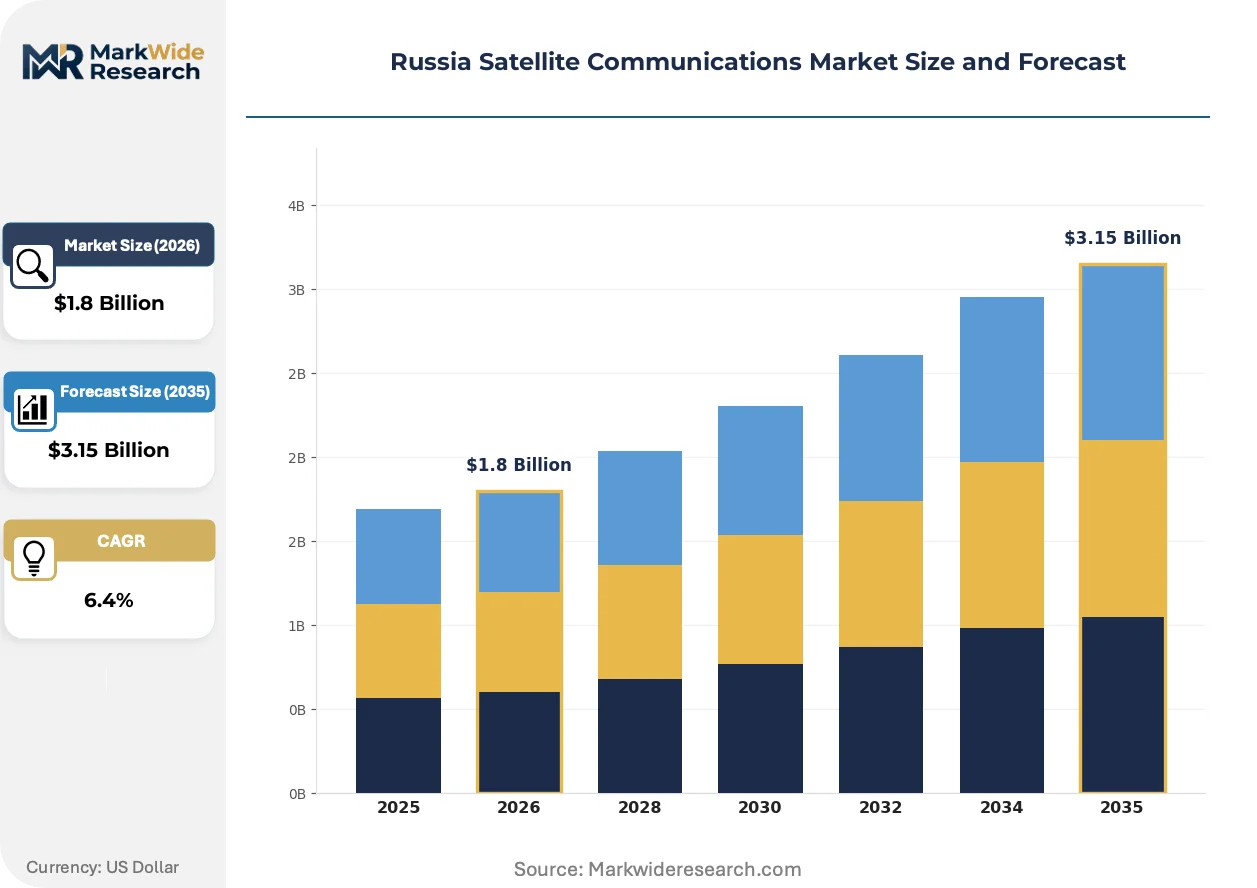
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Transmission, Broadcasting, Remote Sensing, Telemetric Services Application: Government, Defense, Agriculture, Disaster Management End User: Telecom Operators, Maritime, Aviation, Broadcasting Companies Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems |
| Companies Covered | Russian Satellite Communications Company (RSCC), AltegroSky GC, Hughes Network Systems, LLC, RTCOMM (JSC RTComm.RU), JSC Gazprom Space Systems, GeoTelecommunications, LLC, Konnect, Russia (LLC Eutelsat Networks), Gonets Satellite System, SCANEX Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Satellite Communications Market Trends and Innovations
LEO constellation architectures are actively displacing legacy geostationary dominance across Russian defense and maritime segments, while regulatory frameworks harden around domestic infrastructure requirements and frequency sovereignty.
Low Earth Orbit platforms is displacing geostationary satellites for defense command networks and Arctic shipping corridors. The Russian military is accelerating procurement of LEO bandwidth for secure tactical communications where latency thresholds under 50 milliseconds prove critical. This orbital shift is compressing geostationary operator revenue pools in mobility applications while opening gateway infrastructure contracts for domestic teleport operators.
Roscosmos licensing requirements and Ministry of Digital Development frequency allocation rules are tightening operational standards for foreign constellation access. These frameworks mandate domestic ground infrastructure and cybersecurity compliance, effectively reserving orbital service provision for Russia-registered entities. Satellite operators are responding by restructuring joint ventures and localizing gateway assets to maintain market access.
State procurement offices are consolidating bandwidth purchasing through classified channels with multi-year backbone contracts. Defense and energy sector buyers are shifting from spot-market transponder leases toward dedicated network-as-a-service arrangements with uptime guarantees. This pattern concentrates most visibly in Moscow and the Central Federal District, where ground station infrastructure clusters and federal procurement authority overlap.
Russia Satellite Communications Market Segmentation
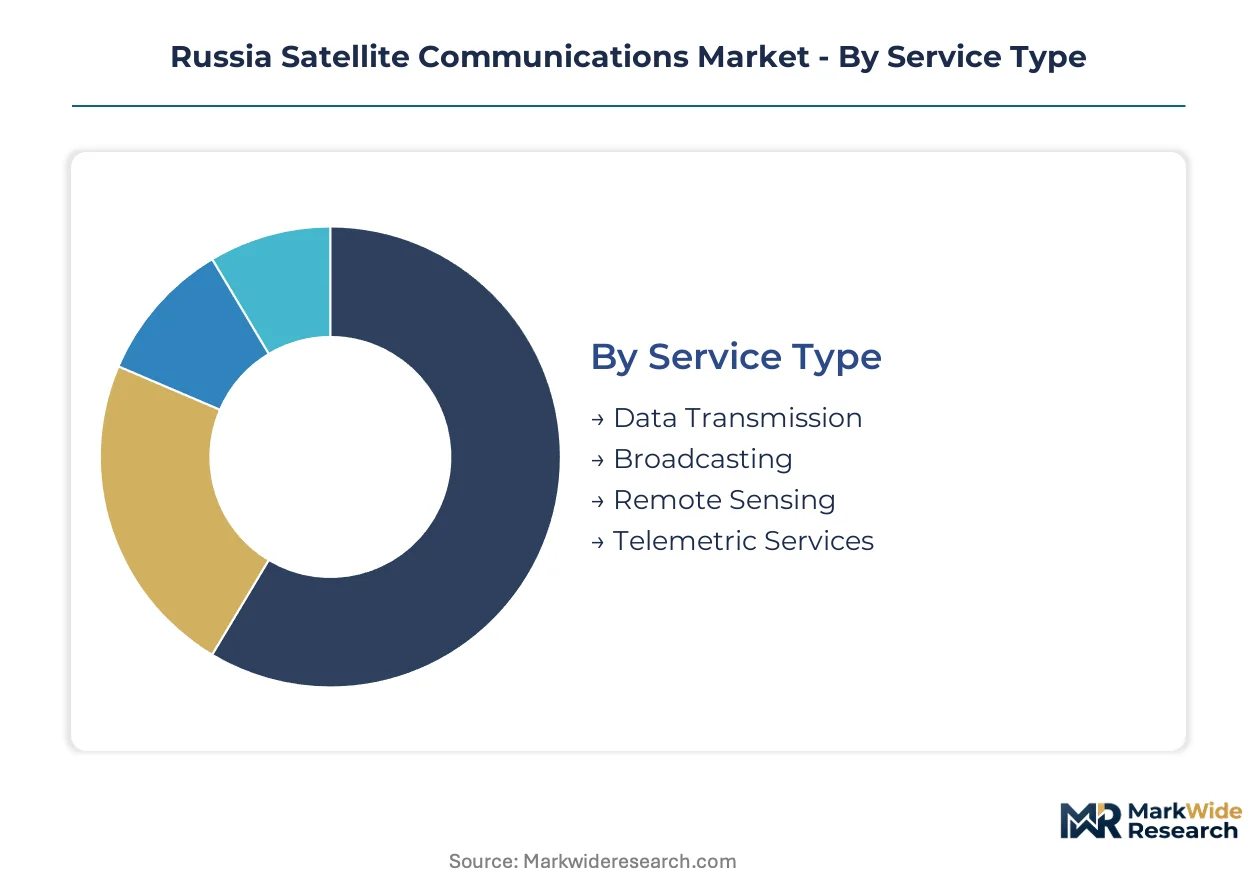
Russian satellite communications procurement channels diverge sharply by segment, with state classified contracts dominating defense and government verticals while commercial spot markets serve broadcasting and maritime mobility. Understanding these channel dynamics illuminates where pricing power concentrates and where infrastructure investment flows.
Service Type:
Broadcasting services flow through long-term transponder leases with state media conglomerates, while data transmission migrates toward managed network contracts with uptime SLAs. Remote sensing and telemetric services operate through specialized procurement channels tied to federal scientific programs.
- Data Transmission:High-throughput Ka-band and Ku-band links support pipeline monitoring, Arctic shipping coordination, and secure government backhaul. Demand concentrates in the Central Federal District where Roscosmos-licensed operators anchor federal backbone contracts for defense command networks.
- Broadcasting:Geostationary C-band and Ku-band distribution retains the largest revenue pool, delivering television signals across Russia's vast territory. Moscow-based state media procurement offices consolidate transponder purchasing through multi-year agreements with orbital slot holders.
- Remote Sensing:Earth observation data serves agricultural monitoring and environmental compliance under Roscosmos scientific mission coordination.
- Telemetric Services:Satellite telemetry supports launch vehicle tracking and orbital asset health monitoring from Vostochny and Baikonur cosmodromes.
Broadcasting dominates installed base. Data transmission is where expansion concentrates.
Application:
Cost tiers stratify sharply across applications, with defense and government commanding premium pricing through classified procurement while agriculture operates at economy margins with scattered pilot deployments.
- Government:Federal backbone networks require encrypted Ku-band and Ka-band connectivity with sub-50 millisecond latency guarantees. Procurement flows through Ministry of Digital Development frequency allocation compliance channels, concentrating in Moscow procurement offices.
- Defense:Secure tactical communications drive LEO constellation adoption for reduced latency versus legacy geostationary platforms. Northern Sea Route maritime patrol and Arctic base connectivity represent the fastest-climbing demand vertical within this segment.
- Agriculture:Precision farming IoT pilots in the Black Earth region remain nascent, with constellation service bundling still unproven at commercial scale.
- Disaster Management:Emergency communications backup leverages portable VSAT terminals for rapid deployment to Siberian and Far East regions with terrestrial infrastructure gaps.
Defense commands premium pricing tiers. Agriculture presents the steepest expansion trajectory if pilot-to-scale conversion succeeds.
End User:
Volume concentration varies by customer type, with telecom operators absorbing bulk transponder capacity while maritime and aviation represent emerging mobility segments with specialized terminal requirements.
- Telecom Operators:RSCC and domestic carriers lease orbital capacity for rural broadband backhaul and cellular network extension. Procurement centralizes through Moscow-based state procurement offices with multi-year backbone contracts.
- Maritime:Northern Sea Route shipping year-round navigation windows create pull for low-latency LEO connectivity that geostationary platforms cannot deliver. AltegroSky GC anchors regional service through Siberian and Far East teleport infrastructure.
- Aviation:In-flight connectivity demand remains underdeveloped versus Western markets, with regulatory certification bottlenecks constraining fleet retrofit adoption.
- Broadcasting Companies:State media and private television networks depend on C-band and Ku-band distribution for nationwide signal reach.
Telecom operators dominate installed base. Maritime is where expansion concentrates.
Technology:
Supply concentration rests with orbital slot holders for geostationary platforms while LEO constellation deployment depends on launch capacity access from domestic cosmodromes.
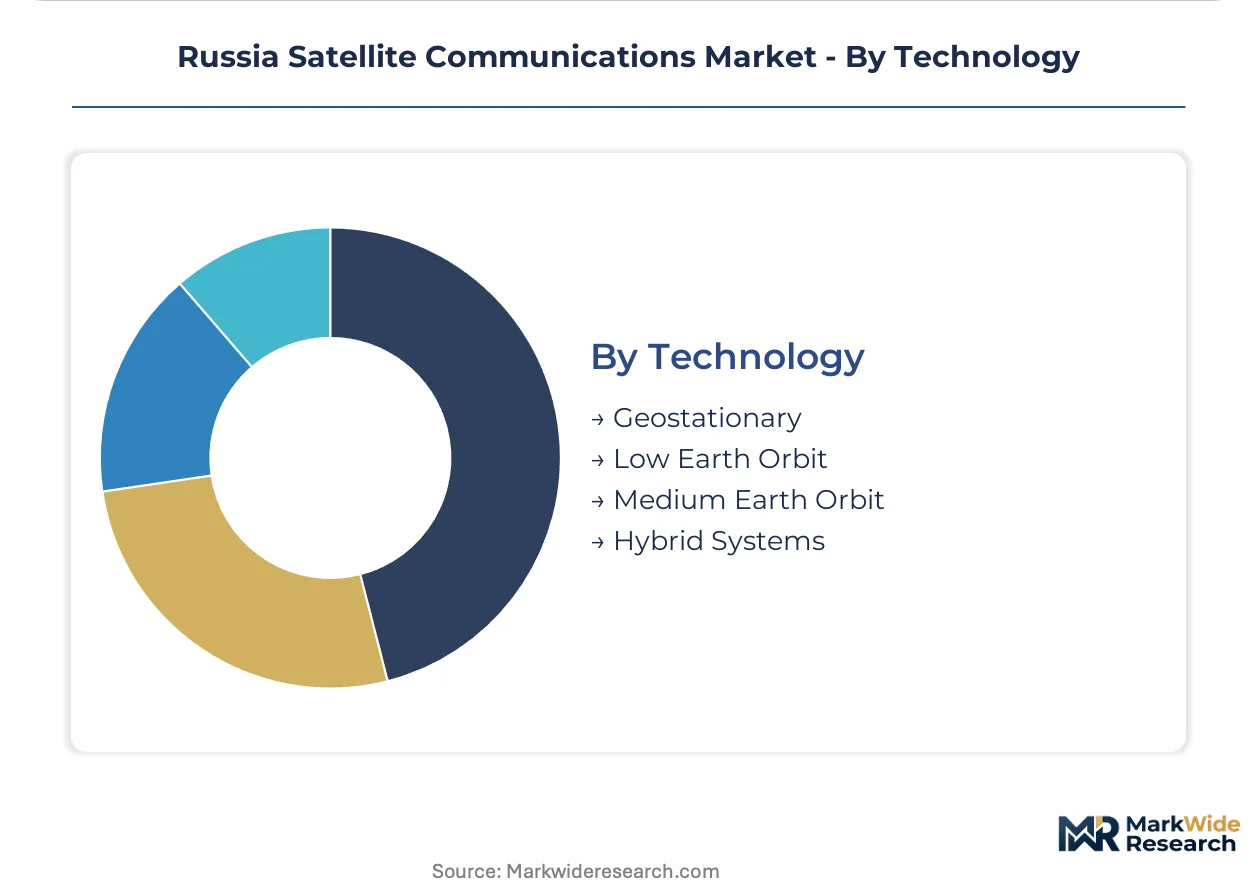
- Geostationary:Historically dominant C-band and Ku-band platforms provide television broadcast backbone and government backhaul. RSCC leverages its orbital slot portfolio to sustain nationwide coverage dominance through federal contracts.
- Low Earth Orbit:Reduced latency architectures displace legacy geostationary systems for defense command networks and Arctic maritime mobility. Russian military procurement accelerates LEO bandwidth adoption where sub-50 millisecond thresholds prove critical.
- Medium Earth Orbit:Intermediate altitude systems offer compromise latency-coverage tradeoffs for regional connectivity applications.
- Hybrid Systems:Gateway coordination protocols integrating LEO and GEO assets demand new ground station expertise that legacy teleport operators lack.
Geostationary dominates installed base. Low Earth Orbit is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's satellite communications infrastructure clusters around Moscow procurement offices and cosmodrome launch capacity, with regional demand patterns tracking federal district economic specialization and Arctic maritime corridors.
Central Federal District
Moscow anchors national bandwidth procurement through Ministry of Digital Development offices and Roscosmos licensing authorities. Federal backbone contracts for defense command networks concentrate here, with state procurement offices consolidating multi-year satellite service agreements. The district hosts RSCC headquarters and primary teleport infrastructure serving nationwide coverage mandates.
Far East Federal District
Year-round Northern Sea Route navigation drives low-latency LEO connectivity demand from maritime operators. Vostochny Cosmodrome launch capacity supports constellation deployment timelines, though scheduling bottlenecks constrain orbital asset replacement velocity. AltegroSky GC anchors regional service through Siberian teleport networks serving extractive industries.
Siberian Federal District
Pipeline monitoring traffic from energy infrastructure generates dedicated Ku-band and Ka-band contract demand. JSC Gazprom Space Systems specializes in low-latency uptime guarantees for remote energy-sector satellite links. Regional teleport gaps present white space for integrated ground-segment operators.
Northwestern Federal District
Arctic base connectivity and maritime patrol operations accelerate military LEO bandwidth procurement where sub-50 millisecond latency thresholds prove critical. Saint Petersburg hosts secondary procurement offices for scientific mission coordination under Roscosmos programs. The district bridges European Russia with polar orbital coverage requirements.
Southern Federal District
Black Sea maritime mobility and precision farming pilots in adjacent Black Earth region create scattered IoT deployment opportunities. Agricultural applications remain nascent, with constellation service bundling unproven at commercial scale. Regional demand tracks seasonal patterns rather than continuous bandwidth consumption.
Russia Satellite Communications Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Russian satellite communications sector. State-backed orbital slot holders dominate geostationary coverage through federal backbone contracts, while regional teleport operators capture Far East connectivity margins. Three archetypes structure competition: orbital asset owners with licensing advantages, ground-segment specialists with geographic density, and constellation service bundlers targeting vertical applications. Consolidation pressure operates through joint venture restructuring for foreign market access and domestic gateway localization mandates.
Within the state-backed tier, Russian Satellite Communications Company (RSCC) and JSC Gazprom Space Systems exemplify orbital asset owners leveraging federal contracts for nationwide coverage dominance. AltegroSky GC occupies a position among regional specialists anchoring Siberian and Far East connectivity through teleport network density. These three entities represent the core competitive structure: RSCC with orbital slot portfolio depth, Gazprom Space Systems with energy-sector vertical specialization, and AltegroSky GC with geographic concentration in underserved eastern territories.
| Leading Market Players |
|---|
| Russian Satellite Communications Company (RSCC) |
| AltegroSky GC |
| Hughes Network Systems, LLC |
| RTCOMM (JSC RTComm.RU) |
| JSC Gazprom Space Systems |
| GeoTelecommunications, LLC |
| Konnect, Russia (LLC Eutelsat Networks) |
| Gonets Satellite System |
| SCANEX Group |
| Others |
Pricing and Supply Chain Analysis
Multi-year backbone contracts with Roscosmos-licensed operators lock in supply access for federal procurement offices while anchoring price visibility across defense and energy verticals. These arrangements concentrate pricing power with orbital slot holders who control gateway infrastructure in Moscow and the Central Federal District.
Pricing Analysis
Ministry of Digital Development frequency allocation rules dictate the pricing tier structure across Russian satellite communications, separating encrypted Ku-band defense contracts from standard broadcasting transponder leases and economy-grade agricultural IoT pilots. Three-tier pricing stratifies across premium latency-guaranteed services, standard bandwidth commitments, and economy spot-market access. Cost compression in the premium tier is intensifying because import substitution mandates inflate domestic ground station electronics procurement versus global alternatives. Government buyers exhibit the least price sensitivity due to classified procurement channels, while precision farming operators in the Black Earth region face acute budget constraints.
Supply Chain Analysis
Russia and China anchor satellite manufacturing and launch vehicle production for the domestic communications sector, with Baikonur and Vostochny cosmodromes feeding from Kazakhstan and Far East Federal District launch capacity. Critical dependencies include radiation-hardened electronics, high-frequency components, and specialized propulsion systems. Single-source vulnerability concentrates around Baikonur scheduling bottlenecks that constrain constellation deployment velocity. Distribution runs through state procurement offices in Moscow and integrated teleport operators serving Siberian and Far East extractive industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal procurement consolidation through classified channels is shifting buyer power toward Ministry of Digital Development offices and defense command networks, fragmenting commercial spot-market leverage.
For Market Incumbents: Compound orbital slot advantages by deepening federal backbone contract renewals while localizing gateway assets to preempt foreign constellation joint venture restrictions. Counter LEO-GEO integration complexity threats through targeted hiring of astrodynamics talent from university pipeline programs. Prioritize certification investment for Ministry of Digital Development cybersecurity compliance to maintain access to premium pricing tiers. For New Entrants and Emerging Players: Lead with Far East teleport infrastructure gaps as the most penetrable white space, where AltegroSky GC's regional density remains incomplete and extractive industry demand outstrips supply. Target Siberian pipeline monitoring and Northern Sea Route maritime mobility as bundled service entry points. Pursue go-to-market angles anchored in domestic ground-segment localization mandates that foreign competitors cannot satisfy without joint venture restructuring. For Investors and Strategic Acquirers: Regional teleport operators with cosmodrome adjacency represent the priority acquisition archetype, capturing Far East connectivity margins as Northern Sea Route shipping expands year-round navigation windows. Long-term viability hinges on positioning ahead of LEO constellation deployment waves that will displace legacy geostationary revenue pools. Watch Roscosmos licensing requirement tightening as the inflection signal for market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Localization | Ministry of Digital Development mandates reserve market access for Russia-registered entities with domestic ground assets. |
| LEO Constellation Deployment | Russian military procurement accelerates adoption where sub-50 millisecond latency thresholds prove critical for tactical communications. |
| Cybersecurity Certification Investment | Federal backbone contracts require encrypted network hardening that creates adjacent revenue for domestic providers. |
| Far East Teleport Expansion | Vostochny Cosmodrome launch capacity supports constellation timelines for Siberian and Arctic maritime connectivity gaps. |
| Joint Venture Restructuring | Roscosmos licensing frameworks force foreign operators to localize gateway assets to maintain orbital service provision rights. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Roscosmos orbital registration filings, Ministry of Digital Development frequency allocation records, and federal procurement databases. Interviews with satellite operators, teleport infrastructure managers, defense procurement officers, and energy-sector connectivity planners informed demand-side validation. Secondary sources include customs data on ground station electronics imports, cosmodrome launch manifests, and state media transponder lease disclosures. Bottom-up capacity utilization models triangulate against top-down federal spending pattern analysis.
Segmentation dimensions modeled include service type, application vertical, end-user category, and orbital architecture across the analysis window. The quantitative framework projects value expansion through installed base replacement cycles, LEO constellation penetration rates, and Ka-band high-throughput migration patterns. CAGRs derive from satellite bandwidth demand elasticity in Arctic maritime corridors and defense command network procurement velocity. Industry-specific inputs capture Northern Sea Route shipping volume trajectories and pipeline monitoring uptime guarantee pricing.
The analysis sits within stated boundaries; outcomes outside Roscosmos licensing stability, frequency allocation continuity, or launch capacity scheduling would require recalibration. Forecasts reflect assumptions about import substitution cost trajectories and 5G spectrum encroachment resolution timelines. Recalibration cycles align with material shifts in federal procurement consolidation patterns and LEO-GEO hybrid network deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Transponder Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Canada Satellite Connectivity Market
Satellite
Latin America Satellite Connectivity Market
Satellite
GEO Satellite Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Global Small Satellite Service Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
High-Throughput Satellite Market
Satellite
North America Remote Sensing Satellites Market
Satellite
North America Satellite Manufacturing Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
EMEA Satellite Antenna Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Middle East Satellite Communications Market