
 Asia Pacific Small UAV Market | 2026-2036
Asia Pacific Small UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Small UAV Market Outlook
Defense procurement consolidation across Southeast Asian militaries is expanding the addressable order base for indigenous UAV suppliers. SZ DJI Technology Co., Ltd. leverages its Shenzhen manufacturing base to dominate consumer and prosumer segments across the region. Terra Drone Corporation anchors its position in industrial inspection through Tokyo-developed flight management software. Autel Robotics Co., Ltd. competes aggressively on price-performance ratios in the enterprise video segment.
Asia Pacific small UAVs denote uncrewed aerial vehicles below twenty-five kilograms maximum takeoff weight, typically powered by lithium-polymer batteries and controlled via ground stations or autonomous waypoint navigation for commercial, civil, and tactical missions. Rotary-wing platforms sustain the largest volume share due to vertical takeoff requirements in dense urban environments and jungle terrain across Indonesia and Malaysia. Fixed-wing systems dominate mapping and agricultural survey applications where endurance exceeds ninety minutes. Thermal Imaging and LiDAR technology segments capture premium pricing in infrastructure and energy inspection workflows.
Japan's Ministry of Economy, Trade and Industry enforces JIS standards for flight reliability, while Australia's Civil Aviation Safety Authority mandates remote pilot licensing tiers that shape operator economics. India's DGCA drone regulations create compliance thresholds that filter out informal operators and formalize channel structures. Stakeholders must monitor evolving beyond-visual-line-of-sight rules across multiple national aviation authorities to calibrate product roadmaps and certification investments.
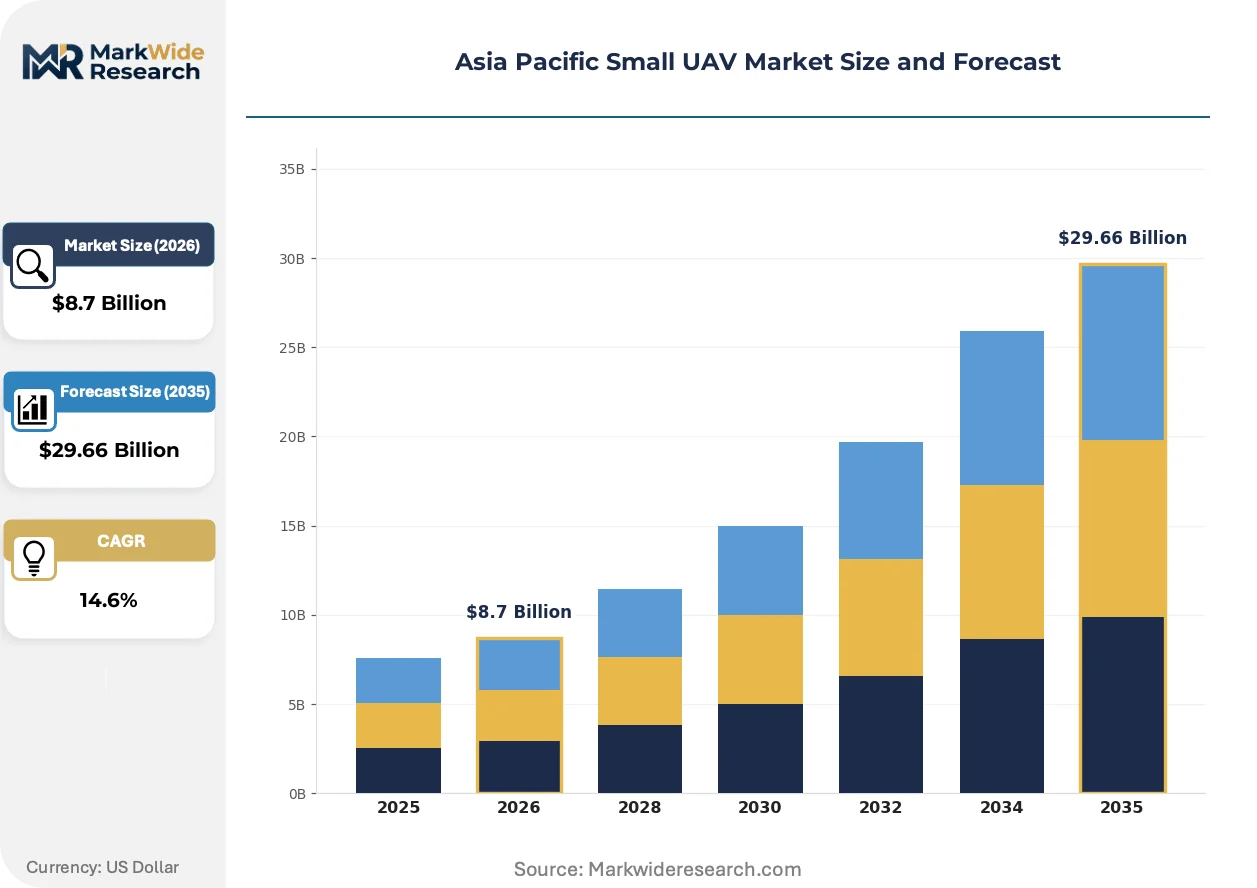
Market Dynamics
Defense ministries across Southeast Asia are consolidating rotary-wing procurement for border surveillance missions, while India's DGCA liberalization of beyond-visual-line-of-sight operations is unlocking commercial flight corridors previously restricted to military operators.
Growth Catalysts
- Beyond-visual-line-of-sight liberalization:India's DGCA revised drone rules removed altitude and distance restrictions for certified commercial operators, expanding addressable mission profiles for infrastructure inspection and logistics.
- Autonomous pit mapping demand:Australia's mining corridor operators deploy fixed-wing UAVs for volumetric surveying, replacing manned aerial surveys with battery-powered platforms capable of sub-centimeter photogrammetry.
- JIS flight reliability standards:Japan's Ministry of Economy, Trade and Industry enforces certification thresholds that filter out low-reliability imports, creating protected demand for compliant systems in disaster response and energy inspection.
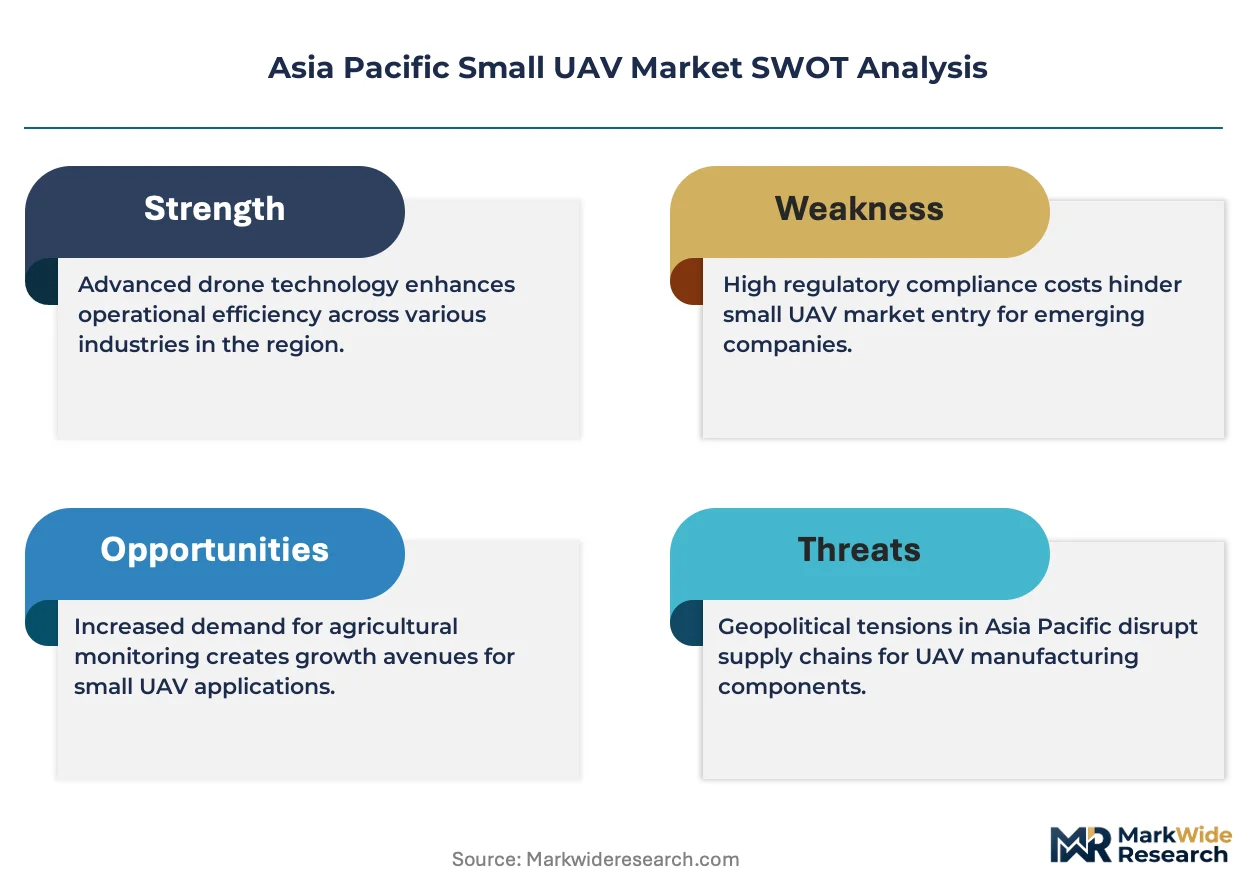
Market Restraints
- Lithium-polymer supply concentration:Cathode material processing clusters in China create input cost volatility and geopolitical exposure for battery-dependent platforms across the region.
- Remote pilot licensing tiers:Australia's Civil Aviation Safety Authority mandates tiered certification costs that compress operator margins in price-sensitive agricultural spraying segments.
- Weather envelope limitations:Tropical precipitation and humidity degradation constrain rotary-wing flight hours during monsoon seasons across Indonesia and Malaysia.
Strategic Opportunities
- Philippine archipelago logistics:Island-to-island cargo UAV corridors remain underpenetrated due to fragmented aviation authority coordination, creating first-mover advantages for integrated flight-management providers.
- Thermal-LiDAR convergence:Combined sensor payloads enable simultaneous infrastructure defect detection and dimensional modeling, commanding premium pricing in energy transmission and pipeline monitoring.
- Vietnam's renewable energy inspection:Wind farm construction mandates create regulatory tailwinds for automated blade-defect monitoring using autonomous waypoint navigation.
Industry Challenges
- Beyond-visual-line-of-sight certification timelines:Multi-jurisdictional approval processes across ASEAN aviation authorities delay product launches by 18-24 months.
- Autonomous navigation IP complexity:Flight management software licensing disputes between Tokyo-developed platforms and Shenzhen hardware integrators create supply chain friction.
- Ground station integration:Legacy mining and energy SCADA systems require custom protocol bridges, extending deployment cycles and technical service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Small UAV Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Rotary Wing, Hybrid, Mini End User: Agriculture, Defense, Inspection, Media Technology: GPS, LiDAR, Thermal Imaging, FPV Purpose: Surveillance, Delivery, Mapping, Research |
| Companies Covered | SZ DJI Technology Co., Ltd., Hubsan, MicroMultiCopter Aero Technology Co., Ltd., Terra Drone Corporation, Autel Robotics Co., Ltd., EHang Holdings Limited, Chengdu Aircraft Industry (Group) Co., Ltd, XAG Co., Ltd, ACSL, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Small UAV Market Strategic Shifts
Sensor miniaturization and autonomous flight management are compressing the cost-performance frontier for commercial UAV operations, while regulatory harmonization efforts across ASEAN aviation authorities are reshaping certification investment priorities.
Edge-computing payloads are integrating real-time defect detection algorithms directly onboard lithium-polymer-powered platforms, eliminating ground-station latency for critical infrastructure inspection. Mining operators in Western Australia deploy these systems for autonomous pit mapping with sub-hour data turnaround. The technology is integrating photogrammetry and thermal anomaly detection into unified workflow outputs, compressing survey crew requirements by eliminating separate flight passes.
India's DGCA beyond-visual-line-of-sight rules create a template for ASEAN aviation authority coordination, with Vietnam and Thailand drafting harmonized remote pilot licensing frameworks. The industrial consequence is reduced regulatory arbitrage between national markets, forcing suppliers to design for the strictest certification tier. Agricultural spraying and logistics segments in Southeast Asia face the steepest compliance investment curves as rules formalize.
Equipment-as-a-service contracting is displacing capital purchase models in Australia's mining corridor, with Rio Tinto and BHP preferring per-flight-hour pricing bundled with predictive maintenance. This compresses supplier working capital cycles while transferring airframe obsolescence risk to OEMs. The shift is most visible in fixed-wing mapping platforms where sensor refresh cycles accelerate with LiDAR resolution improvements.
Asia Pacific Small UAV Market Segmentation
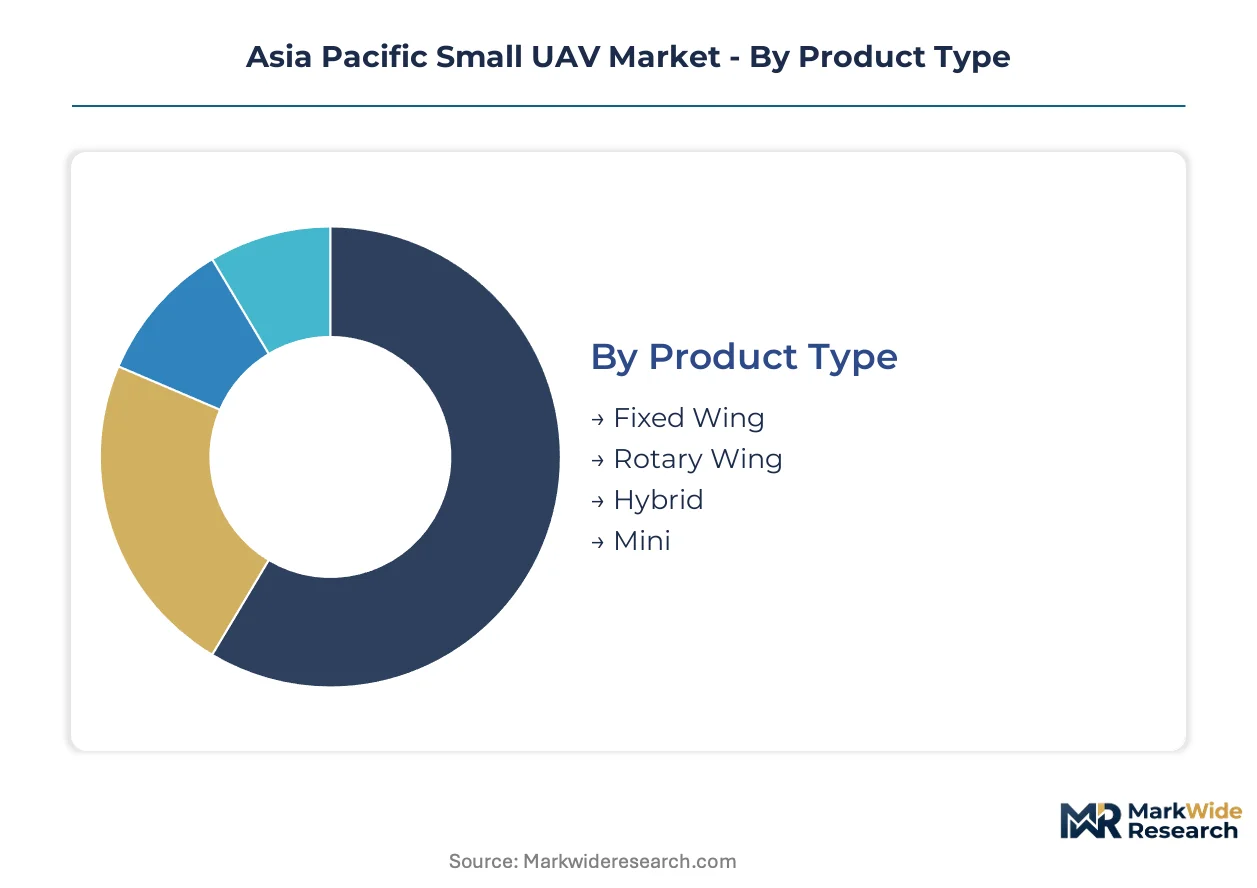
Platform architecture and sensor integration define procurement priorities across Asia Pacific defense and commercial operators. Segment boundaries blur as multi-mission payloads penetrate traditional application silos, forcing suppliers to certify flexible configurations rather than single-purpose designs.
Product Type:
Airframe geometry dictates operational envelope and certification pathway across tropical and temperate flight conditions in the region.
- Fixed Wing:Battery-powered platforms with rigid lifting surfaces achieve endurance exceeding ninety minutes for volumetric surveying. Australia's mining corridor operators deploy these systems for autonomous pit mapping, replacing manned aerial surveys with sub-centimeter photogrammetry output.
- Rotary Wing:Multi-rotor configurations with vertical takeoff capability dominate dense urban environments and jungle terrain across Indonesia and Malaysia. Defense ministries in Southeast Asia consolidate procurement of these systems for border surveillance missions requiring hover-and-stare persistence.
- Hybrid:Tilt-rotor and tailsitter architectures combine VTOL flexibility with fixed-wing efficiency for extended-range logistics corridors.
- Mini:Sub-250 gram platforms operate below most registration thresholds, penetrating consumer and tactical reconnaissance niches.
Rotary Wing leads on scale; Hybrid leads on momentum.
End User:
Customer procurement sophistication varies sharply across public and private budget cycles in the region.
- Agriculture:Fleet operators in Vietnam and Thailand deploy spray-capable rotary platforms for precision chemical application. Australia's Civil Aviation Safety Authority mandates tiered remote pilot certification that compresses margins in price-sensitive spraying segments.
- Defense:Militarized variants with encrypted datalinks and hardened ground stations anchor procurement volumes. India's DGCA liberalization of beyond-visual-line-of-sight rules creates compliance templates filtering into ASEAN defense acquisition frameworks.
- Inspection:Energy transmission and pipeline operators command premium pricing for combined thermal-LiDAR payloads.
- Media:Content production houses drive volume in compact camera-gimbal configurations for broadcast and cinematography.
Defense leads on scale; Inspection leads on momentum.
Technology:
Sensor fusion and navigation autonomy determine platform value capture in mission-critical workflows.
- GPS:Multi-constellation receivers with RTK correction enable centimeter-level positioning for georeferenced mapping outputs. Japan's Ministry of Economy, Trade and Industry enforces JIS reliability standards that filter out low-accuracy imports in disaster response applications.
- LiDAR:Solid-state scanning arrays generate dense point clouds for infrastructure dimensional modeling. Mining operators in Western Australia integrate these payloads with edge-computing defect detection, compressing survey crew requirements.
- Thermal Imaging:Uncooled microbolometer sensors penetrate smoke and darkness for search-and-rescue and energy anomaly detection.
- FPV:First-person-view racing and cinematography platforms sustain consumer segment volume with low-latency video transmission.
GPS leads on scale; LiDAR leads on momentum.
Purpose:
Mission profile specificity shapes airframe-sensor pairing and operator training investment.
- Surveillance:Persistent observation missions require stabilized gimbals and encrypted datalinks for border and maritime domain awareness. Philippine archipelago logistics create underpenetrated corridors for island-to-island cargo routes currently served by conventional aviation.
- Delivery:Last-mile and medical supply chains in fragmented geography markets demand precision drop mechanisms and weather-resistant navigation. Vietnam's wind farm construction mandates create regulatory tailwinds for automated infrastructure monitoring using autonomous waypoint navigation.
- Mapping:Photogrammetry and LiDAR integration enables cadastral survey and construction progress monitoring.
- Research:Academic and environmental monitoring applications drive specialized payload integration for atmospheric and wildlife data collection.
Surveillance leads on scale; Delivery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale contrasts with Australia's resource-driven deployment intensity across the Asia Pacific small UAV landscape. National regulatory frameworks diverge sharply in certification stringency and operational scope. Industrial clusters concentrate in mining corridors, defense procurement hubs, and precision agriculture zones.
China
Shenzhen anchors global hardware production for lithium-polymer-powered platforms serving consumer and enterprise segments. The Ministry of Industry and Information Technology enforces GB standards for radio transmission and flight control reliability. Guangdong Province hosts dense supplier ecosystems for gimbal stabilization and solid-state LiDAR modules.
Australia
Western Australia's Pilbara mining corridor drives autonomous pit mapping demand from Rio Tinto and BHP operations. The Civil Aviation Safety Authority mandates tiered remote pilot licensing that shapes operator economics in agricultural spraying. Queensland's renewable energy construction pipeline creates inspection workflows for wind farm blade monitoring.
India
DGCA beyond-visual-line-of-sight liberalization unlocks commercial corridors for infrastructure inspection and logistics pilots previously restricted to military operators. The Directorate General of Civil Aviation compliance thresholds filter informal operators and formalize distribution channels. Karnataka's aerospace cluster near Bangalore hosts flight management software development for agricultural fleet operators.
Japan
Tokyo-developed platforms dominate industrial inspection through METI-enforced JIS flight reliability standards. The Ministry of Economy, Trade and Industry certification thresholds protect domestic demand in disaster response and energy infrastructure monitoring. Chubu region manufacturers supply precision rotary-wing systems for nuclear facility inspection protocols.
Vietnam
Mekong Delta agricultural operators deploy spray-capable rotary platforms for precision chemical application on rice and coffee plantations. Wind farm construction mandates create regulatory tailwinds for automated blade-defect monitoring using autonomous waypoint navigation. Ho Chi Minh City logistics providers pilot island-to-island cargo corridors for archipelago supply chains.
Asia Pacific Small UAV Market Competitive Environment
Shenzhen producers anchor the hardware tier; Tokyo specialists hold the flight management software tier. The vendor base concentrates around manufacturing scale in southern China and certification-compliant system integration in Japan. Two strategic archetypes dominate: vertically integrated hardware OEMs and software-centric service platforms. Competitive moves center on sensor payload partnerships and per-flight-hour contracting models.
Within the hardware manufacturing tier, SZ DJI Technology Co., Ltd. exemplifies scale-driven production architecture, while Terra Drone Corporation occupies a position in industrial service integration. Autel Robotics Co., Ltd. represents price-performance positioning in the enterprise video segment. These three companies illustrate the geographic and functional segmentation shaping procurement decisions across defense, mining, and agricultural end markets.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Hubsan |
| MicroMultiCopter Aero Technology Co., Ltd. |
| Terra Drone Corporation |
| Autel Robotics Co., Ltd. |
| EHang Holdings Limited |
| Chengdu Aircraft Industry (Group) Co., Ltd |
| XAG Co., Ltd |
| ACSL |
| Others |
Value Chain & Pricing Dynamics
Captive lithium-polymer cell production in Shenzhen anchors both component supply security and pricing power for rotary-wing platform OEMs serving Southeast Asian defense procurement. This integration choice insulates dominant suppliers from cathode material volatility while compressing margins for battery-dependent assemblers lacking upstream chemical processing.
Pricing Analysis
Capacity additions in Guangdong Province are reshaping price floors for consumer-grade multi-rotor systems, forcing economy-tier competitors toward per-flight-hour service contracts. Three-tier pricing structure across certified-commercial, standard-prosumer, and economy-consumer levels separates DGCA-compliant platforms from uncertified imports. Pricing pressure stems from Australia's CASA-mandated remote pilot licensing tiers that inflate operator costs and squeeze hardware budgets. Agricultural spraying segments in Vietnam and Thailand exhibit highest price sensitivity, while mining corridor operators in Western Australia accept premium positioning for sub-centimeter photogrammetry accuracy.
Supply Chain Analysis
Engineering talent availability in Shenzhen, Dongguan, and Hangzhou concentrates flight controller firmware development and gimbal stabilization manufacturing. Solid-state LiDAR modules, uncooled thermal microbolometers, and multi-constellation RTK-GPS receivers constitute critical sensor inputs. Single-source vulnerability runs through cathode precursor processing clusters in China's Hunan and Fujian provinces. Distribution runs through Tokyo-certified system integrators for Japanese industrial inspection, direct OEM channels for Australian mining deployments, and formalized distributor networks filtering DGCA compliance in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific Small UAV procurement operates as a geographic-arbitrage play where India's DGCA beyond-visual-line-of-sight liberalization creates cost-advantaged flight corridors unavailable under Japan's stricter METI enforcement regime.
For Market Incumbents: Extend certification-compliant product architectures across ASEAN aviation authorities to amortize compliance investment across multi-jurisdictional defense tenders. Threaten emerging Shenzhen hardware integrators with flight management software licensing disputes by reinforcing Tokyo-developed IP positions. Prioritize backward integration into solid-state LiDAR module production to capture premium payload margins in energy transmission inspection. For New Entrants and Emerging Players: The price-point gap between DJI-dominated prosumer tiers and informal agricultural operators in Indonesia creates white-space for mid-tier rotary platforms with spray-capable payloads. Philippine archipelago logistics corridors remain underpenetrated due to fragmented aviation authority coordination. Penetrate through equipment-as-a-service contracting bundled with predictive maintenance to displace capital purchase resistance among island-to-island cargo pilots. For Investors and Strategic Acquirers: Roll-up economics work for flight-management software specialists because autonomous navigation IP complexity creates acquisition synergies across hardware-agnostic platform layers. Five-to-ten year viability hinges on regulatory harmonization completion across ASEAN aviation authorities. Target acquisition archetype: Tokyo-developed software platforms with JIS certification compliance and existing BHP or Rio Tinto deployment references. Watch for India's DGCA template adoption by Vietnam and Thailand civil aviation regulators as inflection signal for compliance-investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Certification Investment | DGCA-compliant platforms unlock Indian infrastructure inspection corridors previously restricted to military operators. |
| Sensor Payload Partnership Formation | Thermal-LiDAR convergence enables simultaneous defect detection and dimensional modeling for pipeline operators. |
| Per-Flight-Hour Service Contracting | Rio Tinto and BHP preference transfers airframe obsolescence risk from mining operators to OEM balance sheets. |
| Flight Management Software Licensing | Tokyo-developed platforms create supply chain friction with Shenzhen hardware integrators seeking autonomous navigation IP. |
| Regional Certification Harmonization Lobbying | ASEAN aviation authority coordination reduces 18-24 month multi-jurisdictional approval delays for product launches. |
Study Parameters
Bottom-up mining and agriculture fleet operator modeling reconciled against top-down Shenzhen manufacturing output tracking forms the analytical core of this study. Primary interviews with defense procurement officers, CASA-licensed remote pilots, energy transmission inspection contractors, and agricultural spraying fleet managers combined with secondary validation from DGCA regulatory filings, Australia's Civil Aviation Safety Authority licensing databases, METI JIS certification registries, and customs trade data for lithium-polymer battery exports. Triangulation across these sources grounds volume estimates in actual deployment records rather than shipment projections.
Input-output matrices map platform architecture, sensor integration, and end-use application across the projection horizon. Segmentation dimensions include airframe geometry, technology type, and purpose category, with regulatory framework stringency as an additional industry-specific modeling layer. CAGRs derive from deployment velocity in Australia's Pilbara mining corridor and India's liberalized commercial corridors, cross-referenced against cathode material supply constraints and monsoon-season flight hour degradation patterns.
Caveats apply where lithium-polymer supply concentration in China or multi-jurisdictional certification timeline extensions could materially shift the outlook. Forecasts embed assumptions regarding ASEAN aviation authority coordination progress and edge-computing payload adoption rates in Western Australian autonomous pit mapping. Material deviation in DGCA enforcement intensity or METI JIS standard revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Leasing Market
UAV
Global Drone Sensor Market
UAV
UAV Simulator Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Global Drone Inspection and Monitoring Market
UAV
North America Drones Market
UAV
Toy Drones Market
UAV
Consumer Drone Market
UAV
Drone-Based Consulting Services Market
UAV
Drone Lens Market
UAV
Military UAV Sensor Market
UAV
North America Tactical UAV Market
UAV
Global Drone Light Shows Market
UAV
Middle-East and Africa Drones Market
UAV
Drone Identification System Market
UAV
Inspection Drones in Confined Space Market