
 Asia-Pacific Satellite Connectivity Market | 2026-2036
Asia-Pacific Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Connectivity Market Analytics
Modular service bundling is realigning procurement patterns across enterprise and government buyers in the Asia-Pacific satellite connectivity sector. SpaceX leverages its vertically integrated launch-to-service stack to undercut traditional geostationary incumbents on deployment timelines. Kacific anchors its growth strategy on dedicated high-throughput capacity over the Pacific Islands, while SKY Perfect JSAT Holdings Inc. competes through premium broadcast and maritime mobility packages.
Asia-Pacific satellite connectivity encompasses the transmission of voice, data, and video signals via orbiting relay stations operating across C-band, Ku-band, Ka-band, and emerging Q/V-band frequencies, with link budgets engineered to overcome path loss across distances ranging from 600 kilometers in low Earth orbit to 35,786 kilometers in geostationary arc. Fixed Satellite Services dominate revenue generation due to long-term transponder lease contracts with broadcasters and telecom operators, while Low Earth Orbit Satellites represent the fastest-expanding deployment category as constellation operators slash latency for broadband and backhaul applications. Mobile Satellite Services capture concentrated margin pools from defense and aeronautical contracts requiring guaranteed availability in contested electromagnetic environments.
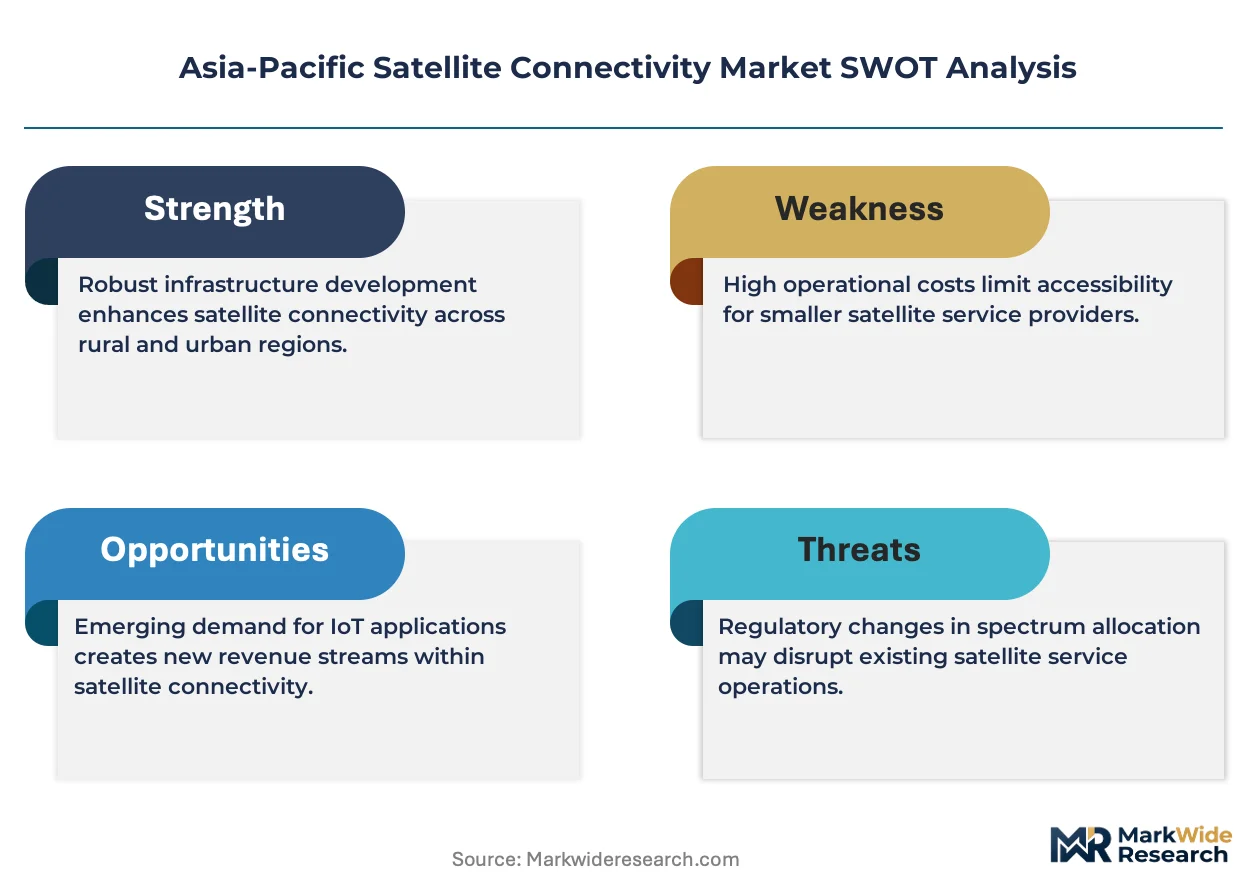
TRAI in India mandates priority spectrum allocation for satellite broadband to bridge rural digital divides, while Japan's MIC enforces orbital debris mitigation standards that elevate launch and operational compliance costs for new entrants. China's MIIT coordinates domestic frequency assignments through state-linked operators, creating asymmetric market access conditions for foreign constellation providers. Stakeholders must monitor evolving national security screening frameworks for foreign satellite ground infrastructure as geopolitical competition over orbital slot registrations intensifies across the region.
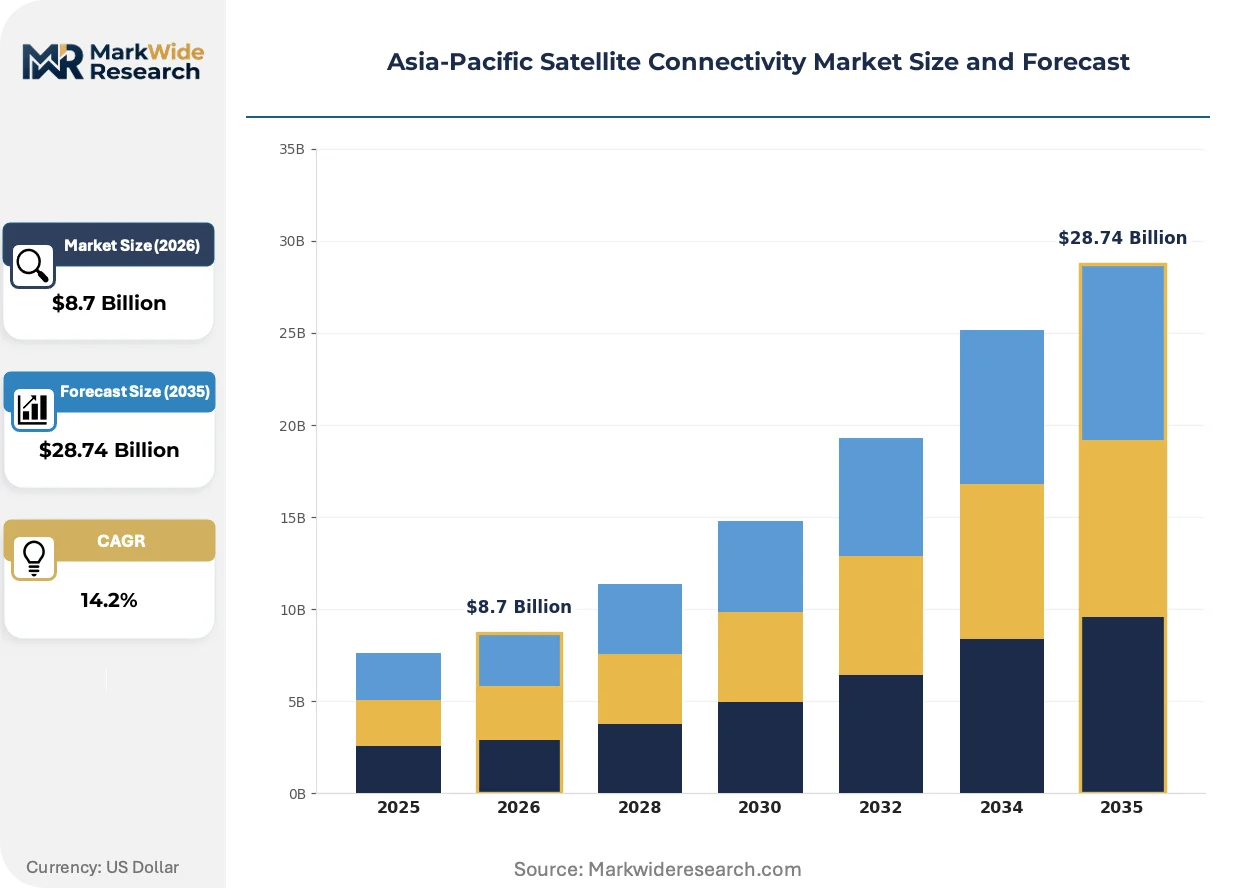
Market Dynamics
Low Earth orbit constellations are compressing latency benchmarks across maritime and aviation mobility segments, forcing geostationary operators to reprice transponder leases and accelerate high-throughput satellite deployments. This orbital-layer competition is restructuring capital allocation across the Asia-Pacific satellite connectivity sector.
Growth Catalysts
- TRAI spectrum mandates:India's priority allocation for satellite broadband in unserved districts accelerates rural backhaul deployment where terrestrial infrastructure gaps persist.
- Maritime digitalization:Fleet operators across Indonesian and Philippine archipelagic routes demand always-on connectivity for crew welfare and predictive engine monitoring systems.
- Ka-band proliferation:High-throughput spot beam architectures enable cost-per-bit reductions that unlock enterprise VPN and cellular backhaul contracts previously served by fiber.
Market Restraints
- Launch cost concentration:Dependence on limited heavy-lift vehicle availability from Chinese and US launch complexes creates deployment queue bottlenecks for constellation expansion.
- Orbital debris compliance:Japan's MIC mandates end-of-life deorbiting plans and collision avoidance systems that elevate insurance and operational overhead for new entrants.
- Spectrum interference limits:C-band reallocation for terrestrial 5G in Australia and South Korea compresses available link budgets for legacy broadcast and government networks.
Strategic Opportunities
- Pacific Island connectivity gaps:Nations including Vanuatu, Samoa, and Tonga lack submarine cable landing points, creating captive demand for satellite backhaul of mobile money and telehealth platforms.
- Q/V-band experimental licensing:Early-adopter regimes in Singapore and Australia permit trials in 40-50 GHz ranges that promise terabit-class throughput for data center interconnection.
- Defense sovereign capacity:Australia's AUKUS-aligned communications modernization and Japan's Space Domain Awareness programs fund dedicated military satellite procurements with premium availability requirements.
Industry Challenges
- RF engineering talent scarcity:Specialist workforce for phased array antenna design and link budget optimization concentrates in South Korea and Japan, constraining deployment velocity elsewhere.
- Ground segment integration complexity:Hybrid networks combining geostationary anchor stations with LEO user terminals require interoperable modem firmware that delays service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Connectivity Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Satellite Services, Mobile Satellite Services, Broadcast Services, VSAT Services Deployment: Geostationary Satellites, Low Earth Orbit Satellites, Medium Earth Orbit Satellites, Hybrid Solutions End User: Government, Military, Commercial, Telecom Connection Type: Broadband, Narrowband, Direct-to-Home, Backhaul |
| Companies Covered | Inmarsat, Kacific, SpaceX, China Aerospace Science and Technology Corporation, SKY Perfect JSAT Holdings Inc., Eutelsat, IPStar, SES S.A, Viasat, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Connectivity Market Evolving Landscape
Software-defined payload architectures are enabling satellite operators to reconfigure coverage footprints and frequency plans in orbit, reducing the risk of capacity misallocation against shifting demand patterns. This flexibility is altering how buyers contract for transponder services across the region.
Electronically steered flat-panel antennas are expanding into maritime and land-mobile applications where mechanically stabilized dishes impose size and maintenance penalties. Cruise operators and overland logistics fleets in Thailand and Malaysia are piloting these terminals for seamless beam handoff between satellites. The technology is expanding into price-sensitive segments previously restricted to geostationary fixed services.
China's MIIT coordinates domestic frequency assignments through state-linked operators, creating asymmetric market access conditions for foreign constellation providers seeking landing rights. This regulatory architecture compels international operators to form joint ventures with designated local entities for spectrum coordination and ground station placement. Foreign providers are responding by prioritizing indirect service models and hosted payload arrangements over direct-to-consumer retail.
Enterprise buyers are consolidating satellite connectivity purchasing through managed service integrators rather than contracting directly with space segment operators. Mining and energy extraction firms in Western Australia and Papua New Guinea now procure end-to-end network operations from specialized system integrators who bundle terrestrial fiber, cellular, and satellite failover. This purchasing consolidation concentrates pricing leverage among a handful of procurement decision-makers per vertical.
Asia-Pacific Satellite Connectivity Market Segmentation
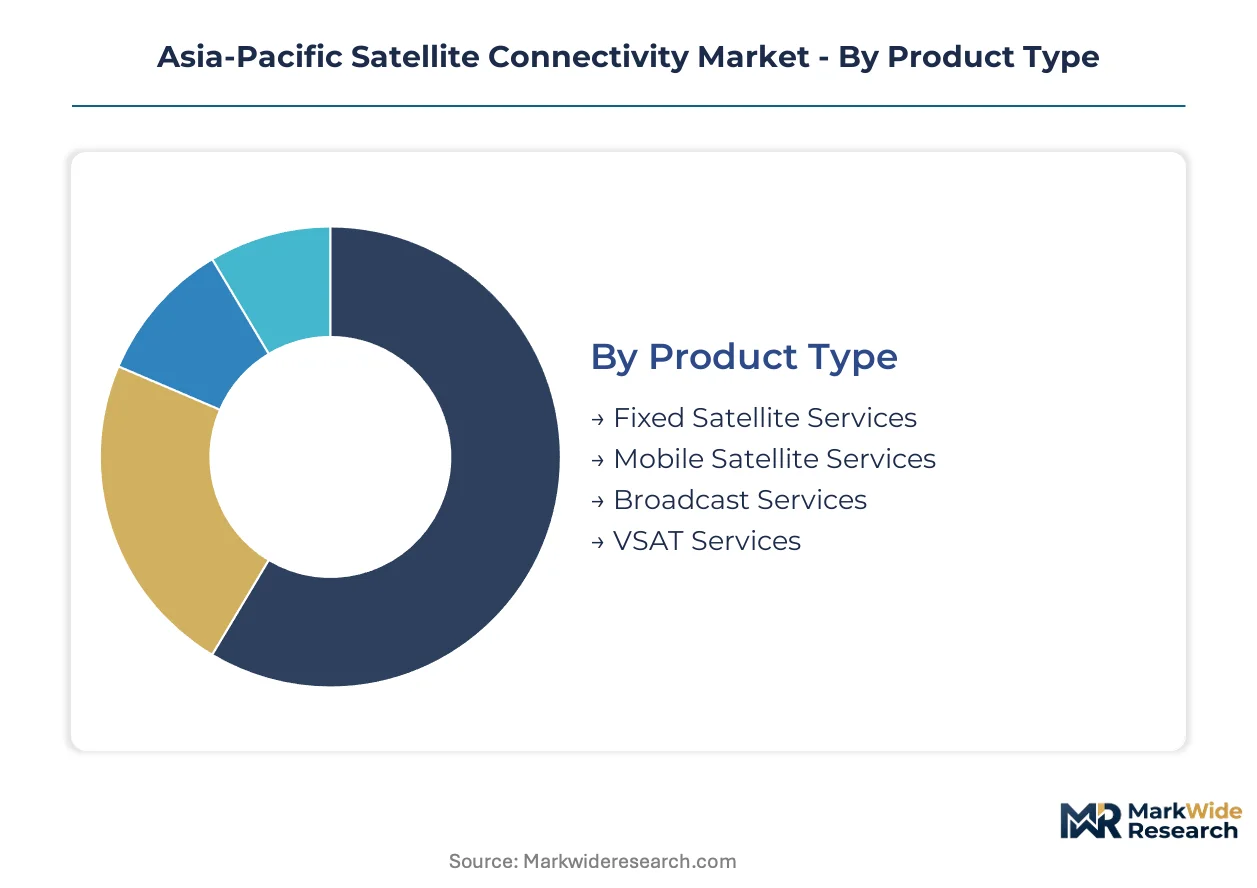
Satellite connectivity procurement in the Asia-Pacific region fragments across orbital architectures, service bundles, and end-user security classifications. Buyers prioritize latency performance, coverage reliability, and regulatory compliance when selecting between fixed broadcast capacity and dynamic LEO constellations.
Product Type:
Replacement cycles for satellite service contracts accelerate as legacy C-band leases expire and Ka-band spot-beam alternatives enter the market. Enterprise buyers renegotiate multi-year transponder agreements to capture throughput gains from high-throughput satellite deployments.
- Fixed Satellite Services:Long-term transponder leases dominate revenue through anchor contracts with broadcasters and telecom operators across Indonesia and the Philippines. Demand concentrates in archipelagic provinces where fiber backhaul remains economically unviable for terrestrial infrastructure builders.
- Mobile Satellite Services:Narrowband and broadband mobility packages serve maritime fleets and aeronautical routes requiring guaranteed availability in contested electromagnetic environments. Defense and commercial aviation contracts in Japan and Australia command premium pricing for sovereign capacity assurance.
- Broadcast Services:Direct-to-home television distribution and content delivery networks leverage geostationary arc stability for uninterrupted signal reception.
- VSAT Services:Enterprise VPN and rural banking networks deploy very small aperture terminals for two-way data exchange in remote mining and agricultural zones.
Volume placements concentrate in Fixed Satellite Services; the faster expansion belongs to Mobile Satellite Services as fleet operators digitize vessel operations.
Deployment:
Cost tiers separate established geostationary operators from capital-intensive constellation builders seeking scale economies through mass manufacturing.
- Geostationary Satellites:Mature orbital slot holdings at 35,786 kilometers deliver predictable coverage footprints for broadcast and government applications. TRAI spectrum mandates in India and MIC debris regulations in Japan shape operational compliance costs for incumbent operators.
- Low Earth Orbit Satellites:Constellation deployments at 600-1,200 kilometer altitudes slash latency benchmarks for broadband and backhaul applications. Maritime shipping corridors across Southeast Asian trade routes drive adoption as crew welfare and predictive maintenance systems demand always-on connectivity.
- Medium Earth Orbit Satellites:Intermediate altitude architectures balance coverage area with latency performance for regional navigation and messaging services.
- Hybrid Solutions:Integrated networks combine geostationary anchor capacity with LEO low-latency overlays for seamless service handoff.
Revenue gravity rests with Geostationary Satellites; the steepest expansion trajectory characterizes Low Earth Orbit Satellites as launch costs decline and terminal prices compress.
End User:
Application requirements dictate security clearances, availability guarantees, and spectrum priority access across buyer categories.
- Government:Civilian agencies procure satellite capacity for disaster response coordination and rural telehealth delivery in Pacific Island nations lacking submarine cable connectivity.
- Military:Australia's AUKUS-aligned communications modernization and Japan's Space Domain Awareness programs fund dedicated military satellite procurements with premium availability requirements.
- Commercial:Mining and energy extraction firms in Western Australia and Papua New Guinea consolidate purchasing through managed service integrators who bundle terrestrial fiber, cellular, and satellite failover.
- Telecom:Mobile network operators lease satellite backhaul to extend coverage into unserved districts where terrestrial infrastructure gaps persist.
Contract value concentrates in Military; the fastest volume growth emerges in Commercial as enterprise buyers outsource network operations to specialized integrators.
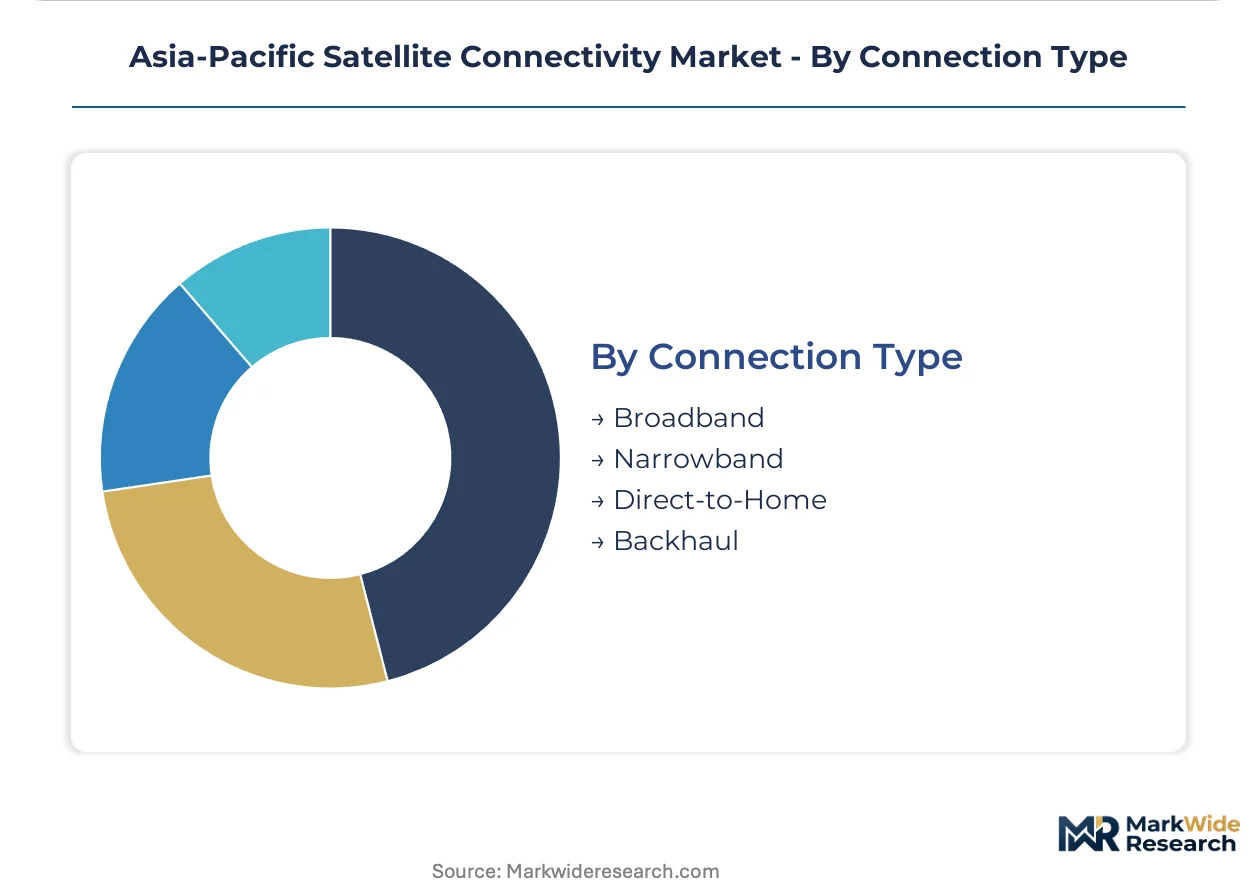
Connection Type:
Customer type segmentation reveals divergent bandwidth needs between consumer entertainment and mission-critical enterprise applications.
- Broadband:High-throughput spot beam architectures enable cost-per-bit reductions that unlock enterprise VPN and cellular backhaul contracts previously served by fiber in Indonesian provinces.
- Narrowband:Low-data-rate messaging and IoT telemetry serve agricultural sensor networks and maritime vessel tracking across archipelagic routes.
- Direct-to-Home:Consumer television reception remains concentrated in suburban and rural households beyond terrestrial broadcast coverage.
- Backhaul:Mobile network operators and remote enterprise sites rely on satellite transport for core network connectivity where fiber cannot be deployed.
Service volume clusters in Backhaul; Broadband climbs the fastest as Ka-band proliferation reduces per-megabit pricing toward fiber parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Satellite capacity production concentrates in China and Japan while consumption spreads across archipelagic Southeast Asian markets lacking terrestrial fiber alternatives. This geographic mismatch shapes operator strategies across the region.
China
China Aerospace Science and Technology Corporation dominates domestic satellite manufacturing while MIIT coordinates frequency assignments through state-linked operators. Foreign constellation providers face asymmetric market access conditions requiring joint ventures for landing rights. Beijing anchors national space policy while Shanghai clusters ground station engineering talent.
Japan
SKY Perfect JSAT Holdings Inc. leverages premium broadcast and maritime mobility packages to capture concentrated margin pools. MIC enforces orbital debris mitigation standards that elevate launch compliance costs for new entrants. Tokyo concentrates RF engineering specialists for phased array antenna design.
India
TRAI mandates priority spectrum allocation for satellite broadband to bridge rural digital divides across unserved districts. Mobile network operators lease satellite backhaul where terrestrial infrastructure gaps persist. Bangalore clusters system integrators bundling terrestrial fiber, cellular, and satellite failover for enterprise buyers.
Indonesia
Archipelagic provinces drive fixed satellite services demand where fiber deployment remains economically unviable for terrestrial infrastructure builders. Maritime shipping fleets expand broadband adoption for crew welfare and predictive engine monitoring systems. Batam anchors ground station placement for regional capacity distribution.
Australia
AUKUS-aligned communications modernization funds dedicated military satellite procurements with premium availability requirements. C-band reallocation for terrestrial 5G compresses available link budgets for legacy networks. Perth concentrates mining sector managed service integrators consolidating satellite connectivity purchasing.
Asia-Pacific Satellite Connectivity Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across orbital architectures and service bundles. Market structure tilts toward consolidation as vertically integrated launch-to-service stacks undercut traditional geostationary incumbents on deployment timelines. Three archetypes dominate: constellation operators with captive launch capacity, regional high-throughput specialists, and legacy broadcast incumbents repositioning for mobility services. Competitive moves center on spectrum coordination partnerships and ground segment integration alliances.
Among constellation operators with captive launch capacity, SpaceX exemplifies the vertically integrated archetype. Regional high-throughput specialists include Kacific, which anchors growth strategy on dedicated capacity over the Pacific Islands. Legacy broadcast repositioning is represented by SKY Perfect JSAT Holdings Inc., occupying a position in premium maritime mobility packages. These three players collectively illustrate the strategic divergence reshaping procurement patterns across enterprise and government buyers.
| Leading Market Players |
|---|
| Inmarsat |
| Kacific |
| SpaceX |
| China Aerospace Science and Technology Corporation |
| SKY Perfect JSAT Holdings Inc. |
| Eutelsat |
| IPStar |
| SES S.A |
| Viasat |
| Others |
Value Network & Pricing Analysis
Sovereign-backed operators in China and Japan anchor satellite manufacturing capacity, creating asymmetric pricing discipline where state-linked producers absorb launch cost volatility while private constellation builders face margin compression from heavy-lift queue bottlenecks.
Pricing Analysis
Margin tightening in enterprise backhaul tiers reflects SpaceX's vertically integrated launch-to-service stack undercutting geostationary incumbents on deployment timelines. Three-tier pricing structure across premium maritime mobility, standard enterprise VSAT, and economy narrowband IoT separates sovereign defense contracts from commercial fleet bundles. Cost-down pressure on Ka-band spot-beam capacity accelerates because terrestrial 5G reallocation in Australia and South Korea compresses legacy C-band link budgets. Mining and energy extraction firms in Western Australia exhibit highest price sensitivity through managed service integrator consolidation, while Japan's defense procurement commands lowest sensitivity via premium availability requirements.
Supply Chain Analysis
Dual-sourcing mandates from Australia's AUKUS-aligned programs and Japan's Space Domain Awareness initiatives require constellation operators to qualify multiple launch complexes and ground station networks. Manufacturing gravity centers on China, Japan, and South Korea for phased array antenna components and RF engineering talent. Raw material dependencies include gallium nitride semiconductors, specialized aluminum-lithium alloys, and radiation-hardened electronics. Single-source vulnerability concentrates in heavy-lift vehicle availability from Chinese and US launch complexes. Distribution runs through regional system integrators in Bangalore, Perth, and Batam who bundle terrestrial fiber, cellular, and satellite failover for enterprise buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low Earth orbit constellations are displacing geostationary architectures across maritime and aviation mobility segments, compressing latency benchmarks that legacy operators cannot match without orbital-layer reinvestment.
For Market Incumbents: Deploy software-defined payload architectures to reconfigure coverage footprints in orbit against shifting demand patterns. Accelerate high-throughput satellite deployments to defend transponder lease pricing from Ka-band spot-beam alternatives. Counter SpaceX's vertically integrated stack through spectrum coordination partnerships with Pacific Island regulators and ground segment integration alliances with regional system integrators. For New Entrants and Emerging Players: Pacific Island nations lacking submarine cable landing points represent the most penetrable buyer archetype for dedicated satellite backhaul of mobile money and telehealth platforms. Vanuatu, Samoa, and Tonga offer white-space demand with captive government procurement and minimal incumbent saturation. Pursue experimental Q/V-band licensing in Singapore and Australia to establish terabit-class throughput credentials for data center interconnection contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional high-throughput specialists with Pacific Island spectrum holdings and established ground station footprints in Batam and Port Moresby. Long-term viability hinges on constellation operators achieving launch cost scale economies through mass manufacturing and captive heavy-lift capacity. Monitor Japan's MIC debris compliance enforcement as inflection indicator for operational overhead escalation that could strain undercapitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Coordination Partnership | Secures priority Ka-band allocation with Indonesia's SDPPI for archipelagic coverage expansion. |
| Ground Segment Integration Alliance | Combines geostationary anchor stations with LEO terminals through interoperable modem firmware development. |
| Software-Defined Payload Deployment | Enables in-orbit reconfiguration of coverage footprints against shifting maritime and enterprise demand. |
| Pacific Island Landing Rights Acquisition | Captures sovereign backhaul demand in Vanuatu and Tonga lacking submarine cable connectivity. |
| Defense Sovereign Capacity Contract | Locks premium pricing through Australia's AUKUS-aligned communications modernization program. |
Research Methodology
Regulatory filings from TRAI, MIC, and MIIT, constellation operator technical specifications, and maritime fleet operator procurement disclosures formed the secondary backbone for capacity and pricing calibration. Primary interviews with satellite system integrators, RF engineering specialists, defense procurement officers, and mobile network operator backhaul managers supplied deployment timeline and contract structure validation. Bottom-up transponder lease pricing and top-down orbital capacity supply estimates were triangulated against customs records for ground station equipment imports and launch manifest disclosures from Chinese and US complexes.
Bottom-up modeling aggregated segment-level demand from government, military, commercial, and telecom end users across fixed satellite services, mobile satellite services, and low Earth orbit constellations. Top-down validation cross-referenced national broadband coverage targets from India's Digital India program and Australia's regional connectivity initiatives against modeled satellite backhaul requirements. CAGRs were derived from replacement cycle analysis of legacy C-band contracts and Ka-band spot-beam adoption curves. Forecast inputs included launch cost trajectories from heavy-lift vehicle availability and terminal price compression from electronically steered flat-panel antenna manufacturing scale.
Revisions become necessary when TRAI spectrum allocation enforcement weakens, MIC debris compliance costs escalate beyond modeled thresholds, or Pacific Island submarine cable projects advance ahead of satellite backhaul deployment. Deviation in launch queue bottlenecks at Chinese and US complexes would shift constellation expansion timelines and capacity pricing materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Mobile Satellite Services Market
Satellite
Middle East Satellite Communications Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
South Korea Satellite Communication Market
Satellite
LEO Satellite Constellation Market
Satellite
M2M Satellite Communication Market
Satellite
Japan Satellite Connectivity Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
GEO Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Africa Satellite Connectivity Market
Satellite
Europe Military Satellite Market