
 Global Commercial Satellite Imaging Market | 2026-2036
Global Commercial Satellite Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Satellite Imaging Market Intelligence
The EU Green Deal, with its stringent environmental monitoring mandates, is pivoting commercial satellite imaging demand towards climate and ecosystem analysis. Maxar Technologies Inc. leverages its high-resolution optical constellation for critical government and commercial missions. Planet Labs PBC differentiates with daily global coverage from its small satellite fleet, tracking rapid environmental changes. Airbus Defence and Space anchors the European market with a diverse portfolio of optical and radar assets.
Commercial satellite imaging is the acquisition and distribution of Earth observation data collected by privately operated satellites. These systems provide imagery with specific spatial resolutions, some capable of sub-meter detail, for various analytical purposes. While the defense and intelligence application remains a foundational revenue source, agricultural monitoring represents a high-growth segment. Optical imaging satellites constitute the largest product category, though Synthetic Aperture Radar (SAR) satellites are gaining traction for all-weather, day-night observation capabilities.
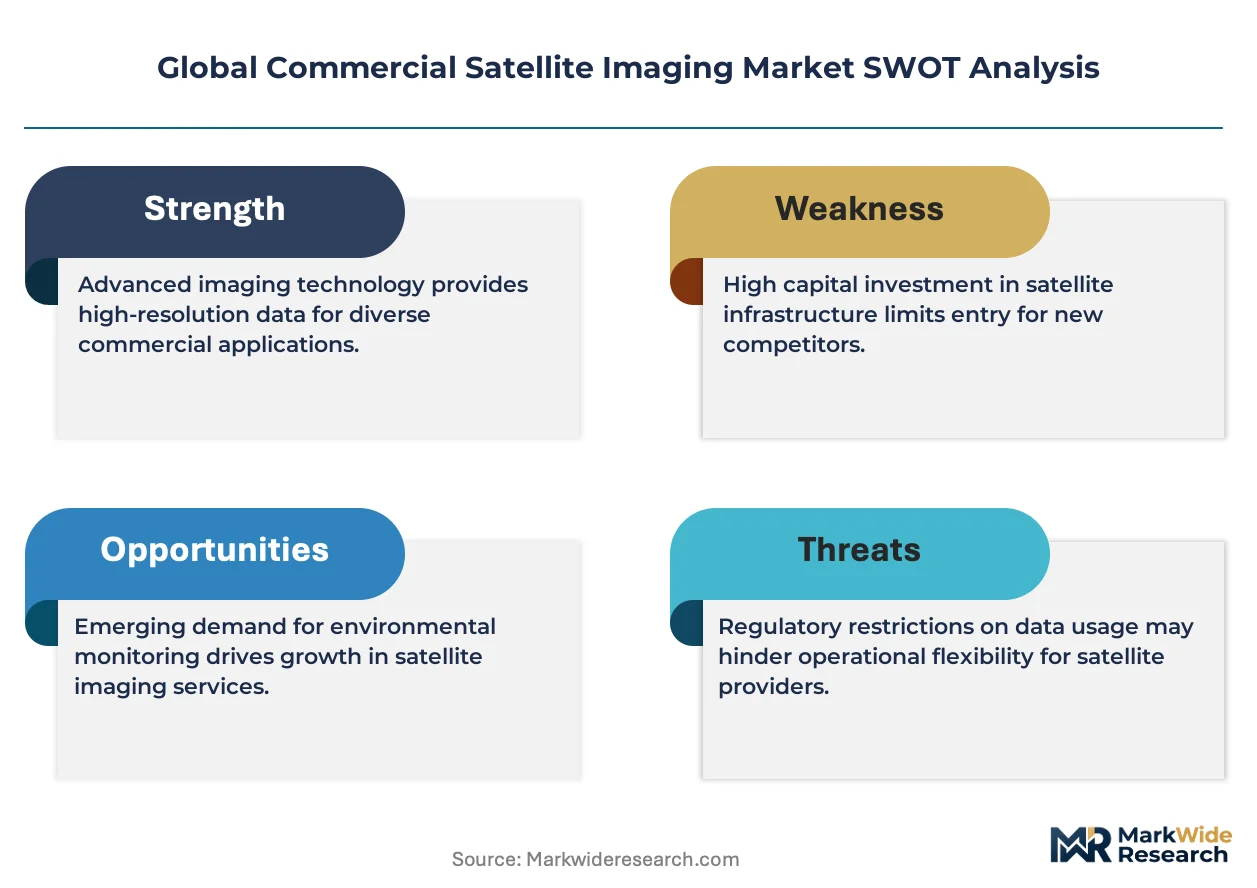
The U.S. Federal Communications Commission (FCC) governs licensing for commercial remote sensing satellite systems, directly impacting market entry timelines. Data handling and privacy are shaped by frameworks like the EU's GDPR, while national policies in countries such as India and Australia regulate imagery resolution and distribution rights. Providers must navigate this complex web of national security restrictions against open data policies to achieve scale.
Market Dynamics
The commercial satellite imaging market is defined by the accelerating demand for near-real-time geospatial intelligence, driven by both commercial analytics and government surveillance needs. This dynamic creates a competitive tension between high-cost, sub-meter resolution satellites and large constellations of lower-cost small satellites offering high revisit rates.
Growth Catalysts
- Precision Agriculture Demand:The agricultural sector's need for data to support precision farming, optimize irrigation, and forecast crop yields is a significant market driver, especially for multispectral imaging.
- Environmental Regulation:Mandates like the EU Green Deal require extensive environmental surveillance, creating new government and commercial contracts for monitoring deforestation, emissions, and water quality.
- Urban Infrastructure Projects:Rapid urbanization, particularly in countries like India and Brazil, fuels requirements for high-resolution imagery for city planning, infrastructure management, and construction monitoring.
Market Restraints
- High Capital Expenditure:The substantial upfront investment required for satellite design, manufacturing, launch services, and ground infrastructure creates a high barrier to entry for new operators.
- Regulatory Fragmentation:Operators must navigate a complex patchwork of national regulations, such as U.S. FCC licensing and Indian data sharing restrictions, which can delay service deployment and limit market access.
- Optical Imaging Limitations:Cloud cover remains a persistent operational constraint for optical satellites, hindering reliable and timely data acquisition in many tropical and temperate regions.
Strategic Opportunities
- Insurance and Risk Analytics:There is a significant opportunity to provide imagery and analytics for the insurance industry to assess damage from natural disasters, verify claims, and model climate-related risks.
- AI-Powered Analytics Platforms:The convergence of satellite imagery with artificial intelligence offers a major growth avenue in creating predictive analytics-as-a-service products for finance, logistics, and retail.
- Maritime Domain Awareness:Monitoring for illegal fishing, piracy, and smuggling provides a growing market for both optical and SAR satellite data, particularly for government and international agencies.
Industry Challenges
- Data Processing and Storage:The immense volume of data collected by satellite constellations presents a significant operational challenge, requiring massive investment in scalable cloud infrastructure and automated processing pipelines.
- Geospatial Talent Shortage:A scarcity of data scientists and geospatial analysts with the skills to interpret complex satellite data and build custom algorithms limits the growth of value-added services.
- Data Interoperability:The lack of standardization across data formats from different satellite providers complicates the fusion of multi-source imagery, creating integration hurdles for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Satellite Imaging Market |
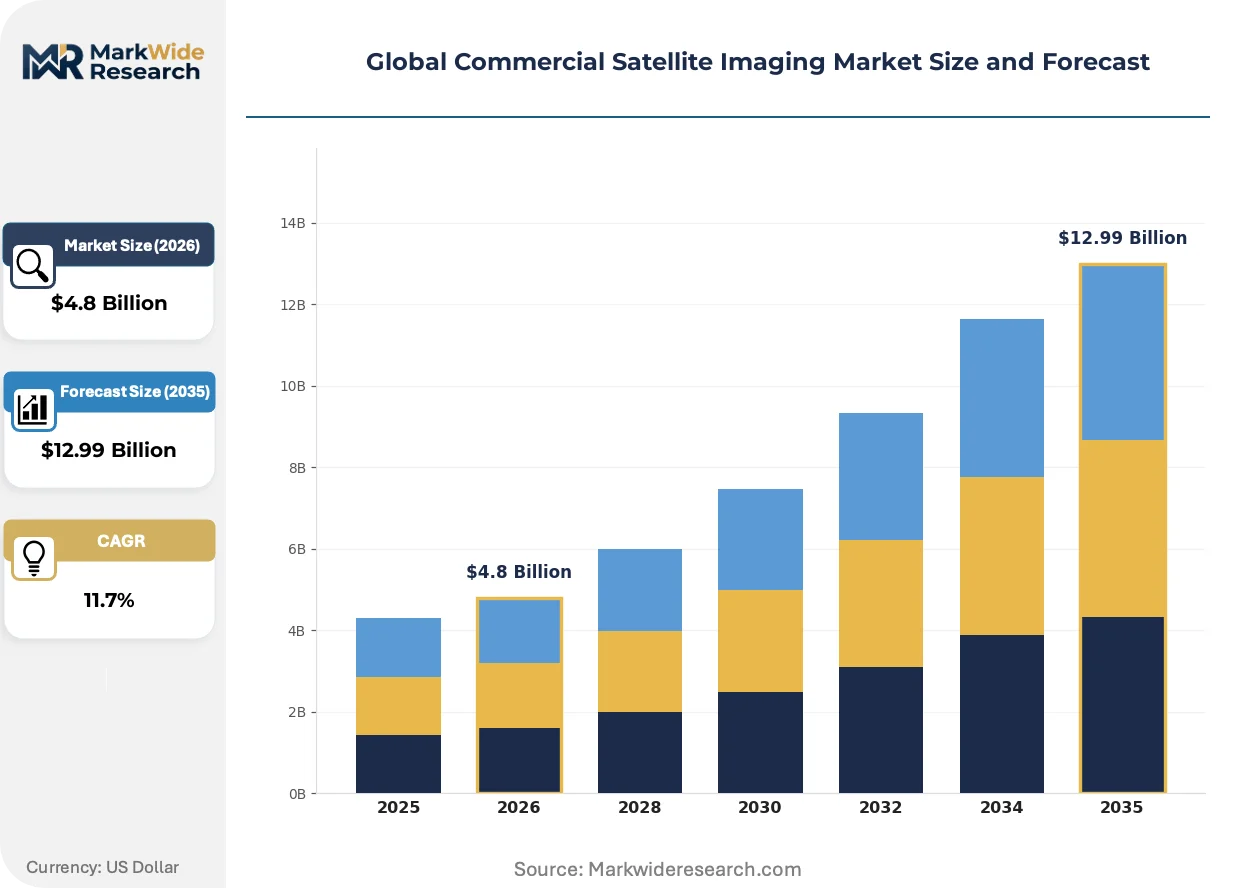
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Imaging Satellites, Synthetic Aperture Radar Satellites, Hyperspectral Imaging Satellites, Multispectral Imaging Satellites, Panchromatic Satellites Application: Defense & Intelligence, Agricultural Monitoring, Environmental Surveillance, Urban Planning, Disaster Management, Marine Observation End User: Government Agencies, Research Institutions, Energy Exploration Firms, Mapping & Survey Companies, Telecommunications Providers Deployment: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Sun-synchronous Orbit |
| Companies Covered | Maxar Technologies Inc., Planet Labs PBC, Airbus Defence and Space, BlackSky Technology Inc., ICEYE, Satellogic Inc., Capella Space, L3Harris Technologies Inc., European Space Imaging GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Satellite Imaging Market Strategic Shifts & Innovations
The market's evolution is marked by a decisive shift from selling raw pixels to delivering integrated analytical insights. This transition is powered by advancements in sensor technology and the maturation of cloud-based platforms that make geospatial data more accessible and actionable for non-specialist users.
Synthetic Aperture Radar (SAR) provides an all-weather, day-and-night imaging capability that overcomes the limitations of traditional optical sensors. Industries such as maritime surveillance and disaster management are rapidly adopting SAR for its reliable monitoring performance in adverse conditions. The technology's ability to see through clouds and darkness is rewriting the operational playbook for time-sensitive environmental and security missions that demand guaranteed data acquisition.
Data sovereignty and privacy regulations, exemplified by the EU's GDPR, are shaping how satellite imagery is processed, stored, and distributed. These rules compel providers to implement regional data handling strategies and invest in anonymization technologies to protect personal information identifiable in high-resolution imagery. The urban planning and real estate intelligence sectors are most affected, needing to adapt their data workflows to remain compliant.
A fundamental shift in consumption patterns sees customers moving away from one-time imagery purchases toward subscription-based data and analytics platforms. This model displaces transactional sales with recurring revenue streams that offer continuous data access and integrated software tools. This trend is most advanced in the agriculture and climate intelligence verticals, where users depend on consistent monitoring for change detection and forecasting.
Global Commercial Satellite Imaging Market Segmentation
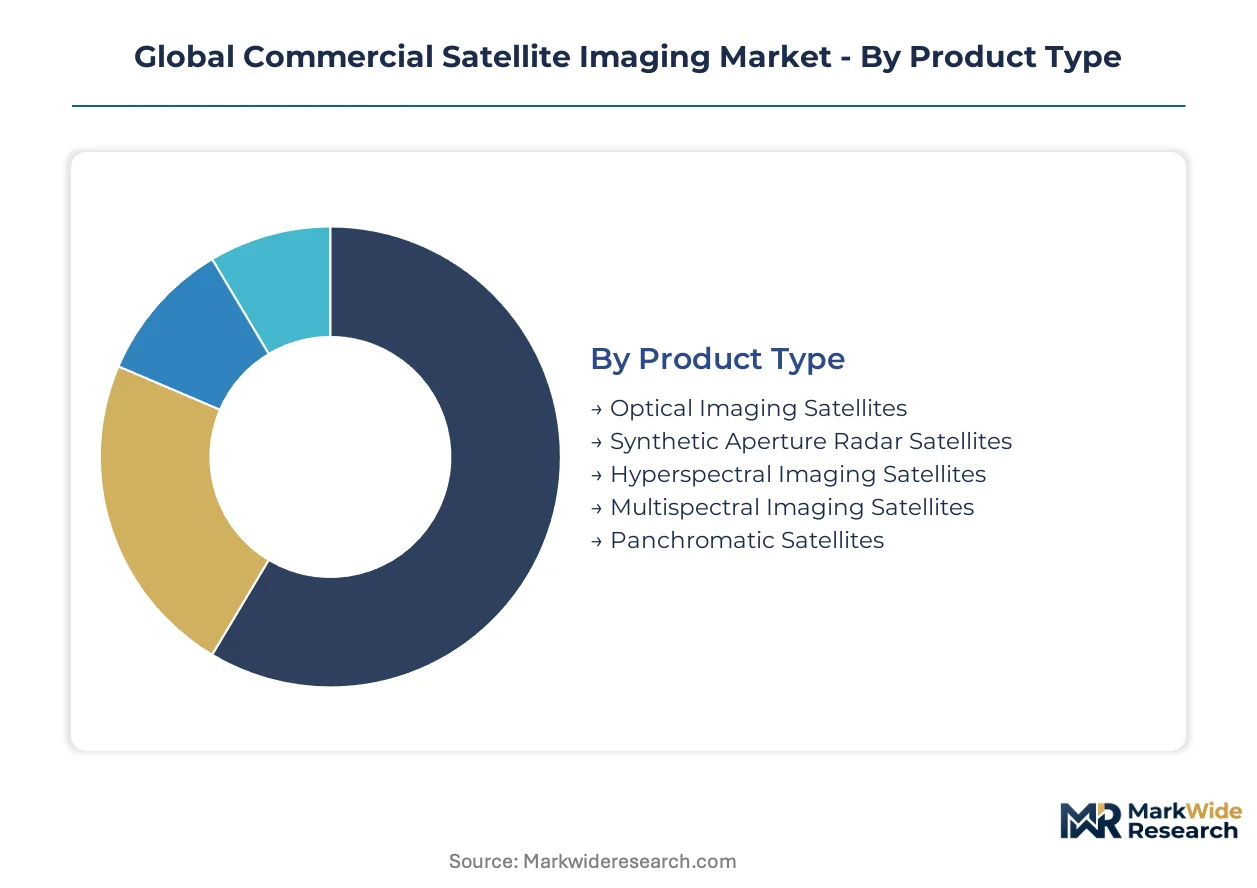
The commercial satellite imaging market segments by the distinct technical capabilities of imaging platforms, the specific analytical needs of various industries, and the operational requirements of end-user organizations. Understanding these divisions is crucial for providers tailoring their data and analytics offerings.
Product Type:
What differentiates buyers in this category is the specific type of electromagnetic radiation captured and the resulting data characteristics. Each product type offers unique advantages for different observation requirements.
- Optical Imaging Satellites:These systems capture reflected sunlight to produce high-resolution visual imagery, crucial for detailed urban mapping, infrastructure monitoring, and land-use analysis. Demand for sub-meter resolution is concentrated in urban planning projects in countries like India and Brazil.
- Synthetic Aperture Radar Satellites:SAR systems emit and receive microwave signals, enabling all-weather, day-and-night imaging capabilities that penetrate clouds and darkness. This technology is gaining traction for maritime surveillance and disaster management, particularly for reliable data acquisition in adverse conditions.
- Hyperspectral Imaging Satellites:These satellites collect data across hundreds of narrow spectral bands, providing highly detailed material composition analysis. Applications include precision agriculture for soil health and environmental monitoring for pollution detection.
- Multispectral Imaging Satellites:Capturing data across several discrete spectral bands, these systems support vegetation health assessment and land cover classification. Agricultural monitoring relies heavily on multispectral data for crop yield forecasting.
- Panchromatic Satellites:These sensors record light across a broad visible spectrum, yielding high-resolution black and white images with excellent spatial detail. Panchromatic imagery often serves as a base layer for other sensor data fusion.
Volume sits with Optical Imaging Satellites; growth tilts toward Synthetic Aperture Radar Satellites.
Application:
The choice of satellite imaging application depends on the specific geospatial intelligence required by the end-user for decision-making. Each application addresses distinct operational challenges and information needs.
- Defense & Intelligence:This application involves using satellite imagery for national security, strategic planning, and monitoring geopolitical developments, forming a foundational revenue source for many providers. Governments globally utilize this data for critical surveillance missions.
- Agricultural Monitoring:Satellite data supports precision farming, crop health assessment, and yield forecasting, optimizing resource use and improving food security. This segment is experiencing high growth due to demand from farmers in regions like the European Union.
- Environmental Surveillance:Monitoring deforestation, water quality, carbon emissions, and biodiversity falls under this category, driven by mandates like the EU Green Deal. This application provides critical data for climate and ecosystem analysis.
- Urban Planning:High-resolution imagery assists city planners with infrastructure development, population density analysis, and land-use management. Rapid urbanization in countries such as India creates significant demand.
- Disaster Management:Satellite imaging aids in damage assessment, emergency response coordination, and post-disaster recovery efforts. SAR data is particularly valuable for its all-weather capabilities during crises.
- Marine Observation:Monitoring illegal fishing, tracking maritime traffic, and observing oceanographic phenomena are key aspects of this application. Government and international agencies use this data for maritime domain awareness.
Environmental surveillance and agricultural monitoring are expanding most quickly, driven by regulatory mandates and efficiency demands.
End User:
End-user categories reflect distinct operational needs and budget allocations for satellite imagery acquisition. Each group leverages geospatial data for specialized purposes, influencing demand patterns.
- Government Agencies:These entities are major consumers of satellite imagery for defense, intelligence, environmental monitoring, and urban planning purposes. The U.S. Federal Communications Commission (FCC) governs licensing for government and commercial systems.
- Energy Exploration Firms:Companies in this sector utilize satellite data for site selection, infrastructure monitoring, and environmental impact assessments in oil, gas, and renewable energy projects. Imagery supports efficient resource management and regulatory compliance.
- Research Institutions:Academic and scientific organizations use satellite data for climate modeling, ecological studies, and geographical research. These institutions often drive innovation in analytical methods.
- Mapping & Survey Companies:These firms integrate satellite imagery into their geospatial products and services for cartography, land surveying, and geographic information systems (GIS). They provide foundational data for various industries.
- Telecommunications Providers:Satellite imagery supports network planning, infrastructure deployment, and coverage optimization for telecommunication services. It helps assess line-of-sight and potential interference for new installations.
Government agencies command the largest share of imagery procurement, while energy exploration firms represent a specialized, high-value segment.
Deployment:
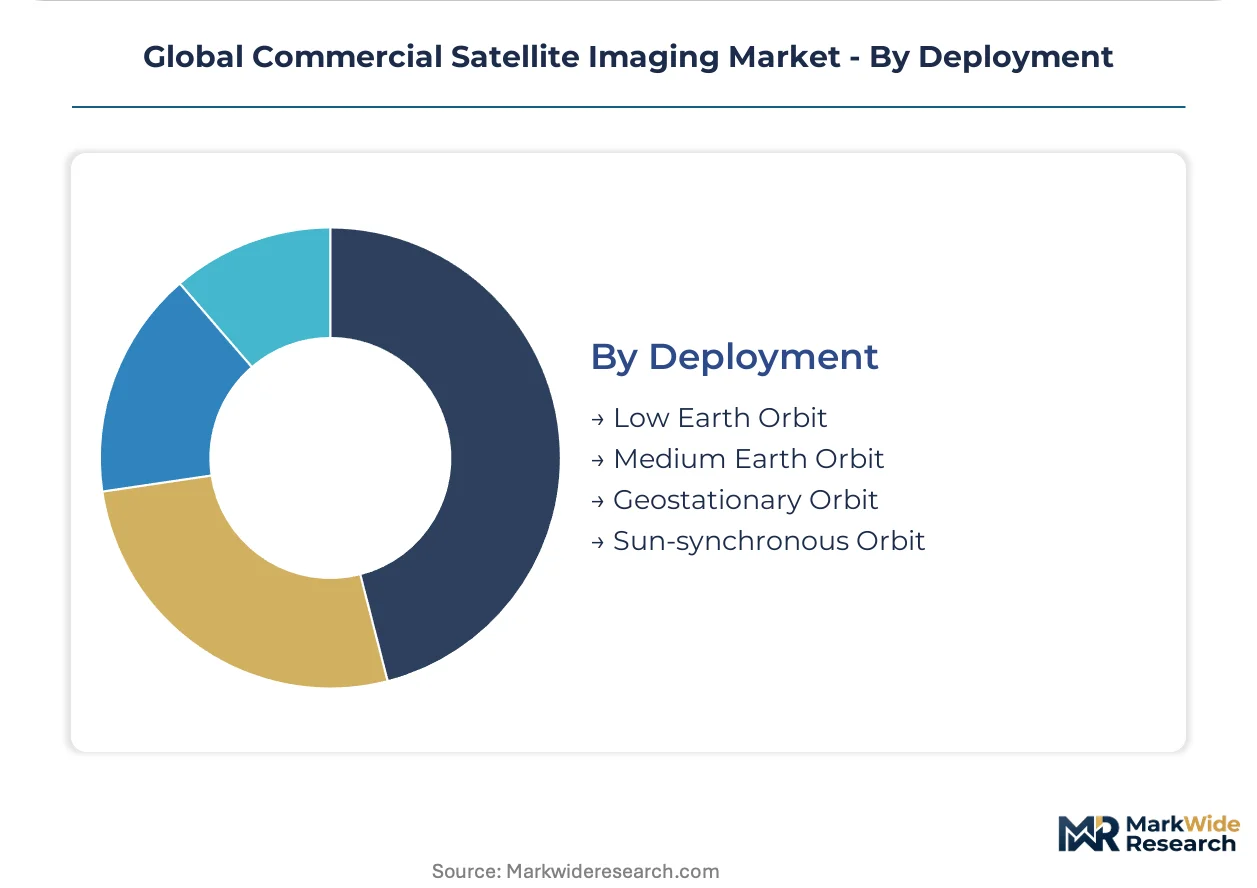
Orbital characteristics dictate the revisit rate, resolution capabilities, and coverage area offered by commercial satellite systems. Each orbit type serves specific operational objectives for Earth observation.
- Low Earth Orbit:Satellites in LEO orbit at altitudes typically below 1,000 km, providing high spatial resolution and frequent revisit times for detailed monitoring. Planet Labs PBC operates large constellations of small satellites in LEO for daily global coverage.
- Sun-synchronous Orbit:This is a specific type of LEO where satellites pass over any given point of the Earth's surface at the same local solar time, ensuring consistent lighting conditions for imagery. Many Earth observation satellites, including optical and SAR, utilize this orbit.
- Medium Earth Orbit:MEO satellites operate at altitudes between 2,000 km and 35,786 km, offering broader coverage than LEO but with less frequent revisits. This orbit is less common for dedicated commercial Earth observation.
- Geostationary Orbit:Satellites in GEO maintain a fixed position relative to the Earth's surface at approximately 35,786 km, providing continuous observation of a large geographic area. This orbit is primarily used for meteorological and communication satellites.
Low Earth Orbit constellations provide frequent revisit times for dynamic monitoring, contrasting with the broader, less frequent coverage from higher orbits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. serves as a pivotal hub for commercial satellite imaging demand, driven by extensive government contracts. Defense and intelligence applications represent a foundational revenue source for companies operating in this sector. The region's strategic importance necessitates advanced Earth observation capabilities.
United States
Demand for high-resolution imagery stems from defense and intelligence requirements. The U.S. Federal Communications Commission (FCC) governs licensing for remote sensing systems. Silicon Valley in California innovates AI-powered analytics platforms for geospatial data. Energy exploration firms also utilize satellite data for infrastructure monitoring.
India
Rapid urbanization creates substantial demand for high-resolution imagery in city planning. National policies in India regulate imagery resolution and distribution rights. Bengaluru is a significant center for geospatial data processing, serving urban development projects. Agricultural monitoring also drives multispectral imaging demand.
Germany
Environmental surveillance mandates, influenced by the EU Green Deal, drive demand for climate analysis. The European Space Agency (ESA) collaborates with German entities on Earth observation missions. Munich hosts aerospace and defense companies leveraging satellite data for diverse applications. Precision agriculture also benefits from satellite insights.
Brazil
Urban infrastructure projects and agricultural monitoring fuel demand for high-resolution imagery. Brazil's environmental regulations emphasize monitoring deforestation in the Amazon rainforest. São Paulo represents a key commercial hub integrating satellite data for urban planning. The country's demand for crop yield forecasting remains strong.
Australia
Agricultural monitoring for crop yield forecasting and environmental regulation are significant demand drivers. Australian policies regulate data sharing and distribution rights, affecting market operations. Canberra supports government agencies utilizing satellite data for national security and environmental oversight. Mining companies employ satellite imagery for site assessment.
Global Commercial Satellite Imaging Market Key Industry Players
The competitive structure tilts toward a tiered ecosystem, where established players with extensive satellite constellations coexist with agile startups. Market consolidation is evident among providers offering high-resolution optical imagery for defense and intelligence, alongside specialized SAR data providers. Strategic partnerships and technology licensing represent dominant competitive moves for expanding service portfolios and geographic reach. Companies increasingly invest in AI-powered analytics platforms to transform raw data into actionable insights.
Among the established industry leaders, Maxar Technologies Inc. represents a provider leveraging high-resolution optical constellations for critical government and commercial missions. Planet Labs PBC exemplifies a specialist in high-revisit rate Earth observation, deploying large fleets of small satellites for daily global coverage. Airbus Defence and Space anchors the European market, occupying a position with a diverse portfolio of optical and radar assets. These entities showcase the market's segmentation by sensor capabilities and operational models.
| Leading Market Players |
|---|
| Maxar Technologies Inc. |
| Planet Labs PBC |
| Airbus Defence and Space |
| BlackSky Technology Inc. |
| ICEYE |
| Satellogic Inc. |
| Capella Space |
| L3Harris Technologies Inc. |
| European Space Imaging GmbH |
| Others |
Cost & Logistics Intelligence
A distinct performance gap between sub-meter optical imagery and high-revisit small satellite data shapes both pricing and supply chain structures. This divergence drives premium models for specialized government contracts and subscription services for broad commercial applications.
Pricing Analysis
Outcome-based analytics platforms anchor pricing in the commercial satellite imaging market. Subscription-based data and analytics platforms dominate, offering continuous access rather than transactional sales. Price differentiation stems from imagery resolution and revisit rates, along with the depth of AI-powered analytical insights. Pricing pressure arises from the increasing number of satellite constellations entering service. Research institutions exhibit the highest price sensitivity, while defense and intelligence agencies are least sensitive.
Supply Chain Analysis
Dual-sourcing requirements for critical satellite components drive resilience in the commercial satellite imaging supply chain. Key manufacturing and R&D hubs concentrate in the United States, Germany, and Japan for specialized optics and radar systems. The industry depends on a limited number of providers for advanced sensor components and launch services. Single-source vulnerability for high-performance optical payloads represents a structural supply chain risk. Distribution runs through direct enterprise sales and integrated analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial satellite imaging market is in a technology-transition phase, with Synthetic Aperture Radar (SAR) systems increasingly replacing traditional optical sensors. SAR's all-weather, day-night capabilities offer superior operational reliability.
For Market Incumbents:Extend existing high-resolution optical constellations with SAR capabilities to counter the threat from specialized SAR providers. Invest in AI-powered analytics platforms to transform raw data into actionable insights, mitigating margin pressure from commoditized imagery. Form strategic partnerships with cloud infrastructure providers to manage immense data volumes and enhance processing efficiencies. Focus R&D on next-generation sensor fusion for comprehensive geospatial intelligence.
For New Entrants and Emerging Players:Geospatial platform integrators offer a direct channel to penetrate the value-added services market. Target the agricultural monitoring and environmental surveillance segments, which exhibit high growth due to specific regulatory mandates like the EU Green Deal. Focus on developing specialized AI models for niche applications, such as crop yield forecasting or deforestation tracking. Offer subscription-based analytics-as-a-service to appeal to non-specialist users.
For Investors and Strategic Acquirers:Re-rating potential sits with vertically integrated analytics providers given the shift from raw pixel sales to actionable insights. Long-term viability depends on companies that can fuse multi-source data and offer predictive capabilities across multiple verticals. Acquisition targets include specialized AI firms developing geospatial algorithms and SAR data specialists. The signal to watch is the increasing adoption rate of subscription-based analytics platforms among non-traditional satellite imagery users.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Analytics Platforms | Transforms raw satellite data into actionable insights for diverse sectors like finance and logistics. |
| Expand SAR Satellite Constellations | Provides all-weather, day-night observation capabilities, enhancing reliability for disaster management. |
| Pursue Vertical Integration in Sensor Manufacturing | Secures critical component supply and reduces costs for advanced optical and radar systems. |
| Form Partnerships with Cloud Service Providers | Manages immense data volumes and enables scalable processing for global satellite imagery. |
| Offer Subscription-Based Data Services | Shifts customer consumption patterns from transactional purchases to continuous data access for users. |
Research Approach
Trade association data, government space agency reports, and financial filings anchored secondary inputs, complemented by primary interviews. This study combined insights from satellite operators, geospatial analysts, urban planners, and agricultural consultants. These primary inputs validated market dynamics and emerging trends. Bottom-up data aggregation and top-down market sizing ensured robust triangulation across all segments.
Data-stream reconciliation across historical trends and projected growth rates formed the analytical framework. This study modeled segmentation dimensions including product type, application, end-user, and deployment, alongside specific sensor technology advancements. Compound annual growth rates were derived from a synthesis of market drivers and competitive intelligence. Satellite launch schedules and environmental regulatory compliance spending served as key forecast inputs.
Caveats apply where geopolitical instability or rapid technological obsolescence could materially shift the outlook. Forecasts reflect current market assumptions regarding investment cycles and regulatory enforcement. Deviation in satellite launch rates or sensor development would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
India Satellite Communication Market
Satellite
Satellite Antenna Market
Satellite
Electric Propulsion Satellite Market
Satellite
Satellite Data Service Market
Satellite
Satellite Photography Service Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Satellite Backhaul Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Satellite Communications Service Market
Satellite
Global Satellite Propulsion System Market
Satellite
Remote Sensing Satellite Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Europe Small Satellite Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
VSAT Maritime Satellite Communication Market