
 UAE Satellite Imagery Services Market | 2026-2036
UAE Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Satellite Imagery Services Market Insights
The shift from foreign dependency to sovereign satellite capacity is decoupling procurement patterns across the Emirates. Airbus SE leverages its constellation scale to anchor defense contracts throughout the Gulf region. MBRSC sustains indigenous manufacturing and launch capabilities through the KhalifaSat program. Yahsat competes across fixed and mobile satellite services while extending ground infrastructure across the Arabian Peninsula.
Satellite imagery services encompass the acquisition, processing, and distribution of geospatial data captured by Earth-orbiting platforms operating at altitudes from 400 to 36,000 kilometers, with spatial resolutions ranging from sub-meter to 30-meter granularity depending on sensor payload and orbital configuration. These services enable terrain modeling, asset tracking, and environmental surveillance across commercial and government workflows. Remote sensing applications for environmental monitoring lead current adoption curves as drought and coastal erosion intensify analytical requirements. Optical sensors dominate present revenue pools while synthetic aperture radar imaging represents the fastest-expanding technology segment due to all-weather operational reliability. Government end users concentrate the largest contract values though commercial demand from logistics and insurance verticals is accelerating.
The UAE Space Agency coordinates licensing under national space legislation aligned with UN COPUOS guidelines, while MOHAP and the Telecommunications and Digital Government Regulatory Authority govern cross-border data transmission and civilian remote sensing operations. These frameworks shape foreign operator market access and mandate domestic data residency for sensitive geospatial intelligence. Stakeholders must monitor evolving sovereignty requirements and local partnership obligations as the Emirates advances orbital manufacturing independence.
Market Dynamics
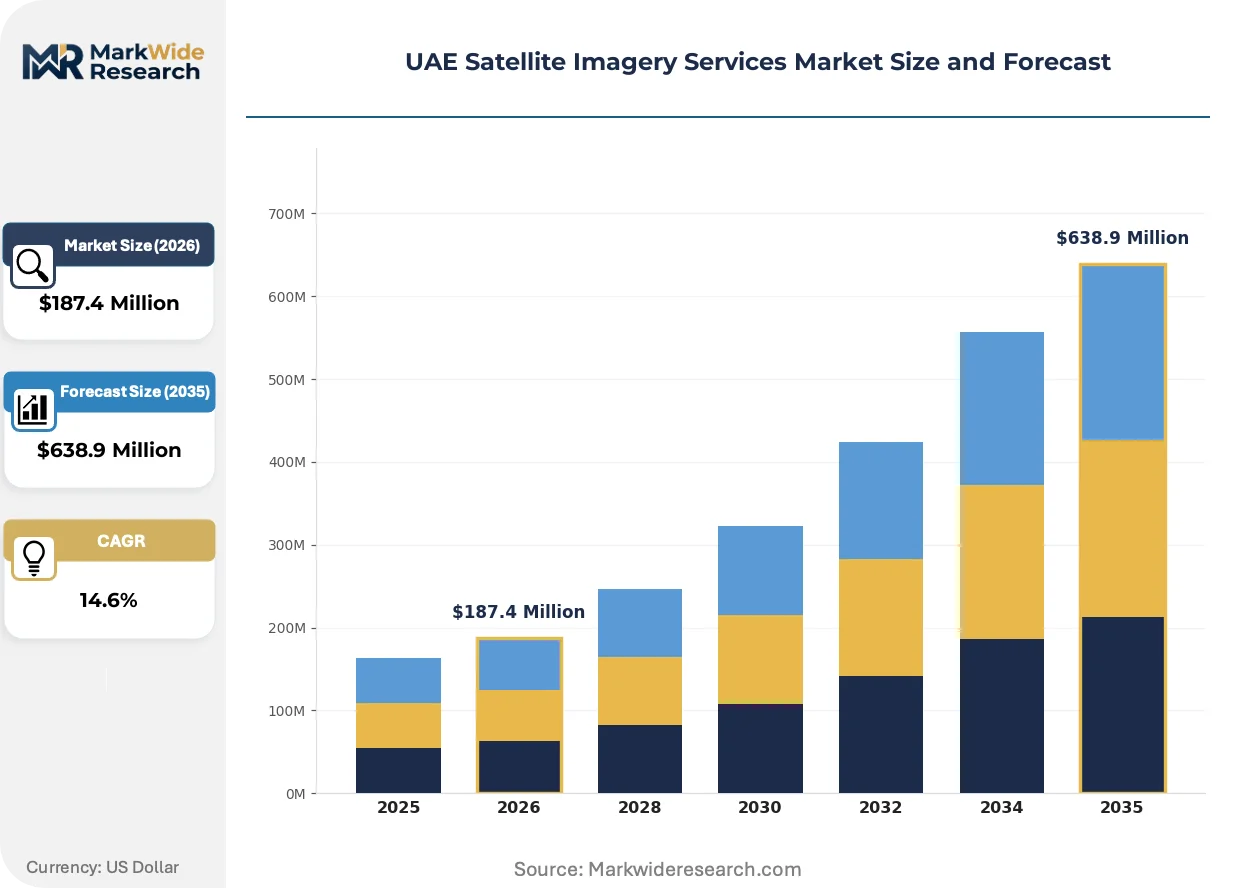
The UAE Satellite Imagery Services Market is restructuring around sovereign data residency mandates and the UAE Space Agency's push for domestic orbital manufacturing independence. Foreign operators now face localization requirements that favor indigenous ground segment and analytics capabilities.
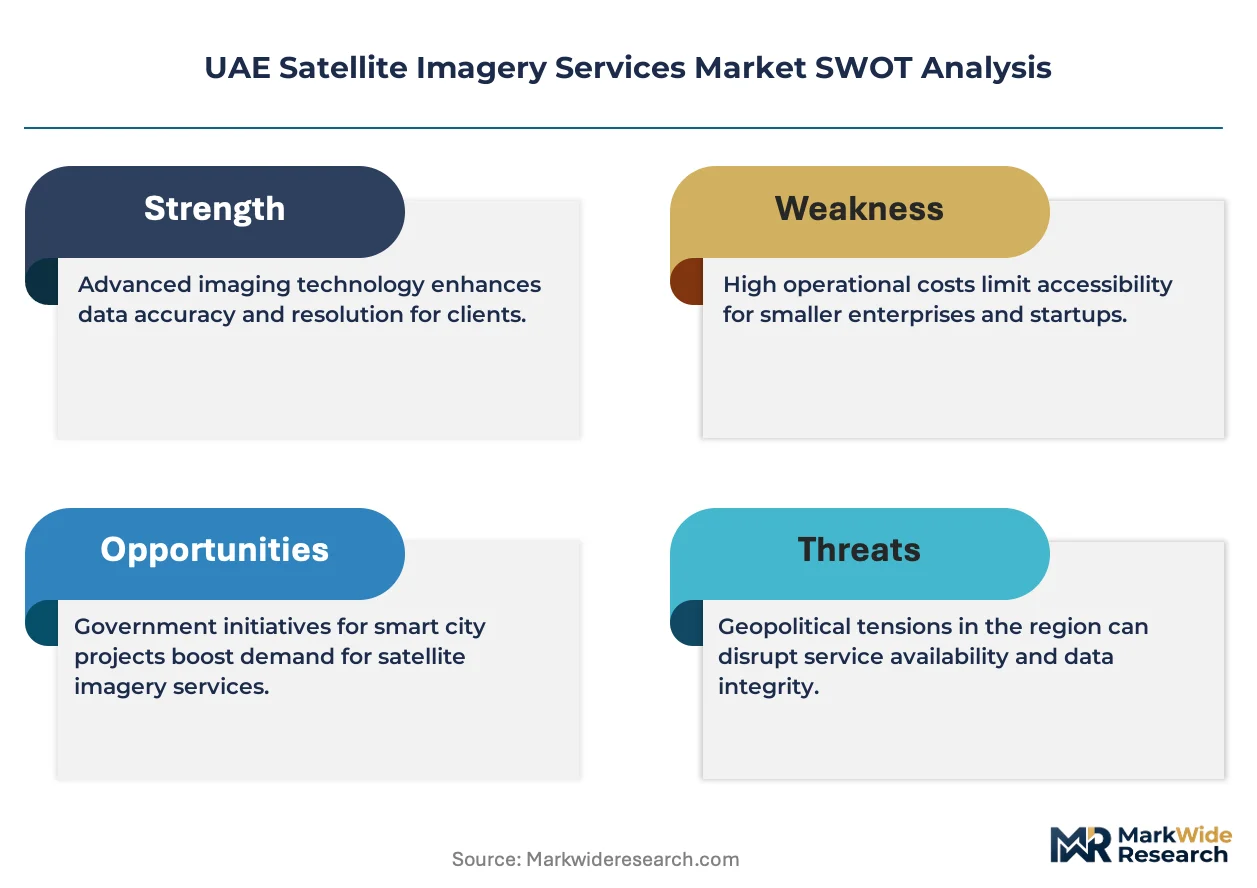
Growth Catalysts
- Smart City Infrastructure:Abu Dhabi's Masdar City and Dubai's 2040 Urban Master Plan require continuous geospatial monitoring for traffic optimization, utility mapping, and coastal zone management.
- Environmental Surveillance Mandates:MOHAP regulations on coastal erosion monitoring and desertification tracking compel government agencies to procure high-frequency satellite revisit capabilities.
- Synthetic Aperture Radar Adoption:All-weather imaging technology is penetrating maritime surveillance and oil infrastructure monitoring where optical sensors fail during sandstorm seasons.
Market Restraints
- Launch Cost Volatility:Falcon Heavy and Ariane 6 pricing fluctuations directly impact the total cost of ownership for custom constellation deployment.
- Sensor Supply Concentration:High-resolution optical payloads rely on a limited set of European and North American component suppliers, creating single-source vulnerabilities.
- Data Sovereignty Friction:Cross-border transmission restrictions under UAE national space legislation complicate foreign cloud-based processing architectures.
Strategic Opportunities
- Ras Al Khaimah Expansion:The emirate's emerging logistics corridor and tourism development zones remain underserved by high-resolution monitoring services.
- AI-Enhanced Analytics Convergence:Machine learning pipelines for automated change detection and vessel classification are opening subscription-based revenue models.
- Telecommunications and Digital Government Regulatory Authority Incentives:Spectrum allocation preferences for domestic operators create regulatory tailwinds for UAE-registered satellite service providers.
Industry Challenges
- Geospatial Data Science Talent Gap:Remote sensing specialists with SAR processing and atmospheric correction expertise command premium compensation in the Emirates.
- Ground Segment Capex Burden:Direct antenna ownership and downlink infrastructure require substantial upfront investment before revenue generation begins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Satellite Imagery Services Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthophoto, 3D Mapping, Change Detection, Remote Sensing Application: Agriculture, Environmental Monitoring, Urban Planning, Disaster Management End User: Government, Defense, Commercial, Research Technology: Optical Sensors, Radar Imaging, Hyperspectral Imaging, LiDAR |
| Companies Covered | Airbus SE, Mohammad Bin Rashid Space Centre (MBRSC), United Arab Emirates Space Agency, Al Yah Satellite Communications Company PJSC (Yahsat), Thuraya Telecommunications Company, Space Imaging Middle East, Maxar Technologies, Esri, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Satellite Imagery Services Market Trends and Innovations
Orbital sensor miniaturization and on-board processing capabilities are compressing the latency between image capture and actionable intelligence delivery. These advances are reconfiguring competitive positioning around speed rather than resolution alone.
SmallSat constellations with sub-meter optical payloads are absorbing demand from traditional single large-satellite procurement models. UAE defense and intelligence agencies are adopting these distributed architectures for daily revisit requirements. The shift is absorbing capital from legacy geostationary programs into low-Earth orbit infrastructure.
UAE Space Agency licensing frameworks aligned with UN COPUOS guidelines are mandating domestic data residency for sensitive geospatial intelligence. This regulatory architecture is compelling foreign operators to establish UAE-based ground stations and processing facilities. Defense contracts now specify sovereign data handling as a non-negotiable technical requirement.
Subscription-based analytics services are displacing traditional per-image licensing in commercial verticals. Logistics and insurance buyers in Dubai International Financial Centre prefer integrated risk monitoring dashboards over raw imagery procurement. The behavioral pivot is most visible in maritime trade finance, where underwriters demand continuous vessel tracking rather than episodic port arrival confirmation.
UAE Satellite Imagery Services Market Segmentation
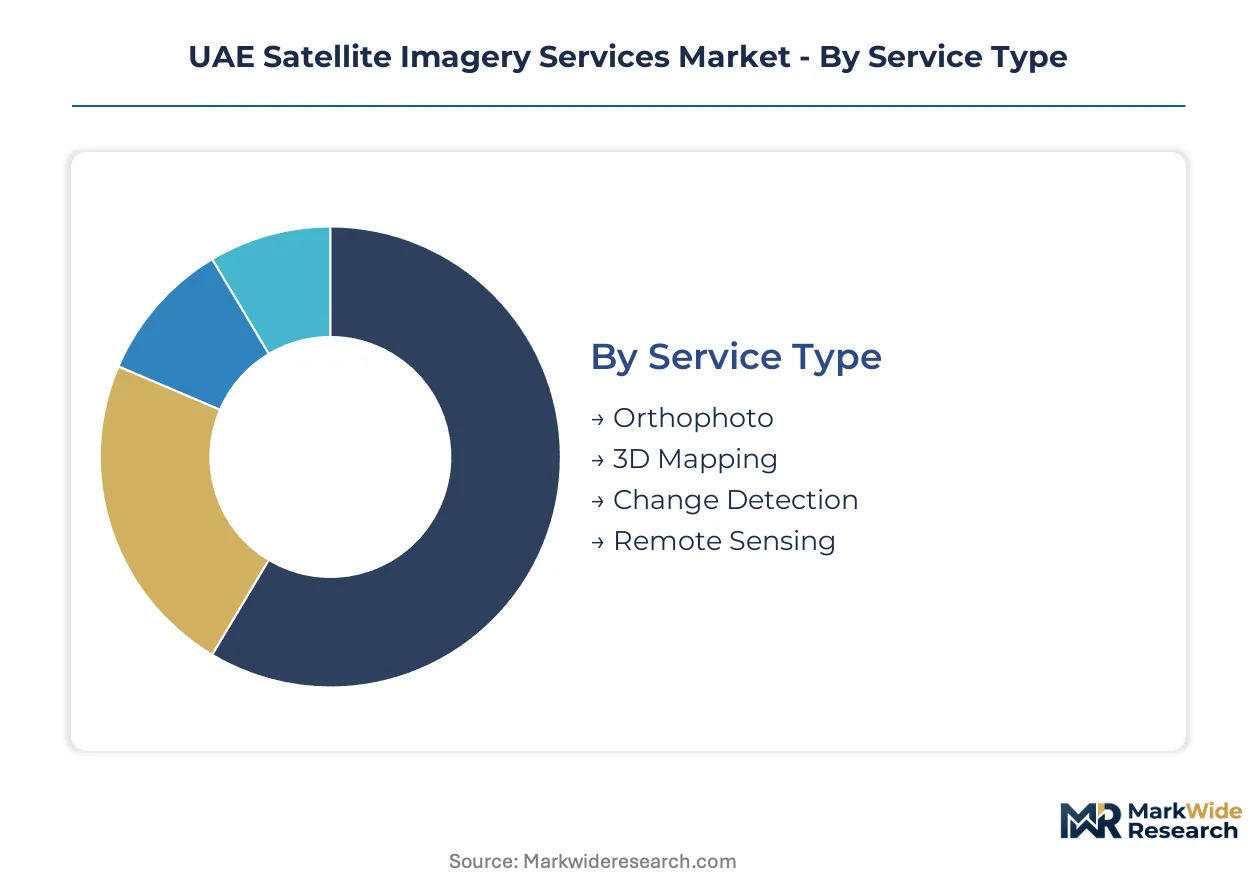
Segmentation in the UAE Satellite Imagery Services Market reveals how procurement patterns diverge across technical capabilities and institutional buyers. Each category exposes distinct supply-side constraints and demand concentration points that shape vendor strategy.
Service Type:
Supply concentration in processing infrastructure favors vendors with dedicated ground stations and in-country data centers.
- Orthophoto:Geometrically corrected aerial photographs deliver distortion-free base maps for cadastral surveys and infrastructure planning. Abu Dhabi Municipality and Dubai's Roads and Transport Authority procure these services for continuous urban boundary monitoring.
- 3D Mapping:Digital elevation models and photorealistic mesh reconstructions enable volumetric analysis for construction progress tracking. Demand concentrates in Dubai's mega-project developments where building information modeling integration is mandatory.
- Change Detection:Automated comparison algorithms flag surface alterations between capture epochs. Environmental compliance audits and unauthorized construction surveillance drive procurement from MOHAP and municipal enforcement divisions.
- Remote Sensing:Broad-area spectral analysis supports agricultural yield forecasting and marine ecosystem health assessment. Ras Al Khaimah's coastal zone management programs represent an emerging demand pocket.
Today's leader: Orthophoto. Tomorrow's challenger: 3D Mapping.
Application:
Cost tier differentiation separates turnkey analytics subscriptions from raw data licensing across use cases.
- Agriculture:Precision farming applications leverage multispectral indices for irrigation optimization and pest early warning. Al Ain date palm plantations and Abu Dhabi food security initiatives anchor demand in this segment.
- Environmental Monitoring:Coastal erosion tracking and desertification mapping absorb the highest revisit frequency requirements. MOHAP mandates and UAE Net Zero commitments institutionalize procurement budgets here.
- Urban Planning:Dubai 2040 Urban Master Plan and Masdar City expansion require continuous land-use classification and transport corridor analysis. Municipal planning departments specify sub-meter resolution as baseline.
- Disaster Management:Rapid damage assessment following flash floods or industrial incidents demands guaranteed tasking capacity. National Emergency Crisis and Disasters Management Authority contracts prioritize 24-hour delivery SLAs.
Environmental Monitoring commands premium pricing. Agriculture offers volume scaling potential.
End User:
Customer type determines data handling protocols and sovereignty requirements more than technical specifications.
- Government:Civilian agencies procure through UAE Space Agency-coordinated frameworks with mandatory domestic data residency. Procurement cycles align with federal budget appropriations.
- Defense:Classified geospatial intelligence requirements specify air-gapped processing and cleared personnel restrictions. Contracts flow through Tawazun Council and offset agreement mechanisms.
- Commercial:Logistics, insurance, and real estate developers favor subscription dashboards over raw imagery. Dubai International Financial Centre firms drive maritime risk monitoring adoption.
- Research:Universities and environmental NGOs access subsidized academic licensing through UAE Space Agency partnerships. Khalifa University and New York University Abu Dhabi maintain dedicated research allocations.
Defense concentrates contract value. Commercial verticals are climbing the fastest.
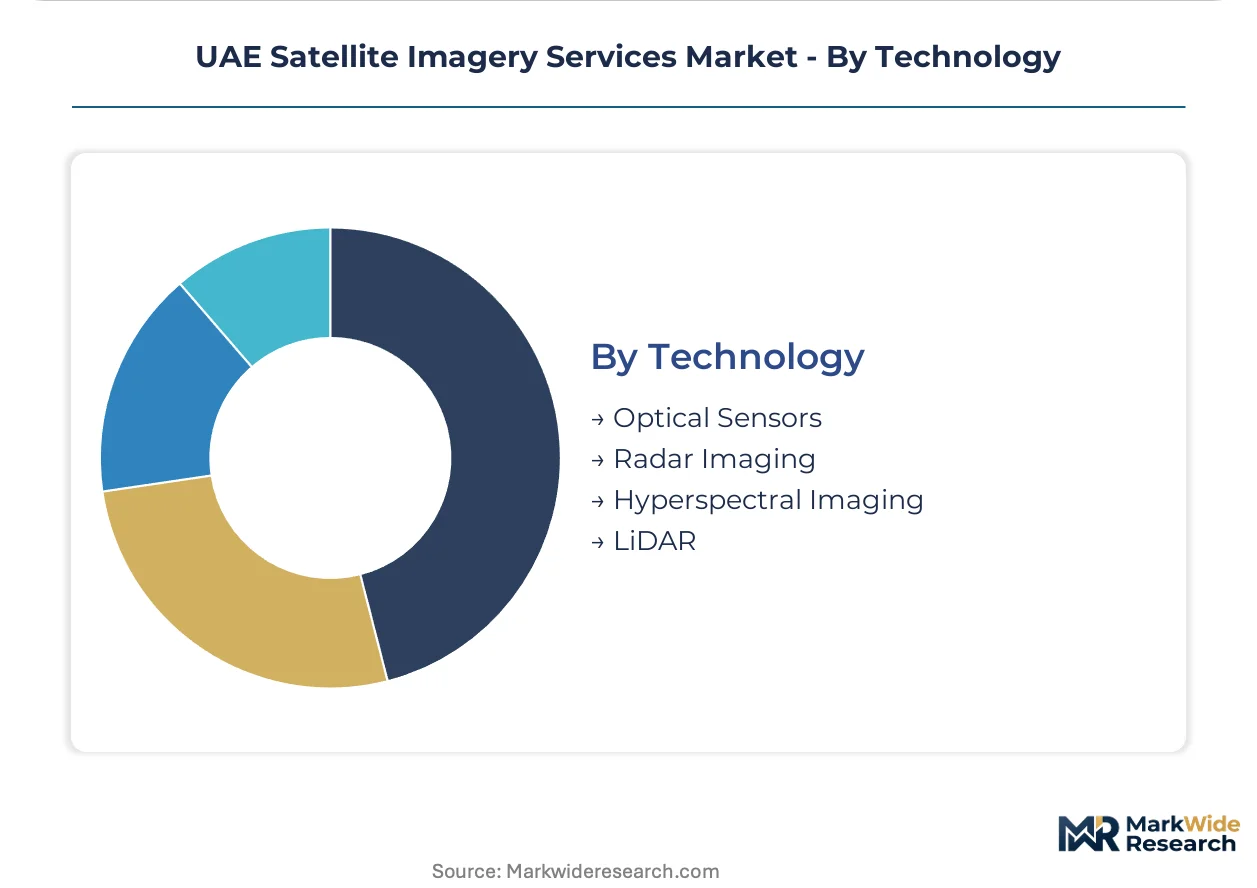
Technology:
Volume deployment favors sensor platforms with proven launch heritage and established ground segment compatibility.
- Optical Sensors:Panchromatic and multispectral imagers dominate current revenue with sub-meter resolution commercially available. Sandstorm seasonality limits operational reliability to approximately 70 percent of calendar days.
- Radar Imaging:Synthetic aperture radar penetrates cloud cover and darkness for all-weather maritime surveillance. Oil infrastructure monitoring and Red Sea vessel tracking absorb capacity from this expanding segment.
- Hyperspectral Imaging:Hundreds of narrow spectral bands enable material identification for mineral exploration and vegetation stress analysis. Emirates Soil Museum and geological survey applications represent niche demand.
- LiDAR:Active laser ranging generates high-precision elevation data for flood modeling and power line clearance surveys. Transmission corridor mapping for Etihad Water and Electricity drives periodic procurement.
Optical Sensors hold installed base. Radar Imaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi anchor satellite imagery demand through sovereign space programs and smart city infrastructure. Defense procurement concentrates contract value in these emirates. Ras Al Khaimah and Sharjah represent emerging demand pockets as logistics corridors expand.
Dubai
Dubai's Roads and Transport Authority procures sub-meter orthophoto services for traffic optimization and utility corridor mapping. The Dubai 2040 Urban Master Plan mandates continuous land-use monitoring through domestic ground stations. Dubai International Financial Centre firms drive commercial adoption of maritime risk monitoring dashboards.
Abu Dhabi
Abu Dhabi Municipality deploys high-resolution imagery for cadastral surveys and coastal zone management across Masdar City developments. MOHAP regulations require environmental surveillance for coastal erosion tracking. Tawazun Council channels defense geospatial intelligence contracts through offset agreement mechanisms.
Sharjah
Sharjah's logistics free zones and industrial parks generate demand for construction progress monitoring and asset tracking services. The emirate's university research clusters access subsidized academic licensing through UAE Space Agency partnerships. American University of Sharjah maintains dedicated remote sensing research allocations.
Ras Al Khaimah
Ras Al Khaimah's emerging tourism development zones and logistics corridors remain underserved by high-resolution monitoring capabilities. The emirate's coastal zone management programs represent a nascent demand pocket for environmental surveillance. Etihad Water and Electricity drives periodic procurement for transmission corridor mapping.
Northern Emirates
Fujairah and Ajman concentrate maritime surveillance demand through port infrastructure and coastal security programs. The UAE Space Agency's national space strategy extends sovereign capability building to these sub-regions through ground station infrastructure. Federal budget appropriations coordinate procurement across smaller emirates.
UAE Satellite Imagery Services Market Competitive Landscape
Global majors compete with regional champions across sovereign data handling and defense contracting. The vendor base stratifies between constellation-scale operators with dedicated ground segments and indigenous manufacturers building orbital independence. Three archetypes dominate: European aerospace conglomerates with Gulf defense relationships, UAE government entities advancing sovereign manufacturing, and specialized analytics providers serving commercial verticals. Competitive moves center on domestic partnership obligations and regulatory tailwinds for UAE-registered operators.
Within the sovereign capability tier, Mohammad Bin Rashid Space Centre and Al Yah Satellite Communications Company exemplify indigenous infrastructure builders. Airbus SE anchors the foreign operator segment through established Gulf defense relationships. These three entities occupy distinct competitive positions shaped by localization requirements and data residency mandates.
| Leading Market Players |
|---|
| Airbus SE |
| Mohammad Bin Rashid Space Centre (MBRSC) |
| United Arab Emirates Space Agency |
| Al Yah Satellite Communications Company PJSC (Yahsat) |
| Thuraya Telecommunications Company |
| Space Imaging Middle East |
| Maxar Technologies |
| Esri |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed operators and foreign defense contractors anchor supply-side discipline in the UAE satellite imagery market, with government equity participation directly constraining aggressive price competition while funneling procurement toward domestic ground segment ownership.
Pricing Analysis
Launch cost pass-through from Falcon Heavy and Ariane 6 pricing volatility feeds directly into constellation deployment economics, compressing margins on custom orbital programs while subscription-based analytics services absorb pricing pressure through SaaS-tiered models. Price differentiation rests on resolution grade and data sovereignty certification, with UAE-registered providers commanding premium positioning over foreign operators lacking domestic ground stations. Cost compression in raw imagery licensing is intensifying because small satellite manufacturers are flooding the market with sub-meter optical payloads. Logistics and insurance buyers in Dubai International Financial Centre show lowest price sensitivity, while municipal planning departments exhibit highest sensitivity due to federal budget appropriation constraints.
Supply Chain Analysis
Freight logistics for satellite components face minimal cost exposure given the extreme value-to-weight ratio of sensor payloads, though specialized handling requirements for optical assemblies create chokepoints at European and North American consolidation hubs. Manufacturing concentrates in France, Germany, and the United States for high-resolution optical sensors, with synthetic aperture radar components sourcing primarily from Germany and Israel. Raw material dependencies include germanium substrates for infrared detectors, precision optics glass from Schott AG, and radiation-hardened electronics from qualified US and European foundries. Single-source vulnerability pervades the sensor supply base, with limited qualified vendors for sub-meter resolution payloads. Distribution runs through direct government contracting frameworks for defense and intelligence end users, while commercial verticals access services through UAE-registered analytics platforms with domestic data residency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the UAE satellite imagery market rests on AI-enhanced analytics automation compressing processing labor costs while defense contracts sustain premium-tier sovereign data handling premiums.
For Market Incumbents: Acquire domestic ground station infrastructure to satisfy UAE Space Agency data residency mandates and secure Tawazun Council defense contract eligibility. Incumbents should anchor subscription-based analytics platforms with machine learning pipelines for automated vessel classification, defending against emerging AI-native entrants lacking classified processing clearances. Certification investment in air-gapped facility accreditation represents the critical lever for maintaining defense procurement access against foreign operators facing localization requirements. For New Entrants and Emerging Players: Ras Al Khaimah logistics corridor operators represent an underserved buyer archetype lacking high-resolution monitoring coverage enjoyed by Dubai and Abu Dhabi incumbents. New entrants should penetrate Sharjah's university research clusters through subsidized academic licensing partnerships with UAE Space Agency, leveraging this beachhead for commercial upsell into adjacent logistics free zones. A go-to-market angle emphasizing rapid small satellite tasking capacity for disaster response contracts with National Emergency Crisis and Disasters Management Authority offers fastest path to revenue generation. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized analytics providers lacking owned constellation assets but possessing trained geospatial data science teams and established UAE government relationships. Long-term viability over the coming decade hinges on successful navigation from raw imagery resale toward integrated risk monitoring dashboards with recurring revenue characteristics. Acquisition targets should demonstrate existing Dubai International Financial Centre commercial relationships and MOHAP environmental compliance audit contracts. The signal to watch is Tawazun Council offset agreement restructuring favoring technology transfer provisions over direct procurement, which would elevate domestic ground segment operators above foreign constellation owners.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Ground Station Buildout | UAE Space Agency licensing mandates require in-country data residency for sensitive geospatial intelligence contracts. |
| AI-Enhanced Analytics Platform Launch | Machine learning pipelines for automated change detection enable subscription revenue models displacing per-image licensing. |
| Synthetic Aperture Radar Capacity Expansion | All-weather imaging penetrates sandstorm seasonality limitations constraining optical sensor operational reliability. |
| Defense Offset Agreement Partnership | Tawazun Council mechanisms channel geospatial intelligence procurement through technology transfer provisions. |
| Academic Licensing Program Expansion | Khalifa University and New York University Abu Dhabi partnerships cultivate talent pipelines and research credibility. |
Research Methodology
Coverage spans the seven emirates of the UAE with primary inputs from each, combining structured interviews with UAE Space Agency licensing officers, defense procurement officials at Tawazun Council, remote sensing directors at Mohammad Bin Rashid Space Centre, and commercial analytics buyers at Dubai International Financial Centre firms. Secondary validation drew from UAE federal budget appropriation documents, MOHAP environmental surveillance mandates, UN COPUOS national space legislation filings, and Telecommunications and Digital Government Regulatory Authority spectrum allocation records. Bottom-up segmentation modeling triangulated against top-down macroeconomic projections for sovereign space program expenditure.
Rate-of-change decomposition across the projection horizon isolated technology adoption curves, regulatory enforcement timelines, and defense procurement cycle phasing as independent variables. Segmentation dimensions modeled include service type, application vertical, end user category, and sensor technology platform, with cross-tabulation against emirate-level demand concentration. CAGRs derived from historical contract value analysis adjusted for announced sovereign capability investments and foreign operator localization commitments. Industry-specific forecast inputs incorporated KhalifaSat program launch schedules and Etihad Water and Electricity transmission corridor mapping procurement patterns.
Underlying measurement precision varies by segment; defense and government end user categories carry tighter precision than emerging commercial verticals given classified contract disclosure limitations. Forecasts reflect documented assumptions regarding UAE Space Agency licensing framework evolution and Tawazun Council offset agreement restructuring. Stakeholders should weight assumptions against their own operating context, particularly regarding data sovereignty enforcement intensity and small satellite launch cost trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Satellite Bus Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Israel Satellite Communications Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Cubesat Market
Satellite
Low-Cost Satellite Market
Satellite
Satellite Internet Market
Satellite
Canada Satellite Connectivity Market
Satellite
Nano and Microsatellite Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Military Satellite Market
Satellite
China Satellite Communication Market
Satellite
Global Enterprise VSAT System Market