
 Global Combination Vaccine Market | 2026-2036
Global Combination Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Combination Vaccine Market Foresight
Multivalent formulation standards are redrawing competitive boundaries in combination vaccines. GSK leverages its adjuvant platform and manufacturing scale to sustain leadership across pentavalent and hexavalent portfolios. Sanofi anchors European supply security through its differentiated meningococcal-pneumococcal conjugate capabilities. Serum Institute of India dominates emerging-market procurement by controlling cost structures for WHO-prequalified DTP-HepB-Hib combinations.
A combination vaccine integrates multiple antigens into a single immunization product, typically combining bacterial toxoids, viral subunits, or conjugated polysaccharides within shared formulation buffers and stabilizer matrices to reduce injection burden and cold-chain complexity. Its primary purpose is to streamline national immunization schedules while preserving seroprotection rates equivalent to individually administered components. The hexavalent category occupies the fastest-expanding margin pool as countries consolidate infant schedules into single-visit delivery. Recombinant technology leads investment intensity among platform approaches, though live attenuated platforms retain entrenched positions in MMR supply. Public health programs channel the dominant procurement volume, with tender aggregation creating price compression that private clinic segments partially escape through branded premium positioning.
FDA's combination vaccine guidance and EMA's CHMP quality benchmarks shape antigen compatibility testing and lot-release protocols that determine market access timelines. WHO prequalification inspection standards further constrain which manufacturing sites can supply Gavi-eligible countries, filtering the effective supplier base. India's CDSCO and China's NMPA operate parallel national regulatory pathways that add complexity for multinational sponsors seeking simultaneous approvals across high-volume markets. Stakeholders must monitor evolving regulatory convergence between WHO, FDA, and EMA on interchangeability standards for multivalent products as these will determine substitution economics in tender markets.
Market Dynamics
Consolidation of infant immunization schedules into single-visit hexavalent delivery is compressing procurement cycles and rewarding manufacturers with integrated antigen platforms and WHO-prequalified supply chains.
Growth Catalysts
- EMA Centralized Approval:The EMA's centralized marketing authorization procedure accelerates multivalent vaccine registration across 27 member states, reducing time-to-market for hexavalent formulations by consolidating quality benchmarks and lot-release protocols.
- Hexavalent Schedule Consolidation:National immunization programs in India, Nigeria, and Indonesia are converging DTP-HepB-Hib-IPV into single-dose infant protocols, eliminating cold-chain touchpoints and clinic visit frequency.
- Recombinant Platform Maturation:Yeast and CHO cell expression systems for hepatitis B surface antigen and acellular pertussis toxoids are achieving yield parity with traditional fermentation, enabling cost structures compatible with Gavi-tier pricing.
Market Restraints
- Aluminum Adjuvant Concentration Risk:Four suppliers control pharmaceutical-grade aluminum hydroxide and phosphate supply, with Indian and Chinese export licensing creating intermittent raw material bottlenecks for formulation buffers.
- Antigen Compatibility Failures:Physical and chemical interactions between conjugated polysaccharides and toxoid proteins in shared formulations trigger stability failures that extend development timelines by 18-36 months.
- Lyophilization Equipment Backlogs:Freeze-dryer manufacturing capacity at German and Italian equipment suppliers carries 24-month order queues, constraining site expansion for heat-stable pentavalent and hexavalent presentations.
Strategic Opportunities
- Indonesia's Subnational Procurement Decentralization:Provincial health offices in Java and Sumatra are gaining tender autonomy, creating entry points for secondary suppliers with CDSCO-registered facilities to bypass national-level concentration.
- Japanese Elderly Combination Programs:Pneumococcal-influenza co-formulation demand among Japan's 65-plus population is outpacing pediatric growth, with PMDA's priority review voucher system accelerating adult indication approvals.
- Controlled Temperature Chain Waivers:WHO's revised stability guidance allowing 40°C exposure for limited durations opens distribution to regions lacking 2-8°C infrastructure, particularly sub-Saharan African markets previously excluded from hexavalent access.
Industry Challenges
- Conjugate Chemistry Talent Scarcity:Synthetic carbohydrate chemists capable of designing meningococcal and pneumococcal polysaccharide-protein linkers command compensation premiums that strain R&D budgets at mid-scale manufacturers.
- Legacy Fill-Finish Line Retrofitting:Existing aseptic processing suites require $40-80 million capital outlays to accommodate multivalent vaccine vial sizes and novel closure systems, freezing capacity decisions until demand visibility clarifies.
- IP Thicket Navigation:Pertussis filamentous hemagglutinin and pertactin antigen patents held across Japanese, US, and European universities complicate freedom-to-operate assessments for next-generation acellular formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Combination Vaccine Market |
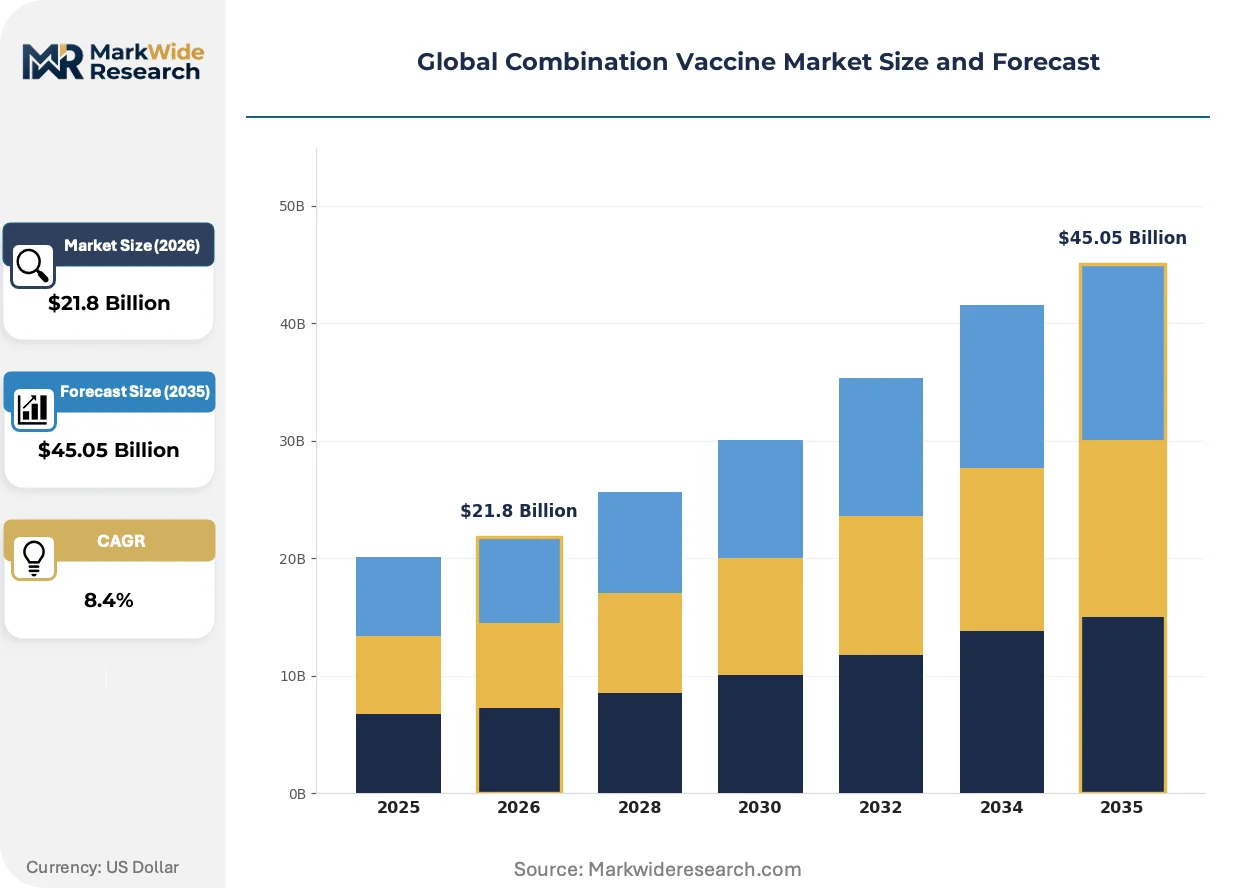
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $45.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: DTP, MMR, Pentavalent, Hexavalent, Typhoid, Hepatitis A & B Technology: Live Attenuated, Inactivated, Subunit, Toxoid, Conjugate, Recombinant Application: Infant Immunization, Adult Vaccination, Travel Medicine, Epidemic Outbreak Control, Biodefense, Geriatric Immunity End User: Public Health Programs, Private Clinics, Military Health Services, Occupational Health Providers, Humanitarian Organizations |
| Companies Covered | Sanofi, GlaxoSmithKline (GSK), Merck, Pfizer, Serum Institute of India, Sinovac, Panacea Biotec, Beijing Minhai Biological Technology, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Combination Vaccine Market Shifts & Advancements
Antigen presentation technologies and regulatory science convergence are redefining formulation stability benchmarks while procurement centralization reshapes competitive access to national immunization programs.
Messenger RNA platforms are displacing traditional recombinant protein production for viral antigens in combination vaccine development pipelines. Sanofi and Moderna are advancing mRNA-influenza combinations through Phase II trials with six-month development cycles versus 24-36 months for egg-based alternatives. This compression is forcing legacy manufacturers to accelerate platform diversification or cede respiratory combination segments to nimble biotech entrants.
WHO's revised prequalification inspection standards for multi-antigen products now mandate continuous manufacturing process validation and real-time release testing. The industrial consequence is exclusion of batch-oriented facilities lacking process analytical technology infrastructure. African and South Asian suppliers with Gavi contracts are responding by partnering with European engineering firms for continuous chromatography upgrades, deferring margin recovery until 2027-2028.
Brazil's federal procurement agency is aggregating state-level vaccine tenders into national framework agreements with five-year volume commitments and inflation-linked price adjustment mechanisms. State immunization programs in São Paulo and Minas Gerais are losing procurement autonomy to ANVISA-registered suppliers with federal contracting eligibility. This concentration is most visible in the northeast, where Pernambuco and Bahia previously sourced 30 percent of pentavalent volumes through independent state tenders now absorbed into federal consolidated purchasing.
Global Combination Vaccine Market Segmentation
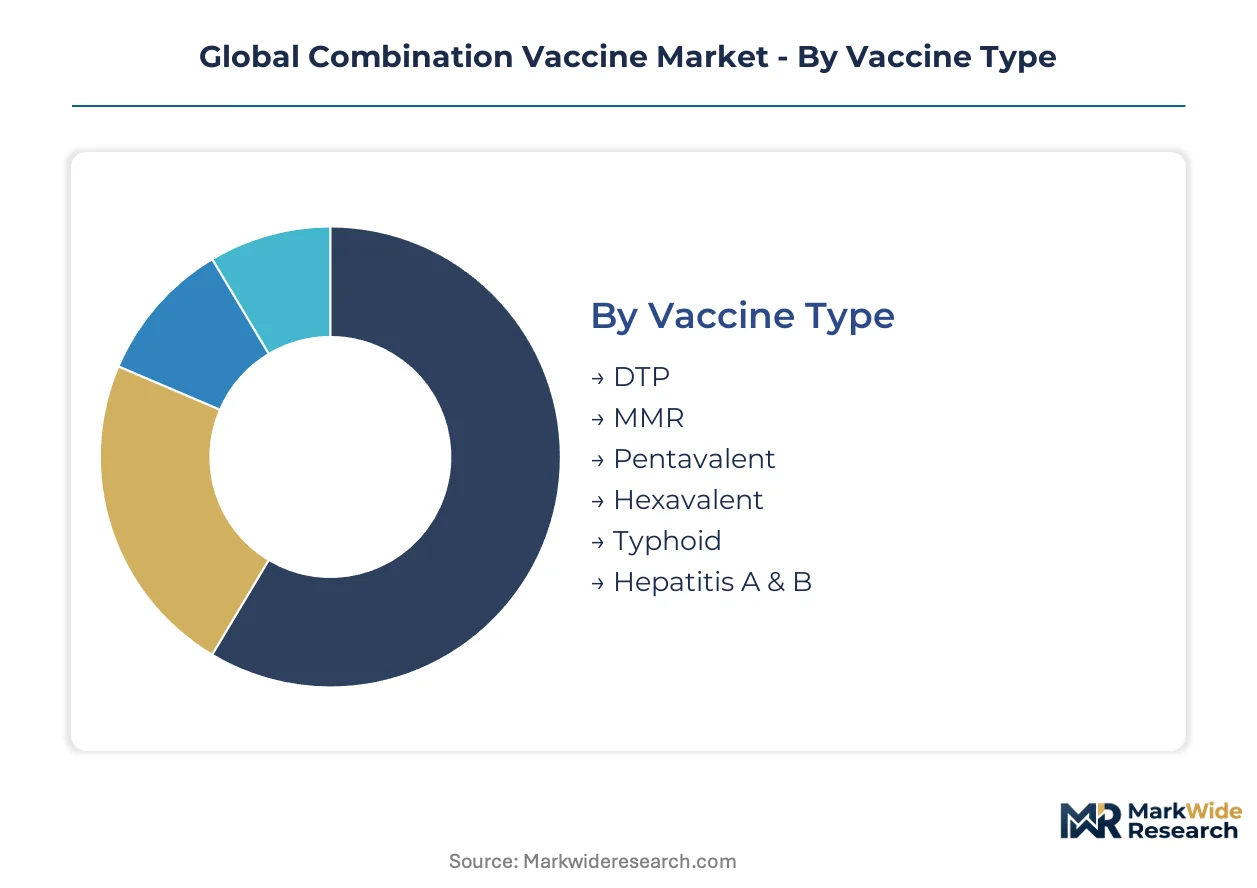
Segmentation in combination vaccines determines procurement pathways, cold-chain requirements, and regulatory approval strategies. Manufacturers align platform investments to specific antigen combinations and end-user channels where tender aggregation and pricing power diverge most sharply.
Vaccine Type:
Margin pools concentrate in multivalent formulations where single-dose delivery commands premium positioning against commodity monovalent alternatives.
- Hexavalent:Combines DTP-HepB-Hib-IPV antigens into single infant doses, eliminating three separate injections and four cold-chain touchpoints. Demand concentrates in India's national immunization program and Gavi-eligible African countries consolidating clinic visit schedules.
- Pentavalent:Integrates DTP-HepB-Hib without IPV, serving markets where inactivated polio vaccine remains separately administered through supplemental campaigns. Nigeria and Indonesia maintain this split-protocol approach due to IPV supply intermittency.
- DTP:The foundational three-antigen combination against diphtheria, tetanus, and pertussis, manufactured at highest volume for basic immunization schedules.
- MMR:Live attenuated measles-mumps-rubella combination retaining entrenched supply positions through established cold-chain infrastructure.
- Typhoid:Vi-polysaccharide conjugate or live oral formulations for endemic zone deployment and traveler segments.
- Hepatitis A & B:Twinrix-type combinations for adult traveler and occupational health markets with private clinic pricing power.
The dominant share belongs to Pentavalent through Gavi procurement volume, while Hexavalent is closing the gap fastest as national programs consolidate schedules.
Technology:
Platform selection drives manufacturing capital intensity, yield economics, and regulatory pathway duration for multivalent product development.
- Recombinant:Yeast and CHO cell expression systems for hepatitis B surface antigen and acellular pertussis components achieve yield parity with traditional fermentation. Indian manufacturers deploy this platform to meet WHO prequalification cost benchmarks.
- Conjugate:Polysaccharide-protein chemistry for meningococcal and pneumococcal antigens commands specialized synthetic carbohydrate expertise. EMA centralized approvals for hexavalent conjugate formulations require extensive compatibility validation.
- Live Attenuated:MMR production relies on chicken embryo fibroblast culture with established but rigid cold-chain dependencies.
- Inactivated:Whole-cell or split virion platforms for IPV and seasonal influenza components in combination formulations.
- Subunit:Purified protein antigens including acellular pertussis toxoids and filamentous hemagglutinin.
- Toxoid:Formalin-inactivated diphtheria and tetanus toxins forming the bacterial backbone of DTP-based combinations.
Conjugate chemistry captures the steepest expansion trajectory as countries add pneumococcal coverage to infant schedules, while Recombinant platforms hold the largest installed manufacturing base.
Application:
Application segments separate by procurement channel concentration, with public tenders dominating volume and private channels preserving price premiums.
- Infant Immunization:National program schedules for DTP-based combinations constitute the procurement volume anchor. Brazil's ANVISA-registered suppliers compete for federal framework agreements with five-year commitments.
- Adult Vaccination:Pneumococcal-influenza combinations for working-age populations in employer-sponsored occupational health programs.
- Travel Medicine:Hepatitis A-B and typhoid combinations for pre-departure clinic consultations with limited price sensitivity.
- Epidemic Outbreak Control:Emergency stockpile deployment of measles-containing vaccines for reactive campaign use.
- Biodefense:Anthrax-smallpox combinations for national strategic reserves with specialized procurement security protocols.
- Geriatric Immunity:Pneumococcal-influenza and zoster combinations for Japan's 65-plus population through PMDA priority review pathways.
Infant Immunization commands the dominant procurement volume, while Geriatric Immunity is gaining share fastest as aging demographics reshape immunization policy in East Asia and Western Europe.
End User:
End-user channels determine pricing architecture, with tender aggregation in public programs compressing margins that private clinic segments partially recover.
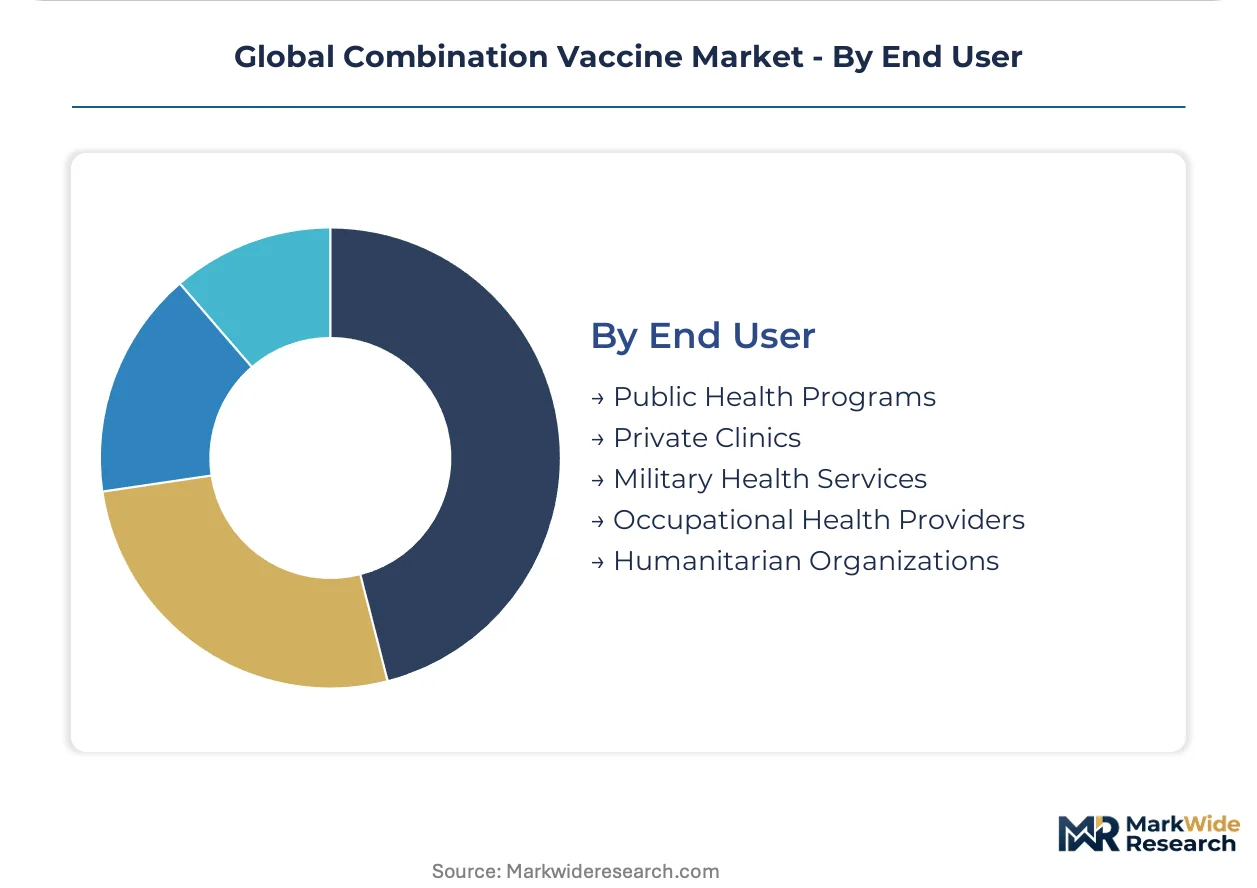
- Public Health Programs:Gavi-supported national immunization programs aggregate pentavalent and hexavalent demand through WHO prequalified supplier pools. Serum Institute of India and GSK compete on cost structure for multi-year tenders.
- Private Clinics:Branded premium positioning for travel and adult combinations escapes price compression, particularly in urban Indian and Southeast Asian markets.
- Military Health Services:Biodefense and deployment-ready combination stockpiles with specialized stability requirements.
- Occupational Health Providers:Employer-sponsored hepatitis and influenza programs for healthcare and laboratory worker segments.
- Humanitarian Organizations:UNICEF and MSF procurement of heat-stable presentations for conflict-zone and refugee camp deployment.
Public Health Programs hold the dominant procurement volume, while Private Clinics are expanding margin contribution fastest as branded adult and travel segments deepen in middle-income cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in combination vaccines tilt heavily toward manufacturing concentration in India and supply security investments in Europe and North America. Nations with domestic fill-finish capacity command procurement leverage, while import-dependent markets face cold-chain vulnerability and tender price volatility.
India
Serum Institute of India and domestic manufacturers supply WHO-prequalified pentavalent and hexavalent volumes for Gavi-eligible countries through CDSCO-registered facilities. The national immunization program aggregates demand through federal tenders, compressing margins while securing volume commitments. Hyderabad and Pune host clustered manufacturing sites with integrated antigen production and lyophilization capacity for heat-stable presentations.
United States
FDA combination vaccine guidance shapes antigen compatibility testing standards that determine lot-release timelines for multivalent products entering the national stockpile. The Biomedical Advanced Research and Development Authority channels procurement toward domestic fill-finish security, particularly for pandemic-responsive hexavalent surge capacity. Massachusetts and North Carolina concentrate recombinant platform R&D with adjacent contract manufacturing organizations supporting Phase III trials.
Germany
EMA centralized approval mechanisms accelerate multivalent registration across member states, with Paul-Ehrlich-Institut lot-release protocols setting quality benchmarks for exported European volumes. Federal procurement frameworks prioritize supply security through five-year framework agreements with inflation-linked adjustments. Marburg and Dresden anchor conjugate chemistry manufacturing with specialized carbohydrate-protein linker production for meningococcal components.
Brazil
ANVISA-registered suppliers compete for federal framework agreements consolidating previously decentralized state tenders into national purchasing pools. The northeast region's Pernambuco and Bahia states lost independent procurement autonomy, concentrating volumes with federally eligible manufacturers. São Paulo's Butantan Institute maintains domestic fill-finish partnerships for pentavalent formulations while expanding IPV integration capabilities.
Japan
PMDA priority review voucher systems accelerate adult indication approvals for pneumococcal-influenza combinations targeting the 65-plus demographic. National health insurance reimbursement schedules favor single-visit delivery formats that reduce clinic administrative burden. Osaka and Tokyo metropolitan areas concentrate geriatric immunization program deployment with specialized cold-chain infrastructure for mRNA-platform combinations.
Global Combination Vaccine Market Competitive Landscape
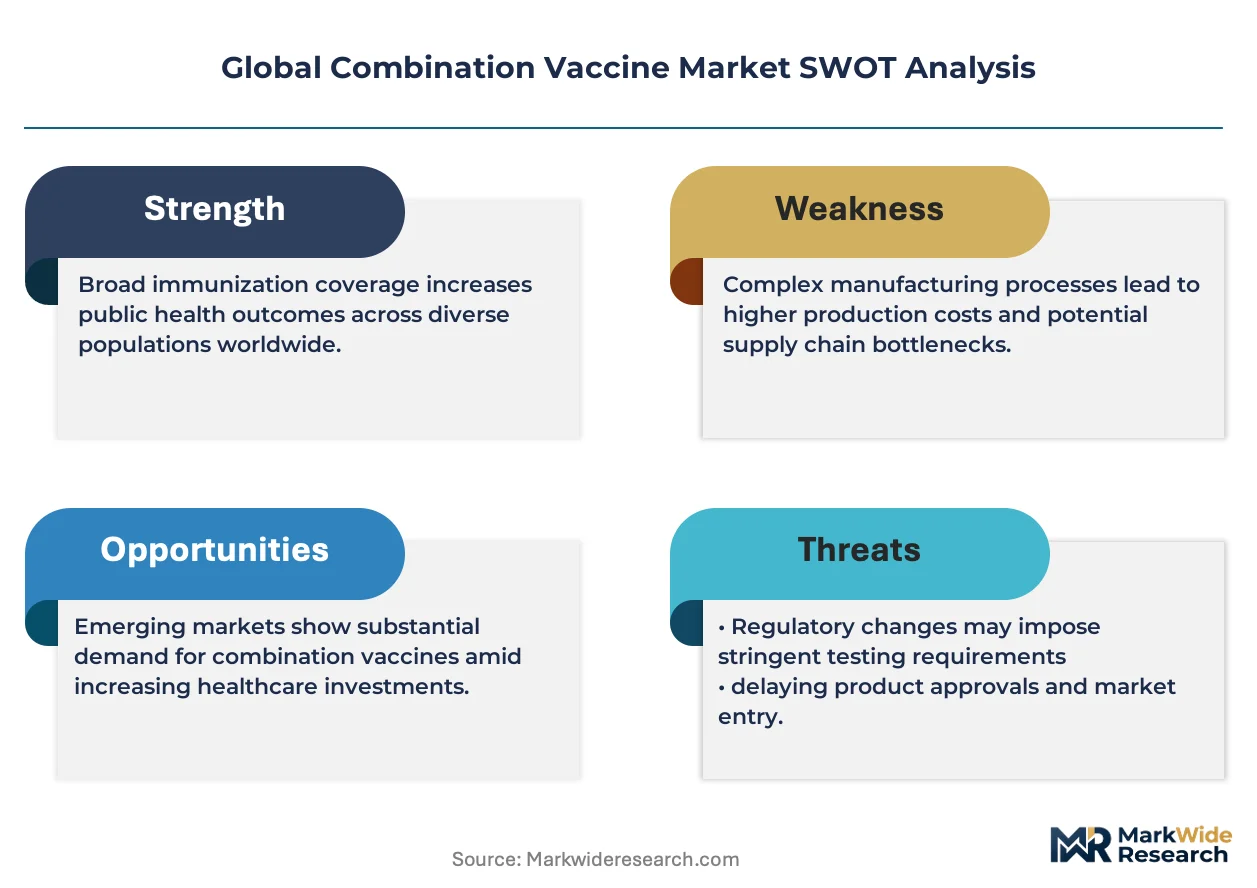
Concentration sits with integrated multinational pharmaceutical groups possessing adjuvant platforms and WHO-prequalified manufacturing networks. Three to four entities control hexavalent and pentavalent procurement channels through Gavi and national immunization program tenders, while mid-scale regional manufacturers occupy secondary positions in split-protocol markets. Strategic archetypes separate into platform-integrated innovators, cost-optimized emerging market suppliers, and specialized conjugate chemistry houses. Competitive moves center on continuous manufacturing upgrades for real-time release testing compliance and partnerships with European engineering firms for lyophilization capacity expansion.
Within the platform-integrated tier, GlaxoSmithKline and Sanofi occupy positions exemplifying adjuvant-enabled multivalent portfolio breadth, while Serum Institute of India represents the emerging market archetype with cost-optimized WHO-prequalified supply chains for Gavi-tier pricing. Merck and Pfizer sit within the conjugate-specialist vector, with Merck's presence in pediatric combination schedules and Pfizer's pneumococcal conjugate capabilities anchoring adult and infant segments respectively. These five entities collectively span the procurement concentration points from federal framework agreements to emergency stockpile deployment, with their geographic distribution across European, North American, and South Asian manufacturing clusters determining regional supply security hierarchies.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline (GSK) |
| Merck |
| Pfizer |
| Serum Institute of India |
| Sinovac |
| Panacea Biotec |
| Beijing Minhai Biological Technology |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with Gavi and national immunization programs lock in supply access for pentavalent and hexavalent volumes while compressing price visibility through inflation-linked adjustment clauses. Serum Institute of India and GSK anchor procurement economics by committing fill-finish capacity years ahead of delivery, freezing out spot-market competitors from tender participation.
Pricing Analysis
Public health program buyers anchor three-tier pricing structure across premium, standard, and economy levels, with WHO prequalification status and volume scale as the primary differentiation drivers. Pricing pressure stems from tender aggregation in Brazil's federal framework agreements and India's national immunization program, where five-year commitments force margin compression. Private clinic segments exhibit the least price sensitivity, absorbing branded premiums for travel and adult combinations in urban Indian and Southeast Asian markets.
Supply Chain Analysis
India and China anchor pharmaceutical-grade aluminum hydroxide and phosphate production for adjuvant formulations, with German and Italian equipment suppliers controlling lyophilization capacity. The supply chain draws from recombinant yeast and CHO cell expression systems for hepatitis B surface antigen, plus synthetic carbohydrate chemistry for meningococcal conjugate linkers. Single-source vulnerability concentrates in freeze-dryer manufacturing, where 24-month order queues constrain heat-stable presentation expansion. Distribution runs through WHO prequalified cold-chain networks to Gavi-eligible countries, with regional fill-finish partnerships bypassing import bottlenecks in Brazil and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated federal procurement frameworks, as Brazil's ANVISA-registered suppliers and India's CDSCO-tender aggregation eliminate state-level autonomy and fragment independent purchasing channels.
For Market Incumbents: Consolidate adjuvant platform control and WHO prequalified manufacturing networks against mRNA-platform entrants displacing traditional recombinant production. Serum Institute of India's cost-optimized supply chains and GSK's EMA centralized approval advantages create defensive moats, but continuous manufacturing upgrades for real-time release testing compliance represent the critical capacity lever. Backward integration into aluminum adjuvant production mitigates raw material bottlenecks from Indian and Chinese export licensing volatility. For New Entrants and Emerging Players: Heat-stable presentation gaps in sub-Saharan African markets, where controlled temperature chain waivers open distribution to regions lacking 2-8°C infrastructure, represent the most penetrable white space. Provincial health offices in Indonesia's Java and Sumatra regions offer tender autonomy entry points bypassing national-level concentration. A CDSCO-registered facility partnership with European engineering firms for lyophilization capacity expansion provides the fastest go-to-market angle for WHO prequalification eligibility. For Investors and Strategic Acquirers: Synthetic carbohydrate chemistry specialists with meningococcal and pneumococcal polysaccharide-protein linker capabilities command scarcity premiums that strain R&D budgets at mid-scale manufacturers, positioning them as priority acquisition targets. Long-term viability over the coming decade hinges on conjugate chemistry talent pipelines and continuous chromatography infrastructure for process analytical technology compliance. The signal to watch is WHO prequalification inspection standard convergence on real-time release testing, which will exclude batch-oriented facilities and trigger consolidation among Gavi-contracted African and South Asian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | EMA centralized approval mechanisms accelerate multivalent registration across member states through consolidated quality benchmarks. |
| Continuous Manufacturing Scale-Up | Process analytical technology infrastructure upgrades enable real-time release testing compliance for Gavi contract retention. |
| Lyophilization Capacity Expansion | Heat-stable pentavalent and hexavalent presentations unlock sub-Saharan African markets lacking cold-chain infrastructure. |
| Adjuvant Backward Integration | In-house aluminum hydroxide production mitigates raw material bottlenecks from concentrated supplier bases. |
| mRNA Platform Diversification | Six-month development cycles for viral antigens compress timelines versus traditional egg-based recombinant alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at EMA and WHO prequalification units, vaccine development executives at adjuvant platform manufacturers, and national immunization program procurement directors, then refined against secondary validation from FDA combination vaccine guidance documents, EMA CHMP quality benchmarks, ClinicalTrials.gov pipeline disclosures, and Gavi tender aggregation records. Bottom-up volume modeling across hexavalent, pentavalent, and DTP antigen combinations triangulated with top-down market sizing from public health program expenditure databases.
Variance decomposition across the projection horizon isolates volume drivers by vaccine type, technology platform, application segment, and end-user channel, with specific modeling of infant immunization schedule consolidation rates and geriatric immunity program expansion patterns. CAGRs derive from segment-level growth rate reconciliation against macroeconomic healthcare expenditure indicators and regulatory approval pathway duration assumptions. Forecast inputs incorporate EMA centralized approval timelines, WHO prequalification inspection standards, and controlled temperature chain waiver adoption curves.
Underlying assumptions cover antigen compatibility stability, aluminum adjuvant supply continuity, and lyophilization equipment delivery schedules, with deviation risk concentrated in regulatory convergence timelines for interchangeability standards and mRNA platform displacement rates for viral antigen production. Recalibration cycles align with material shifts in WHO prequalification inspection protocols, Gavi tender framework restructuring, and national immunization program schedule consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Theophylline and Aminophylline Market