
 Cough Oral Solution Market | 2026-2036
Cough Oral Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Oral Solution Market Insights
India is fragmenting cough oral solution manufacturing capacity as domestic API sourcing expands and contract manufacturing scales. Johnson & Johnson leverages its pediatric formulation expertise to sustain shelf presence across North American pharmacy chains. Reckitt Benckiser anchors the European expectorant segment through deep retail distribution. GlaxoSmithKline competes on clinical trial heritage in combination therapies.
A cough oral solution is a liquid pharmaceutical preparation containing one or more active ingredients—dextromethorphan, guaifenesin, or herbal extracts such as ivy leaf or thyme—dispersed in aqueous or hydroalcoholic vehicles with viscosity modifiers, flavoring agents, and preservatives, manufactured through controlled mixing, homogenization, and sterile or clean-room filling processes, designed for peroral administration to suppress cough reflex, facilitate mucus clearance, or soothe irritated respiratory mucosa. The expectorant category leads volume as wet cough prevalence drives guaifenesin demand, while the herbal segment captures premium positioning through clean-label appeal in European and Asian markets. Combination therapies concentrate margin pools where multi-symptom positioning commands pharmacist recommendation rates.
The FDA's OTC monograph reform and EMA's pharmacovigilance framework tighten safety documentation requirements, pushing manufacturers toward standardized efficacy claims and post-market surveillance commitments. India's CDSCO mandates stability testing under tropical climate conditions, creating a regulatory moat for domestic producers with validated hot-zone data. China's NMPA accelerates generic approval timelines for essential cough medicines, intensifying price competition in the world's largest volume market. Stakeholders must monitor evolving monograph classifications and regional bioequivalence standards to preserve market access and avoid reformulation costs.
Market Dynamics
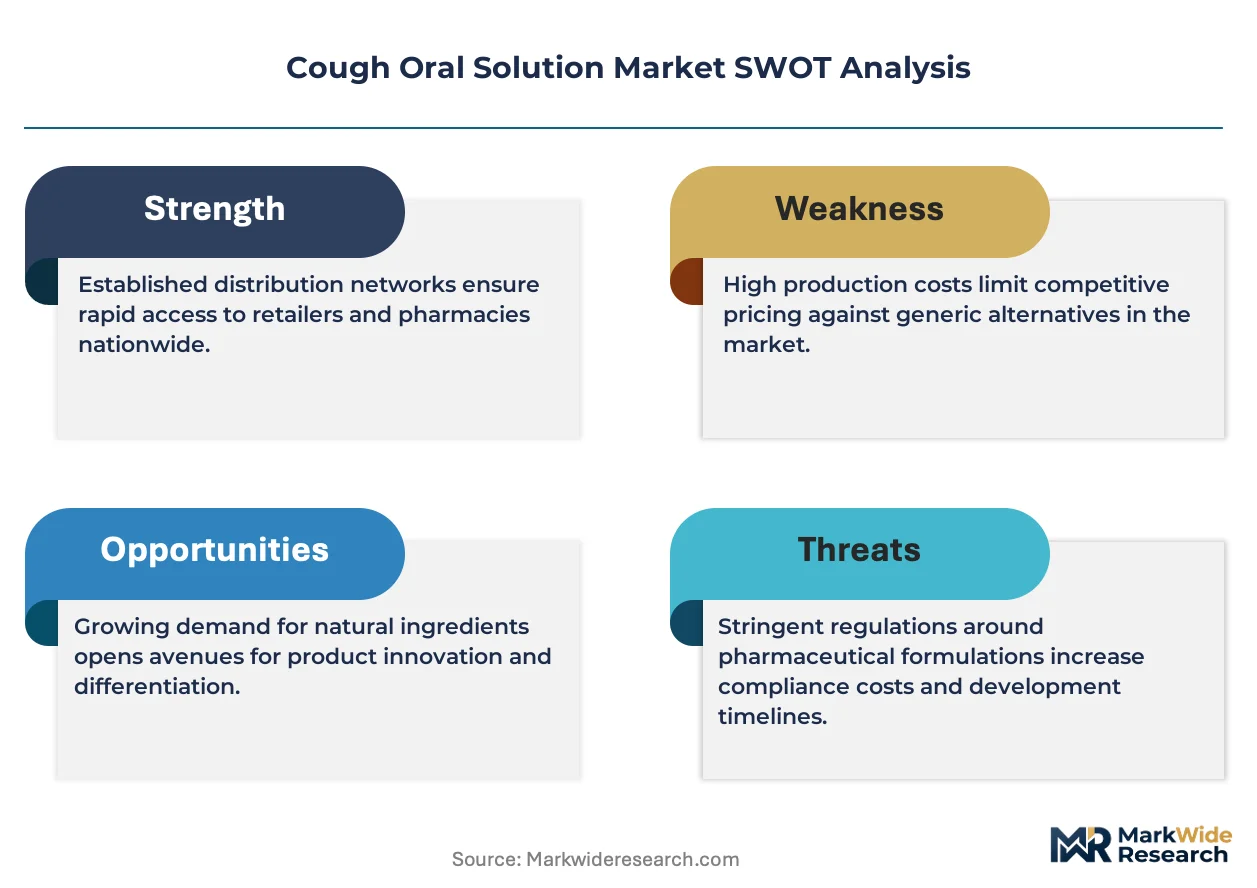
OTC monograph reform across the United States, Europe, and India is forcing manufacturers to revalidate legacy formulations and absorb compliance costs before reformulation deadlines hit.
Growth Catalysts
- FDA OTC Monograph Reform:The FDA's updated monograph framework creates clarity for new ingredient approvals, accelerating pipeline transitions from prescription to OTC status for combination therapies.
- Pediatric Self-Medication:Parents in retail pharmacy channels increasingly select cough oral solutions for home treatment, expanding unit volumes in family-oriented product lines.
- CDSCO Tropical Stability Mandate:India's domestic manufacturers with validated hot-zone data capture contract manufacturing demand from multinational brands seeking tropical-market registration.
Market Restraints
- API Supply Concentration:Dextromethorphan and guaifenesin active pharmaceutical ingredients concentrate among Chinese and Indian bulk manufacturers, exposing formulators to price volatility and supply disruption.
- EMA Pharmacovigilance Documentation:Post-market surveillance commitments for herbal extracts impose recurring analytical costs that compress margins for European specialty producers.
- Substitution by Inhalation Devices:Nebulized bronchodilators and dry powder inhalers displace oral solutions in managed care settings where rapid onset commands formulary preference.
Strategic Opportunities
- NMPA Accelerated Generic Pathway:China's streamlined approval for essential cough medicines enables first-mover positioning in the world's largest volume market before price competition intensifies.
- Clean-Label Herbal Positioning:Ivy leaf and thyme formulations command premium shelf space in German and French pharmacies where pharmacist recommendation drives substitution away from synthetic actives.
- E-Pharmacy Direct Distribution:Telehealth-integrated delivery platforms in India and Southeast Asia bypass traditional wholesale markups, capturing margin recovery and patient adherence data.
Industry Challenges
- Formulation Scientist Shortage:Expertise in hydroalcoholic stability and pediatric palatability masking resides with aging specialists in European and North American R&D centers, constraining pipeline velocity.
- Legacy System Integration:Track-and-trace serialization requirements for the Drug Supply Chain Security Act collide with decades-old manufacturing execution systems at mid-sized contract manufacturers.
- Bioequivalence Study Backlogs:Regional reference product shortages delay generic filing timelines, particularly for combination therapies requiring complex pharmacokinetic bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Oral Solution Market |
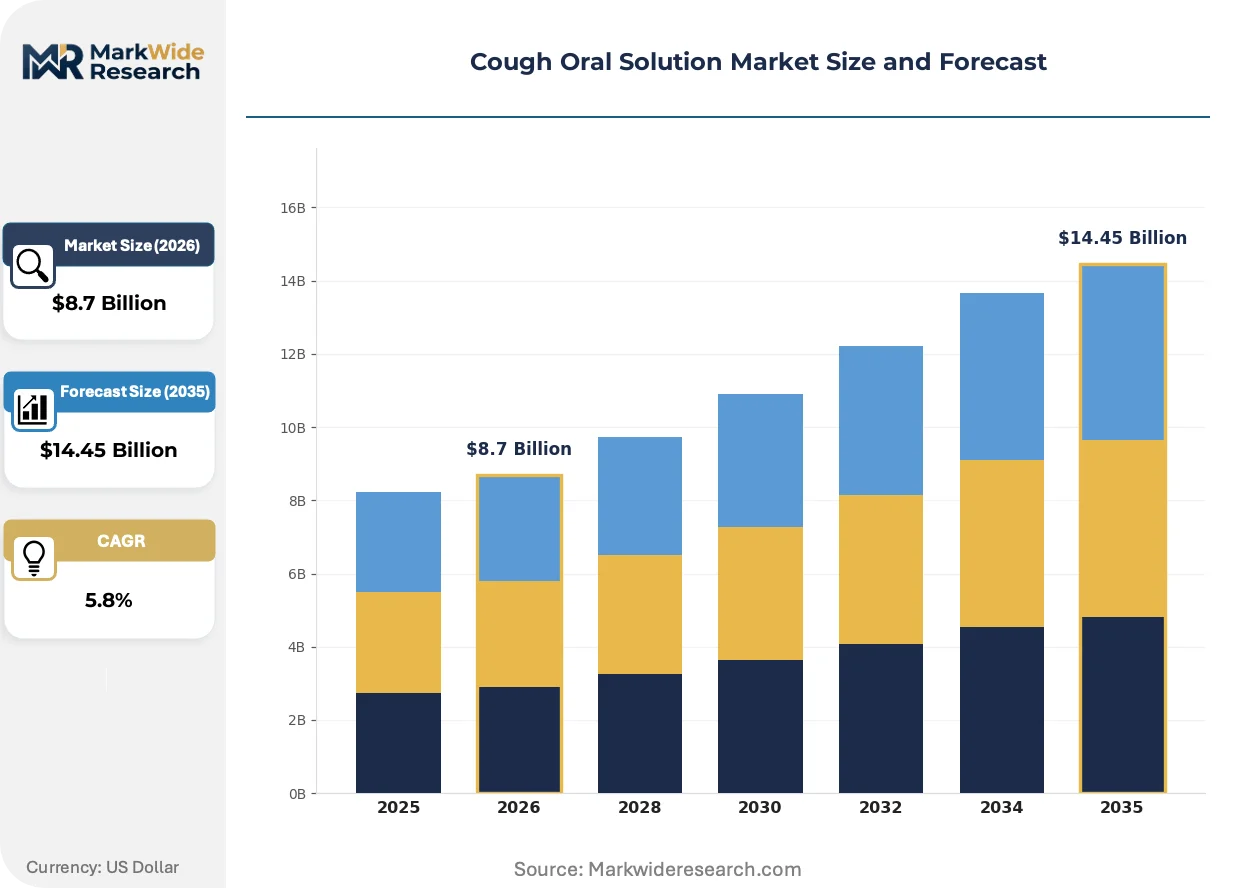
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expectorants, Antitussives, Combination, Herbal Therapy Area: Dry Cough, Wet Cough, Allergic Cough, Smokers' Cough Packaging Type: Bottles, Sachets, Vials, Blister Packs End User: Pharmacies, Hospitals, Supermarkets, Online Retailers |
| Companies Covered | Johnson & Johnson, Reckitt Benckiser Group plc, GlaxoSmithKline plc, Pfizer Inc., Bayer AG, Haleon, Procter & Gamble, Perrigo Company plc, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Oral Solution Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how cough oral solutions reach patients, with viscosity engineering, regulatory data standards, and channel fragmentation each commanding strategic attention.
Extended-release mucoadhesive polymers are migrating from niche pediatric applications toward mainstream adult expectorant formulations. These viscosity-modified systems prolong mucosal contact time, improving guaifenesin efficacy in overnight dosing scenarios. European contract manufacturers with hot-melt extrusion capabilities capture formulation partnerships as brand owners seek differentiation beyond standard syrup vehicles.
EMA's updated pharmacovigilance framework tightens safety signal detection requirements for herbal combination products, compelling manufacturers to invest in real-world evidence infrastructure. The industrial consequence is a bifurcation between large players with dedicated epidemiology teams and smaller herbal specialists facing outsourcing costs. German and Austrian producers with established phytovigilance networks leverage this as a competitive moat against new market entrants.
Pharmacist recommendation algorithms in European pharmacy chains now integrate reimbursement data and local epidemiological patterns, displacing traditional brand loyalty as the primary purchase driver. This behavioral shift concentrates volume behind products with demonstrated formulary compliance and regional indication alignment. French and Italian pharmacy cooperatives exhibit the most pronounced algorithmic procurement adoption, compressing shelf diversity while rewarding clinical trial heritage.
Cough Oral Solution Market Segmentation
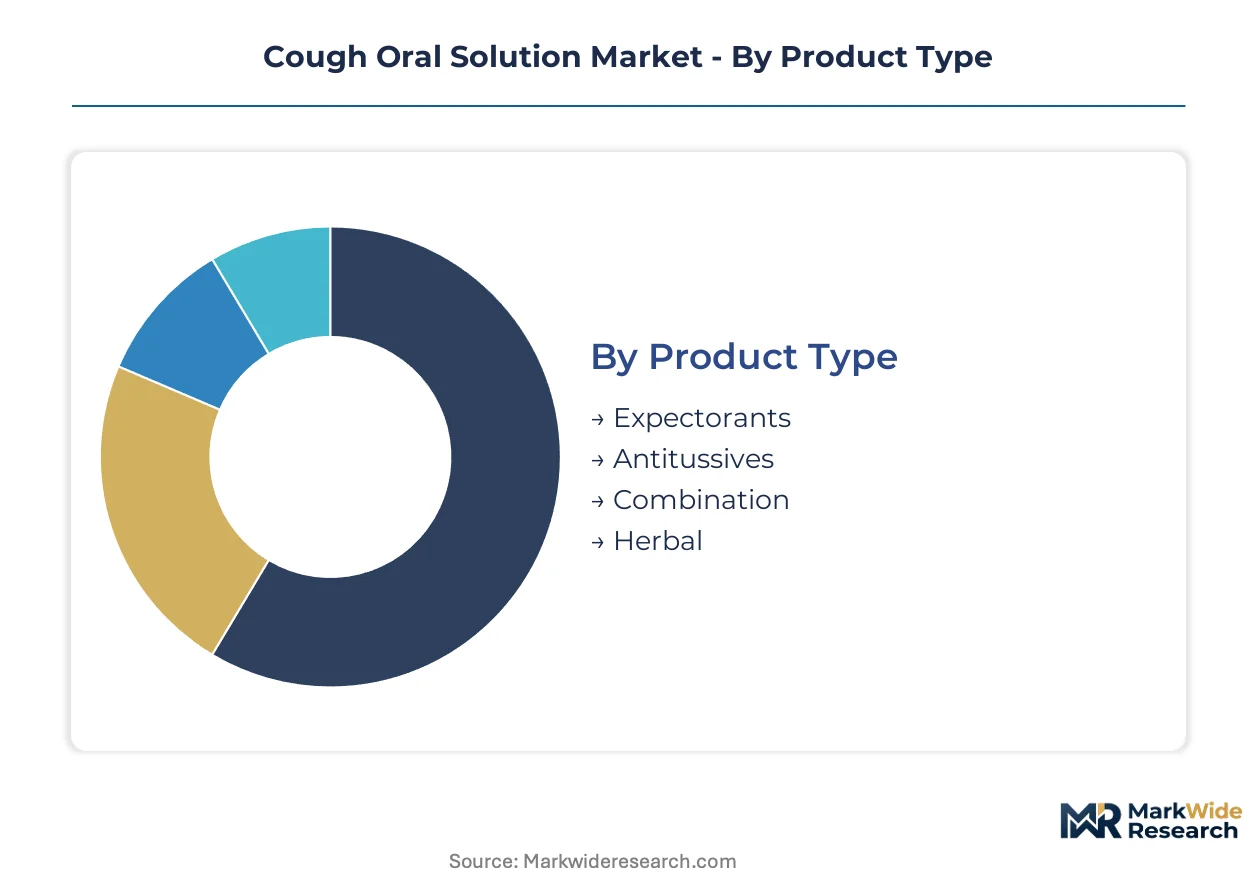
Cough oral solutions fragment across formulation science, therapeutic indication, and distribution channel. Each segmentation dimension carries distinct margin profiles and regulatory requirements that reshape competitive positioning.
Product Type:
Use-case spectrum spans symptomatic suppression to mucus clearance, with formulation complexity determining reimbursement tiers and shelf placement.
- Expectorants:Guaifenesin-based formulations reduce sputum viscosity through enhanced hydration of respiratory mucus. Wet cough prevalence in pediatric and geriatric populations across the United States, China, and India drives volume concentration, though EMA pharmacovigilance documentation imposes recurring analytical costs on European producers.
- Combination:Multi-symptom formulations pair dextromethorphan with expectorants or antihistamines to address concurrent cough and cold symptoms. Pharmacist recommendation algorithms in French and Italian pharmacy cooperatives concentrate volume behind these clinically differentiated products.
- Antitussives:Dextromethorphan-centered formulations suppress cough reflex at the medullary level.
- Herbal:Ivy leaf and thyme extracts capture premium positioning through clean-label appeal.
Established volume favors Expectorants; emerging adoption favors Combination.
Therapy Area:
Patient presentation and underlying pathology dictate formulation selection, with diagnostic clarity improving through retail pharmacy triage protocols.
- Wet Cough:Productive cough with mucus expectoration responds to guaifenesin and mucolytic agents. Prevalence clusters in seasonal respiratory infection cycles across temperate climates, with India's CDSCO tropical stability mandate creating regulatory moats for domestic manufacturers with validated hot-zone data.
- Dry Cough:Non-productive cough without mucus production targets antitussive suppression. Post-viral and medication-induced presentations in managed care settings face substitution pressure from nebulized bronchodilators where rapid onset commands formulary preference.
- Allergic Cough:Histamine-mediated respiratory irritation requires antihistamine combination therapy.
- Smokers' Cough:Chronic bronchitic presentation in long-term tobacco users demands specialized mucolytic protocols.
Clinical incidence concentrates in Wet Cough; therapeutic innovation concentrates in Allergic Cough.
Packaging Type:
Unit economics and patient adherence requirements reshape primary packaging selection across institutional and retail channels.
- Bottles:Multi-dose amber or opaque PET containers with child-resistant closures dominate household stocking behavior. North American pharmacy chains and European pharmacy cooperatives favor this format for family-oriented product lines where dosing flexibility matters.
- Sachets:Single-unit flexible pouches enable precise dosing and travel portability. India's e-pharmacy direct distribution platforms and Southeast Asian telehealth-integrated delivery systems accelerate adoption of this format for margin recovery and patient adherence tracking.
- Vials:Small-volume glass or plastic containers serve institutional dispensing.
- Blister Packs:Unit-dose cavity packaging supports compliance packaging programs.
Household penetration favors Bottles; channel disruption favors Sachets.
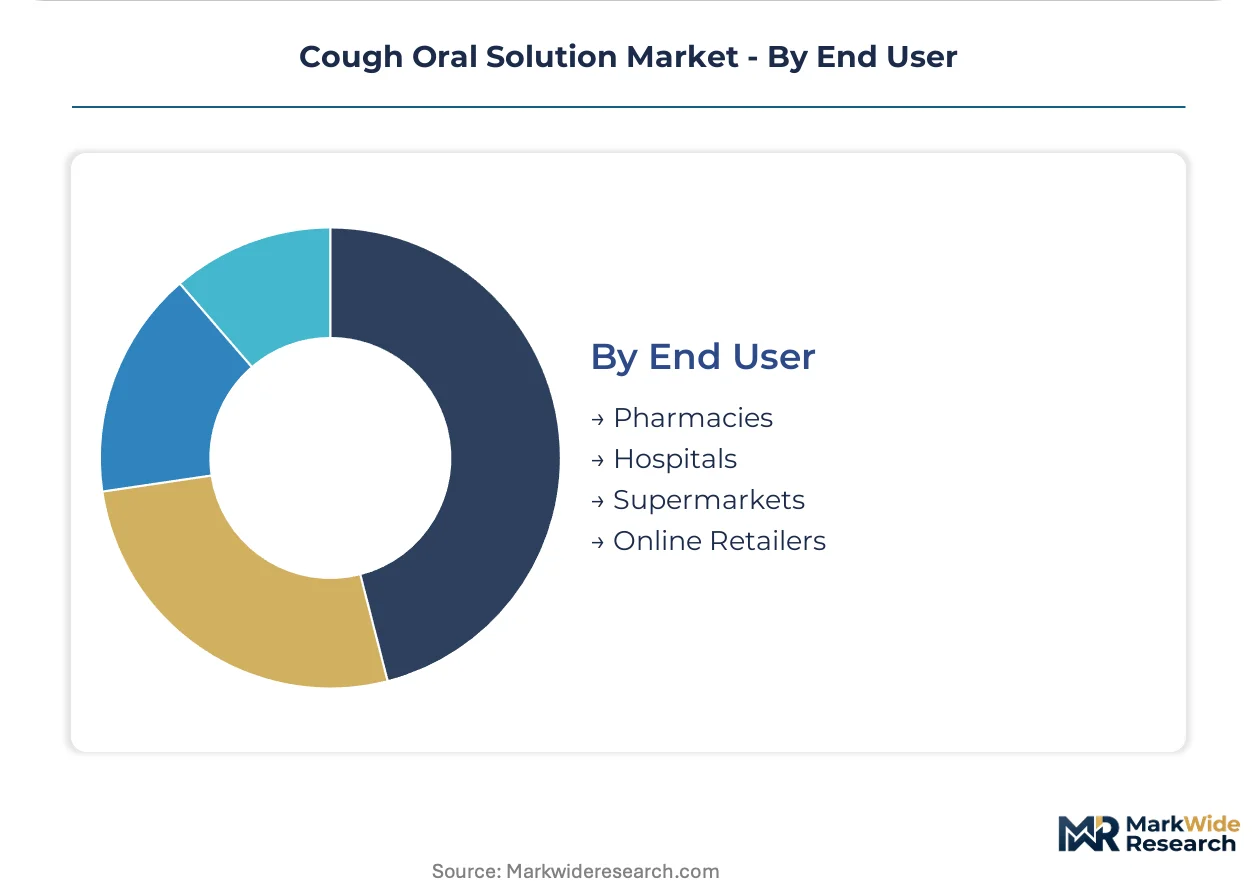
End User:
Procurement authority and patient access pathways determine pricing architecture and promotional investment allocation.
- Pharmacies:Community and chain pharmacy networks remain the primary recommendation-driven channel. German and French pharmacy markets exhibit pronounced algorithmic procurement adoption, compressing shelf diversity while rewarding products with demonstrated formulary compliance.
- Online Retailers:Direct-to-patient platforms bypass traditional wholesale markups. India's e-pharmacy ecosystem and China's NMPA-accelerated generic pathway converge to enable first-mover positioning before price competition intensifies.
- Hospitals:Institutional formularies prioritize rapid-onset alternatives.
- Supermarkets:Mass-market self-selection channels compete on brand recognition and promotional pricing.
Recommendation authority favors Pharmacies; margin recovery favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States favors multi-symptom combination therapies through pharmacy chains, while India and China concentrate volume in single-ingredient expectorants distributed through fragmented retail networks. European markets split between synthetic actives in northern countries and herbal formulations in German-speaking and Mediterranean regions.
United States
Pediatric self-medication drives family-oriented product lines through CVS, Walgreens, and independent pharmacy networks. The FDA's OTC monograph reform accelerates prescription-to-OTC transitions for combination therapies containing dextromethorphan-guaifenesin pairings. New Jersey and Pennsylvania host formulation R&D clusters where contract manufacturers validate hydroalcoholic stability protocols for tropical export registration.
China
Wet cough prevalence in northern industrial cities sustains guaifenesin demand through hospital-affiliated retail pharmacies. The NMPA's accelerated generic approval pathway compresses timelines for essential cough medicines, intensifying price competition before multinational brands establish formulary position. Yangtze River Delta manufacturing bases in Jiangsu and Zhejiang provinces scale API-to-finished-dose integration for domestic and Southeast Asian export markets.
India
Tropical climate conditions concentrate contract manufacturing demand among domestic producers with CDSCO-validated hot-zone stability data. Maharashtra and Gujarat pharmaceutical corridors expand API sourcing backward into captive dextromethorphan and guaifenesin production. E-pharmacy platforms in Bangalore and Hyderabad bypass traditional wholesale markups, capturing patient adherence data and margin recovery in telehealth-integrated distribution.
Germany
Pharmacist recommendation algorithms in pharmacy cooperatives concentrate volume behind products with demonstrated formulary compliance and regional indication alignment. EMA pharmacovigilance documentation requirements for herbal extracts impose recurring analytical costs that compress margins for specialty producers. Bavarian and Baden-Württemberg phytovigilance networks leverage real-world evidence infrastructure as competitive moats against new entrants in ivy leaf and thyme formulations.
Brazil
Seasonal respiratory infection cycles in São Paulo and Rio de Janeiro metropolitan areas drive expectorant volume through pharmacy chains and supermarket self-selection channels. ANVISA's alignment with FDA bioequivalence standards streamlines generic registration for multinational brands seeking Latin American expansion. São Paulo state's pharmaceutical manufacturing belt scales liquid dosage form capacity to serve Mercosur distribution networks.
Cough Oral Solution Market Competitive Landscape
Capability concentration sits with European phytovigilance specialists and North American pediatric formulation experts; scale advantage sits with Asian contract manufacturers and diversified consumer health conglomerates. The market structures around three tiers: multinational pharmaceutical companies with clinical trial heritage, regional herbal specialists with pharmacist recommendation networks, and emerging market contract manufacturers with tropical stability validation. Dominant competitive moves include portfolio diversification into combination therapies and backward integration into API production to secure supply continuity.
Within the multinational pharmaceutical tier, Johnson & Johnson and GlaxoSmithKline occupy positions anchored by pediatric formulation expertise and clinical trial heritage respectively. Reckitt Benckiser exemplifies the European expectorant specialist archetype through deep retail distribution networks. These three companies represent contrasting strategic postures: one leverages North American pharmacy chain relationships, another competes on combination therapy clinical data, and the third anchors shelf presence through algorithmic procurement compliance in cooperative pharmacy systems.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Reckitt Benckiser Group plc |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Bayer AG |
| Haleon |
| Procter & Gamble |
| Perrigo Company plc |
| AstraZeneca plc |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang provinces anchor API-to-finished-dose integration capacity that feeds downstream pricing power to formulators seeking tropical-market registration. Contract manufacturers with validated hot-zone stability data command premium offtake terms from multinational brands, while spot-market API buyers absorb volatility in dextromethorphan and guaifenesin inputs.
Pricing Analysis
Long-term offtake agreements dominate procurement between established brands and CDSCO-validated Indian manufacturers, insulating volume commitments from spot-price swings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and pharmacist recommendation algorithms. Cost compression in economy tiers intensifies as China's NMPA accelerates generic approvals. Hospital procurement committees exhibit highest price sensitivity; German pharmacy cooperatives demonstrate lowest sensitivity due to formulary compliance premiums.
Supply Chain Analysis
Maharashtra and Gujarat pharmaceutical corridors concentrate contract manufacturing capacity for tropical stability validation. Dextromethorphan, guaifenesin, and hydroalcoholic vehicle inputs draw from captive Indian production and Chinese bulk API sources. Single-source vulnerability concentrates in pediatric palatability masking expertise held by aging European specialists. Distribution runs through pharmacy cooperative networks in Germany and France, e-pharmacy platforms in India, and retail pharmacy chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's OTC monograph reform creates a regulatory inflection that accelerates prescription-to-OTC transitions, opening high-growth disruption for combination therapy specialists. This technological-regulatory convergence rewards first-movers with validated documentation infrastructure.
For Market Incumbents: Insulate formulation portfolios against nebulized bronchodilator substitution by deepening pediatric palatability expertise and securing backward integration into tropical stability validation. Johnson & Johnson's pharmacy chain relationships and GlaxoSmithKline's clinical trial heritage provide defensive moats, but EMA pharmacovigilance documentation commitments compress margins for herbal specialists lacking epidemiology teams.
For New Entrants and Emerging Players: Southeast Asian e-pharmacy penetration represents the most penetrable white-space target, where telehealth-integrated delivery platforms bypass wholesale markups. India's CDSCO tropical stability mandate creates regulatory moats for domestic producers with validated hot-zone data. Clean-label herbal positioning in French and German pharmacies offers pharmacist recommendation-driven entry, leveraging ivy leaf and thyme formulations to capture premium shelf space.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with tropical stability validation and phytovigilance network infrastructure. Long-term viability concentrates on players bridging API sourcing backward into captive production while maintaining EMA-compliant real-world evidence systems. The signal to watch is NMPA generic approval velocity in China's essential medicines pathway, which indicates price competition intensity ahead.
| Strategic Initiative | Industry Significance |
|---|---|
| Tropical Stability Validation Investment | CDSCO-mandated hot-zone data creates regulatory moats for Indian contract manufacturers seeking multinational offtake. |
| Phytovigilance Network Expansion | EMA's tightened herbal safety requirements reward German and Austrian producers with established real-world evidence infrastructure. |
| E-Pharmacy Platform Integration | Telehealth-integrated delivery in Bangalore and Hyderabad captures margin recovery and patient adherence data streams. |
| Combination Therapy Pipeline Advancement | FDA monograph reform accelerates prescription-to-OTC transitions for dextromethorphan-guaifenesin pairings. |
| Backward API Integration | Maharashtra and Gujarat corridors expand captive dextromethorphan production to secure supply continuity. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions driving this analysis. Primary interviews across these stakeholder roles combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up volume modeling and top-down market sizing triangulated through cross-referencing customs data and pharmacy procurement records.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning formulation type, therapy indication, packaging format, patient population, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and forward-looking scenario weighting incorporated API price volatility indices, pediatric self-medication trend lines, and e-pharmacy penetration curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese generic manufacturers or nebulized device entrants would shift outcomes beyond modeled ranges. Quarterly review of NMPA approval velocity, EMA pharmacovigilance guidance updates, and Indian e-pharmacy transaction volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Oxycodone Market