
 Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market | 2026-2036
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Foresight
Market Context
The Latin America DPP-4 inhibitors market is repositioning around a widening split between originator molecules and commoditized generic sitagliptin. Novartis leverages its cardiovascular-metabolic portfolio to sustain premium positioning in linagliptin across Brazilian teaching hospitals. Merck & Co anchors its historical sitagliptin franchise through volume agreements with Mexico's Instituto Mexicano del Seguro Social. Eli Lilly and Company differentiates via combination therapy development targeting dual-incretin pathways.
Technical Definition and Segment Structure
Dipeptide Peptidase 4 (DPP-4) inhibitors are oral antihyperglycemic agents that block the DPP-4 enzyme to prolong incretin hormone activity, with sitagliptin requiring once-daily 100 mg dosing and linagliptin offering distinct renal non-dependence for dose adjustment. These agents serve primarily as second-line therapy in type 2 diabetes mellitus where metformin monotherapy proves inadequate, preserving beta-cell function while minimizing hypoglycemia risk relative to sulfonylureas. Sitagliptin dominates volume across Latin American hospital formularies due to early entry and extensive generic availability, while linagliptin captures margin concentration in private clinic channels where renal safety profiles command pricing power. Extended-release formulations represent the fastest-expanding delivery mode segment as patient adherence programs gain traction in Colombia and Chile.
Regulatory Environment and Outlook
ANVISA in Brazil and COFEPRIS in Mexico govern DPP-4 inhibitor registration, with both agencies tightening bioequivalence standards for generic sitagliptin that filter substandard entrants from procurement tenders. Argentina's ANMAT maintains additional stability testing requirements that extend approval timelines for imported finished dosages. Stakeholders must monitor how regional pharmacoeconomic guidelines evolve to determine whether DPP-4 inhibitors retain preferred status against SGLT2 inhibitors in national essential medicine lists.
Market Dynamics
Generic sitagliptin commoditization is splitting Latin American formularies into volume-driven public procurement and premium-positioned private channels, forcing portfolio restructuring across every market participant.
Growth Catalysts
- Brazil's SUS Expansion:Type 2 diabetes management programs within Brazil's public health system are widening patient eligibility criteria and accelerating DPP-4 inhibitor dispensing through municipal pharmacy networks.
- COFEPRIS Streamlining:Mexico's bioequivalence approval acceleration is compressing generic substitution timelines and enabling faster formulary turnover for sitagliptin alternatives.
- Renal Safety Positioning:Linagliptin's dose-independence in chronic kidney disease is capturing nephrology clinic preference across São Paulo's metropolitan hospital networks.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for sitagliptin concentrates among Indian and Chinese manufacturers, exposing Latin American formulators to freight cost volatility and customs clearance delays.
- SGLT2 Substitution Pressure:Sodium-glucose cotransporter-2 inhibitors are displacing DPP-4 inhibitors in cardiovascular outcome-driven prescribing protocols across Colombian cardiology departments.
- ANMAT Stability Burden:Argentina's extended stability testing requirements for imported finished dosages stretch approval timelines beyond regional comparators, freezing market entry for new entrants.
Strategic Opportunities
- Extended-Release Formulation Growth:Once-weekly DPP-4 inhibitor delivery systems are penetrating adherence-program channels in Chilean primary care networks where patient compliance metrics drive formulary inclusion.
- Dual-Incretin Combinations:Fixed-dose combinations pairing DPP-4 inhibitors with GLP-1 receptor agonists are opening specialist endocrinology segments previously closed to oral therapy alone.
- Colombian Regional Expansion:Underpenetrated Andean mountain cities present whitespace for DPP-4 inhibitor volume growth as diabetes prevalence screening expands through subsidized regime coverage.
Industry Challenges
- Bioequivalence Laboratory Bottleneck:Limited certified testing capacity across Latin America extends generic sitagliptin approval timelines, constraining tender participation for domestic manufacturers.
- Pharmacoeconomic Justification Burden:National essential medicine list reviews in Brazil and Mexico demand head-to-head cardiovascular outcome data that many established DPP-4 inhibitor dossiers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market |
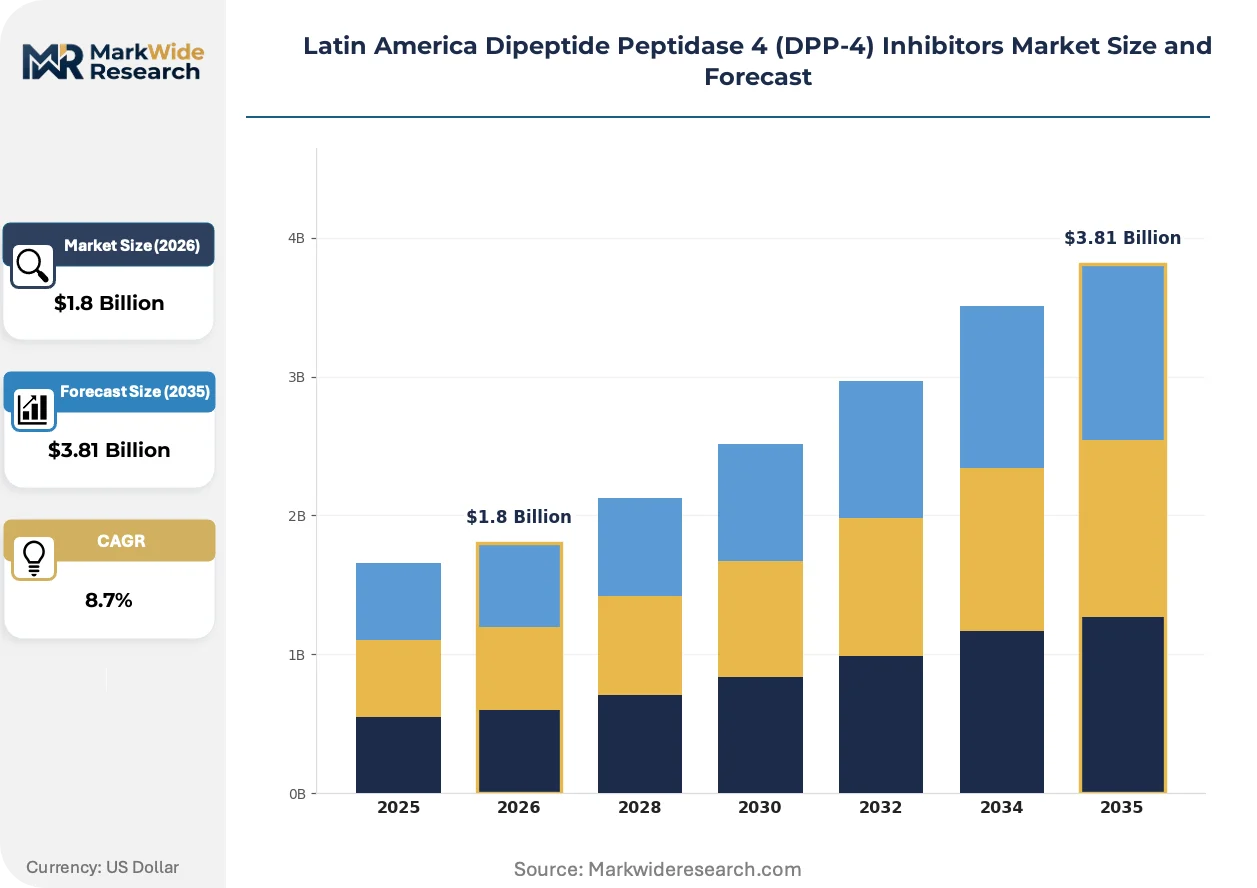
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Delivery Mode: Oral Tablets, Injectable, Combination Therapy, Extended Release End User: Hospitals, Clinics, Home Healthcare, Community Pharmacies Distribution Channel: Pharmacies, Hospital Dispensaries, Online Retail, Wholesalers |
| Companies Covered | Novartis, Eli Lilly and Company, Merck & Co, Pfizer, Boehringer Ingelheim, AstraZeneca, Takeda Pharmaceuticals, Sanofi, Bristol Myers Squibb, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Shifts & Advancements
Formulation science and procurement digitization are converging to reshape how DPP-4 inhibitors reach patients across Latin America's fragmented healthcare infrastructure.
Extended-release sitagliptin formulations are overtaking immediate-release tablets in Colombian and Chilean adherence programs. Municipal health departments in Bogotá and Santiago are prioritizing weekly-dosing options for rural diabetes outreach. This delivery mode compression is collapsing the traditional daily-dosing compliance advantage that originator brands once commanded.
ANVISA's tightened bioequivalence standards for generic DPP-4 inhibitors are filtering substandard entrants from Brazilian procurement tenders. The industrial consequence is a shakeout of undercapitalized local manufacturers unable to fund expanded clinical endpoint studies. São Paulo's metropolitan hospital networks are responding by consolidating supplier lists around proven bioequivalence dossiers.
Hospital pharmacy committees are unbundling DPP-4 inhibitor selection from cardiovascular bundle contracts that previously favored SGLT2 inhibitors. This committee-level autonomy is restoring oral therapy preference in budget-constrained public institutions. The behavioral shift is most visible in Mexico's Instituto Mexicano del Seguro Social facilities where formulary autonomy has devolved to state-level jurisdictions.
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Segmentation
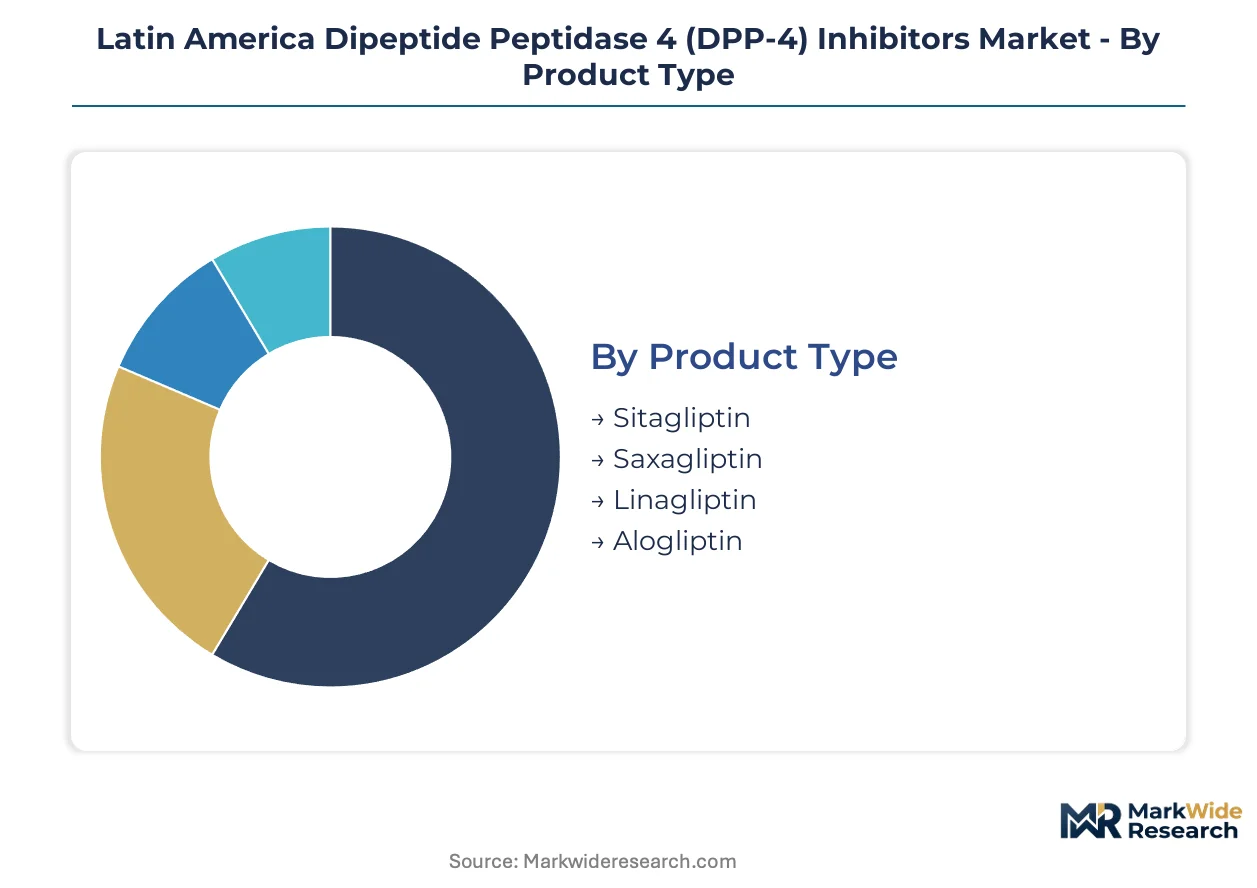
DPP-4 inhibitor segmentation in Latin America reflects divergent prescribing economics across public and private channels. Product type and delivery mode splits determine whether manufacturers compete on volume tenders or premium positioning.
Product Type:
Volume concentration versus margin capture defines competitive strategy across molecular variants.
- Sitagliptin:The first-to-market DPP-4 inhibitor dominates Brazilian municipal pharmacy networks through extensive generic substitution. São Paulo's metropolitan hospital networks anchor prescription volumes where bioequivalence-certified generics command tender participation.
- Linagliptin:Renal-independent dosing eliminates adjustment requirements in chronic kidney disease populations. Nephrology clinics across Brazil's Southeast region and Mexico City's private hospital chains drive premium positioning where dosing simplicity justifies higher acquisition cost.
- Saxagliptin:Bristol-Myers Squibb's cardiovascular outcome data supports prescribing in Mexican cardiology departments where heart failure comorbidities complicate therapy selection.
- Alogliptin:Takeda's late entrant struggles against entrenched formulary positioning in Colombia and Argentina where procurement committees favor established alternatives with deeper local dossiers.
Mature deployment sits with sitagliptin across Latin American public procurement systems. Newer deployment is concentrated in linagliptin within nephrology and private pay channels where renal safety profiles command pricing power.
Delivery Mode:
Patient adherence metrics and dosing frequency determine formulary inclusion across Chilean primary care networks and Colombian subsidized regimes.
- Oral Tablets:Immediate-release sitagliptin tablets remain the default prescribing format across Mexico's Instituto Mexicano del Seguro Social facilities where daily dosing protocols are entrenched.
- Extended Release:Once-weekly formulations penetrate adherence-program channels in Santiago and Bogotá where municipal health departments prioritize rural diabetes outreach compliance metrics.
- Combination Therapy:Fixed-dose pairing with metformin captures second-line therapy initiation in Brazilian teaching hospitals where step-up protocols from metformin monotherapy are standardized.
- Injectable:Subcutaneous DPP-4 inhibitor delivery remains niche, limited to hospitalized patients with acute glycemic instability in Argentine tertiary care centers.
Immediate-release oral tablets dominate established prescribing workflows. Extended-release formats are climbing the fastest as adherence programs expand across Andean municipal networks.
End User:
Institutional purchasing power versus patient self-management capacity shapes channel economics.
- Hospitals:Brazilian SUS-affiliated teaching hospitals drive originator molecule volume through cardiovascular-metabolic bundle contracts where formulary committees retain therapeutic class autonomy.
- Clinics:Private endocrinology practices in São Paulo and Mexico City prescribe linagliptin based on renal safety profiles, capturing margin concentration outside public procurement.
- Community Pharmacies:Generic sitagliptin dispensing concentrates in Brazilian municipal pharmacy networks where patient co-pay waivers accelerate volume throughput.
- Home Healthcare:Chronic disease management programs in Chile deploy extended-release formulations through visiting nurse protocols where dosing supervision ensures compliance.
Hospital procurement anchors volume contracting for established molecules. Home healthcare channels represent expanding deployment for adherence-optimized delivery formats.
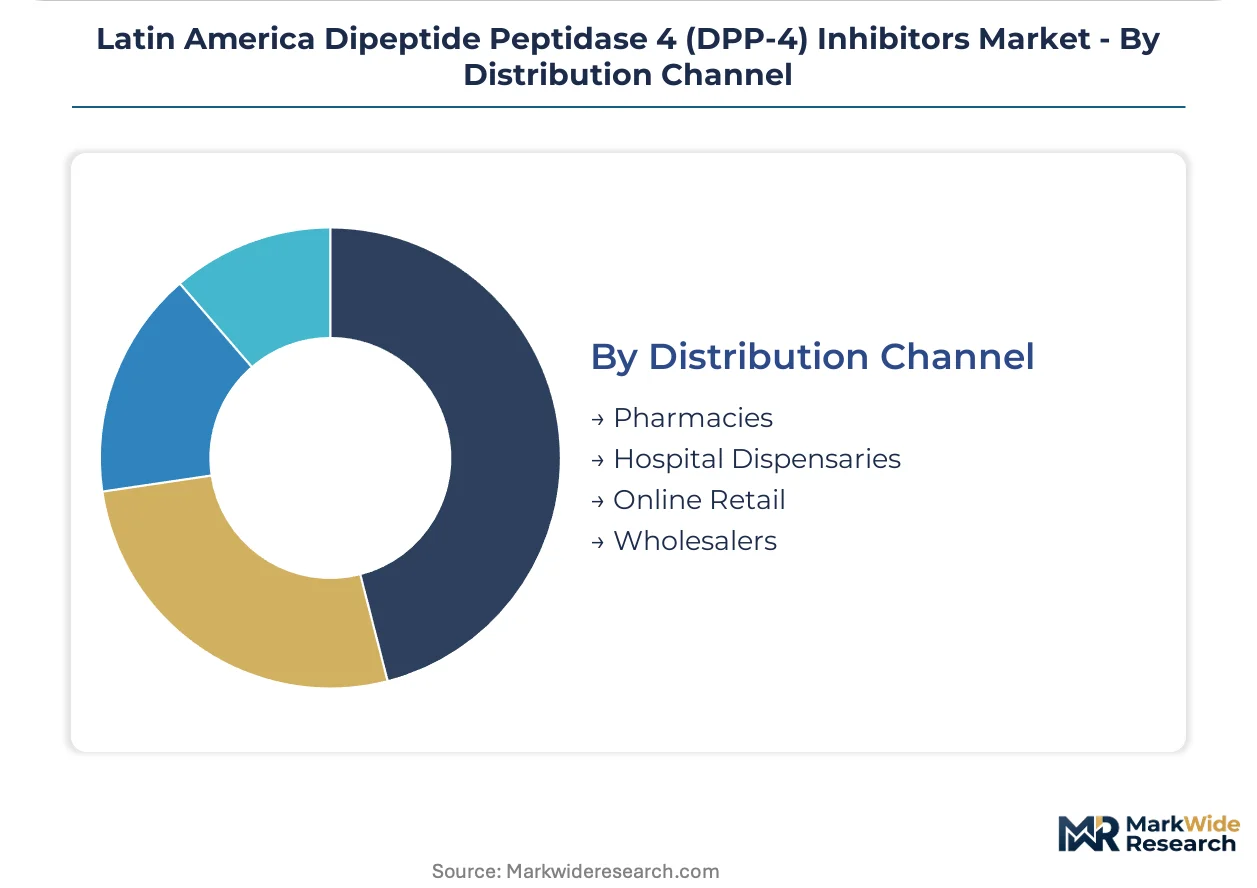
Distribution Channel:
Regulatory oversight intensity and cold-chain requirements determine channel feasibility across national boundaries.
- Pharmacies:Brazilian retail pharmacy chains process the majority of DPP-4 inhibitor prescriptions through ANVISA-regulated dispensing protocols with mandatory generic substitution options.
- Hospital Dispensaries:Captive distribution within Mexican IMSS facilities enables volume agreements where Merck & Co. anchors historical sitagliptin franchise positioning.
- Wholesalers:Regional distributors manage inventory across Argentina's extended geography where ANMAT stability testing requirements delay imported finished dosage availability.
- Online Retail:COFEPRIS-regulated e-pharmacy channels in Mexico accelerate generic substitution timelines through direct-to-patient delivery models bypassing traditional retail markup.
Hospital dispensaries concentrate procurement leverage for volume-driven molecules. Online retail channels are gaining share fastest where regulatory streamlining enables faster formulary turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan hospital networks anchor prescription volumes for DPP-4 inhibitors across Latin America, with Brazil's Southeast region commanding the largest share of regional dispensing activity.
Brazil
Brazil's SUS expansion widens patient eligibility for type 2 diabetes management programs, accelerating DPP-4 inhibitor dispensing through municipal pharmacy networks. ANVISA tightened bioequivalence standards filter substandard generic entrants from procurement tenders. São Paulo's metropolitan hospital networks consolidate supplier lists around proven bioequivalence dossiers.
Mexico
COFEPRIS regulatory streamlining compresses generic substitution timelines for sitagliptin alternatives across Mexican formularies. The Instituto Mexicano del Seguro Social anchors volume agreements for established molecules. Mexico City Metro's private hospital chains drive premium positioning for renal-independent dosing options.
Argentina
ANMAT stability testing requirements stretch approval timelines for imported finished dosages beyond regional comparators. Buenos Aires-based procurement committees favor established alternatives with deeper local dossiers. The extended geography strains inventory management through regional wholesalers.
Colombia
Bogotá's municipal health departments prioritize weekly-dosing extended-release options for rural diabetes outreach compliance metrics. Underpenetrated Andean mountain cities present whitespace for volume growth as diabetes prevalence screening expands. Cardiology departments displace DPP-4 inhibitors with SGLT2 inhibitors in cardiovascular outcome-driven protocols.
Chile
Santiago's primary care networks deploy extended-release formulations through visiting nurse protocols where dosing supervision ensures compliance. Municipal health departments prioritize adherence-program channels for once-weekly delivery systems. The subsidized regime coverage expansion targets chronic disease management in remote communities.
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across molecular differentiation and renal safety positioning. Originators with cardiovascular outcome data defend formulary placement against generic substitution. Three archetypes dominate: portfolio-integrated pharmaceutical majors, single-molecule generic specialists, and combination-therapy developers. Consolidation pressures force portfolio restructuring through bioequivalence certification investments and dual-incretin pathway expansion.
Within the portfolio-integrated tier, Novartis, Merck & Co, and Eli Lilly and Company anchor distinct competitive positions. Novartis occupies the cardiovascular-metabolic convergence space through teaching hospital networks. Merck & Co exemplifies volume-driven contracting with social security institutions. Eli Lilly and Company represents the combination-therapy development vector targeting specialist endocrinology segments. Each anchors a different margin tier: premium positioning, volume scale, and innovation pipeline respectively.
| Leading Market Players |
|---|
| Novartis |
| Eli Lilly and Company |
| Merck & Co |
| Pfizer |
| Boehringer Ingelheim |
| AstraZeneca |
| Takeda Pharmaceuticals |
| Sanofi |
| Bristol Myers Squibb |
| Others |
Supply & Pricing Matrix
Originator-generic bifurcation between linagliptin and sitagliptin manifests in divergent pricing power and sourcing configurations across Latin American procurement channels. ANVISA's tightened bioequivalence standards create a certification ladder that filters substandard generics from Brazilian tenders while concentrating premium positioning in nephrology clinics where renal-independent dosing commands margin retention.
Pricing Analysis
Value-based pricing anchors on cardiovascular outcome differentiation and renal safety profiles. Three-tier pricing structure across originator molecules, certified generics, and uncertified alternatives stratifies by bioequivalence dossier depth and clinical endpoint data. Cost compression in commodity sitagliptin intensifies as COFEPRIS accelerates Mexican generic substitution timelines. Public procurement committees exhibit highest price sensitivity, while São Paulo's private nephrology clinics demonstrate lowest sensitivity due to dosing simplicity premiums.
Supply Chain Analysis
ANVISA's local-content requirements for bioequivalence certification reshape API sourcing toward Indian and Chinese manufacturers with established dossier capabilities. Active pharmaceutical ingredient supply concentrates in India, China, and selected European Union producers. Key dependencies include sitagliptin phosphate monohydrate, linagliptin crystalline forms, and specialized excipients for extended-release matrices. Single-source vulnerability in freight consolidation points exposes formulators to customs clearance volatility. Distribution runs through hospital dispensaries for volume molecules and retail pharmacy chains for generic substitution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioequivalence laboratory capacity constraints prop pricing premiums for certified generics, creating supply-constrained margin retention for dossier-complete manufacturers.
For Market Incumbents: Hedge against SGLT2 substitution pressure by deepening cardiovascular outcome data for DPP-4 inhibitors and securing backward integration into API sourcing. Novartis and Merck & Co should prioritize ANVISA certification renewals while expanding extended-release formulation capacity in Brazilian manufacturing zones. For New Entrants and Emerging Players: Launch via COFEPRIS-fast-tracked bioequivalence pathways targeting Mexico's Instituto Mexicano del Seguro Social volume agreements. Colombian Andean mountain cities present the most penetrable whitespace, with rural diabetes outreach programs favoring once-weekly delivery formats through municipal health department tenders. For Investors and Strategic Acquirers: Re-rating potential sits with dual-incretin combination developers given GLP-1 receptor agonist pairing traction in specialist endocrinology segments. Long-term viability favors manufacturers with captive API supply and proven bioequivalence dossiers across multiple Latin American regulators. Monitor ANVISA procurement tender participation rates as inflection indicator for generic certification pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| Bioequivalence Certification Investment | ANVISA's tightened standards filter substandard entrants from Brazilian municipal pharmacy tenders. |
| Extended-Release Formulation Development | Once-weekly dosing captures Colombian and Chilean adherence-program formulary inclusion. |
| Dual-Incretin Combination Pipeline | Fixed-dose GLP-1 pairings open specialist endocrinology segments previously closed to oral therapy. |
| API Backward Integration | Captive sourcing from Indian and Chinese manufacturers mitigates freight cost volatility exposure. |
| Regional Wholesaler Consolidation | Argentina's ANMAT stability requirements favor distributors with inventory management across extended geography. |
Research Methodology
Regulatory filings, hospital procurement databases, and clinical trial registries formed the secondary backbone, supplemented by trade customs data and pharmaceutical import records. Primary interviews with formulary directors, regulatory affairs leads at ANVISA and COFEPRIS, hospital procurement managers, and payer access specialists validated segmentation assumptions. Bottom-up and top-down triangulation cross-checked prescription volume estimates against tender participation data.
Bottom-up modeling anchored patient population projections and treatment line progression rates, while top-down analysis calibrated against national essential medicine list expenditure patterns. Segmentation dimensions included molecular type, delivery mode, end-user institution class, and regional regulatory cluster. CAGRs derived from longitudinal tender award analysis and dispensing volume trajectories across the projection horizon. Forecast inputs incorporated bioequivalence approval timelines and SGLT2 inhibitor displacement rates in cardiology protocols.
The model assumes a particular technology adoption path for extended-release formulations; alternative pathways for once-weekly delivery systems would alter the outlook. Forecasts reflect assumptions regarding regulatory streamlining continuity and API supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
Kidney Cancer Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market