
 Human Immunodeficiency Virus Therapeutics Market | 2026-2036
Human Immunodeficiency Virus Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Human Immunodeficiency Virus Therapeutics Market Analytics
The capital-intensity divergence between large-cap integrators and mid-size innovators is unwinding traditional competitive boundaries. Gilead Sciences leverages its nucleoside reverse transcriptase inhibitor backbone to sustain manufacturing scale across oral and injectable formats. ViiV Healthcare anchors long-acting injectable development through dedicated HIV-focused R&D infrastructure. Bristol-Myers Squibb Company competes via its integrase inhibitor portfolio, positioning manufacturing flexibility as a counterweight to single-molecule dominance.
Human immunodeficiency virus therapeutics comprise pharmaceutical agents engineered to suppress viral replication, maintain CD4+ T-cell counts, and prevent progression to acquired immunodeficiency syndrome through sustained viral load reduction below detectable thresholds. These therapies functionally depend on multi-drug combination regimens targeting distinct stages of the retroviral life cycle, with potency measured in copies of RNA per milliliter of plasma. Antiretrovirals occupy the mature core of the market, where generic erosion compresses margins while originators pivot toward fixed-dose combinations. Long-acting injectable delivery modes represent the fastest-expanding structural pocket, as formulation science extends dosing intervals from daily tablets to monthly or quarterly administration. Hospitals retain concentrated procurement power for inpatient initiation protocols, though homecare channels capture follow-on maintenance volumes as oral regimens stabilize.
The FDA governs approval pathways through accelerated review mechanisms, while the EMA enforces centralized marketing authorization requirements that shape multi-jurisdictional launch sequencing. The WHO prequalification program and national regulatory authorities in India and South Africa determine market access for generic antiretroviral supply into public procurement channels. Stakeholders must monitor evolving payer evidence requirements for long-acting formulations versus daily oral standard-of-care, as formulary positioning will hinge on demonstrable adherence advantages and total cost-of-care models rather than clinical efficacy alone.
Market Dynamics
Long-acting injectable formulations are compressing dosing intervals from daily oral tablets to monthly or quarterly administration, forcing manufacturers to reconfigure manufacturing assets and supply chain logistics around cold-chain distribution networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated clinical trial timelines compress development cycles for novel antiretroviral classes, enabling faster patient access to suppressive regimens.
- 340B Program Expansion:US hospital systems and affiliated outpatient clinics capture redirected procurement volumes, concentrating demand through integrated delivery networks.
- Formulation Science Advances:Nanoparticle and prodrug technologies enable extended-release injectable platforms that improve adherence profiles in maintenance therapy populations.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for nucleoside reverse transcriptase inhibitors clusters in India and China, creating single-source vulnerability for generic formulations.
- Cold-Chain Infrastructure Requirements:Long-acting injectable stability demands temperature-controlled distribution networks that raise logistics costs and limit rural access.
- Generic Erosion Pressure:Patent expirations on first-line oral combination therapies compress originator margins and redirect R&D budgets toward differentiated delivery formats.
Strategic Opportunities
- Sub-Saharan Africa Access Expansion:WHO prequalification pathways and national procurement programs in South Africa and Kenya create volume opportunities for affordable fixed-dose combinations.
- Specialty Pharmacy Integration:Patient adherence programs through centralized dispensing models capture follow-on maintenance volumes outside hospital settings.
- Biomarker-Guided Personalization:Pharmacogenomic testing integration enables tailored regimen selection based on metabolic enzyme profiling and resistance mutation patterns.
Industry Challenges
- Formulation Scientist Scarcity:Extended-release injectable development requires rare expertise in polymer chemistry and controlled-release engineering that outpaces academic pipeline output.
- Multi-Jurisdictional Label Harmonization:Divergent EMA and FDA evidence requirements for long-acting formulations delay synchronized launch timelines and fragment commercialization strategy.
- Legacy Manufacturing Retooling:Oral solid-dose facilities require capital-intensive conversion to aseptic fill-finish capacity for injectable production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Immunodeficiency Virus Therapeutics Market |
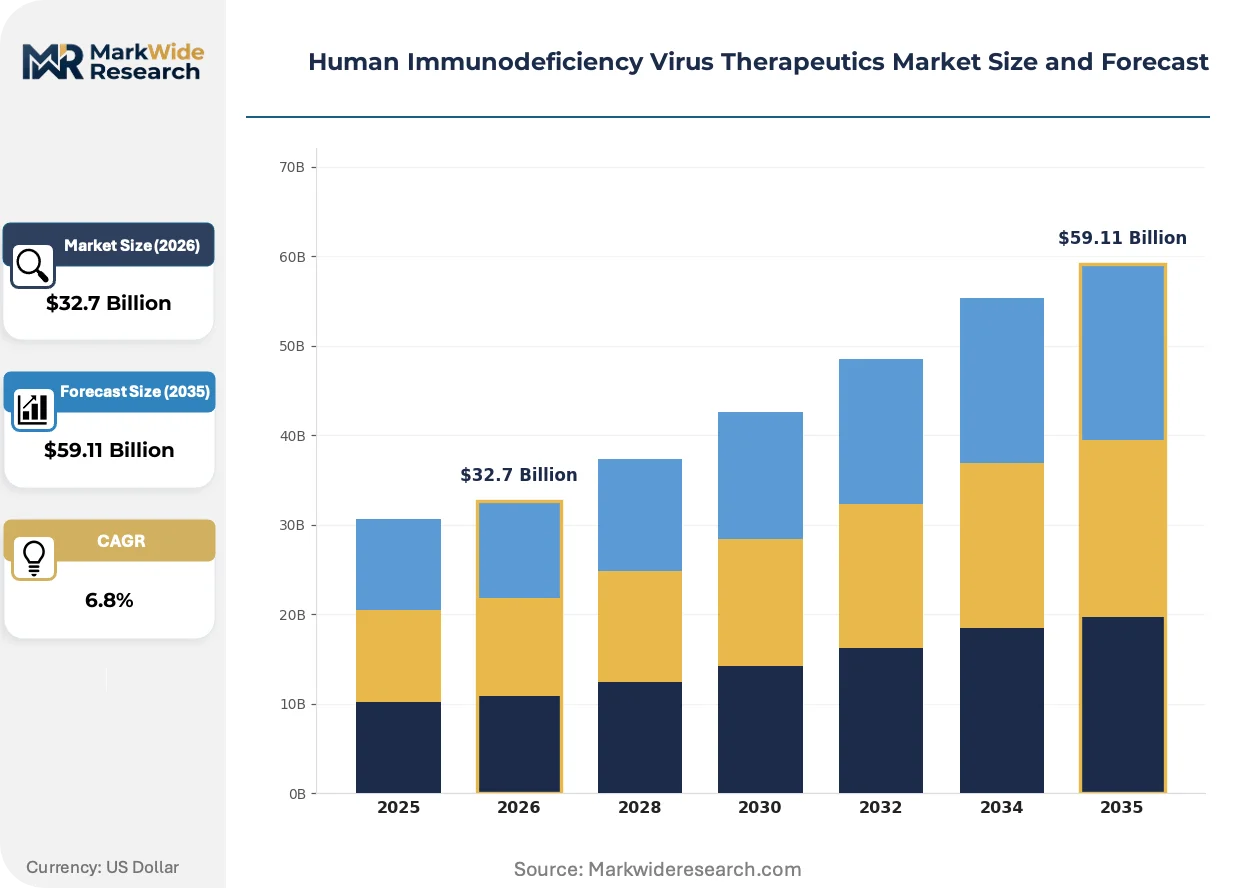
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretrovirals, Monoclonal Antibodies, Fusion Inhibitors, Integrase Inhibitors Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Homecare, Clinics, Specialty Pharmacies Application: Prophylaxis, Treatment, Management, Vaccination |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Bristol-Myers Squibb Company, Merck & Co., Inc., AbbVie, Johnson & Johnson, Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Immunodeficiency Virus Therapeutics Market Evolving Landscape
Formulation science and regulatory science are converging to redefine competitive advantage around adherence metrics rather than virologic endpoints alone, compressing traditional boundaries between pharmaceutical and device development.
Extended-release depot injectables are fragmenting the daily oral standard-of-care by enabling quarterly dosing intervals through crystallizable prodrug technology. HIV clinics and community health centers in the United States and Western Europe are adopting these platforms for stable patients seeking regimen simplification. This shift is fragmenting market share concentration among oral-dose specialists and rewarding manufacturers with integrated device-drug capabilities.
EMA's centralized marketing authorization requirements are reshaping multi-jurisdictional launch sequencing for novel antiretroviral classes. The agency's accelerated assessment pathways for products addressing unmet medical needs compress review timelines but demand comprehensive pediatric investigation plans upfront. Fixed-dose combination developers are responding by front-loading age-de-escalation studies to enable simultaneous adult and adolescent labeling.
Buyer consolidation among US payers and pharmacy benefit managers is compressing formulary access negotiations into centralized procurement events. Hospital systems leveraging 340B pricing advantages are displacing retail pharmacy channels for initial therapy initiation, particularly in Medicaid-heavy states. This concentration is most visible in California, Texas, and New York, where integrated delivery networks now control majority outpatient antiretroviral dispensing volume.
Human Immunodeficiency Virus Therapeutics Market Segmentation
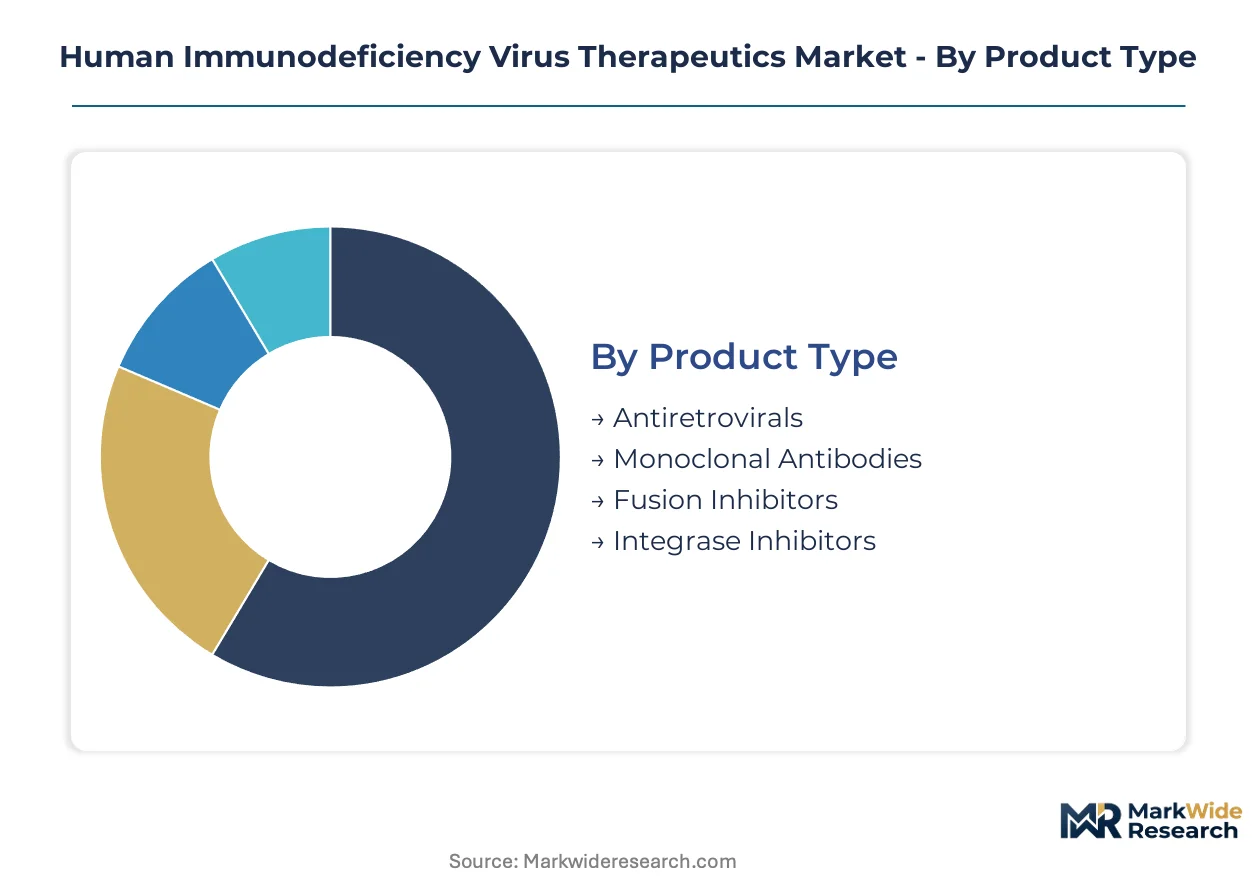
Segmentation in HIV therapeutics reveals divergent supply chain requirements across delivery modes and stark differences in procurement concentration between institutional and retail channels. Manufacturers configure production assets and distribution networks around these structural divides.
Product Type:
Antiretrovirals dominate domestic consumption in developed markets, while monoclonal antibodies and novel classes drive export-led growth into premium segments.
- Antiretrovirals:Multi-drug combination regimens targeting reverse transcriptase, protease, and integrase enzymes form the therapeutic backbone. Demand concentrates in public procurement channels across the United States, South Africa, and India, where national treatment programs prioritize first-line suppressive therapy.
- Monoclonal Antibodies:Engineered immunoglobulins targeting gp120 or CD4 receptor sites function as salvage therapy for multi-drug resistant populations. Export volumes track toward Western European hospital systems and US academic medical centers with specialized resistance testing capabilities.
- Fusion Inhibitors:Peptide-based entry blockers disrupt viral envelope fusion with host cell membranes. Niche positioning in salvage regimens limits production scale.
- Integrase Inhibitors:Small-molecule strand transfer inhibitors achieve rapid viral suppression with favorable resistance profiles. Fixed-dose combination demand drives formulation complexity.
Antiretrovirals hold the largest share; momentum sits with monoclonal antibodies.
Delivery Mode:
Cost tier stratification separates high-complexity biologic manufacturing from commoditized oral solid-dose production.
- Oral:Daily tablet and capsule formulations of nucleoside reverse transcriptase inhibitors and integrase inhibitors constitute the standard-of-care. Volume concentrates in generic substitution markets where Indian and Chinese API suppliers feed formulation facilities serving Africa and Southeast Asia.
- Injectable:Long-acting depot formulations of cabotegravir and rilpivirine extend dosing intervals to monthly or quarterly intervals. Cold-chain distribution requirements limit initial rollout to US and Western European urban centers with specialized pharmacy infrastructure.
- Transdermal:Patch-based delivery systems remain investigational, with clinical trials evaluating adherence advantages in unstable housing populations.
- Intravenous:Infusion-based monoclonal antibody administration occurs exclusively in hospital outpatient settings, concentrating procurement through 340B-eligible systems.
Oral formulations capture the volume base; injectable platforms are climbing the fastest.
End User:
Customer type fragmentation is accelerating as integrated delivery networks disperse procurement across inpatient, outpatient, and home-based care settings.
- Hospitals:Inpatient initiation protocols and outpatient infusion centers anchor procurement for complex cases and long-acting injectable administration. US hospital systems leveraging 340B pricing capture dominant share in Medicaid-heavy states.
- Homecare:Mail-order and visiting nurse services manage stable patients on oral maintenance regimens, with specialty pharmacy networks handling prior authorization and adherence monitoring.
- Clinics:Community health centers and Ryan White-funded sites serve uninsured and underinsured populations through federal procurement programs.
- Specialty Pharmacies:Centralized dispensing models with dedicated HIV clinical pharmacists manage prior authorization complexity and co-pay assistance programs.
Hospitals retain the largest share; specialty pharmacies are gaining share fastest.
Application:
Maturity gradients separate established treatment paradigms from pre-exposure prophylaxis expansion and still-elusive vaccine development.
- Treatment:Sustained viral suppression through combination antiretroviral therapy represents the mature revenue core, with procurement concentrated through national programs and commercial insurance formularies.
- Prophylaxis:Pre-exposure prophylaxis with tenofovir-based regimens and long-acting cabotegravir is expanding into high-incidence urban corridors and serodiscordant couple counseling programs.
- Management:Resistance testing, therapeutic drug monitoring, and adherence support services wrap around pharmaceutical procurement.
- Vaccination:Prophylactic immunization remains in clinical development, with no approved products generating commercial revenue.
Treatment commands the largest share; prophylaxis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement channels. Medicaid-dependent populations in the United States absorb minimal out-of-pocket costs, while uninsured segments in India and Nigeria face full generic substitution pressure. Western European systems with centralized tendering sit between these extremes.
United States
Hospital systems and affiliated outpatient clinics capture dominant procurement volumes through 340B program expansion. FDA breakthrough therapy designations compress clinical trial timelines for novel antiretroviral classes. California, Texas, and New York concentrate dispensing through integrated delivery networks that control majority outpatient volume.
South Africa
National treatment programs prioritize first-line suppressive therapy for the world's largest antiretroviral patient population. The country's national pharmaceutical regulator enforces WHO prequalification alignment for public procurement channels. Johannesburg and Cape Town anchor formulation manufacturing and distribution infrastructure serving the Southern African Development Community.
India
Active pharmaceutical ingredient manufacturing for nucleoside reverse transcriptase inhibitors clusters in Hyderabad and Ahmedabad, creating supply concentration for generic formulations. The Central Drugs Standard Control Organization governs export licensing for prequalified antiretroviral supply into African procurement programs. Domestic demand concentrates through the National AIDS Control Organization's free distribution scheme.
Germany
EMA centralized marketing authorization requirements shape multi-jurisdictional launch sequencing for long-acting injectable platforms. Statutory health insurance funds negotiate reimbursement through the Federal Joint Committee's benefit assessment process. Berlin and Munich host specialized resistance testing capabilities that anchor salvage therapy demand for monoclonal antibodies.
Brazil
ANVISA governs marketing authorization for fixed-dose combinations distributed through the Unified Health System's universal access program. São Paulo and Rio de Janeiro concentrate clinical trial sites evaluating extended-release depot formulations. Federal procurement auctions drive price compression for first-line oral regimens while preserving originator access for treatment-experienced populations.
Human Immunodeficiency Virus Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across delivery-mode competencies. Large-cap pharmaceutical companies with nucleoside reverse transcriptase inhibitor backbones leverage manufacturing scale across oral and injectable formats. Mid-size innovators anchor long-acting injectable development through dedicated HIV-focused research infrastructure. Competitive moves concentrate on formulation science partnerships and aseptic fill-finish capacity expansion.
Within the integrated leader tier, Gilead Sciences and ViiV Healthcare exemplify divergent strategic postures around single-molecule dominance versus delivery-format differentiation. Bristol-Myers Squibb Company occupies a position within the integrase inhibitor specialist segment, representing manufacturing flexibility as a counterweight to backbone-dependent competitors. These three entities collectively illustrate how capital-intensity divergence unwinds traditional competitive boundaries across the therapeutic landscape.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| AbbVie |
| Johnson & Johnson |
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche |
| Cipla |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Indian and Chinese API manufacturing clusters shapes both supply concentration and originator price floors for nucleoside reverse transcriptase inhibitors. Generic substitution pressure from these scale centers compresses margins on oral solid-dose formulations while forcing originators toward differentiated delivery formats with higher price persistence.
Pricing Analysis
Adherence support services and patient assistance programs drive lifetime value capture beyond unit drug sales. Three-tier pricing structure across premium originator, authorized generic, and commodity generic levels segments buyer archetypes. Cost compression in first-line oral regimens intensifies because of patent cliff acceleration and 340B program expansion. Uninsured populations in Medicaid-heavy states exhibit highest price sensitivity; integrated delivery networks with 340B eligibility demonstrate lowest sensitivity due to federal pricing advantages.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for nucleoside reverse transcriptase inhibitors and protease inhibitors. Hyderabad and Ahmedabad clusters feed formulation facilities with key starting materials and advanced intermediates. Single-source vulnerability for long-acting injectable cold-chain distribution creates structural risk for rural access expansion. Distribution runs through hospital-system consolidated procurement for initiation protocols, with specialty pharmacy networks capturing maintenance volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting injectable substitution threatens oral-dose incumbents with regimen simplification advantages that could displace daily tablet maintenance populations. Incumbents must navigate this delivery-format transition while defending against generic erosion in commoditized antiretroviral classes.
For Market Incumbents: Fortify formulation science capabilities through polymer chemistry partnerships and controlled-release engineering investments. Backward integration into aseptic fill-finish capacity reduces reliance on contract manufacturing organizations for injectable platform launches. Patent extension strategies through fixed-dose combination modifications defend against immediate generic entry on core oral backbones. For New Entrants and Emerging Players: FDA Breakthrough Therapy Designation fast-track offers accelerated pathway entry for novel antiretroviral classes with differentiated resistance profiles. Sub-Saharan Africa public procurement channels present most penetrable geography for affordable fixed-dose combination supply. WHO prequalification alignment enables volume scaling through national treatment program tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform specialists with integrated device-drug capabilities over single-molecule originators. Long-acting injectable infrastructure ownership provides 5-10 year defensive moat as dosing interval extension becomes standard-of-care. Inflection indicator: EMA-FDA label harmonization velocity for extended-release depot formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA Breakthrough Therapy Designation compresses development timelines for novel antiretroviral classes. |
| Manufacturing Scale-Up | Aseptic fill-finish capacity expansion enables long-acting injectable production at commercial volumes. |
| Regulatory Approval Pathway | WHO prequalification alignment unlocks public procurement access across Sub-Saharan Africa. |
| Pipeline Diversification | Extended-release depot platforms reduce dependence on daily oral regimen revenue concentration. |
| Strategic Partnership | Specialty pharmacy integration captures adherence program revenue outside hospital settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical expenditure analysis were triangulated to reconcile volume and value estimates.
Across the analysis window, the forecasting framework modeled treatment line progression, dosage form evolution, administration route substitution, and regional regulatory cluster differentiation. CAGRs were derived from segment-level growth trajectory aggregation and cross-referenced with historical approval-to-peak sales patterns. Resistance mutation prevalence and long-acting formulation uptake curves served as HIV-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained viral suppression targets and stable payer reimbursement frameworks; material deviation in 340B program scope or generic entry timing would warrant model refresh. Recalibration cycles align with material shifts in FDA breakthrough designation velocity and WHO prequalification queue progression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Global Sterile Injectable Drugs Market