
 Global Small Molecule Sterile Injectable Drugs Market | 2026-2036
Global Small Molecule Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Molecule Sterile Injectable Drugs Market Foresight
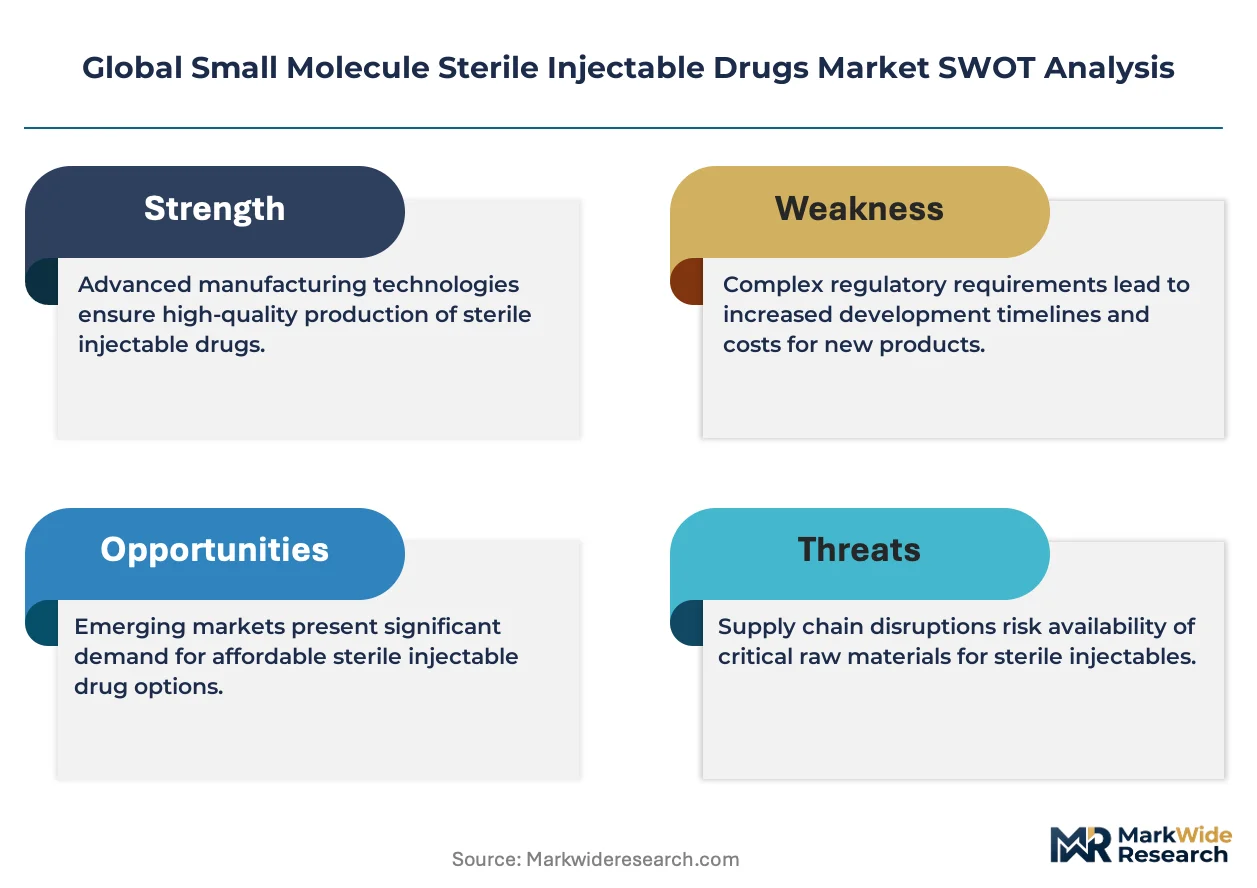
EU MDR is consolidating the cost-of-entry calculus for sterile injectable manufacturers, forcing smaller participants toward contract development or exit. Pfizer Inc. leverages its integrated sterile manufacturing network across multiple continents to sustain supply security for hospital systems. Novartis AG anchors its position through deep specialization in oncology injectables, while Merck & Co., Inc. competes via rigorous cold-chain logistics and aseptic fill-finish capabilities.
Small molecule sterile injectable drugs are chemically synthesized, low-molecular-weight therapeutics formulated in pyrogen-free aqueous or lyophilized preparations for parenteral administration, requiring terminal sterilization or aseptic processing under ISO 5 conditions to prevent microbial contamination. These products deliver rapid bioavailability and precise dosing for acute and critical-care interventions where oral administration is contraindicated. Oncology and antibiotics represent the dominant product type segments, with oncology commanding premium pricing due to narrow therapeutic indices and complex handling requirements. Intravenous delivery mode leads volume throughput in hospitals, though subcutaneous formulations are gaining traction in specialty clinics seeking reduced administration costs and patient throughput efficiency.
FDA, EMA, and WHO standards collectively govern sterile injectable quality, with each body enforcing escalating requirements for endotoxin limits, particulate matter, and container-closure integrity that directly shape facility capital expenditure and batch release timelines. The EU AI Act introduces emerging compliance dimensions for automated visual inspection systems used in final product release. Stakeholders must monitor regulatory divergence between FDA's Quality Management Maturity program and EMA's intensified GMP inspection cadence when prioritizing capacity allocation and partnership strategies.
Market Dynamics
The EU MDR's tightened sterile manufacturing requirements are compressing the supplier base and elevating capital barriers, forcing manufacturers toward consolidated production networks or contract manufacturing partnerships to maintain hospital supply contracts.
Growth Catalysts
- Oncology Hospital Demand:Chronic disease burdens in tertiary care centers are intensifying consumption of narrow-therapeutic-index injectables requiring complex handling protocols.
- EMA GMP Inspection Intensification:Stricter enforcement cadence is filtering out subscale manufacturers and concentrating volume among qualified suppliers with validated aseptic fill-finish lines.
- Subcutaneous Formulation Migration:Specialty clinics are adopting subcutaneous delivery to reduce administration costs and improve patient throughput efficiency.
Market Restraints
- API Supply Concentration:Reliance on concentrated active pharmaceutical ingredient sourcing from specific Asian manufacturing clusters creates vulnerability to geopolitical disruption and quality events.
- Terminal Sterilization Limitations:Heat-sensitive small molecules cannot undergo terminal sterilization, forcing costlier aseptic processing under ISO 5 conditions with higher contamination risk.
- Endotoxin Testing Burden:FDA and EMA escalation of endotoxin limit enforcement extends batch release timelines and elevates quality control expenditure.
Strategic Opportunities
- India CDMO Expansion:Underpenetrated sterile injectable capacity in Indian contract development and manufacturing organizations offers cost-competitive alternatives for Western sponsors seeking supply diversification.
- Cold-Chain Automation Convergence:Integration of IoT temperature monitoring with automated visual inspection systems creates differentiation in high-value oncology logistics.
- Japan Specialty Clinic Channel:Regulatory pathways under PMDA are enabling direct distribution to ambulatory oncology centers bypassing traditional hospital pharmacy intermediaries.
Industry Challenges
- Aseptic Processing Skill Scarcity:Qualified personnel for isolator technology and barrier systems remain concentrated among legacy sterile manufacturers, constraining capacity expansion timelines.
- EU AI Act Compliance Friction:Automated visual inspection systems now face emerging validation requirements under the EU AI Act, complicating equipment procurement and software upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Molecule Sterile Injectable Drugs Market |
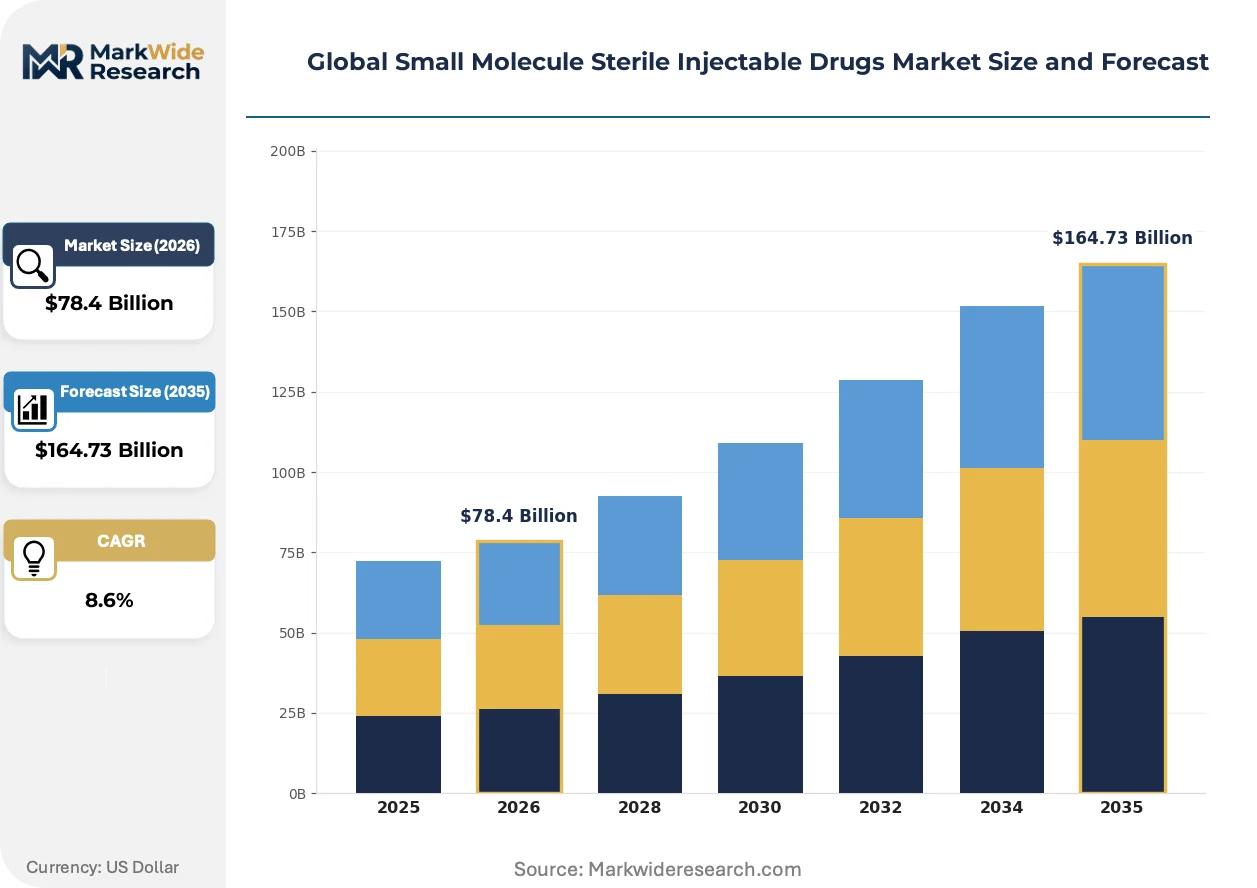
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Anti-inflammatory, Cardiovascular, Oncology, Neurology Therapy Area: Infectious Diseases, Pain Management, Autoimmune Disorders, Cardiovascular Diseases, Cancer Care, Neurological Disorders End User: Hospitals, Specialty Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Pharmacies, Research Institutions Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-articular, Intradermal, Epidural |
| Companies Covered | Novartis AG, Pfizer Inc., Merck & Co., Inc., AstraZeneca Plc, Johnson & Johnson, Sanofi S.A., Amgen Inc., Gilead Sciences Inc., GlaxoSmithKline Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Molecule Sterile Injectable Drugs Market Shifts & Advancements
Continuous manufacturing technologies are displacing batch processing in sterile injectable production, while regulatory convergence around data integrity and automated inspection is reshaping facility design standards across FDA, EMA, and PMDA jurisdictions.
Isolator-based aseptic processing is unifying filling operations with real-time environmental monitoring, eliminating human intervention in critical zones. Hospital systems and large CDMOs in Germany and the United States are retrofitting legacy cleanrooms with closed isolator technology at accelerated capital deployment cycles. This unifying architecture is compressing contamination risk profiles while extending equipment validation timelines and elevating technical service requirements.
The EU AI Act's risk-classification framework for automated decision systems is imposing new validation protocols on machine-learning visual inspection platforms used in final product release. Manufacturers deploying AI-driven defect detection must now document algorithmic transparency and performance drift monitoring, extending software qualification periods. Oncology injectables with high visual complexity are experiencing the most significant compliance adaptation costs as firms revalidate legacy inspection systems.
Hospital procurement departments are consolidating supplier relationships through single-source contracts for high-volume oncology and antibiotic injectables, displacing fragmented multi-vendor purchasing. This concentration is compressing price negotiation cycles and elevating service-level requirements for supply security and cold-chain documentation. The United States and Japanese hospital systems are most advanced in this consolidation, with European facilities following under centralized tendering frameworks.
Global Small Molecule Sterile Injectable Drugs Market Segmentation
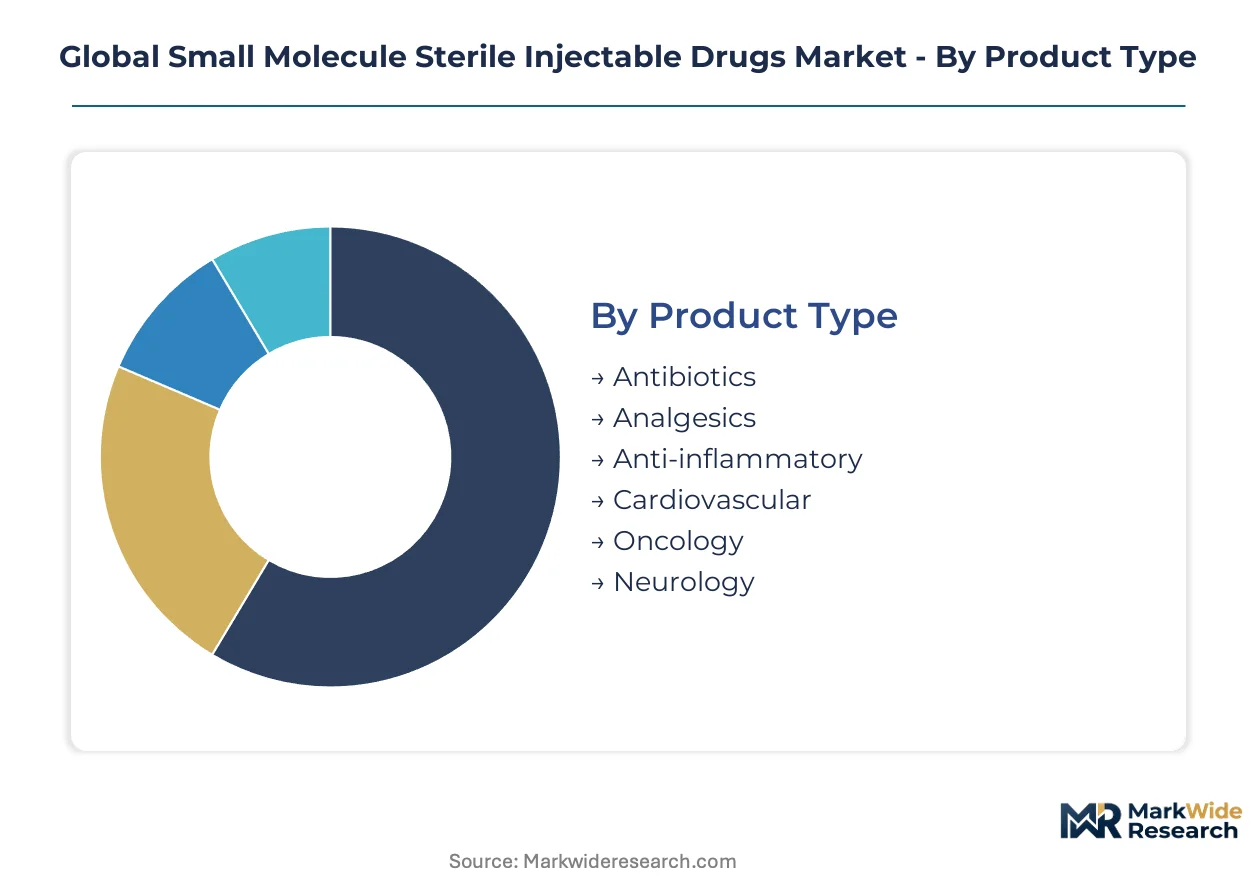
Segmentation in sterile injectables reveals how formulation complexity, regulatory burden, and site-of-care economics fragment purchasing authority across hospital systems, specialty clinics, and contract manufacturers. Understanding these divides exposes where pricing power concentrates and where commoditization pressures mount.
Product Type:
Buyers in this category separate by therapeutic risk tolerance and handling infrastructure — oncology commands premium procurement budgets while antibiotics face tender-driven compression.
- Oncology:Narrow-therapeutic-index cytotoxics and supportive care agents demand cold-chain integrity, complex admixture protocols, and specialized waste disposal. Demand clusters in United States and German tertiary centers where CAR-T co-administration protocols intensify injectable consumption.
- Antibiotics:High-volume beta-lactams and glycopeptides for sepsis and resistant infections require rapid batch release but face formulary substitution pressure. Tender frameworks in European hospital systems compress margins while India and Brazil expand volume through national health programs.
- Analgesics:Post-operative opioid and non-opioid injectables serve ambulatory surgery recovery protocols with shorter shelf-life requirements.
- Anti-inflammatory:Corticosteroid and NSAID formulations target acute flare management in rheumatology and emergency departments.
- Cardiovascular:Anticoagulants and antiarrhythmics for catheterization labs and stroke units require precise unit-dose packaging.
- Neurology:Antiepileptic and acute migraine therapies concentrate in level-one trauma centers with neurocritical care capabilities.
Volume sits with antibiotics; growth tilts toward oncology.
Therapy Area:
Maturity gradients distinguish this category — infectious disease protocols are standardized while cancer care injectables evolve with immuno-oncology combination regimens.
- Cancer Care:Chemotherapy, immunotherapy, and supportive injectables require biosafety level handling and patient-specific dosing. United States comprehensive cancer centers and Japan's designated cancer hospitals anchor demand as combination protocols expand treatment cycles.
- Infectious Diseases:Sepsis, pneumonia, and resistant pathogen therapies prioritize broad-spectrum coverage and rapid formulary access. Hospital procurement in Germany and France drives volume through centralized antibiotic stewardship programs.
- Pain Management:Perioperative and chronic pain protocols in ambulatory settings favor short-acting formulations with rapid onset.
- Autoimmune Disorders:Biologic adjuncts and corticosteroid pulses serve rheumatology and dermatology infusion centers.
- Cardiovascular Diseases:Acute coronary syndrome and stroke protocols in catheterization labs require immediate availability of thrombolytics and antiarrhythmics.
- Neurological Disorders:Status epilepticus and acute migraine therapies concentrate in neurocritical care units with continuous monitoring capabilities.
Standardized protocols dominate infectious diseases; steepest expansion trajectory runs through cancer care combination regimens.
End User:
Capital intensity and reimbursement models fragment this category — hospitals absorb total cost of ownership while specialty clinics optimize for throughput efficiency.
- Hospitals:Tertiary centers with 24-hour pharmacy operations and aseptic compounding facilities manage the full spectrum of sterile injectables. United States academic medical centers and Japan's national hospital organizations concentrate high-complexity oncology and antibiotic demand.
- Specialty Clinics:Ambulatory oncology and infusion centers prioritize subcutaneous formulations and same-day discharge protocols. German onco-hematology networks and United States community oncology practices are expanding subcutaneous migration to reduce chair time.
- Diagnostic Centers:Contrast media and pre-procedure medications for imaging suites require limited storage but rapid turnaround.
- Ambulatory Surgical Centers:Short-acting anesthetics and post-operative analgesics favor prefilled syringes and ready-to-administer formats.
- Pharmacies:Retail and home infusion services manage patient-directed injectable therapies with cold-chain delivery requirements.
- Research Institutions:Investigational sterile formulations for clinical trials demand flexible batch sizes and expedited release testing.
Procurement scale favors hospitals; site-of-care shift gains share fastest in specialty clinics.
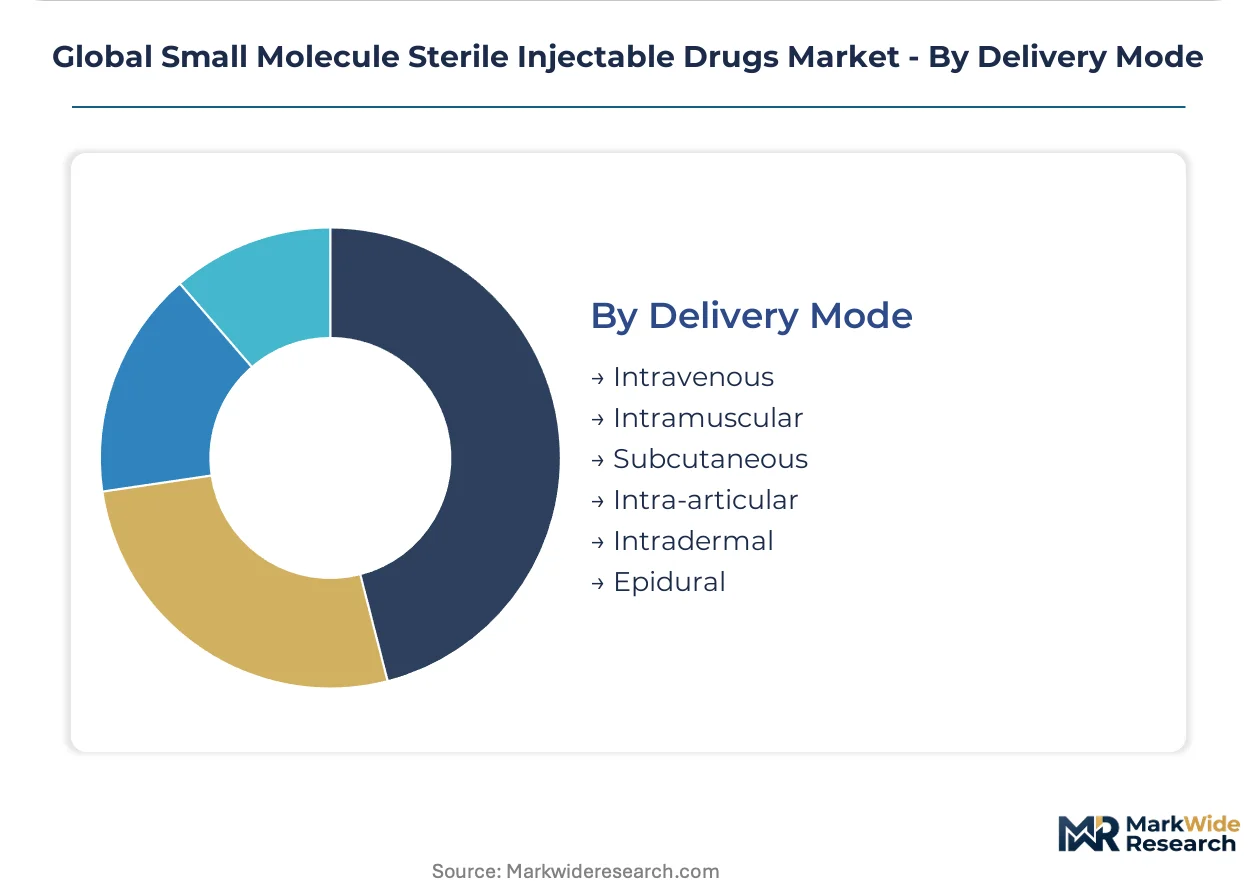
Delivery Mode:
Administration economics and patient convenience preferences are restructuring this category — intravenous retains acute care dominance while subcutaneous captures migration to lower-cost settings.
- Intravenous:Direct vascular access enables rapid bioavailability for critical-care and high-volume fluid replacement. United States and German hospital systems anchor demand through centralized infusion centers and emergency department protocols.
- Subcutaneous:Depot formulations and patient-administered therapies reduce facility dependency and nursing labor. Japanese specialty clinics and United States home infusion providers are expanding subcutaneous oncology and autoimmune protocols.
- Intramuscular:Vaccines and long-acting antipsychotics serve public health programs and mental health facilities with depot administration requirements.
- Intra-articular:Corticosteroid and hyaluronic acid injections target orthopedic and rheumatology practices with procedure-room administration.
- Intradermal:Tuberculosis testing and allergy immunotherapy concentrate in public health and allergy specialty settings.
- Epidural:Anesthesia and pain management protocols in obstetric and surgical units require specialized pharmacy compounding and neuraxial delivery expertise.
Throughput volume concentrates in intravenous; administration cost reduction drives subcutaneous expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Andhra Pradesh are attracting sterile injectable manufacturing through tax holidays and accelerated environmental clearances. India's Pharmaceutical Park schemes in Telangana and the dedicated medical device zones near Hyderabad concentrate new aseptic fill-finish capacity.
United States
Academic medical centers in Boston and Houston drive consumption of narrow-therapeutic-index oncology injectables requiring complex handling protocols. FDA's Quality Management Maturity program rewards manufacturers with expedited facility inspections. The Research Triangle Park corridor in North Carolina anchors contract manufacturing expansion for hospital system supply security.
Germany
Centralized antibiotic stewardship programs in Berlin and Munich hospital networks prioritize qualified suppliers with validated aseptic lines. EMA's intensified GMP inspection cadence filters out subscale manufacturers. The Rhine-Main biotech cluster near Frankfurt concentrates isolator technology retrofitting for legacy cleanroom facilities.
Japan
Designated cancer hospitals in Tokyo and Osaka anchor demand for combination regimen injectables as immuno-oncology protocols expand. PMDA regulatory pathways enable direct distribution to ambulatory oncology centers bypassing traditional pharmacy intermediaries. The Kansai medical technology corridor accelerates subcutaneous formulation migration to specialty clinics.
India
National health program expansion in Maharashtra and Tamil Nadu drives volume for high-volume beta-lactam antibiotics through tender frameworks. CDSCO's alignment with WHO prequalification standards accelerates export-oriented sterile capacity. The Hyderabad-Visakhapatnam pharmaceutical belt attracts Western sponsors seeking cost-competitive contract manufacturing alternatives.
Switzerland
Specialty pharmaceutical headquarters clustering in Basel shapes premium-tier oncology injectable development. Swissmedic maintains rigorous batch release timelines that elevate quality control expenditure across the Alpine manufacturing corridor. The Zürich-Schaffhausen logistics hub concentrates cold-chain automation for high-value European distribution.
Global Small Molecule Sterile Injectable Drugs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated production networks dominate hospital supply contracts while mid-scale participants face exit pressure under tightened EU MDR compliance costs. Three archetypes define competitive positioning: integrated pharmaceutical majors with captive sterile manufacturing, oncology-focused specialists with deep therapeutic expertise, and contract development organizations offering supply diversification. Capacity expansion through isolator technology retrofitting and strategic partnerships for cold-chain automation represent the dominant competitive moves.
Among Swiss- and German-based pharmaceutical majors, Novartis AG and Merck & Co., Inc. exemplify the oncology-specialist archetype through deep therapeutic concentration. Pfizer Inc. occupies a position representing the integrated conglomerate model with multi-continental manufacturing networks. These three entities anchor the qualified supplier tier that EMA's intensified inspection cadence favors.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| AstraZeneca Plc |
| Johnson & Johnson |
| Sanofi S.A. |
| Amgen Inc. |
| Gilead Sciences Inc. |
| GlaxoSmithKline Plc |
| Others |
Supply & Pricing Matrix
EU MDR compliance certification gates both qualified sterile manufacturing capacity and premium-tier pricing access for oncology injectables, compressing supplier margins for unqualified participants while rewarding validated aseptic fill-finish operators with contract security. Hospital procurement consolidation in the United States and Germany amplifies this bifurcation as formulary directors demand cold-chain documentation and ISO 5 processing guarantees that only capital-intensive facilities can deliver.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency replenishment premiums from scheduled contract volumes, with United States academic medical centers paying surcharges for same-day oncology injectable availability while European tender frameworks capture lower spot pricing through consolidated annual offtake. Three-tier pricing structure across premium, standard, and economy levels reflects GMP inspection history, isolator technology deployment, and cold-chain automation depth. Cost compression in antibiotic segments intensifies as Indian national health programs drive tender participation. Specialty clinics demonstrate lowest price sensitivity for subcutaneous oncology formulations with reduced chair-time economics.
Supply Chain Analysis
Freight cost escalation for temperature-controlled pharmaceutical logistics is reshaping regional sourcing strategies as manufacturers weigh European distribution hub proximity against Indian contract manufacturing economics. Active pharmaceutical ingredient concentration in China and India draws from fermentation-based beta-lactam capacity and synthetic oncology intermediate clusters. Single-source vulnerability concentrates in heat-labile molecules requiring aseptic rather than terminal sterilization. Distribution runs through hospital system consolidated service organizations in the United States and centralized pharmacy cooperatives in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into active pharmaceutical ingredient supply and captive aseptic fill-finish capacity defines the vertical-integration race in sterile injectables, with EMA inspection qualification serving as the critical gating credential for hospital contract access.
For Market Incumbents: Cement isolator technology retrofitting across legacy cleanroom facilities in the Rhine-Main and Research Triangle Park corridors to defend against CDMO price competition. Prioritize EU MDR technical documentation completion ahead of notified body backlog peaks. Lock in multi-year oncology supply agreements with United States academic medical centers before formulary consolidation accelerates.
For New Entrants and Emerging Players: Enter via underpenetrated subcutaneous formulation development for ambulatory oncology centers in Japan's Kansai corridor, where PMDA pathways enable direct specialty clinic distribution. Target antibiotic tender participation in Maharashtra and Tamil Nadu national health program expansion. Lead with cost-competitive aseptic capacity certified to WHO prequalification standards for Western sponsor supply diversification.
For Investors and Strategic Acquirers: FDA Quality Management Maturity program enrollment acceleration is the leading indicator that mid-scale manufacturers face compliance-driven exit pressure and consolidation opportunity. Position acquisition screening around isolator-equipped facilities with validated oncology lines across a five-to-ten year supply security horizon. Watch for EMA GMP inspection failure announcements as inflection signals for distressed capacity availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofitting | Closed-barrier aseptic processing eliminates human intervention, satisfying EMA's intensified GMP inspection protocols. |
| Cold-Chain Automation Integration | IoT temperature monitoring with AI-driven visual inspection differentiates oncology logistics for hospital system contracts. |
| Subcutaneous Formulation Migration | Reduced administration costs capture specialty clinic volume in Germany's onco-hematology networks. |
| Indian CDMO Capacity Expansion | Hyderabad-Visakhapatnam pharmaceutical belt offers Western sponsors cost-competitive supply diversification alternatives. |
| EU MDR Technical Documentation | Notified body certification gates premium-tier pricing access and hospital procurement eligibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with aseptic fill-finish operations directors, hospital formulary managers, regulatory affairs leads at sterile manufacturing facilities, and CDMO business development executives. FDA 483 observation databases, EMA inspection outcome reports, ClinicalTrials.gov protocol registries, and WHO prequalification listings supplied validation benchmarks. Bottom-up capacity modeling and top-down therapeutic demand estimation triangulated volume and value outputs.
Data-stream reconciliation across hospital procurement databases, GPO contract repositories, and national health program tender awards shaped the analytical framework. Segmentation dimensions spanned product type, therapy area, end user, and delivery mode, with regional regulatory cluster differentiation across FDA, EMA, PMDA, and CDSCO jurisdictions. CAGRs derived from compound growth trajectory analysis against baseline capacity utilization and demand elasticity parameters. Aseptic processing batch release timelines and endotoxin testing burden escalation served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical API supply disruption or accelerated EU AI Act enforcement on automated visual inspection systems. Forecasts reflect documented assumptions regarding regulatory inspection cadence, hospital procurement consolidation velocity, and subcutaneous formulation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Parathyroid Hormone Market