
 Minocycline Hydrochloride Market | 2026-2036
Minocycline Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Minocycline Hydrochloride Market Analysis
Market Context
REACH compliance for active pharmaceutical ingredient purity is expanding the cost-of-entry calculus for European minocycline suppliers. Tecoland Corporation leverages captive synthesis capabilities to sustain margin resilience against rising certification burdens. Hovione anchors its position through specialized tetracycline fermentation expertise. Sun Pharmaceutical Industries competes on geographic scale across emerging and developed markets.
Technical Definition and Segment Structure
Minocycline hydrochloride is a semi-synthetic tetracycline antibiotic with a dimethylamino group at the C7 position, conferring enhanced lipophilicity and tissue penetration compared to earlier tetracyclines; it functions primarily as a bacteriostatic agent inhibiting the 30S ribosomal subunit across gram-positive, gram-negative, and atypical pathogens. The injectable formulation segment leads in hospital revenue per unit, while topical delivery channels are gaining traction in dermatology clinics seeking localized acne therapy with reduced systemic antibiotic exposure. Tablet and capsule formats remain the mature volume base in retail pharmacy, though margin pools are shifting toward specialty distribution for resistant bacterial indications.
Regulatory Frame and Outlook
FDA bioequivalence standards, EMA impurity profiling guidelines, and India's CDSCO manufacturing facility inspections collectively shape product standards and market access timelines for minocycline hydrochloride producers. These frameworks elevate documentation and validation costs, particularly for generic entrants targeting regulated markets. Stakeholders must monitor evolving antimicrobial stewardship protocols and their downstream impact on prescription duration limits and formulary tiering.
Market Dynamics
FDA bioequivalence requirements for generic tetracyclines are compressing formulation margins while antimicrobial stewardship protocols in US hospital systems are shortening prescription durations. These dual pressures are forcing manufacturers toward specialized delivery formats and resistant-indication positioning.
Growth Catalysts
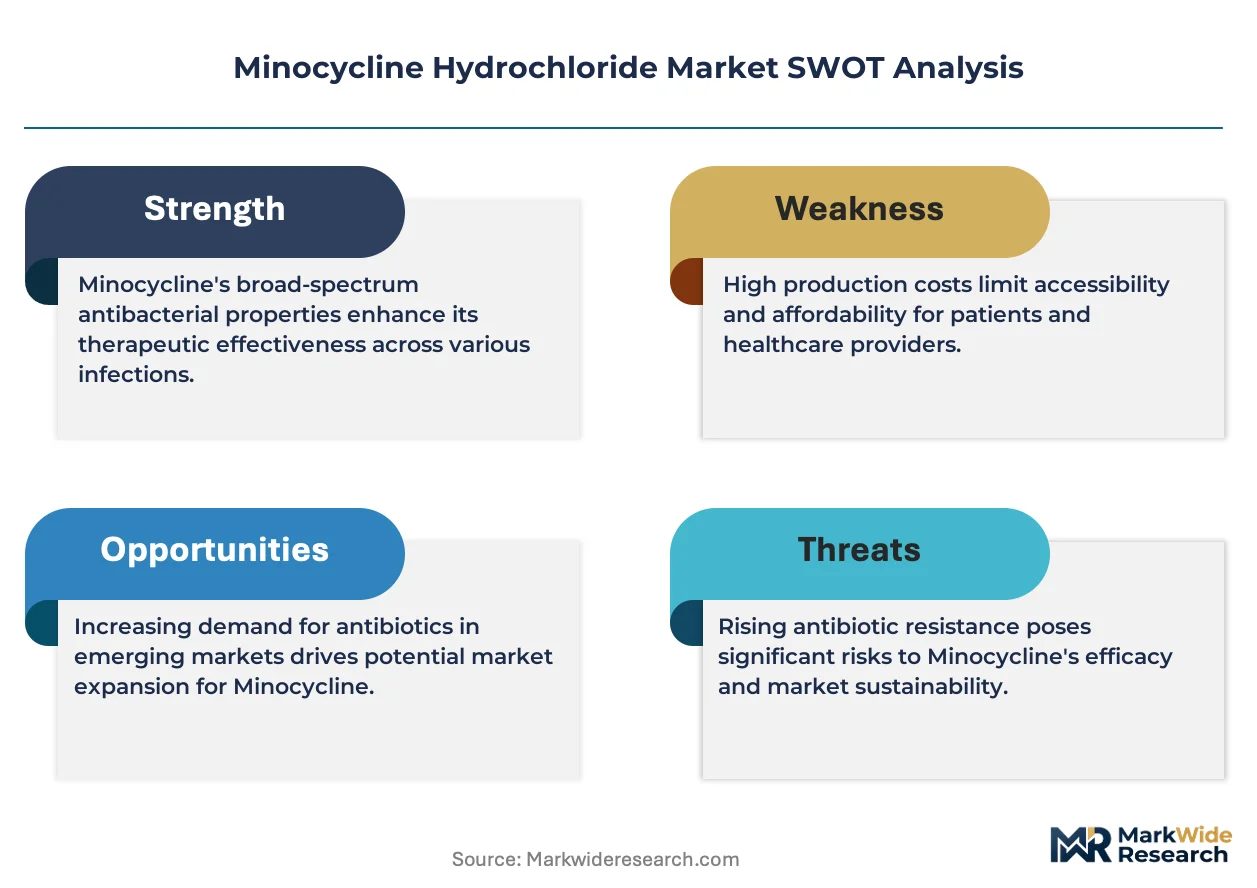
- MRSA Skin Infection Protocols:US hospital infectious disease wards are embedding oral minocycline into outpatient parenteral antimicrobial therapy pathways, expanding the addressable patient base beyond traditional acne demographics.
- REACH Compliance Expansion:ECHA impurity profiling mandates for active pharmaceutical ingredients are raising purity standards that favor established European suppliers with captive synthesis capabilities over opportunistic entrants.
- Topical Delivery Innovation:Dermatology clinics are adopting foam and gel formulations that enable localized acne therapy with reduced systemic antibiotic exposure, creating new prescription volume in aesthetic medicine channels.
Market Restraints
- Tetracycline Raw Material Concentration:Fermentation-derived starting materials concentrate among Chinese and Indian API suppliers, exposing finished dose manufacturers to geopolitical trade friction and customs inspection delays.
- Generic Substitution Pressure:FDA therapeutic equivalence ratings for immediate-release minocycline tablets enable automatic pharmacy-level substitution, collapsing brand premium capture in retail channels.
- Antimicrobial Resistance Surveillance:CDC and ECDC pathogen tracking networks are documenting declining minocycline susceptibility in community-acquired MRSA, threatening empirical use protocols in emergency departments.
Strategic Opportunities
- Extended-Release Formulation Gaps:Solodyn patent expiry has created white space for differentiated pharmacokinetic profiles targeting adolescent compliance through once-daily dosing in US pediatric dermatology.
- CDSCO Manufacturing Incentives:India's production-linked incentive scheme for active pharmaceutical ingredients is attracting fermentation capacity investment that could rebalance supply concentration away from legacy coastal clusters.
- Companion Diagnostic Pairing:Pharmacogenomic screening for CYP2C19 metabolizer status is enabling personalized minocycline dosing in refractory rosacea, opening specialty pharmacy channels with higher reimbursement tiers.
Industry Challenges
- Fermentation Expertise Attrition:Tetracycline biosynthesis requires specialized strain engineering and downstream purification skills that are aging out of the workforce at European and North American contract manufacturers.
- Bioequivalence Study Complexity:FDA requirements for fed-state pharmacokinetic comparisons in tetracycline generics demand larger clinical trial cohorts and extended sampling windows, stretching R&D timelines for abbreviated new drug applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minocycline Hydrochloride Market |
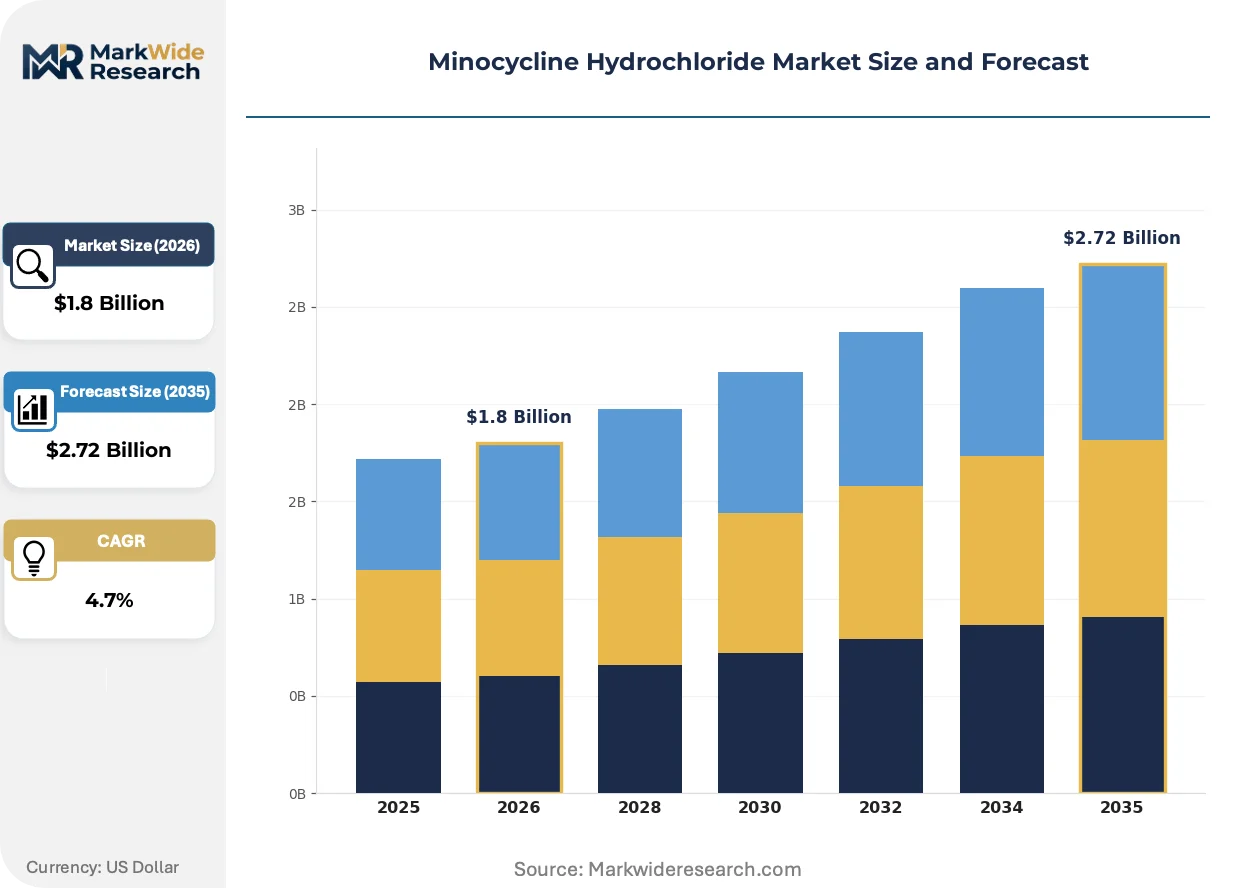
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Topical End User: Hospitals, Clinics, Pharmacies, Online Retailers Therapy Area: Infectious Diseases, Acne Treatment, Respiratory Disorders, Others Distribution Channel: Retail, E-commerce, Wholesalers, Direct Sales |
| Companies Covered | Tecoland Corporation, North China Pharmaceutical Group (NCPC), Hovione, Dr. Reddy's Laboratories, HISUN Pharmaceutical, Euticals S.p.A., Uquifa S.A., Sun Pharmaceutical Industries, Atral Cipan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minocycline Hydrochloride Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape competitive positioning in minocycline markets. Manufacturers are pursuing differentiation through delivery technology rather than molecular modification, while stewardship pressures are compressing traditional volume-based business models.
Extended-release matrix technologies using hydroxypropyl methylcellulose and acrylic resin coatings are rewriting the compliance economics of long-term acne therapy. Adolescent dermatology practices in the United States are adopting these formulations at accelerating rates to reduce pill burden and improve completion rates for 12-week treatment courses. The technology is compressing generic commoditization by creating functional differentiation that survives automatic substitution protocols.
EMA's revised guideline on nitrosamine impurities in chemically synthesized APIs is forcing tetracycline manufacturers to revalidate synthetic routes and implement secondary amine scavenging steps. This regulatory revision is elevating analytical chemistry and process validation costs disproportionately for smaller generic entrants targeting European markets. Injectable minocycline formulations for hospital MRSA protocols are experiencing the most acute compliance timeline pressure due to sterility assurance and impurity control requirements.
Hospital formulary committees are consolidating antibiotic stewardship decisions under centralized pharmacy and therapeutics structures, displacing individual prescriber autonomy in minocycline selection. This behavioral shift is concentrating procurement influence among infectious disease pharmacists who prioritize spectrum-narrowing protocols and resistance surveillance data over historical prescribing patterns. The transformation is most visible in US academic medical centers and integrated delivery networks where value-based contracts penalize avoidable broad-spectrum antibiotic utilization.
Minocycline Hydrochloride Market Segmentation
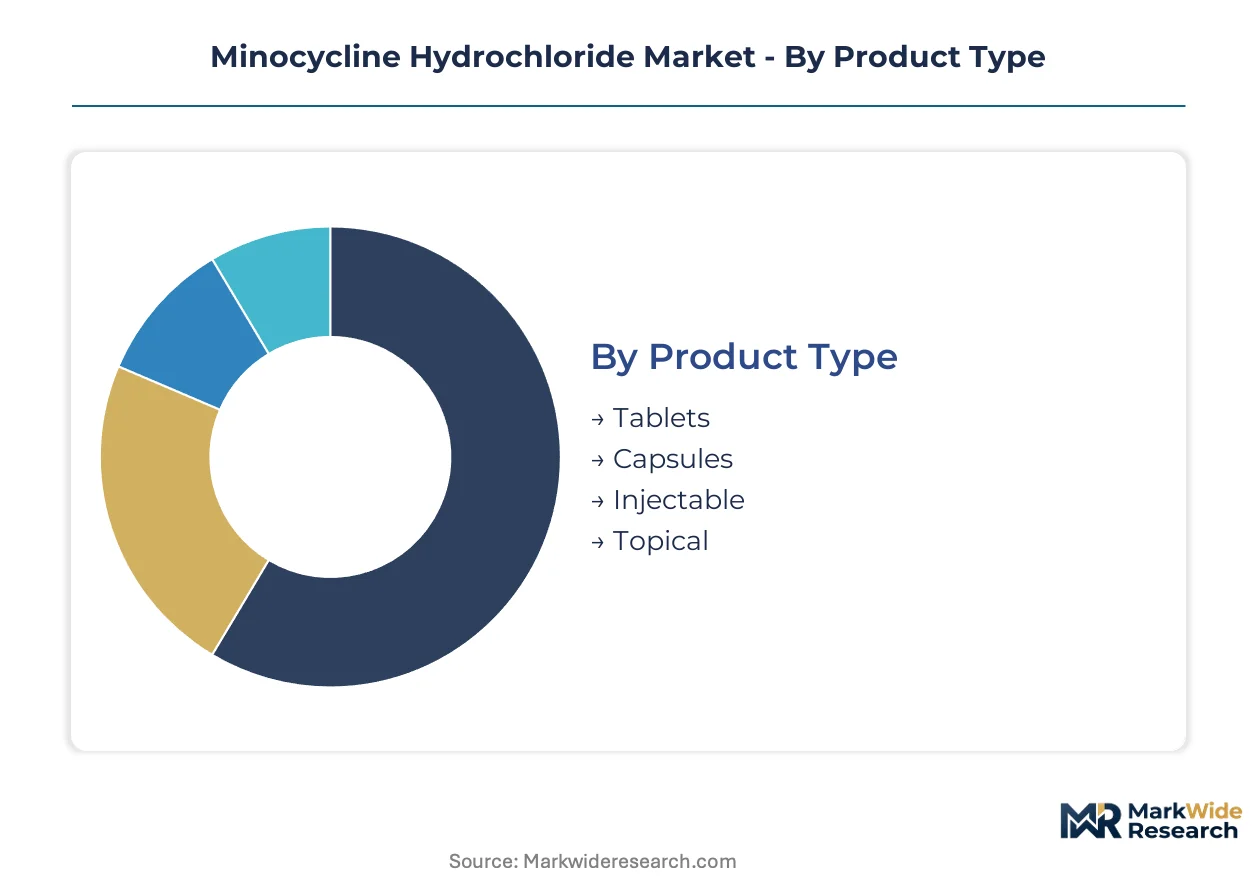
Minocycline hydrochloride markets fragment across four critical dimensions: physical formulation dictates manufacturing complexity and margin structure; end-user setting determines reimbursement pathways and prescription protocols; therapy area shapes regulatory scrutiny and stewardship intensity; distribution channel governs price transparency and substitution exposure. Understanding these intersections reveals where value concentrates and where commoditization threatens.
Product Type:
Volume leadership sits with oral solid doses, while premium capture concentrates in specialized delivery systems that resist automatic substitution.
- Tablets:Immediate-release compressed formulations dominate retail pharmacy volumes through high-throughput production and established bioequivalence pathways. Demand concentrates in United States outpatient acne therapy where FDA therapeutic equivalence ratings enable automatic pharmacy substitution, collapsing brand premiums.
- Injectable:Sterile lyophilized or solution formulations for hospital MRSA protocols command the highest revenue per unit due to sterility assurance and impurity control requirements. United States infectious disease wards embed these into outpatient parenteral antimicrobial therapy pathways, expanding utilization beyond traditional demographics.
- Capsules:Gelatin or HPMC shells containing powder or granulated API serve markets with swallowability preferences or enteric release requirements.
- Topical:Foam and gel formats enable localized acne therapy with reduced systemic antibiotic exposure, gaining traction in dermatology clinics and aesthetic medicine channels.
Today's leader: Tablets. Tomorrow's challenger: Topical.
End User:
Procurement authority is shifting from individual prescribers toward centralized pharmacy committees, altering competitive dynamics across institutional settings.
- Hospitals:Inpatient and emergency departments administer injectable minocycline under antimicrobial stewardship protocols that prioritize resistance surveillance data. United States academic medical centers and integrated delivery networks consolidate formulary decisions under infectious disease pharmacists who penalize avoidable broad-spectrum utilization through value-based contracts.
- Clinics:Dermatology and infectious disease outpatient facilities prescribe oral and topical formulations with greater prescriber autonomy than hospital settings.
- Pharmacies:Retail dispensers face automatic substitution pressures for immediate-release tablets, compressing margin capture for non-differentiated products.
- Online Retailers:Digital channels expose pricing to consumer comparison, accelerating generic commoditization for standard tablet and capsule formats.
Institutional concentration favors hospitals; clinic autonomy preserves differentiation.
Therapy Area:
Stewardship intensity varies sharply across indications, with infectious disease applications facing the most restrictive prescription duration limits.
- Infectious Diseases:MRSA skin and soft tissue infections represent the highest-stakes application, with CDC pathogen tracking networks documenting declining minocycline susceptibility in community-acquired strains. United States emergency departments face pressure to narrow empirical therapy based on local resistance patterns.
- Acne Treatment:Adolescent and adult dermatology sustains the largest prescription volumes, with extended-release matrix technologies improving compliance economics for 12-week treatment courses.
- Respiratory Disorders:Atypical pathogen coverage in community-acquired pneumonia protocols supports niche utilization where tetracycline resistance remains lower than macrolide alternatives.
- Others:Rosacea, periodontitis, and rarer indications contribute fragmented demand with variable reimbursement tiers.
Acne commands volume; infectious disease commands scrutiny.
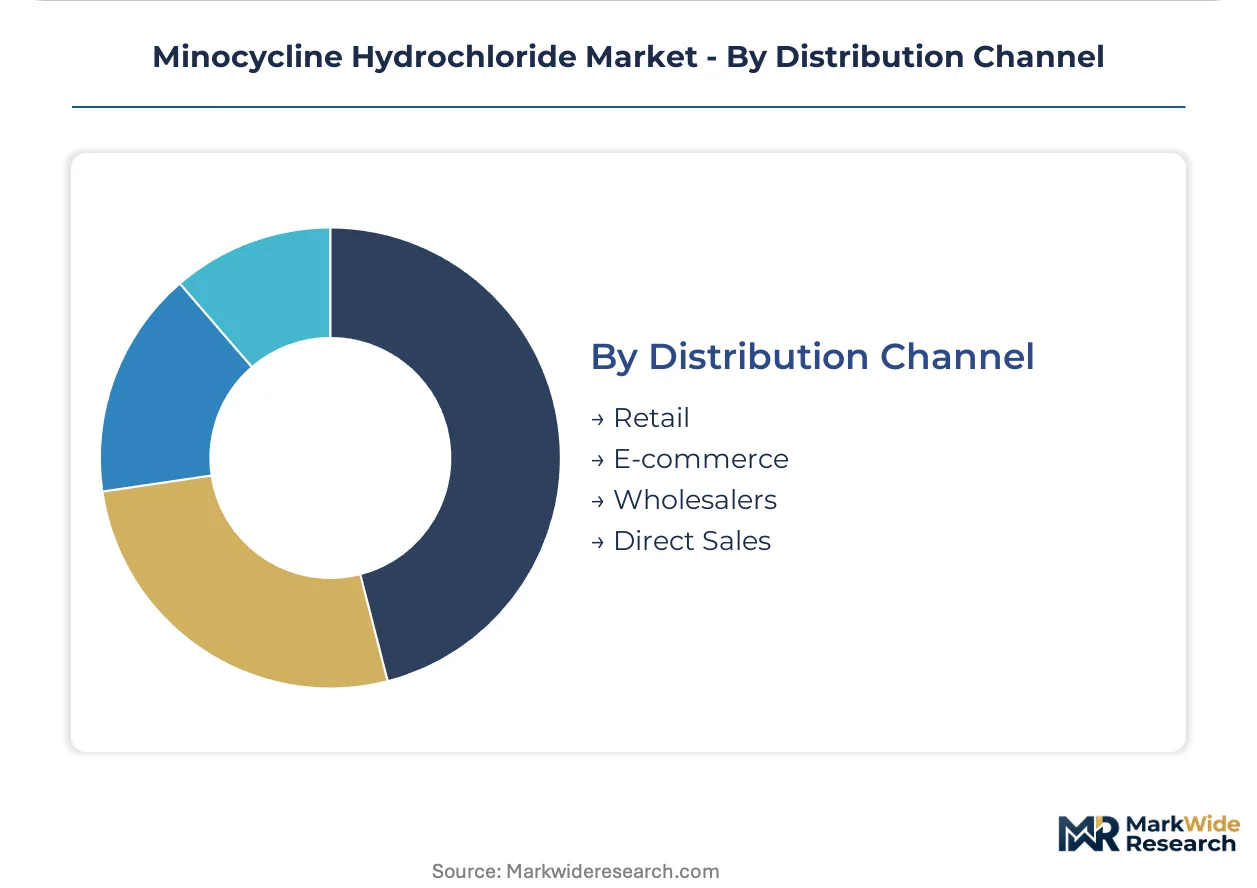
Distribution Channel:
Channel selection determines exposure to price transparency, with direct sales offering the most insulation from substitution pressures.
- Retail:Brick-and-mortar pharmacies handle the majority of tablet and capsule volumes, with automatic substitution enabled by FDA therapeutic equivalence ratings.
- E-commerce:Online platforms accelerate price discovery and generic commoditization, particularly for standard oral formulations with established bioequivalence.
- Wholesalers:Three-tier distribution networks serve institutional and retail accounts with volume-based contracting that favors manufacturers with geographic scale across emerging and developed markets.
- Direct Sales:Manufacturer-to-institution relationships for injectable and specialty formulations preserve margin through contracted pricing outside public formularies.
Direct sales defend margins; retail and e-commerce surrender them to substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation chemists and tetracycline biosynthesis specialists concentrate in legacy pharmaceutical manufacturing clusters across the United States, Portugal, India, and China, anchoring regional supply capabilities.
United States
Outpatient acne therapy and MRSA skin infection protocols sustain elevated minocycline utilization in dermatology and infectious disease wards. FDA bioequivalence requirements for generic tetracyclines elevate manufacturing compliance costs and documentation burdens. New Jersey and North Carolina pharmaceutical corridors host formulation facilities serving hospital and retail channels.
Portugal
Specialized tetracycline fermentation expertise anchors European supply resilience against REACH compliance expansion for active pharmaceutical ingredient purity. ECHA impurity profiling mandates favor established suppliers with captive synthesis capabilities. Lisbon-Porto industrial zones concentrate contract manufacturing organizations with legacy antibiotic biosynthesis infrastructure.
India
CDSCO manufacturing facility inspections and production-linked incentive schemes for active pharmaceutical ingredients attract fermentation capacity investment toward domestic API self-sufficiency. Maharashtra and Gujarat pharmaceutical clusters host finished dose manufacturers dependent on Chinese and Indian API suppliers for fermentation-derived starting materials.
China
Raw material concentration for tetracycline fermentation exposes finished dose manufacturers to customs inspection delays and trade friction. NMPA manufacturing standards and dual carbon goals reshape environmental compliance costs for antibiotic biosynthesis facilities. Shandong and Jiangsu provinces concentrate API fermentation capacity serving global generic supply chains.
Italy
EMA nitrosamine impurity guidelines force revalidation of synthetic routes and secondary amine scavenging implementation across chemically synthesized API operations. Northern Italian chemical-pharmaceutical districts maintain specialized tetracycline production infrastructure serving regulated European markets.
Minocycline Hydrochloride Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across minocycline hydrochloride supply chains. The vendor base spans multinational pharmaceutical corporations with geographic scale, mid-sized API specialists with fermentation expertise, and regional contract manufacturers serving local markets. Three archetypes dominate: integrated innovators with captive synthesis, pure-play fermentation specialists, and geographic-scale generic finished dose suppliers. Competitive moves concentrate on strategic partnerships for API supply security and portfolio diversification into specialty delivery formats.
Among fermentation-centric specialists, Hovione exemplifies the tetracycline biosynthesis archetype through specialized expertise anchored in European regulatory compliance. Sun Pharmaceutical Industries occupies a position representing geographic-scale diversification across emerging and developed markets. Tecoland Corporation sits within the integrated tier, leveraging captive synthesis capabilities to sustain margin resilience against rising certification burdens.
| Leading Market Players |
|---|
| Tecoland Corporation |
| North China Pharmaceutical Group (NCPC) |
| Hovione |
| Dr. Reddy's Laboratories |
| HISUN Pharmaceutical |
| Euticals S.p.A. |
| Uquifa S.A. |
| Sun Pharmaceutical Industries |
| Atral Cipan |
| Others |
Supply Flow & Price Mechanics
Captive synthesis capabilities at established European and North American manufacturers anchor both supply security and pricing power against rising REACH compliance costs for API purity. This integration pattern insulates incumbents from raw material volatility while compressing margins for outsourced competitors dependent on Chinese and Indian fermentation feedstocks.
Pricing Analysis
Bundled sterility assurance and impurity control services command substantial premiums in injectable minocycline for hospital MRSA protocols, while unbundled immediate-release tablets face automatic pharmacy substitution that collapses brand capture. Price differentiation rests on FDA bioequivalence certification tier and geographic delivery cost to institutional buyers. Pricing pressure intensifies in retail channels as therapeutic equivalence ratings enable generic commoditization. Hospital procurement committees demonstrate lowest price sensitivity due to stewardship-driven formulary consolidation, whereas online retailers accelerate price discovery and margin compression.
Supply Chain Analysis
Specialized tetracycline fermentation expertise is aging out of workforces in Portugal and the United States, constraining capacity expansion at legacy European and North American contract manufacturers. Supply concentrates in China, India, and Italy for fermentation-derived starting materials and finished API. Raw material dependencies include fermentation media, specialized strain cultures, and downstream purification resins. Single-source vulnerability runs through concentrated Chinese API clusters exposed to customs inspection delays and trade friction. Distribution runs through three-tier wholesaler networks serving institutional and retail accounts with volume-based contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO manufacturing incentives in India attract fermentation capacity investment away from legacy coastal clusters, exploiting cost differentials against REACH-burdened European suppliers.
For Market Incumbents: Hedge against raw material concentration by securing captive synthesis capabilities or long-term offtake agreements with Indian API producers benefiting from production-linked incentives. Reinforce compliance infrastructure to navigate EMA nitrosamine impurity guidelines and FDA bioequivalence requirements that disproportionately burden smaller generic entrants. Prioritize extended-release formulation development to create functional differentiation surviving automatic substitution protocols. For New Entrants and Emerging Players: E-commerce platforms for direct-to-consumer topical formulations offer the most penetrable entry vector, bypassing consolidated hospital formulary committees and retail pharmacy substitution pressures. Target dermatology clinics and aesthetic medicine channels seeking localized acne therapy with reduced systemic antibiotic exposure. Pursue partnership-based go-to-market models with established European contract manufacturers possessing legacy fermentation infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation specialists because workforce attrition in tetracycline biosynthesis creates scarcity value for remaining technical capabilities. Long-term viability hinges on positioning for antimicrobial stewardship protocols that favor narrow-spectrum positioning and resistance surveillance data. Watch for inflection signals in CDC pathogen tracking networks documenting minocycline susceptibility trends in community-acquired MRSA.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive synthesis insulates margins from REACH compliance cost escalation and raw material volatility. |
| Extended-Release Formulation Development | Matrix technologies create compliance economics differentiation surviving automatic pharmacy substitution. |
| Companion Diagnostic Partnership | Pharmacogenomic screening for CYP2C19 metabolizer status opens specialty pharmacy reimbursement tiers. |
| CDSCO Manufacturing Facility Certification | Indian production-linked incentives attract fermentation capacity investment toward API self-sufficiency. |
| Antimicrobial Stewardship Data Integration | Resistance surveillance alignment penetrates consolidated hospital formulary committee procurement decisions. |
Methodological Framework
Direct dialogue with infectious disease pharmacists, dermatology clinic administrators, API procurement managers, and regulatory affairs specialists at tetracycline manufacturers grounded qualitative findings. Secondary validation drew from FDA ANDA filings, EMA scientific advice letters, CDSCO inspection reports, and hospital formulary databases. Bottom-up prescription volume modeling and top-down API trade flow analysis enabled cross-verification across the analysis window.
Bottom-up segmentation modeling tracked oral solid dose, injectable, and topical formulation volumes by therapy area and distribution channel. Top-down macroeconomic calibration incorporated antimicrobial stewardship protocol adoption curves and regional regulatory enforcement intensity. CAGRs were derived from prescription duration trend analysis and resistant-indication protocol expansion rates. Forecast inputs included fermentation capacity investment pipelines and nitrosamine impurity guideline implementation timelines.
The model assumes a particular technology adoption path for extended-release matrix formulations; alternative pathways for topical foam and gel delivery systems would alter the outlook. Forecasts reflect assumptions about stewardship protocol penetration and generic substitution elasticity. Material deviation in CDC resistance surveillance data or EMA impurity guideline enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market