
 Meningococcal Disease Treatment Market | 2026-2036
Meningococcal Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Meningococcal Disease Treatment Market Outlook
Recombinant protein technology is restructuring product economics across meningococcal vaccines, displacing older polysaccharide-based formulations with higher-efficacy conjugate and factor H binding protein candidates. GlaxoSmithKline plc leverages its MenACWY franchise and Bexsero serogroup B platform to sustain manufacturing scale across European and North American supply chains. Pfizer Inc. anchors its position through Trumenba, competing on dosing flexibility and adolescent indication breadth. Serum Institute of India Pvt. Ltd. dominates emerging-market access through cost-optimized pentavalent and conjugate supply, extending affordable volumes across African and South Asian immunization programs.
Meningococcal disease treatment encompasses pharmaceutical and biological interventions targeting Neisseria meningitidis infection, spanning multivalent vaccines composed of capsular polysaccharides conjugated to carrier proteins such as CRM197 or tetanus toxoid, and acute-phase antibiotics including third-generation cephalosporins and penicillin derivatives. The primary purpose centers on prevention of invasive meningococcal disease through immunization, alongside rapid bacterial eradication in septicemia and meningitis presentations. Vaccines command the largest value pool within product type segmentation, with conjugate formulations capturing premium positioning due to T-cell dependent immunogenicity and memory response induction. Preventive care leads the therapy area dimension, while post-exposure prophylaxis represents a faster-growing niche driven by outbreak response protocols and close-contact chemoprophylaxis guidelines.
The FDA governs biologics licensure and breakthrough therapy designation for novel meningococcal vaccines, while the EMA's Committee for Medicinal Products for Human Use shapes European market access through centralized marketing authorization and pediatric investigation plan requirements. The CDC's Advisory Committee on Immunization Practices directly influences United States demand by setting routine and risk-based recommendation categories for adolescent and college-aged cohorts. Stakeholders must monitor serogroup epidemiology shifts and regulatory harmonization between FDA accelerated pathways and EMA conditional approval frameworks to anticipate portfolio prioritization decisions.
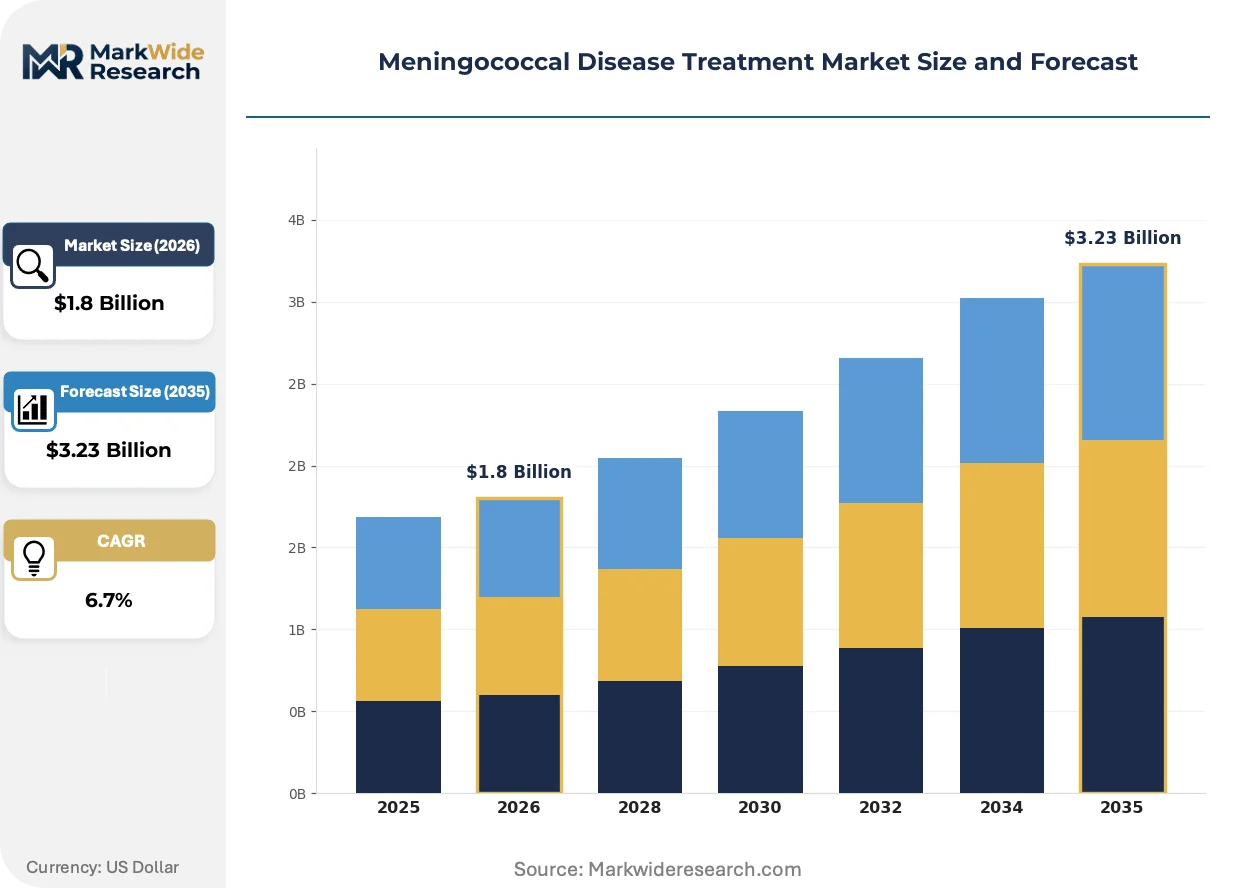
Market Dynamics
Recombinant protein technology is compressing development timelines for serogroup B vaccines while CDC recommendation categories reshape demand concentration across adolescent and college-aged cohorts in the United States.
Growth Catalysts
- FDA Accelerated Approval:Breakthrough therapy designation compresses clinical development timelines for novel vaccine candidates targeting emerging serogroups.
- Carrier Screening Protocols:Expanded genetic testing programs in university health systems drive demand for preventive immunization among matriculating students.
- CRM197 Conjugation:T-cell dependent immunogenicity from diphtheria toxoid carrier proteins strengthens memory response durability in pediatric formulations.
Market Restraints
- Factor H Binding Protein Complexity:Technical limitations in achieving broad coverage across diverse fHbp subvariants constrain serogroup B vaccine efficacy breadth.
- Cold Chain Infrastructure:Supply concentration risk in sub-Saharan Africa and South Asia limits conjugate vaccine distribution to urban centers.
- Polysaccharide Formulation Obsolescence:Older plain polysaccharide vaccines face substitution pressure from higher-efficacy conjugate alternatives in procurement tenders.
Strategic Opportunities
- Indian Universal Immunization Programme:Cost-optimized pentavalent supply contracts create white space for expanded meningococcal conjugate inclusion in national schedules.
- EMA Conditional Approval Framework:Adaptive licensing pathways enable earlier market entry for candidates targeting outbreak-prone serogroup C strains.
- Direct-to-Pharmacy Distribution:Bypassing traditional hospital procurement channels expands retail access for adolescent booster doses in suburban United States markets.
Industry Challenges
- Bioprocess Engineering Talent:Shortages in mammalian cell culture expertise constrain scale-up capacity for recombinant protein antigen production.
- Lot-to-Lot Consistency Certification:Extended analytical validation timelines for conjugate potency assays delay batch release and inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meningococcal Disease Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Antiseptics, Supportive Care Therapy Area: Preventive Care, Acute Treatment, Post-Exposure Prophylaxis, Research & Development End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., Sanofi Pasteur, Novartis AG, Merck & Co., Inc., Serum Institute of India Pvt. Ltd., F. Hoffmann-La Roche Ltd., Johnson & Johnson, Wockhardt Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meningococcal Disease Treatment Market Strategic Shifts
Technology convergence between recombinant antigen design and adjuvant formulation is redefining immunogenicity benchmarks while regulatory pathways compress development-to-approval intervals.
mRNA platform technology is expanding into meningococcal vaccine development, enabling rapid reconfiguration against emergent serogroup variants. European biotech developers and United States defense health agencies are piloting synthetic antigen approaches for pandemic preparedness stockpiles. This technology is expanding into outbreak response protocols, compressing the traditional 5-7 year development window for strain-matched vaccines.
The FDA's Project NextGen initiative prioritizes platform-agnostic regulatory frameworks for respiratory and invasive bacterial vaccines. This industrial consequence accelerates Investigational New Drug application reviews for candidates utilizing novel delivery mechanisms. Pediatric indication sponsors in the United States are responding by front-loading immunobridging studies to capture adolescent label expansions.
University health systems are consolidating vaccine procurement through centralized GPO contracts, displacing fragmented department-level purchasing. This channel concentration forces manufacturers to negotiate exclusive formulary access against standardized tender specifications. The phenomenon is most visible across large state university systems in the United States, where mandatory immunization compliance tracking drives volume commitments.
Meningococcal Disease Treatment Market Segmentation
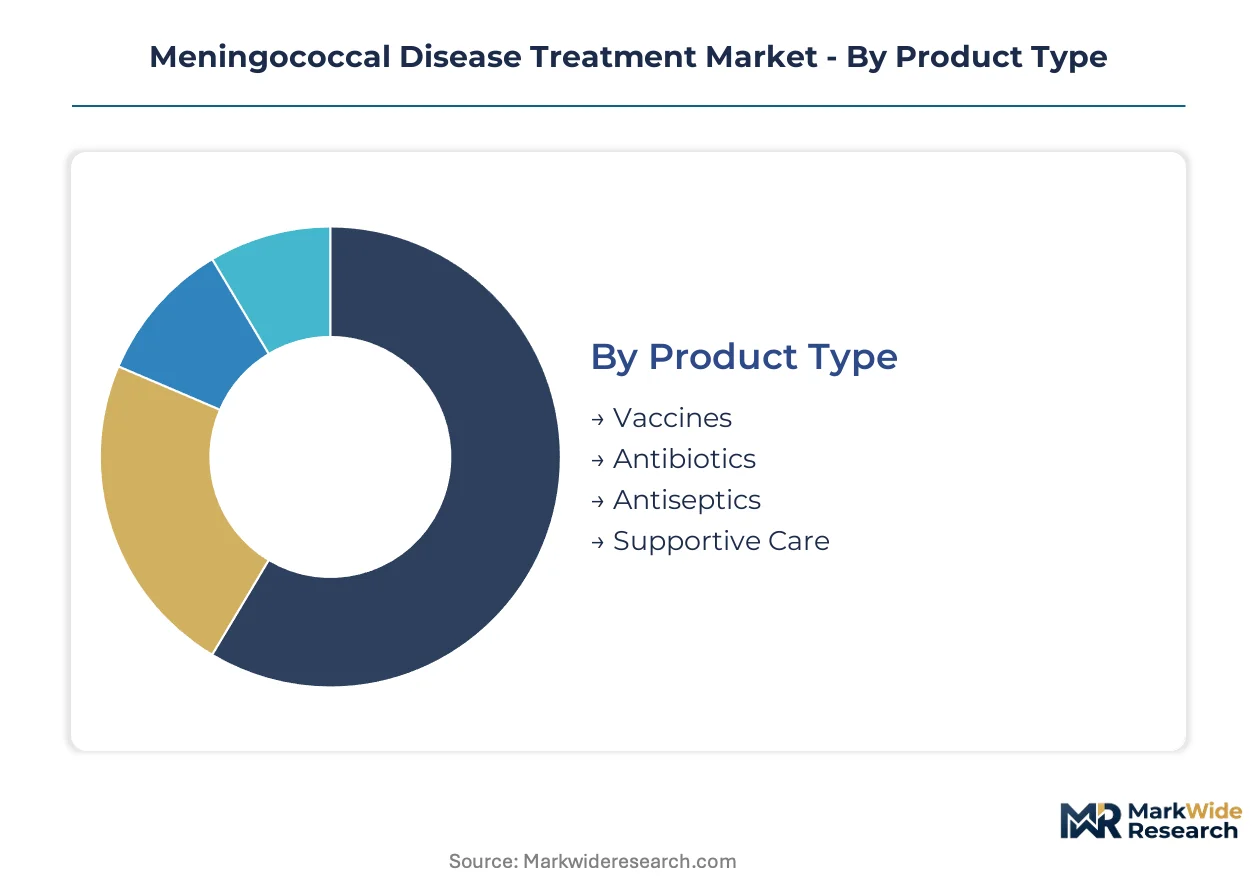
Meningococcal disease treatment markets fragment across intervention timing, care setting, and biological mechanism. Each segment carries distinct regulatory pathways, margin structures, and procurement concentration that shape competitive positioning.
Product Type:
Upgrade cycles favor conjugate and recombinant formulations over legacy polysaccharide platforms, compressing obsolescence timelines for older manufacturing assets.
- Vaccines:Conjugate formulations employing CRM197 or tetanus toxoid carriers dominate pediatric immunization schedules through T-cell dependent immunogenicity. Demand concentrates in United States adolescent cohorts where CDC recommendation categories mandate coverage for college matriculation; carrier screening protocols at university health systems reinforce volume.
- Antibiotics:Third-generation cephalosporins and penicillin derivatives constitute acute-phase bacterial eradication for septicemia and meningitis presentations. Usage clusters in hospital emergency departments across India and Nigeria where rapid pathogen clearance determines mortality outcomes; resistance surveillance programs constrain formulary flexibility.
- Antiseptics:Topical and mucosal preparations target decolonization protocols in outbreak settings.
- Supportive Care:Fluid resuscitation and vasopressor adjuncts address septic shock complications in intensive care units.
Volume placements concentrate in Vaccines; the faster expansion belongs to Antibiotics as resistance-driven combination protocols extend treatment duration.
Therapy Area:
Cost tier differentiation separates mass preventive programs from resource-intensive acute interventions, with procurement budgets diverging sharply across public health and hospital pharmacy channels.
- Preventive Care:Routine immunization schedules and risk-based recommendations target adolescents, military recruits, and asplenic patients. Deployment scales through national programs in the United Kingdom and Saudi Arabia where public procurement tenders specify multivalent coverage; cold chain infrastructure limits rural penetration in sub-Saharan Africa.
- Acute Treatment:Hospital-based antibiotic protocols and intensive care management address invasive disease presentations. Concentration sits in tertiary referral centers across Brazil and Australia where meningococcal sepsis triage protocols compress time-to-antibiotic windows; mortality outcomes drive formulary premium tolerance.
- Post-Exposure Prophylaxis:Close-contact chemoprophylaxis and outbreak response vaccination target household and institutional clusters.
- Research & Development:Clinical trial supply and serogroup surveillance support pipeline candidates.
Preventive Care captures dominant share; Post-Exposure Prophylaxis is climbing the fastest as university outbreak protocols expand chemoprophylaxis coverage.
End User:
Customer type segmentation reveals procurement consolidation in institutional channels versus fragmentation in retail-accessible settings, with pricing power diverging accordingly.
- Hospitals:Inpatient antibiotic administration and intensive care supportive management anchor acute treatment revenue. Volume aggregates in metropolitan medical centers across Germany and Japan where sepsis bundle compliance mandates rapid diagnostic-to-treatment intervals; pharmacy and therapeutics committees control formulary access.
- Clinics:Outpatient vaccination delivery and post-exposure prophylaxis dispensing serve community-based preventive demand. Access concentrates in United States retail health clinics and French vaccination centers where appointment availability determines adolescent series completion; reimbursement parity with physician offices varies by payer.
- Research Institutions:Clinical trial sites and epidemiological surveillance networks support vaccine development.
- Home Care:Limited to oral antibiotic completion and recovery monitoring in stable patients.
Hospitals retain volume leadership; Clinics are gaining share fastest as retail vaccination access expands suburban coverage.
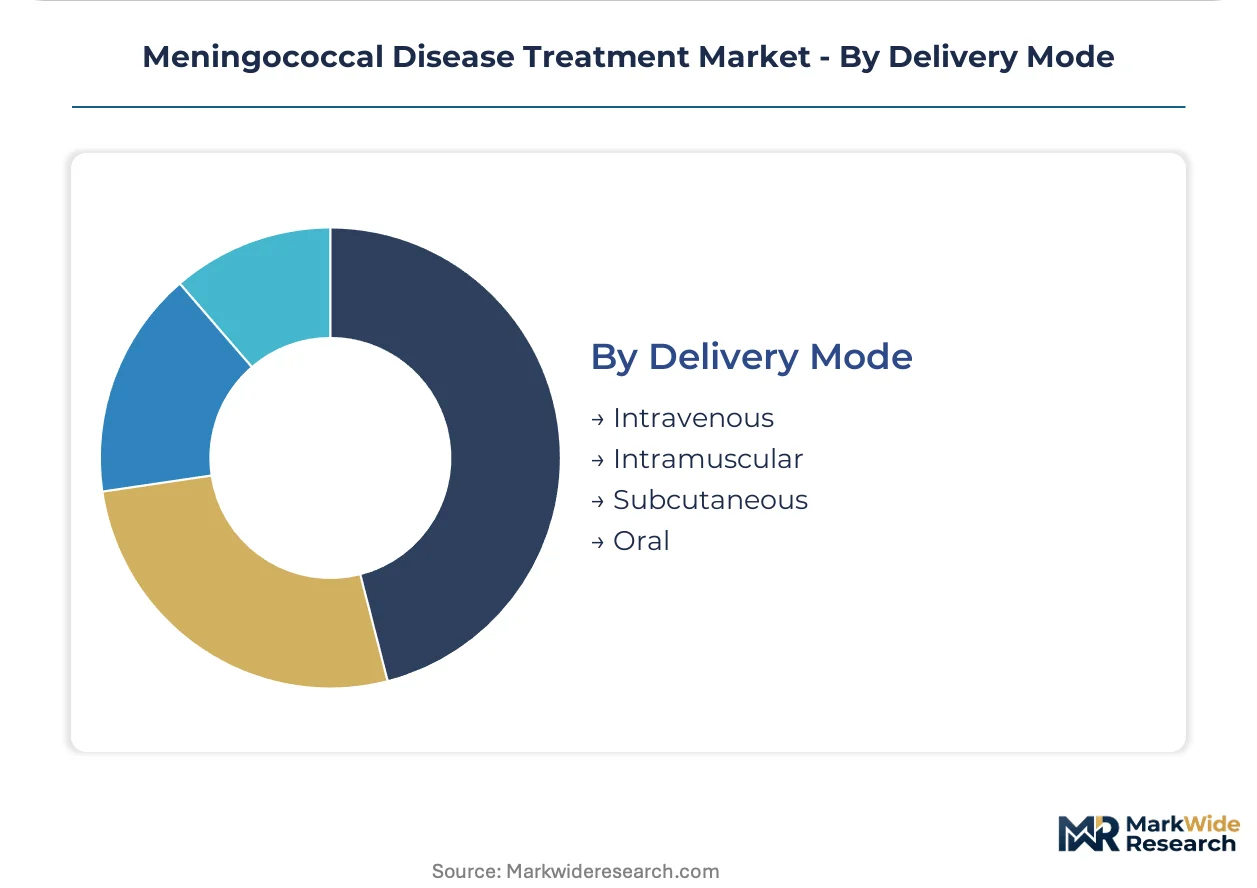
Delivery Mode:
Supply concentration in parenteral manufacturing creates bottlenecks that oral formulation developers exploit where bioequivalence permits, reshaping competitive entry strategies.
- Intravenous:Direct bloodstream antibiotic delivery ensures rapid peak concentrations in septicemia and meningitis. Utilization dominates emergency departments across Italy and South Korea where thirty-minute antibiotic administration targets constrain route selection; infusion pump compatibility limits generic substitution.
- Intramuscular:Vaccine administration in deltoid or anterolateral thigh sites enables efficient mass immunization. Deployment scales through school-based programs in Canada and community pharmacies in the United Kingdom where trained immunizer availability expands access; needle gauge and adjuvant viscosity influence site reaction profiles.
- Subcutaneous:Alternative vaccine delivery for specific patient populations with bleeding risk.
- Oral:Outpatient antibiotic completion and prophylaxis regimens where bioavailability permits.
Intravenous commands acute treatment volume; Intramuscular shows steepest expansion trajectory as pharmacy-based vaccination access broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States where the CDC's Advisory Committee on Immunization Practices drives adolescent vaccination schedules and university carrier screening protocols. Pediatric immunization programs in Saudi Arabia and India's public health systems are expanding access to conjugate formulations. Cold chain infrastructure limitations constrain distribution reach across sub-Saharan Africa and South Asian rural markets.
United States
The CDC's routine and risk-based recommendation categories mandate MenACWY coverage for adolescents aged 11-12 years with booster doses at 16. University health systems in California, Texas, and Massachusetts enforce carrier screening protocols for matriculating students. The FDA's accelerated approval pathways compress development timelines for novel serogroup B candidates targeting college-aged cohorts.
United Kingdom
The NHS national immunization program delivers routine MenACWY doses to teenagers alongside catch-up campaigns for university entrants. Public Health England coordinates outbreak response protocols across Greater London and Manchester metropolitan clusters. The MHRA's pediatric investigation plan requirements shape European market access timelines for adolescent label expansions.
India
The Universal Immunization Programme is evaluating pentavalent conjugate inclusion for high-burden states including Maharashtra and Karnataka. Serum Institute of India anchors domestic supply through cost-optimized manufacturing in Pune. CDSCO regulatory harmonization with WHO prequalification standards accelerates tender access for African export volumes.
Saudi Arabia
The Ministry of Health mandates meningococcal vaccination for Hajj pilgrims and domestic adolescents through the national preventive care schedule. Riyadh and Jeddah medical cities concentrate tertiary treatment capacity for invasive disease presentations. The SFDA's streamlined biologics registration supports rapid deployment of multivalent formulations during outbreak periods.
Brazil
ANVISA governs licensure for imported conjugate vaccines while Fiocruz maintains domestic production capacity for public sector tenders. São Paulo and Rio de Janeiro hospital networks anchor acute treatment demand through sepsis bundle compliance programs. The national immunization program is expanding adolescent MenACWY coverage beyond historical risk-group targeting.
Meningococcal Disease Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers balance conjugate vaccine franchises against recombinant protein development pipelines. The structure consolidates around multinational pharmaceutical conglomerates with established biologics manufacturing infrastructure and emerging-market specialists competing on cost-optimized supply. Three archetypes define positioning: CRM197 conjugation platform holders, factor H binding protein innovators, and high-volume tenders serving Gavi-eligible countries. Geographic expansion and technology licensing represent the dominant competitive moves, with manufacturers securing exclusive formulary access through centralized university procurement contracts.
Within the multinational tier, GlaxoSmithKline plc and Pfizer Inc. exemplify platform-scale competitors leveraging adolescent indication breadth and dosing flexibility. Serum Institute of India Pvt. Ltd. occupies a distinct position as an emerging-market anchor, representing the high-volume, cost-optimized archetype serving national immunization programs across Africa and South Asia.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Sanofi Pasteur |
| Novartis AG |
| Merck & Co., Inc. |
| Serum Institute of India Pvt. Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson |
| Wockhardt Ltd. |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification standards gate qualified supply for Gavi-eligible tenders and simultaneously stratify access to premium-tier pricing reserved for CDC-recommended formulations in United States university procurement channels. Cold chain compliance investments and conjugate potency certification costs feed directly into margin structures, compressing economy-tier viability while reinforcing incumbent pricing power at the top of the stack.
Pricing Analysis
Volume placements concentrate in high-volume tenders to national immunization programs where price sensitivity peaks, while margin capture concentrates in adolescent booster doses sold through university health system GPO contracts. Three-tier pricing structure across premium conjugate, standard polysaccharide, and economy bulk-supply levels differentiates by immunogenicity certification and cold-chain assurance grade. Pricing pressure stems from Serum Institute of India's cost-optimized pentavalent supply penetrating African tender markets. Public procurement managers in Gavi-eligible countries exhibit extreme price sensitivity; United States pharmacy benefit managers at large state university systems demonstrate lowest sensitivity due to mandatory immunization compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with CRM197 carrier protein production concentrated in United States and Italian contract manufacturing facilities. Recombinant fHbp antigen supply draws from mammalian cell culture capacity in Belgium and North Carolina, while conjugation chemistry inputs hinge on diphtheria toxoid fermentation runs in France and India. Tariff exposure on temperature-controlled logistics equipment amplifies cost volatility for sub-Saharan African distribution. Distribution runs through centralized government procurement warehouses in emerging markets and direct-to-pharmacy channels in United States suburban retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
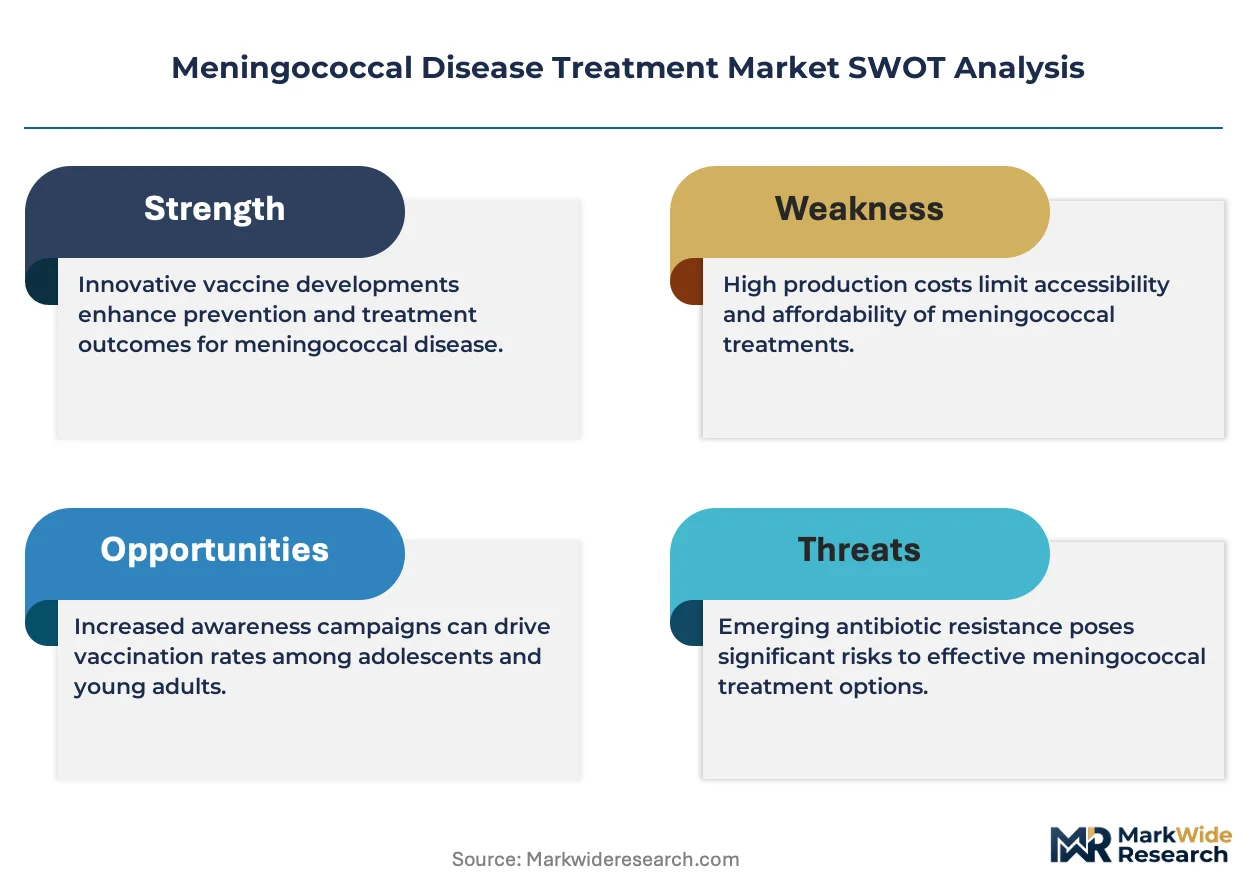
Recombinant protein technology is displacing legacy polysaccharide platforms across meningococcal vaccine development pipelines, creating portfolio transition risk for incumbents and white-space entry points for biotech developers with novel antigen design capabilities.
For Market Incumbents: Anticipate fHbp subvariant coverage gaps in serogroup B formulations by accelerating immunobridging studies for adolescent label expansions ahead of FDA Project NextGen pathway deadlines. Secure backward integration into CRM197 carrier protein production to defend against single-source fermentation bottlenecks threatening conjugate vaccine batch release timelines. Lock exclusive formulary access through multi-year GPO contracts with large state university systems before channel consolidation completes.
For New Entrants and Emerging Players: The premium-economy price-point gap in African national immunization tenders creates white-space for WHO-prequalified pentavalent conjugate supply at 40-60% cost reduction versus multinational incumbent pricing. Target India's Universal Immunization Programme evaluation phase for Maharashtra and Karnataka inclusion as the most penetrable geography. Deploy direct government tender relationships bypassing fragmented hospital procurement channels.
For Investors and Strategic Acquirers: EMA conditional approval framework activation for outbreak-prone serogroup C strains is the leading indicator that adaptive licensing pathways will compress time-to-revenue for platform-agnostic vaccine developers. Position acquisition screening toward biotech developers with mRNA platform capabilities applicable to rapid serogroup variant response. Monitor CDC Advisory Committee on Immunization Practices meeting minutes for recommendation category expansions signaling demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses clinical development timelines for novel serogroup B candidates. |
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Pune and Belgium addresses recombinant antigen production bottlenecks. |
| Pipeline Diversification | mRNA platform investment enables rapid antigen reconfiguration against emergent meningococcal serogroup variants. |
| Licensing Agreement | Technology licensing from European biotech developers accelerates pandemic preparedness stockpile access for defense health agencies. |
| Long-term Supply Agreement | Exclusive GPO contracts with California and Texas university systems lock adolescent booster dose volume commitments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with vaccine development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at United States university health systems. FDA biologics licensure applications, EMA centralized marketing authorization submissions, CDC Advisory Committee on Immunization Practices meeting records, and WHO prequalification assessment reports supplied segmentation inputs. Bottom-up patient cohort modeling and top-down national immunization program budget analysis enabled triangulation across value chain estimates.
Data-stream reconciliation across shipment volumes, tender awards, and manufacturer disclosed capacity yields integrated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from trend extrapolation of adolescent vaccination coverage rates and outbreak response protocol frequency. Serogroup epidemiology surveillance data and cold chain infrastructure investment flows informed regional growth differentials.
Inputs from CDC recommendation updates and EMA pediatric investigation plan determinations were available through the study window; gaps in real-time university health system procurement transaction data introduce uncertainty bands around United States demand concentration estimates. Forecasts reflect assumptions regarding regulatory harmonization timelines and serogroup shift patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Brucellosis Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Measles Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market