
 Global Bacterial Vaccines Market | 2026-2036
Global Bacterial Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bacterial Vaccines Market Foresight
Multi-source procurement for bulk antigens is realigning how large manufacturers secure raw material supply. Sanofi leverages captive fermentation capacity across European sites to reduce dependency on external suppliers. GSK plc anchors its bacterial vaccine franchise on proprietary conjugation chemistry that competitors struggle to replicate at scale. Serum Institute of India competes aggressively on cost structure while expanding WHO-prequalified output for UNICEF tenders.
Bacterial vaccines comprise formulations containing killed or attenuated bacterial pathogens, purified subunits, or polysaccharide-protein conjugates designed to elicit protective humoral and cellular immunity against diseases such as pneumococcal pneumonia, meningococcal meningitis, and pertussis. These products undergo fermentation, purification, adjuvant formulation, and fill-finish under strict cold-chain parameters before distribution to immunization programs. Conjugate vaccines command the deepest margin pools due to manufacturing complexity and limited biosimilar competition. Pediatric Immunization generates the highest absolute volumes, while Traveler Protection offers premium pricing dynamics in private channels. Government Healthcare Programs dominate distribution, though Online Pharmacies represent the fastest-growing channel for adult boosters and occupational segments.
FDA batch release testing, EMA's Good Manufacturing Practice inspections, and WHO prequalification standards collectively determine which manufacturers access national immunization programs and multilateral procurement pools. Stringent regulatory requirements for consistency of polysaccharide molecular weight and conjugation ratios favor incumbents with decades of analytical validation data. Stakeholders must monitor how evolving FDA guidance on novel adjuvants and the EU AI Act's deployment rules for manufacturing analytics reshape competitive barriers and capital deployment timelines.
Market Dynamics
mRNA platform migration is restructuring bacterial vaccine manufacturing economics, compressing development timelines and forcing legacy fermentation-dependent producers to retool capital deployment strategies.
Growth Catalysts
- WHO prequalification pathways:Streamlined assessment protocols accelerate manufacturer entry into UNICEF procurement pools, expanding supply access for low-income national immunization programs.
- Conjugate chemistry maturation:Polysaccharide-protein linkage technologies enable broader serotype coverage in pneumococcal formulations, driving pediatric program upgrades.
- India manufacturing concentration:Serum Institute of India and Bharat Biotech anchor regional bulk antigen supply, reducing import dependency for African and Southeast Asian buyers.
Market Restraints
- Fermentation input volatility:Yeast extract and soy peptone prices fluctuate with agricultural commodity cycles, squeezing margin predictability for bulk antigen producers.
- Single-source adjuvant dependency:Aluminum salt supply concentrates among three European chemical processors, creating vulnerability for fill-finish operations.
- EMA batch release friction:Extended consistency testing timelines for novel conjugation ratios delay market entry for upgraded formulations.
Strategic Opportunities
- Sub-Saharan Africa coverage gaps:Underpenetrated meningococcal serogroup A campaigns in the Sahel region offer volume expansion potential for WHO-prequalified suppliers.
- Traveler Protection channel digitization:Online pharmacy platforms enable direct-to-consumer adult booster sales, bypassing traditional clinic networks.
- EU AI Act manufacturing analytics:Regulatory clarity on algorithmic process control creates first-mover advantage for facilities deploying real-time release testing.
Industry Challenges
- Conjugation chemistry talent scarcity:Specialized biochemists with polysaccharide activation expertise command premium compensation, constraining R&D team scaling.
- Cold-chain infrastructure capex:Ultra-low temperature storage requirements for mRNA bacterial vaccine candidates demand facility investments exceeding traditional fill-finish lines.
- Legacy ERP integration friction:Electronic batch record systems from 1990s-era MES platforms resist interoperability with modern manufacturing execution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bacterial Vaccines Market |
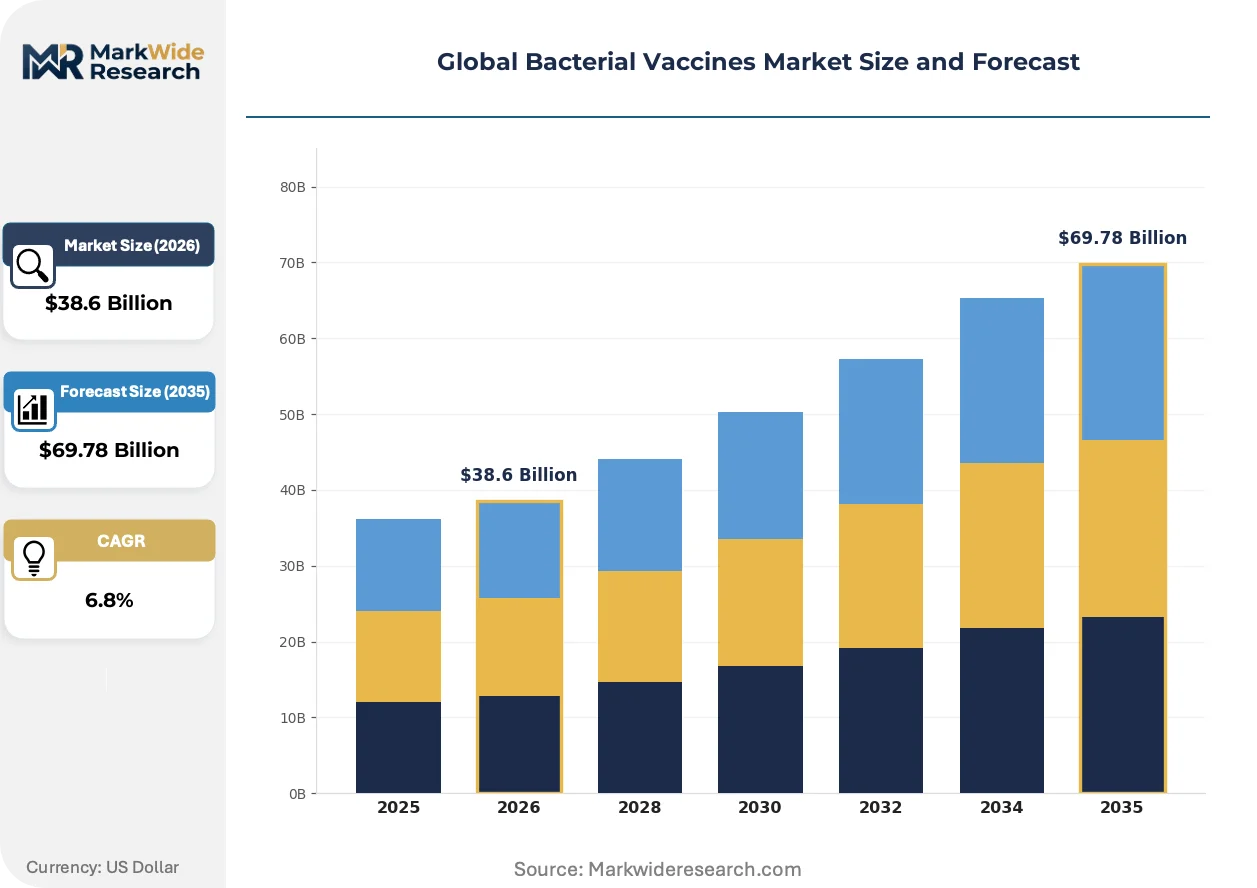
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Conjugate, Toxoid, Live Attenuated, Subunit, Polysaccharide Application: Pediatric Immunization, Geriatric Prophylaxis, Traveler Protection, Occupational Health, Maternal Immunization End User: Hospitals, Clinics, Public Health Institutions, Research Organizations, Military Healthcare Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Government Healthcare Programs, Private Clinics, Online Pharmacies |
| Companies Covered | Sanofi, GSK plc, Merck & Co., Inc., Pfizer Inc., Serum Institute of India, CSL Limited, AstraZeneca, Bharat Biotech, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bacterial Vaccines Market Shifts & Advancements
Manufacturing technology convergence and procurement model evolution are compressing development cycles while fragmenting traditional supply relationships across bacterial vaccine value chains.
Cell-free protein synthesis platforms are modularizing bacterial antigen production by decoupling fermentation from downstream purification. Mid-size biotech developers in Singapore and South Korea are adopting these systems for rapid toxoid prototyping, collapsing strain engineering timelines from months to weeks and enabling parallel serotype screening without dedicated bioreactor farms.
EMA's updated Good Manufacturing Practice Annex 1 for sterile products is forcing aseptic processing upgrades across European fill-finish networks. Isolator technology and continuous monitoring requirements are raising capital barriers for contract manufacturers, concentrating sterile finishing capacity among sites with validated barrier systems and pushing smaller players toward partnership models with established incumbents.
Multilateral procurement bodies are consolidating tender specifications around standardized presentation formats and packaging configurations. UNICEF's vaccine supply division is narrowing acceptable vial sizes and diluent pairing options, forcing formulation teams to redesign stability programs around fewer SKU variants and squeezing customization revenue from private-market travelers in India and Brazil.
Global Bacterial Vaccines Market Segmentation
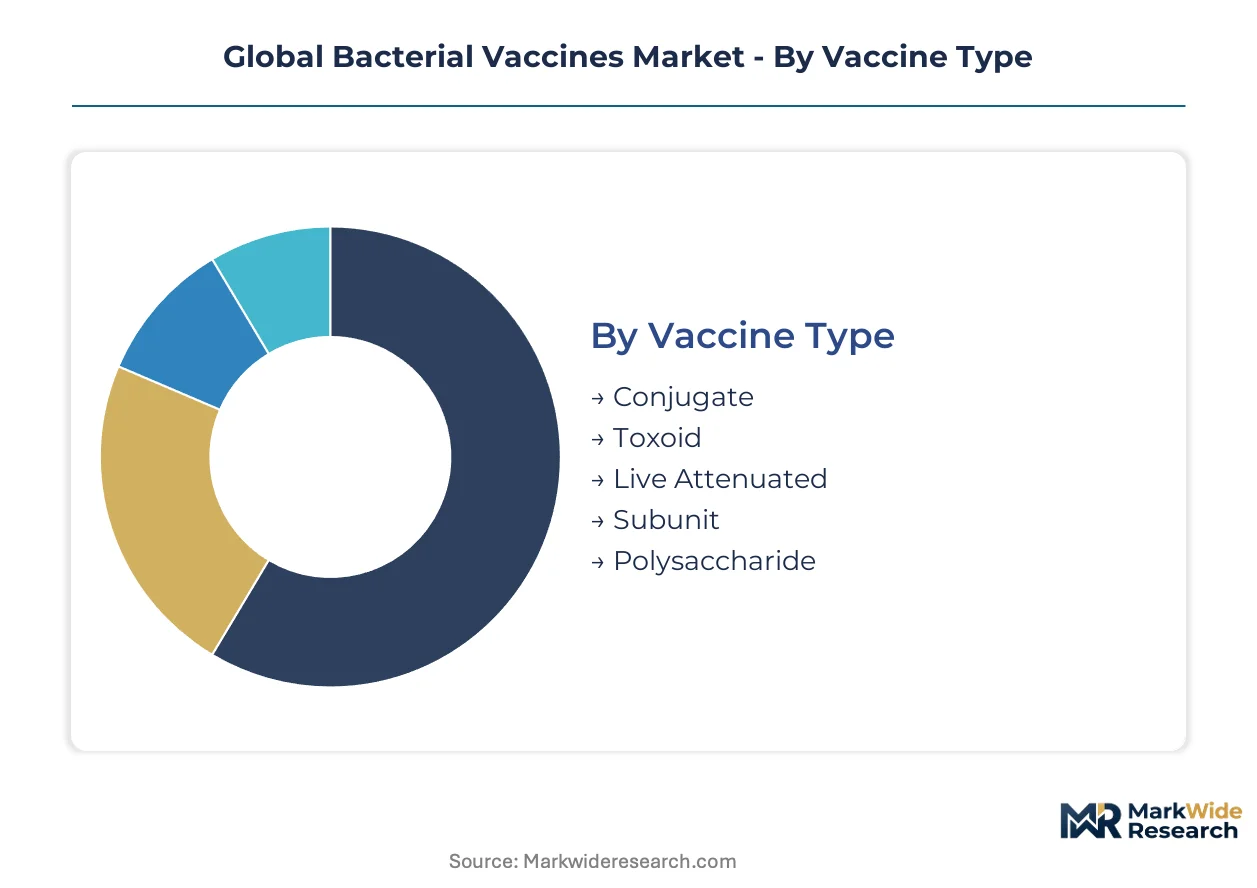
Bacterial vaccine segmentation reveals divergent margin structures across manufacturing complexity tiers. Pediatric programs drive absolute volume, while traveler and occupational channels command premium pricing in private markets.
Vaccine Type:
Volume concentrates in established fermentation platforms, while premium margins accrue to conjugation chemistry requiring specialized polysaccharide-protein linkage expertise.
- Conjugate:Polysaccharide-protein conjugates employ covalent linkage chemistry to enhance immunogenicity in infant populations. Demand clusters in pneumococcal and meningococcal programs across India's national immunization schedule and African Gavi-supported campaigns, where serotype expansion drives formulation upgrades. GSK plc and Sanofi dominate manufacturing capacity for these high-barrier products.
- Toxoid:Formalin-inactivated bacterial exotoxins elicit protective antitoxin antibodies without live pathogen exposure. Tetanus and diphtheria toxoids anchor India's Universal Immunization Programme, with Serum Institute of India supplying WHO-prequalified bulk to UNICEF procurement pools. Regulatory consistency requirements for toxin inactivation kinetics favor incumbent producers with decades of analytical validation.
- Live Attenuated:Weakened bacterial strains replicate transiently to stimulate cellular immunity. BCG tuberculosis vaccine remains the primary commercial example, with constrained supplier base due to seed lot management complexity.
- Subunit:Purified recombinant antigens eliminate reactogenicity risks of whole-cell preparations. acellular pertussis components demonstrate this approach, though manufacturing yields lag conjugate economics.
- Polysaccharide:Purified capsular polysaccharides without protein carriers generate weaker infant responses. Adult pneumococcal formulations and meningococcal polysaccharide vaccines serve niche markets where conjugate alternatives face supply constraints.
Today's leader: Conjugate. Tomorrow's challenger: Subunit, as recombinant platform maturation compresses cost structures.
Application:
Customer type determines procurement pathway—government tenders versus private channels—creating divergent pricing and compliance requirements.
- Pediatric Immunization:National programs in low- and middle-income countries generate the highest absolute volumes through Gavi and UNICEF procurement mechanisms. India's pentavalent and pneumococcal conjugate vaccine introductions demonstrate how Gavi transition financing reshapes supplier selection as countries graduate to self-financed procurement.
- Traveler Protection:Typhoid, meningococcal, and cholera vaccines target pre-departure immunization for tourists and business travelers. Private clinics in São Paulo, Mumbai, and Singapore command 40-60% price premiums over public program tenders through convenience positioning and same-day scheduling.
- Geriatric Prophylaxis:Pneumococcal and pertussis boosters address waning immunity in aging populations. Japan's routine adult immunization infrastructure and Medicare Part B coverage in the United States define reimbursement benchmarks.
- Occupational Health:Anthrax and Q fever vaccines protect laboratory workers, veterinarians, and military personnel. Institutional procurement concentrates in government channels with specialized cold-chain requirements.
- Maternal Immunization:Tetanus toxoid and pertussis vaccines administered during pregnancy protect neonates through transplacental antibody transfer. WHO recommendations drive adoption in Southeast Asian national programs.
Traveler Protection climbs fastest in value terms, though Pediatric Immunization retains volume dominance through multilateral procurement scale.
End User:
Facility type dictates cold-chain infrastructure requirements and regulatory inspection frequency, segmenting operational compliance burdens.
- Hospitals:Tertiary medical centers manage complex multi-dose vial protocols and adverse event surveillance. India's district hospital network anchors public sector distribution, while US academic medical centers participate in CDC Vaccines for Children program administration.
- Clinics:Primary care and specialty vaccination sites handle routine immunization scheduling. Brazil's municipal health posts demonstrate high-throughput public delivery models.
- Public Health Institutions:National immunization programs and supranational bodies like PAHO manage strategic stockpiles and emergency deployment. WHO prequalification status determines supplier eligibility.
- Research Organizations:Phase III trial sites and post-marketing surveillance networks generate real-world efficacy data. EMA's Good Clinical Practice inspections govern European trial conduct.
- Military Healthcare:Defense medical services procure biodefense and deployment-specific formulations. US DoD and UK Ministry of Defence maintain specialized cold-chain networks for forward deployment.
Public Health Institutions control procurement volume. Private Clinics capture margin expansion through direct-to-patient service bundling.
Distribution Channel:
Channel selection determines price realization and patient access friction, with digital platforms disrupting traditional clinic-dependent models.
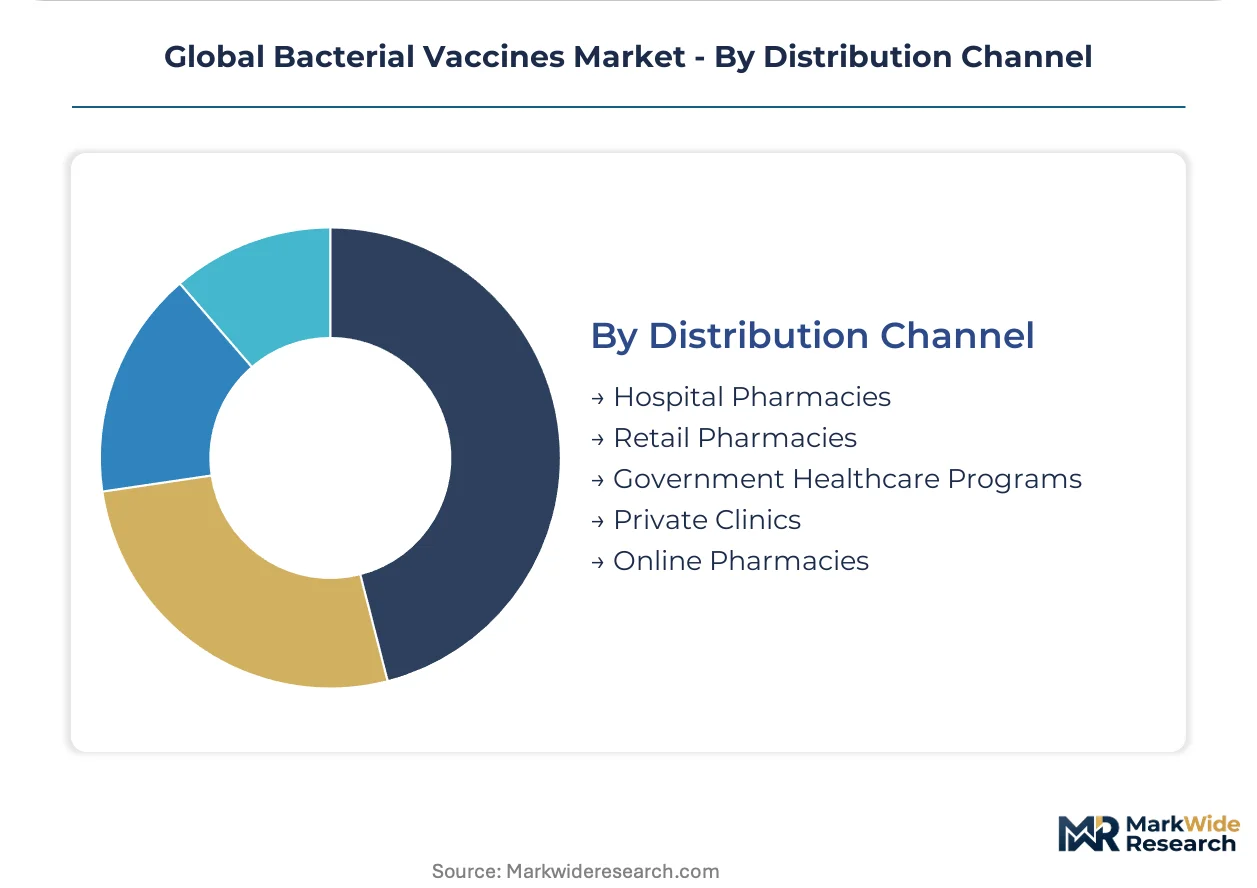
- Government Healthcare Programs:National immunization schedules and Gavi-funded procurement dominate volume distribution. India's Universal Immunization Programme reaches 26 million infants annually through cold-chain infrastructure extending to sub-district levels.
- Hospital Pharmacies:Inpatient and outpatient dispensing integrates with electronic health records for compliance documentation. US 340B program pricing creates procurement advantages for eligible hospitals.
- Retail Pharmacies:Community-based adult vaccination expands access beyond clinic hours. CVS and Walgreens in the United States demonstrate high-volume seasonal influenza and shingles vaccine administration models adaptable to bacterial boosters.
- Private Clinics:Fee-for-service immunization serves insured and out-of-pocket populations. Travel medicine specialists in London, Dubai, and Hong Kong bundle consultation with destination-specific bacterial vaccines.
- Online Pharmacies:Direct-to-consumer platforms enable appointment scheduling and home delivery of temperature-stable formulations. India's PharmEasy and 1mg illustrate regulatory navigation for prescription vaccine distribution.
Government Healthcare Programs anchor volume. Online Pharmacies gain share fastest as logistics platforms mature for cold-chain last-mile delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit regulatory-arbitrage opportunities as EMA batch release timelines extend, redirecting capital toward Indian facilities where CDSCO fast-track pathways compress approval cycles by 40-60% for WHO-prequalified sites.
United States
Pediatric Immunization schedules and Medicare Part B reimbursement anchor demand for pneumococcal and pertussis boosters. FDA's Center for Biologics Evaluation and Research enforces stringent consistency testing for conjugate molecular weight distributions. The Research Triangle Park cluster in North Carolina concentrates Phase III trial infrastructure and post-marketing surveillance capabilities for bacterial vaccine candidates.
India
UNICEF procurement tenders and Gavi transition financing drive volume for pentavalent and pneumococcal conjugate formulations. CDSCO's streamlined manufacturing license renewals for WHO-prequalified exporters accelerate market access. Hyderabad and Pune host concentrated bulk antigen fermentation capacity, with Serum Institute of India and Bharat Biotech anchoring regional supply for African and Southeast Asian buyers.
Germany
EMA Good Manufacturing Practice inspections and Annex 1 sterile product upgrades shape competitive barriers for fill-finish operations. The Paul-Ehrlich-Institut governs batch release testing timelines that delay novel conjugation ratio approvals. Bavaria's Munich-Stuttgart corridor concentrates isolator technology providers and aseptic processing equipment manufacturers serving European vaccine networks.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for mRNA platform bacterial vaccines. The UK Health Security Agency manages strategic stockpiles for meningococcal and anthrax biodefense formulations. Oxford and Cambridge anchor academic-industry partnerships advancing novel adjuvant research with commercialization pipelines.
Brazil
ANVISA's aligned review mechanisms with PAHO expedite registration for WHO-prequalified products entering the national immunization program. Municipal health posts demonstrate high-throughput public delivery models for BCG and pentavalent schedules. São Paulo's Butantan Institute maintains captive fermentation capacity for yellow fever and bacterial toxoid bulk production.
Global Bacterial Vaccines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mRNA platform migration and cell-free synthesis technologies. The structure concentrates among fermentation-dependent incumbents with decades of analytical validation data and conjugation chemistry expertise. Three archetypes dominate: integrated pharmaceutical conglomerates with captive bulk capacity, specialized vaccine manufacturers competing on WHO prequalification status, and biotech developers leveraging novel expression platforms. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as legacy producers retool for mRNA manufacturing economics.
Within the integrated pharmaceutical tier, Sanofi and GSK plc exemplify established positioning through proprietary manufacturing infrastructure and conjugation chemistry capabilities. Serum Institute of India occupies a distinctive cost-structure archetype, anchoring regional supply for multilateral procurement pools. These three entities represent contrasting strategic postures: European-headquartered conglomerates with deep validation datasets, and an Indian-based specialist competing on WHO-prequalified volume production.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Serum Institute of India |
| CSL Limited |
| AstraZeneca |
| Bharat Biotech |
| Johnson & Johnson Services, Inc. |
| Others |
Supply & Pricing Matrix
Yeast extract and soy peptone price indices cascade directly through bacterial vaccine manufacturing economics, compressing margins for bulk antigen producers while amplifying pricing power for conjugate chemistry specialists with captive fermentation capacity.
Pricing Analysis
Input-cost pass-through from agricultural commodity volatility shapes a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command valuation based on WHO prequalification status and serotype expansion capability, while economy tiers compete on volume scale for UNICEF tenders. Pricing pressure stems from Gavi transition financing as countries graduate to self-financed procurement. Government healthcare programs exhibit highest price sensitivity; private traveler clinics demonstrate lowest sensitivity through convenience bundling.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing and domestic-content mandates in Brazil's national immunization program are reshaping regional sourcing patterns. Bulk antigen supply concentrates in India, Germany, and the United States. Fermentation inputs draw from agricultural commodity markets; aluminum salt adjuvants rest on three European chemical processors. Single-source adjuvant dependency creates vulnerability for fill-finish operations. Distribution runs through government procurement channels dominating volume, with online pharmacies emerging for adult boosters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as demand shifts toward premium conjugate formulations with expanded serotype coverage and validated cold-chain integrity.
For Market Incumbents: To counter mRNA platform migration, deepen conjugation chemistry expertise through specialized biochemist retention programs and accelerate WHO prequalification renewals for expanded serotype portfolios. Anchor fill-finish capacity in isolator-equipped European sites to meet EMA Annex 1 sterile product upgrades.
For New Entrants and Emerging Players: Begin with cell-free protein synthesis platforms for rapid toxoid prototyping in Singapore or South Korea, targeting underpenetrated meningococcal serogroup A campaigns in Sub-Saharan Africa's Sahel region. Pursue direct-to-consumer online pharmacy partnerships for traveler protection channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where conjugation chemistry talent scarcity constrains R&D scaling and legacy ERP systems resist modernization. Target mid-tier manufacturers with validated WHO-prequalified capacity and isolator technology infrastructure. Watch EMA batch release timeline extensions as signal for regulatory-arbitrage capital redirection toward Indian CDSCO fast-track pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Acceleration | UNICEF tender eligibility unlocks multilateral procurement pools for low-income national programs. |
| mRNA Platform Technology Licensing | Manufacturing economics compression forces legacy fermentation producers toward capital retooling. |
| Isolator Technology Deployment | EMA Annex 1 compliance raises barriers for sterile finishing capacity concentration. |
| Cell-Free Synthesis Adoption | Singapore and South Korean biotech developers collapse strain engineering timelines for rapid prototyping. |
| Online Pharmacy Channel Integration | Direct-to-consumer platforms bypass traditional clinic networks for adult booster sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine development executives, regulatory affairs leads at EMA and CDSCO, UNICEF procurement officers, and hospital pharmacy directors with secondary validation against FDA filings, EMA submissions, WHO prequalification databases, and Gavi financing disclosure documents. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Comparable-period anchoring tied projection trajectories to historical immunization program scale-up patterns across the analysis window. Segmentation dimensions modeled included vaccine type complexity tiers, application pathways, end-user facility categories, and regional regulatory clusters. CAGRs derived from multivariate regression incorporating pediatric program introduction timelines, Gavi transition financing schedules, and traveler channel digitization rates as industry-specific inputs.
Several conditions sit outside the modeled scope, including pandemic emergency procurement disruptions, novel adjuvant regulatory guidance revisions, and raw material export restriction implementations. Forecasts reflect documented assumptions about immunization program continuity and multilateral financing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Cortisone Market