
 Global Non-Small Cell Lung Cancer Drugs Market | 2026-2036
Global Non-Small Cell Lung Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Small Cell Lung Cancer Drugs Market Foresight
Project finance for late-stage oncology trials is rewriting competitive access in the Global Non-Small Cell Lung Cancer Drugs Market. AstraZeneca leverages its extensive immuno-oncology portfolio to sustain leadership in combination therapy development. Bristol-Myers Squibb Company anchors its position through deep clinical investments in checkpoint inhibitor platforms.
Non-small cell lung cancer drugs comprise systemic therapeutic agents designed to inhibit tumor proliferation through molecular targeting of epidermal growth factor receptors, programmed death-ligand pathways, or microtubule function, typically formulated as intravenous biologics or oral small-molecule inhibitors for stage III and IV disease management. Immunotherapy dominates current revenue pools as pembrolizumab-class agents displace first-line chemotherapy across major markets. Targeted therapy represents the fastest-growing segment as biomarker-driven patient stratification expands addressable populations with EGFR, ALK, and KRAS-directed agents.
The FDA's Breakthrough Therapy designation and the EMA's Priority Medicines scheme are compressing regulatory timelines for novel NSCLC agents while tightening post-market evidence requirements. China's NMPA has expanded its conditional approval framework for oncology drugs, accelerating patient access to imported therapies. Stakeholders must monitor evolving biomarker coverage policies and biosimilar entry timelines as these forces reshape commercial positioning across major markets.
Market Dynamics
Checkpoint inhibitor protocols are compressing first-line treatment paradigms across oncology departments, forcing incumbent chemotherapy franchises to defend position through biomarker-driven combination strategies or cede share entirely.
Growth Catalysts
- Breakthrough Therapy designation:The FDA's accelerated pathway compresses Phase II-to-approval timelines from five years to eighteen months for qualifying immuno-oncology assets.
- Companion diagnostic proliferation:Liquid biopsy platforms expand addressable patient pools by enabling real-time resistance mutation detection without tissue re-biopsy.
- China's conditional approval framework:The NMPA's oncology fast-track allows commercialization based on single-arm Phase II data, accelerating access for imported PD-1 inhibitors.
Market Restraints
- Platinum-based input cost volatility:Cisplatin and carboplatin supply concentrates in Indian API manufacturers, exposing formulation partners to export restriction risk.
- Biomarker testing infrastructure gaps:Community oncology practices in Brazil and Mexico lack NGS capacity, creating treatment eligibility bottlenecks for targeted agents.
- IRDAI reimbursement compression:India's national health insurance caps oncology drug coverage at INR 5 lakh per patient, limiting access to premium immunotherapies.
Strategic Opportunities
- Brain metastasis protocols:Underserved NSCLC patients with CNS progression represent a white space for blood-brain barrier-penetrant small molecules.
- Japan's Sakigake designation:PMDA's priority review system offers twelve-month approval timelines for first-in-class assets addressing unmet mutation subsets.
- Direct-to-patient pharmacy models:Specialty distributors bypass hospital markup structures in Germany and France, capturing margin through home infusion services.
Industry Challenges
- Translational medicine talent scarcity:Biomarker strategy and clinical pharmacology functions face acute hiring pressure as trial complexity escalates.
- CDx co-development timeline misalignment:Diagnostic partners and drug sponsors operate on mismatched funding cycles, delaying simultaneous approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Small Cell Lung Cancer Drugs Market |
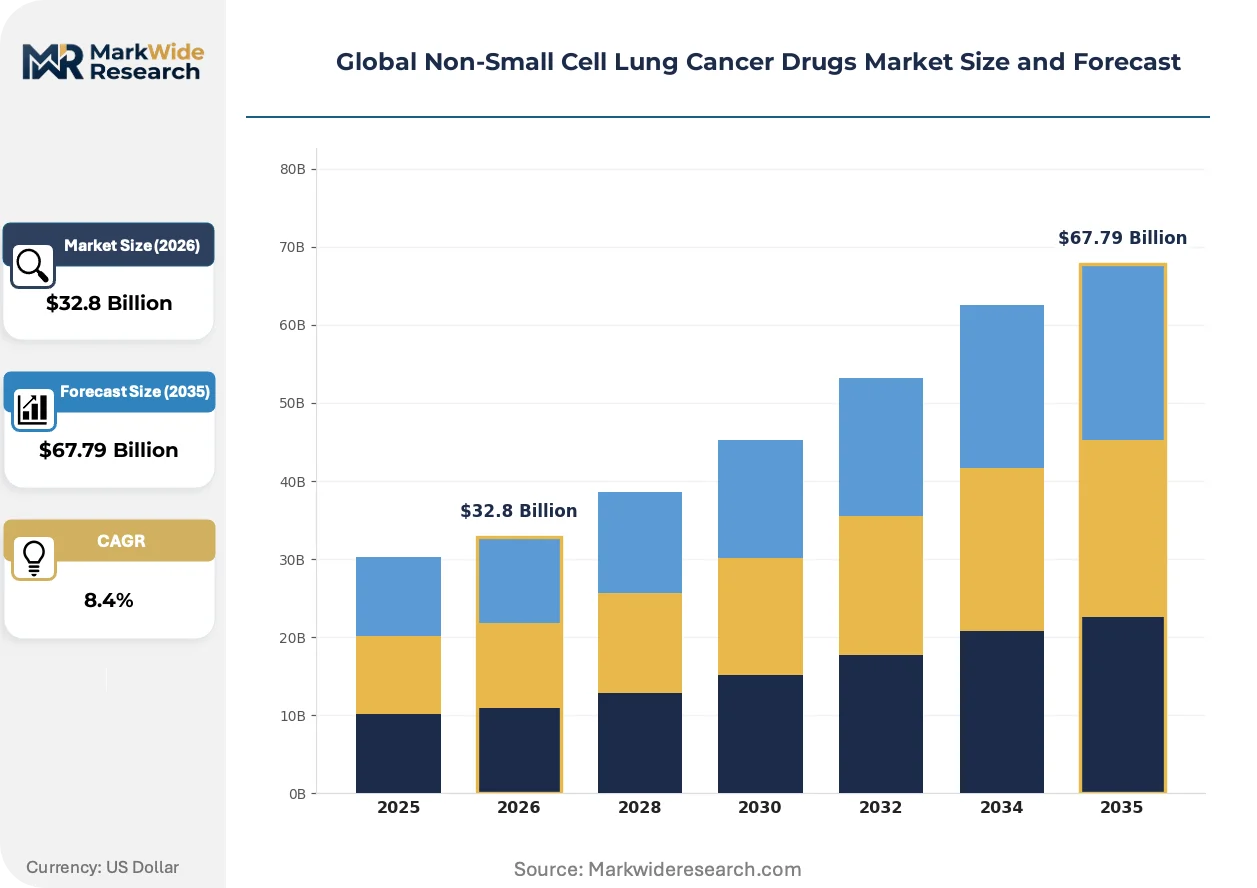
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapy, Immunotherapy Application: Palliative Care, Surgical Treatment, Adjuvant Therapy, Neoadjuvant Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Clinics, Research Institutions, Homecare |
| Companies Covered | AstraZeneca, Bristol-Myers Squibb Company, Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Pfizer Inc., Novartis AG, Amgen Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Small Cell Lung Cancer Drugs Market Shifts & Advancements
Antibody-drug conjugates and bispecific T-cell engagers are emerging from developmental pipelines, threatening to fragment the checkpoint inhibitor monopoly that has dominated NSCLC revenue pools since 2015.
Antibody-drug conjugates targeting HER2, TROP2, and MET are collapsing the historical boundary between chemotherapy and biologic therapy by delivering cytotoxic payloads with tumor-selective precision. Academic medical centers in the United States and South Korea have adopted ADC protocols for post-immunotherapy progression, compressing the addressable window for salvage chemotherapy regimens. The structural consequence is a forced repositioning of taxane and platinum agents to earlier lines or combination backbones where they retain utility.
The EMA's Priority Medicines scheme and the FDA's Project Orbis are synchronizing multi-jurisdictional review timelines for novel NSCLC submissions, reducing regulatory lag between first and fifth market entry from thirty-six months to under twelve. This convergence compresses commercial exclusivity windows for originators while accelerating patient access in secondary markets. Manufacturers now front-load health technology assessment submissions to NICE, G-BA, and HAS to secure pricing and reimbursement before regulatory approval.
Hospital procurement consortia in Italy, Spain, and the Netherlands are consolidating oncology drug purchasing through tender-based frameworks that unbundle clinical service contracts from product supply. Regional hospital networks negotiate multi-year volume commitments in exchange for rebate structures that erode list-price realization. This concentration is most visible in Southern Europe, where public budget constraints have forced centralized purchasing at the autonomous community or regional level rather than individual hospital discretion.
Global Non-Small Cell Lung Cancer Drugs Market Segmentation
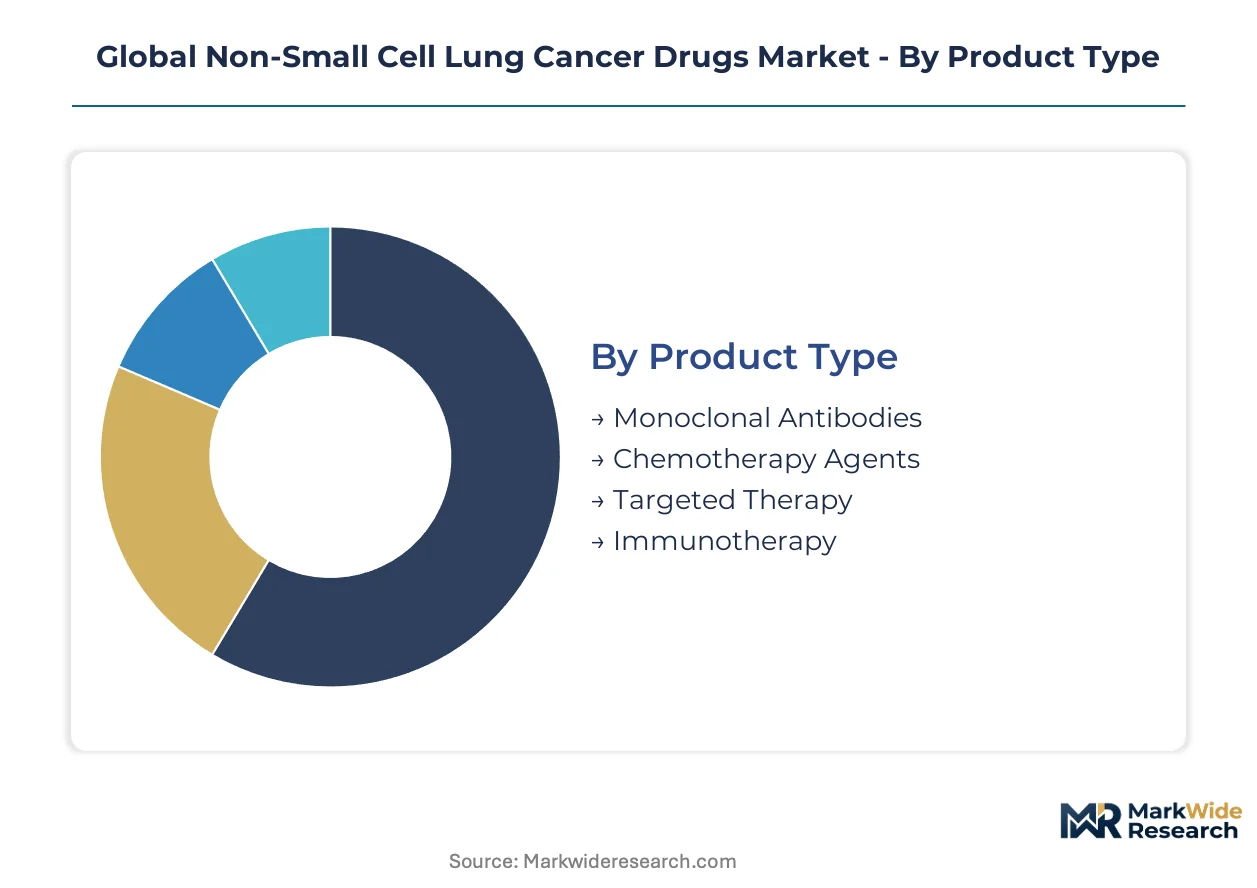
NSCLC treatment selection hinges on biomarker status, disease stage, and patient performance status, creating distinct commercial pockets across therapeutic modalities and care settings. Segmentation reveals where immunotherapy protocols displace legacy chemotherapy and which delivery innovations reshape site-of-care economics.
Product Type:
Use-case spectrum spans curative-intent combination regimens through salvage monotherapy, with each modality carrying distinct reimbursement profiles and development risk.
- Monoclonal Antibodies:Engineered immunoglobulins targeting PD-1, PD-L1, or CTLA-4 checkpoints to restore anti-tumor immunity. Demand concentrates in tertiary oncology centers across the United States and Germany, where pathology turnaround times support biomarker-driven treatment initiation within guideline windows.
- Targeted Therapy:Small-molecule inhibitors modulating EGFR, ALK, ROS1, KRAS G12C, and other oncogenic drivers. Academic medical centers in South Korea and Japan are expanding liquid biopsy protocols to identify resistance mutations, accelerating adoption of next-generation TKIs.
- Immunotherapy:Checkpoint inhibitors and cellular therapies harnessing adaptive immune response. Community oncology practices in the United States are consolidating infusion capacity to capture rising patient volumes.
- Chemotherapy Agents:Platinum doublets and taxanes functioning as combination backbones or salvage options. Procurement in Italy and Spain increasingly flows through regional hospital consortia seeking volume rebates.
The dominant share belongs to Monoclonal Antibodies, while Targeted Therapy is closing the gap fastest.
Application:
Cost tier stratification separates premium-priced neoadjuvant immunotherapy from commoditized palliative regimens, with reimbursement intensity varying by treatment intent and line of therapy.
- Neoadjuvant Therapy:Pre-surgical systemic treatment to downstage locally advanced disease. Major cancer centers in the United States and United Kingdom are adopting perioperative checkpoint inhibitor protocols based on pathological complete response endpoints.
- Adjuvant Therapy:Post-surgical treatment to eradicate micrometastatic disease. Community hospitals in France and Germany face formulary pressure to justify premium immunotherapy against observation.
- Surgical Treatment:Resection-based management for early-stage NSCLC without systemic therapy. Volume concentrates in high-volume thoracic surgery centers with multidisciplinary tumor boards.
- Palliative Care:Symptom-focused management for advanced or terminal disease. Home infusion services in the Netherlands are capturing share from hospital-based delivery for stable patients.
Neoadjuvant Therapy commands premium pricing, while Palliative Care represents the largest addressable volume pool.
Delivery Mode:
Patient preference and site-of-care economics are shifting administration away from infusion centers toward oral and subcutaneous alternatives where clinically equivalent.
- Intravenous:Infusion-based delivery for biologics requiring controlled administration. Hospital outpatient departments in the United States retain revenue through facility fees despite drug cost compression.
- Oral:Self-administered small-molecule inhibitors enabling treatment outside clinical settings. Specialty pharmacies in Germany are capturing dispensing margin through direct-to-patient models.
- Subcutaneous:Rapid-injection alternatives reducing chair time and nursing burden. Regulatory approvals in Japan and South Korea are expanding addressable populations for fixed-dose combinations.
- Inhalation:Localized delivery for investigational agents targeting pulmonary lesions. Clinical trial activity concentrates in academic medical centers with interventional pulmonology expertise.
Intravenous remains the revenue anchor, though Subcutaneous formulations are expanding most quickly.
End User:
Customer type determines purchasing leverage, with consolidated hospital systems extracting deeper rebates than fragmented clinic networks or individual prescribers.
- Hospitals:Integrated delivery networks with oncology service line accountability. Regional procurement consortia in Spain and Italy negotiate multi-year volume commitments.
- Clinics:Community oncology practices with limited infusion capacity. Independent sites in Brazil face biomarker testing infrastructure gaps limiting targeted therapy access.
- Research Institutions:Academic medical centers with early-phase trial portfolios. Investigator-initiated studies in South Korea and Japan are accelerating ADC and bispecific development.
- Homecare:Home infusion and nursing services for stable patients on oral or subcutaneous regimens. Reimbursement frameworks in France are expanding eligibility for hospital-at-home oncology.
Hospitals capture the dominant share of biologic therapy revenue, while Homecare is gaining share fastest as oral targeted agents expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy pathways and Japan's Sakigake designation are accelerating regulatory convergence across major oncology markets, compressing commercialization timelines for novel NSCLC agents while reshaping geographic revenue concentration.
United States
Tertiary cancer centers in Houston, New York, and Boston drive immunotherapy protocol adoption through multidisciplinary tumor boards and rapid biomarker turnaround. Medicare's coverage determination for liquid biopsy testing expands eligibility for targeted therapy selection. The MD Anderson and Memorial Sloan Kettering corridor anchors clinical trial density for antibody-drug conjugate development.
Japan
PMDA's Sakigake priority review system delivers twelve-month approval timelines for first-in-class assets addressing EGFR exon 20 insertion and MET exon 14 skipping mutations. The national health insurance's premium pricing mechanism for innovative oncology drugs sustains manufacturer margins. Tokyo and Osaka academic medical centers lead perioperative checkpoint inhibitor protocol adoption in Asia-Pacific.
Germany
G-BA's early benefit assessment framework forces rapid health technology evaluation for PD-1/PD-L1 inhibitors entering first-line NSCLC indications. Hospital procurement consortia in Bavaria and North Rhine-Westphalia negotiate multi-year volume commitments with escalating rebate structures. The Heidelberg and Munich oncology clusters specialize in neoadjuvant immunotherapy surgical trials.
China
NMPA's conditional approval framework permits commercialization based on single-arm Phase II data, accelerating patient access to imported PD-1 inhibitors and domestic biosimilars. National reimbursement drug list negotiations compress net prices while expanding volume access. Shanghai and Beijing house the highest concentration of Phase III immuno-oncology trial sites outside the United States.
United Kingdom
NICE's technology appraisal process creates binary access decisions that delay or accelerate NHS adoption of premium immunotherapies based on cost-per-QALY thresholds. The Cancer Drugs Fund provides managed access for promising agents pending mature survival data. The Manchester and London cancer center networks pilot real-world evidence collection for post-market commitment fulfillment.
Global Non-Small Cell Lung Cancer Drugs Market Competitive Landscape
On the supply side, the industry is consolidating around immuno-oncology platforms with checkpoint inhibitor franchises defending position against emerging modalities. Large-cap pharmaceutical developers anchor the competitive set through combination therapy portfolios and diagnostic partnerships. Mid-tier biotech specialists occupy the targeted therapy vector with mutation-specific kinase inhibitors. Competitive intensity concentrates on biomarker co-development timelines, biosimilar defense strategies, and perioperative protocol expansion.
Within the large-cap integrated tier, AstraZeneca, Bristol-Myers Squibb Company, and Merck & Co., Inc. exemplify distinct strategic positioning archetypes. AstraZeneca occupies a position emphasizing antibody-drug conjugate and bispecific pipeline density alongside established checkpoint inhibitor presence. Bristol-Myers Squibb Company anchors the dual immunotherapy combination approach through CTLA-4 and PD-1 pathway expertise. Merck & Co., Inc. represents the scale-driven, indication-expansion model with broad first-line positioning across histologies. These three entities collectively shape clinical trial design standards, biomarker coverage policies, and contracting norms that constrain follower strategies.
| Leading Market Players |
|---|
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian API manufacturing for platinum salts is compressing input costs for generic cisplatin and carboplatin formulations while simultaneously eroding pricing discipline among contract manufacturers serving European and Latin American markets. This utilization imbalance forces originator biologics to defend premium positioning through outcome-based contracting and indication-specific value demonstrations rather than commodity competition.
Pricing Analysis
Certification level (FDA-breakthrough versus standard NDA) creates the primary spread between premium checkpoint inhibitors and follow-on PD-1 assets. Three-tier pricing structure across premium immuno-oncology, standard targeted therapy, and economy chemotherapy levels stratifies the market. Cost compression in the chemotherapy tier is intensifying because of biosimilar entry and regional tender consolidation. Community oncology practices in Brazil and Mexico exhibit highest price sensitivity due to reimbursement caps, while tertiary centers in the United States and Germany show lowest sensitivity where outcomes-based contracts dominate.
Supply Chain Analysis
Export-control regimes on dual-use biologics manufacturing equipment constrain capacity expansion in emerging production hubs. Supply concentrates in Switzerland, Singapore, and Ireland for sterile biologics fill-finish, with active pharmaceutical ingredient production anchored in India and China. Key inputs include platinum salts, recombinant cell lines, and single-use bioreactor components. Single-source vulnerability runs through Chinese heparin and Indian platinum API suppliers. Distribution runs through specialty pharmacy networks in the United States and hospital procurement consortia in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-driven patient stratification is fragmenting addressable populations into mutation-specific niches, creating entry points for specialists lacking scale to compete in broad immuno-oncology.
For Market Incumbents: Build diagnostic co-development moats through exclusive liquid biopsy partnerships that lock in companion diagnostic coverage before regulatory submission. Secure capacity reservations at Singapore biologics manufacturing sites to preempt supply constraints for antibody-drug conjugate pipelines. Defend against ADC displacement by accelerating perioperative checkpoint inhibitor protocol expansion into earlier treatment lines. For New Entrants and Emerging Players: Pursue brain metastasis indications as the most penetrable white space, where blood-brain barrier penetration remains underserved by existing PD-1 assets. Target Japan's Sakigake pathway for MET exon 14 and EGFR exon 20 insertion mutations where priority review timelines compress competitive windows. Establish investigator-initiated trial networks with Seoul and Tokyo academic medical centers to generate real-world evidence before formal regulatory engagement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antibody-drug conjugate manufacturing due to payload-linker complexity and containment requirements. Long-term viability favors platforms with diagnostic assets attached, not standalone small molecules. Acquisition candidates should demonstrate biomarker strategy capabilities and at least one Phase II asset with breakthrough therapy designation potential. Watch FDA breakthrough therapy grant velocity as the inflection signal for pipeline quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA's accelerated pathway compresses Phase II-to-approval timelines from five years to eighteen months. |
| Companion Diagnostic Co-Development | Simultaneous CDx approval locks in biomarker exclusivity and formulary placement before competitor entry. |
| Regional Manufacturing Footprint Expansion | Singapore and Switzerland sterile fill-finish capacity secures supply continuity for biologics amid export restrictions. |
| Perioperative Protocol Expansion | Neoadjuvant checkpoint inhibitor adoption in MD Anderson and Memorial Sloan Kettering corridors extends market duration. |
| Liquid Biopsy Platform Partnership | Real-time resistance mutation detection expands addressable pools for next-generation TKI sequencing. |
Research Methodology
The analysis maps immuno-oncology, targeted therapy, and chemotherapy sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview insights combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases enable bottom-up and top-down triangulation across market sizing exercises.
Assumptions held fixed include regulatory pathway timelines for breakthrough therapy designation and biomarker coverage expansion rates, while pricing elasticity and biosimilar entry timing were varied across sensitivity scenarios. Segmentation dimensions modeled span treatment line, administration route, patient biomarker status, and regional regulatory cluster. CAGRs derive from patient flow analysis through diagnosis-to-treatment funnels and line-of-therapy progression probabilities, with inputs including clinical trial enrollment velocity and real-world evidence publication rates.
Sensitivities concentrate around FDA breakthrough therapy grant rates, NMPA conditional approval framework durability, and platinum API supply disruption from Indian export restrictions. Forecasts reflect these assumptions with acknowledged uncertainty from regulatory policy shifts and competitive trial readouts. Cross-checking against IQVIA prescription audit data and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market