
 Global DPT Vaccine Market | 2026-2036
Global DPT Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global DPT Vaccine Market Foresight
Combination vaccine bundling is rebalancing procurement economics across public health systems. Sanofi leverages its pentavalent and hexavalent portfolios to capture integrated tender awards in African and Asian national programs. GlaxoSmithKline anchors European and North American supply through established immunization schedules and cold-chain partnerships. Serum Institute of India dominates volume contracts for UNICEF and Gavi-eligible countries with cost-optimized whole-cell formulations.
DPT vaccine denotes a trivalent immunization containing diphtheria toxoid, tetanus toxoid, and pertussis antigens, administered in a 0.5 mL intramuscular dose to induce active immunity against three bacterial diseases. The formulation requires aluminum salt adjuvant for enhanced immunogenicity and must maintain 2-8°C cold chain integrity throughout distribution. Combination vaccines lead value generation by reducing injection burden and logistics costs in national programs, while pre-filled syringes represent the fastest-growing packaging format due to dosing accuracy and waste reduction advantages. Multi-dose vials retain cost-critical roles in high-volume public campaigns despite higher cold-chain sensitivity.
FDA and EMA standards govern antigen potency, purity, and stability testing for manufacturers accessing regulated markets, while WHO prequalification shapes eligibility for Gavi and UNICEF procurement channels. National regulators in India and China enforce parallel compliance pathways that determine market access for domestic and export-bound production. Stakeholders must monitor evolving pertussis antigen specifications as acellular dominance pressures whole-cell cost structures and manufacturing investment priorities.
Market Dynamics
Combination vaccine bundling is compressing procurement cycles and reconfiguring supplier hierarchies as national immunization programs prioritize injection burden reduction over single-antigen sourcing. This structural shift favors manufacturers with integrated pentavalent and hexavalent portfolios capable of meeting WHO prequalification standards for Gavi and UNICEF tenders.
Growth Catalysts
- Gavi 5.0 strategic framework:The alliance's replenishment commitments expand eligible country access to combination DPT-HepB-Hib formulations, driving volume procurement through UNICEF's centralized purchasing mechanism.
- Whole-cell pertussis manufacturing:Cost-optimized production platforms in India and Indonesia enable price-competitive supply for public sector tenders, sustaining coverage expansion in low-income settings.
- Cold chain infrastructure investments:Solar direct-drive refrigeration deployment across sub-Saharan Africa reduces vaccine spoilage rates and extends reach to last-mile health facilities previously excluded from routine immunization.
Market Restraints
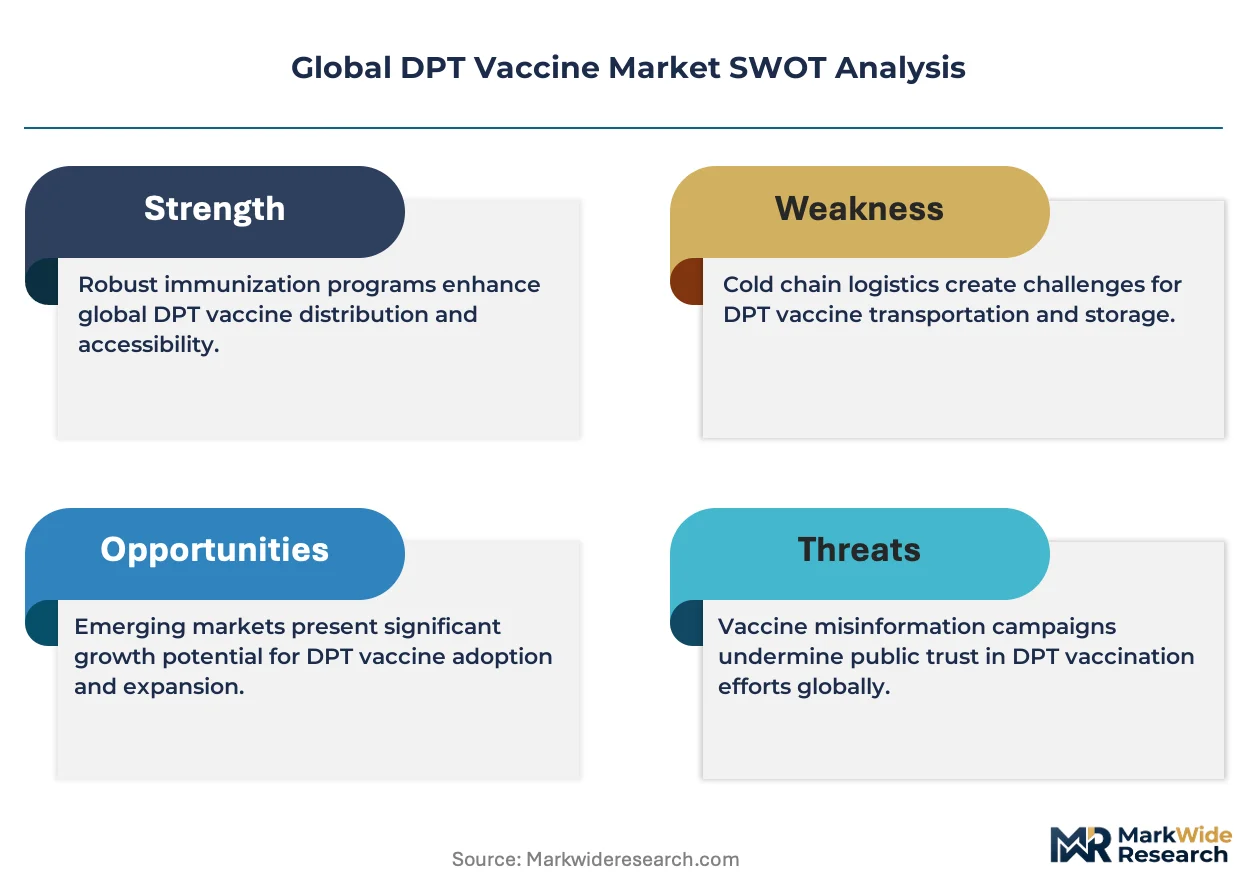
- Aluminum adjuvant supply concentration:Global production of aluminum phosphate and hydroxide adjuvants concentrates among three specialized chemical suppliers, creating input cost volatility for formulation manufacturers.
- Acellular pertussis antigen yield constraints:Purification complexity for filamentous hemagglutinin and pertactin limits batch consistency, constraining capacity expansion for higher-value combination products.
- WHO prequalification timeline friction:Extended stability testing requirements for novel formulations delay market entry by 18-24 months, freezing supplier rosters for multi-year tender cycles.
Strategic Opportunities
- Micro-array patch delivery:Dissolvable microneedle technology eliminates cold chain dependence and enables community health worker administration without needle disposal infrastructure.
- Indonesia's national immunization scale-up:The country's demographic dividend and expanding domestic manufacturing capacity create demand for localized DPT-containing combination supply.
- Pre-filled syringe format migration:Auto-disable syringe integration reduces dosing errors and open-vial wastage, aligning with WHO injection safety mandates for campaign settings.
Industry Challenges
- Fill-finish automation engineering:Specialized aseptic processing expertise for combination vaccines remains scarce, constraining capacity expansion at existing facilities.
- Multi-antigen stability formulation:Protein-protein interactions between diphtheria and tetanus toxoids with acellular pertussis components complicate shelf-life extension efforts.
- Regulatory divergence across prequalification pathways:Parallel FDA, EMA, and WHO stability testing requirements impose redundant validation burdens on multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DPT Vaccine Market |
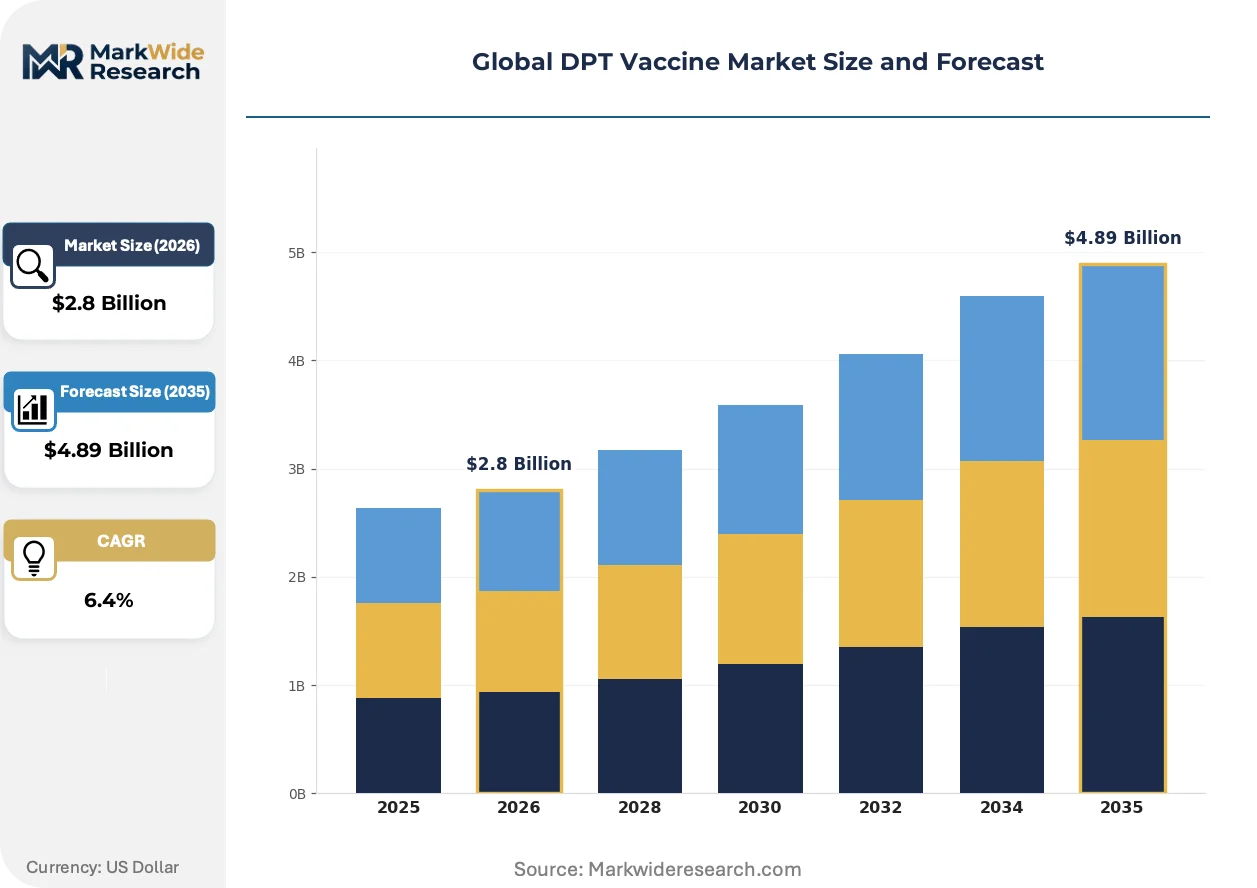
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DPT Whole-cell, DPT Acellular, Combination Vaccines, Monovalent Vaccines Administration Route: Intramuscular, Subcutaneous, Intradermal, Oral End User: Public Immunization Programs, Pediatric Clinics, Travel Clinics, Military Health Services Packaging Type: Single-dose Vials, Multi-dose Vials, Pre-filled Syringes, Ampoules |
| Companies Covered | Sanofi, GlaxoSmithKline, Merck, Serum Institute of India, Pfizer, Johnson & Johnson, AJ Vaccines, Bionet-Asia, Biken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DPT Vaccine Market Shifts & Advancements
Process analytical technology and continuous manufacturing platforms are reshaping vaccine production economics, enabling real-time quality assurance that reduces batch failure rates. These advances intersect with regulatory science evolution and procurement model transformation to redefine competitive positioning.
Single-use bioreactor systems are automating upstream antigen production for acellular pertussis components, replacing stainless steel vessel cleaning validation with disposable contact surfaces. European and North American manufacturers are adopting these platforms for hexavalent combination products, compressing facility turnaround times from weeks to days. This automation is enabling smaller batch sizes that match tender volume flexibility without sacrificing unit economics.
EMA's revised guideline on quality, safety, and efficacy of combination vaccines tightens co-formulation stability requirements, mandating accelerated degradation studies for novel antigen combinations. Manufacturers must now demonstrate 24-month shelf life under stress conditions before market authorization. High-income country suppliers with established stability databases gain compliance advantages, while emerging market entrants face extended development timelines.
National tender consolidation is compressing supplier rosters as Brazil, Nigeria, and Bangladesh shift from fragmented state-level purchasing to federal centralized procurement. UNICEF's vaccine independence initiative enables direct manufacturer negotiation, bypassing traditional distributor intermediaries. This concentration is most visible in Southeast Asia, where Vietnam and Philippines now issue multi-year combination vaccine contracts with price-volume agreements tied to coverage targets.
Global DPT Vaccine Market Segmentation
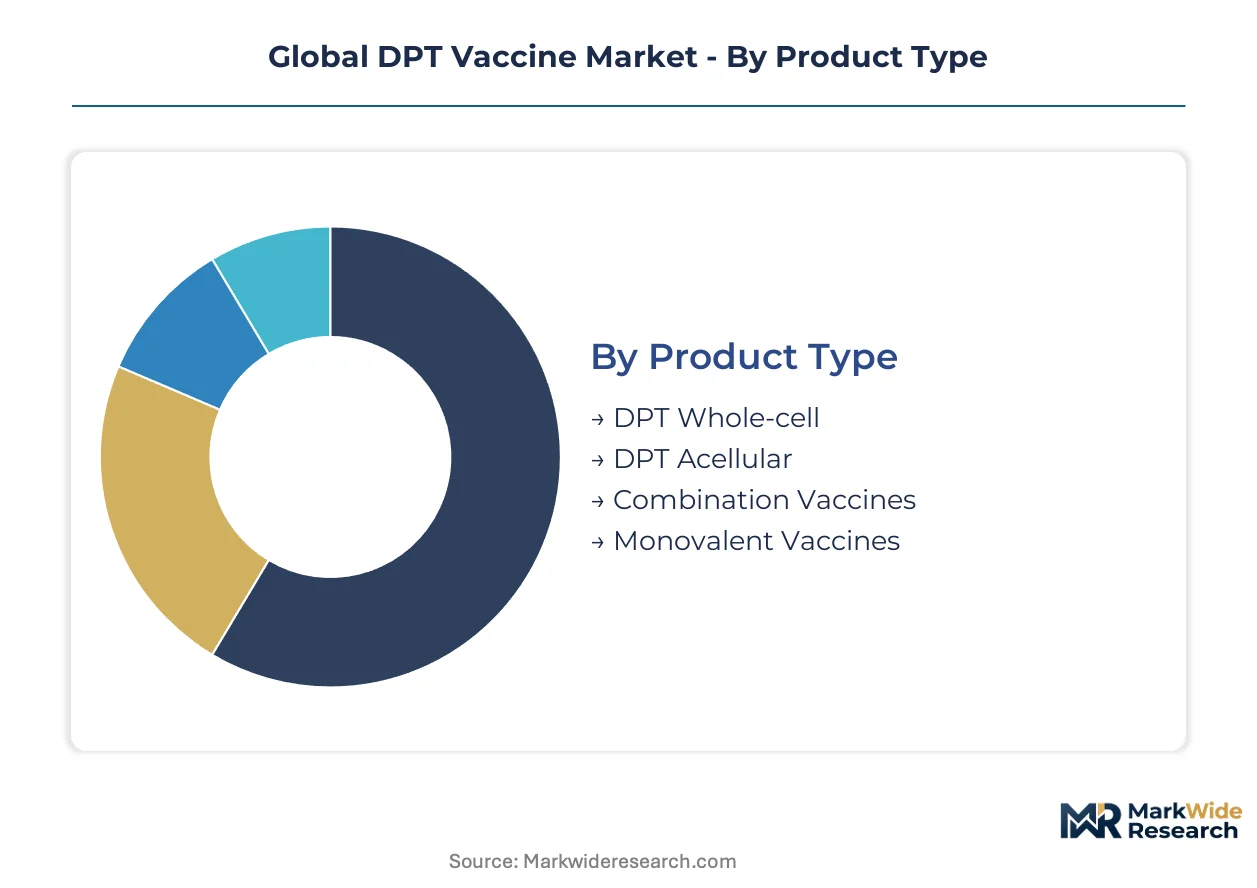
DPT vaccine procurement splits sharply between cost-optimized public tenders and premium-priced private channels. Manufacturers must align formulation, packaging, and distribution strategies to these divergent buyer economics.
Product Type:
Whole-cell formulations anchor UNICEF and Gavi procurement at the lowest cost per dose, while acellular and combination products command premium positioning in regulated markets.
- DPT Whole-cell:Contains inactivated Bordetella pertussis bacteria with aluminum salt adjuvant. Demand concentrates in India, Nigeria, and Bangladesh where national programs prioritize cost per fully immunized child over reactogenicity concerns.
- DPT Acellular:Purified filamentous hemagglutinin, pertactin, and pertussis toxoid antigens reduce fever and injection-site reactions. European and North American pediatric schedules specify acellular-only procurement through EMA and FDA compliance pathways.
- Combination Vaccines:Pentavalent and hexavalent bundling with HepB and Hib antigens.
- Monovalent Vaccines:Single-antigen diphtheria, tetanus, or pertussis boosters for specialized indications.
Whole-cell leads on scale; combination vaccines lead on momentum.
Administration Route:
Route selection determines cold chain requirements, health worker training, and wastage rates across delivery settings.
- Intramuscular:Standard 0.5 mL deltoid or anterolateral thigh injection using 23-25 gauge needles. WHO immunization schedules specify intramuscular as the default for all DPT-containing products in routine and campaign settings.
- Subcutaneous:Alternative delivery for specific combination formulations where antigen stability permits.
- Intradermal:Microinjection techniques under evaluation for reduced antigen dosing.
- Oral:Not commercially available for DPT; experimental mucosal adjuvant research only.
Intramuscular dominates volume; intradermal shows steepest expansion trajectory in development pipelines.
End User:
Buyer type dictates pricing structure, contract duration, and technical service requirements from manufacturers.
- Public Immunization Programs:Government tenders through UNICEF, PAHO, and national procurement agencies. Multi-year supply agreements with price-volume mechanisms and stringent WHO prequalification requirements.
- Pediatric Clinics:Private practice purchases in urban India, Brazil, and Mexico where middle-class families opt for acellular or hexavalent alternatives.
- Travel Clinics:Tetanus-diphtheria boosters for pre-departure immunization.
- Military Health Services:Stockpiling requirements for force protection and deployment readiness.
Public programs lead on scale; travel clinics lead on margin per dose.
Packaging Type:
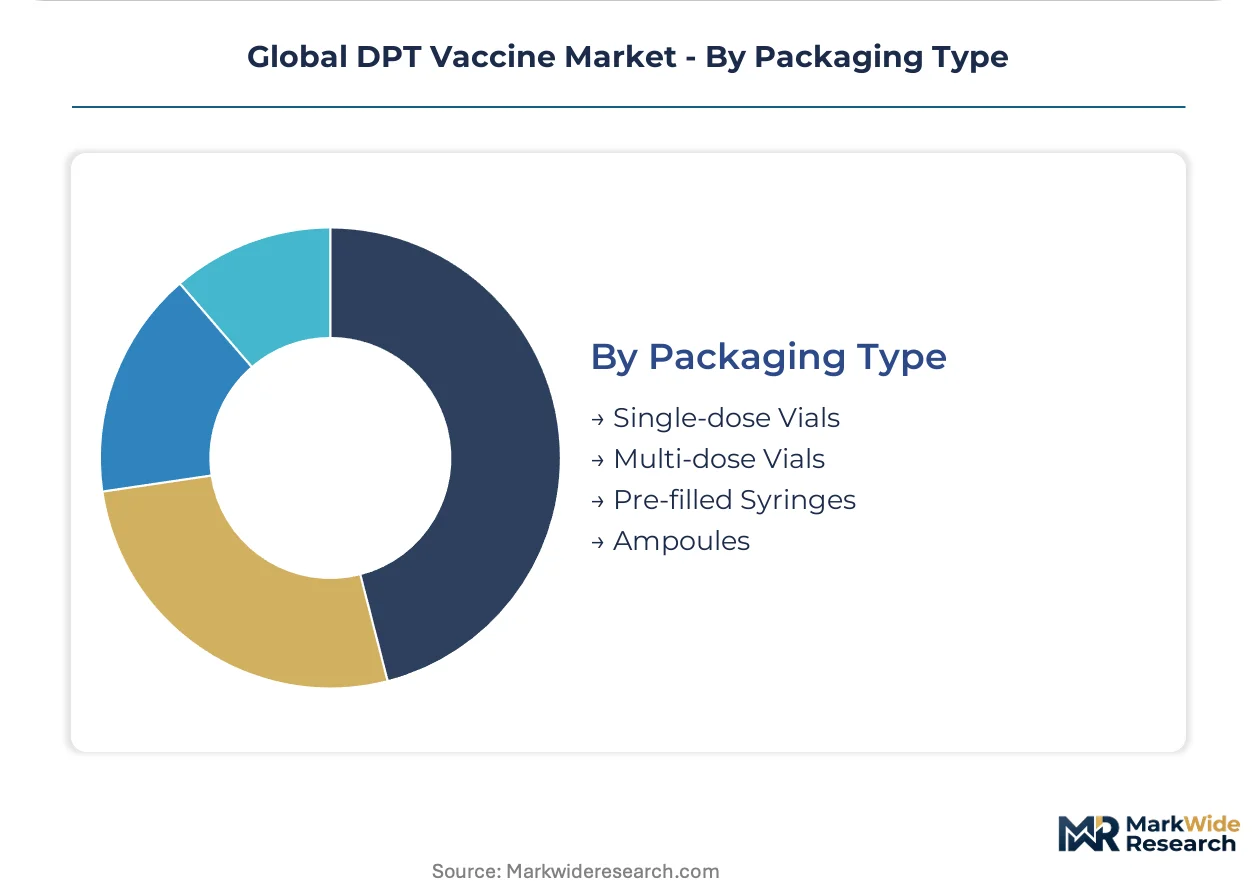
Format selection balances unit cost against wastage, cold chain footprint, and injection safety compliance.
- Pre-filled Syringes:Auto-disable syringes with integrated needles eliminate reconstitution errors and reduce open-vial wastage. Gaining share fastest in campaign settings where WHO injection safety mandates apply.
- Multi-dose Vials:10-dose and 20-dose presentations minimize per-dose packaging cost. Cold chain efficiency supports last-mile distribution in sub-Saharan African and South Asian health facilities.
- Single-dose Vials:Lyophilized or liquid presentations for private market premium positioning.
- Ampoules:Glass break-seal containers requiring syringe aspiration.
Multi-dose vials lead on scale; pre-filled syringes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DPT vaccine manufacturing originated in European pharmaceutical centers during the mid-twentieth century before migrating to high-volume production platforms in South Asia. Today's supply geography reflects this bifurcation between regulated-market innovators and cost-optimized public-sector suppliers.
United States
Pediatric immunization schedules drive steady demand for acellular combination products through CDC procurement channels. FDA maintains stringent potency and stability standards that limit supplier eligibility to established manufacturers with decades-long compliance histories. The Research Triangle Park cluster in North Carolina anchors domestic fill-finish capacity for combination vaccines distributed through the Vaccines for Children program.
India
UNICEF and Gavi tender volumes concentrate in Indian manufacturing facilities optimized for whole-cell pertussis production at sub-dollar per-dose economics. CDSCO enforces parallel WHO prequalification standards for export-bound production while streamlining domestic market authorization pathways. The Pune-Hyderabad corridor houses the world's largest DPT bulk antigen manufacturing complexes, with Serum Institute of India anchoring global supply for low-income country programs.
China
National immunization program expansion drives domestic demand for pentavalent combination products incorporating DPT-HepB-Hib antigens. NMPA implemented revised vaccine lot release procedures in 2019 that extended testing timelines but improved batch consistency surveillance. The Chengdu-Chongqing biopharmaceutical cluster specializes in bacterial vaccine fermentation capacity serving both domestic programs and Belt and Road export initiatives.
Brazil
Federal centralized procurement through the Ministry of Health's Programa Nacional de Imunizações consolidates previously fragmented state-level purchasing. ANVISA alignment with WHO prequalification standards enables domestic manufacturers to access PAHO revolving fund mechanisms for regional supply. The São Paulo-Rio de Janeiro axis concentrates fill-finish capacity for combination vaccines distributed throughout Latin American national programs.
Indonesia
Demographic expansion and domestic manufacturing investments create demand for localized DPT-containing combination supply as the national immunization program scales toward universal coverage. The national pharmaceutical regulator enforces stability testing requirements that parallel WHO standards for products entering the government tender system. The Jakarta-Bandung industrial corridor hosts emerging vaccine manufacturing infrastructure targeting self-sufficiency in routine immunization antigens.
Global DPT Vaccine Market Competitive Landscape
The competitive structure tilts toward vertically integrated multinational pharmaceutical groups with established prequalification status and cold-chain distribution networks. Three to four manufacturers capture the majority of UNICEF and Gavi tender volumes through multi-year supply agreements, while a broader tier of regional suppliers serves domestic public programs and private markets. Strategic archetypes include: (1) global innovators with hexavalent portfolios optimized for regulated markets, (2) emerging market volume leaders with cost-optimized whole-cell platforms, and (3) regional specialists leveraging geographic proximity for tender advantages. Dominant competitive moves center on combination vaccine portfolio expansion and manufacturing capacity additions in South and Southeast Asia.
Within the global innovator tier, Sanofi and GlaxoSmithKline occupy positions defined by decades of regulatory compliance in FDA and EMA jurisdictions. Serum Institute of India exemplifies the emerging market volume archetype, anchoring public-sector supply through UNICEF channels with manufacturing scale that few competitors can replicate. These three entities collectively represent the competitive poles around which procurement patterns in low-income, middle-income, and high-income country segments respectively organize.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Merck |
| Serum Institute of India |
| Pfizer |
| Johnson & Johnson |
| AJ Vaccines |
| Bionet-Asia |
| Biken |
| Others |
Supply & Pricing Matrix
UNICEF and Gavi centralized procurement programs concentrate buyer power and enforce cost-plus contracting that caps margins for whole-cell DPT suppliers while rewarding scale economies. This tender concentration forces manufacturers to optimize aluminum adjuvant sourcing and fermentation yields rather than pursue price premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates acellular hexavalent formulations for private pediatric clinics in Europe and North America from pentavalent public tenders in middle-income countries and whole-cell bulk supply for low-income national programs. Price differentiation hinges on WHO prequalification status and cold-chain certification tier, with FDA and EMA compliance commanding substantial premiums over CDSCO-aligned pathways. Cost compression in the economy tier is intensifying because Indonesian and Vietnamese domestic manufacturers are qualifying for UNICEF procurement. Public immunization programs exhibit highest price sensitivity; travel clinic boosters show lowest sensitivity due to convenience premiums.
Supply Chain Analysis
Single-source vulnerability sits with aluminum phosphate and hydroxide adjuvant production concentrated among specialized chemical suppliers in Germany, the United States, and India. Bulk antigen manufacturing draws from fermentation capacity in the Pune-Hyderabad corridor, with fill-finish operations distributed across Brazil, Indonesia, and South Africa. Tariff exposure on cold-chain equipment imports constrains last-mile distribution expansion in sub-Saharan Africa. Distribution runs through UNICEF's centralized purchasing mechanism and PAHO revolving fund channels, bypassing traditional pharmaceutical distributors for government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between Indian whole-cell platforms and European acellular facilities creates geographic positioning advantages for suppliers with dual-qualification capabilities. CDSCO streamlined pathways and WHO prequalification friction generate 18-24 month regulatory lag that rewards early entrants.
For Market Incumbents: Extend combination vaccine portfolios through pentavalent and hexavalent formulation investments to capture integrated tender awards before Indonesian domestic capacity matures. Defend against Serum Institute of India's volume dominance by securing multi-year price-volume agreements with Brazilian and Nigerian federal procurement agencies. Prioritize fill-finish automation engineering to reduce batch failure rates and compress facility turnaround times.
For New Entrants and Emerging Players: Launch via direct negotiation with UNICEF's vaccine independence initiative, bypassing distributor intermediaries that incumbent relationships have locked. Target Indonesia's national immunization scale-up as the most penetrable geography, where demographic expansion outpaces domestic manufacturing capacity. Position around micro-array patch delivery technology to eliminate cold-chain dependence and differentiate from injectable formulations.
For Investors and Strategic Acquirers: Pharmaceutical conglomerates with established prequalification status are the most active acquirer in this space, seeking volume anchors for combination vaccine portfolios. Long-term viability hinges on manufacturing scale and regulatory compliance databases that shorten WHO prequalification timelines. Watch acellular pertussis antigen yield constraints as the inflection indicator for capacity expansion feasibility and margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | CDSCO and NMPA alignment with WHO standards unlocks UNICEF and Gavi procurement channels for emerging market manufacturers. |
| Combination Vaccine Portfolio Expansion | Pentavalent and hexavalent bundling reduces injection burden and captures integrated tender awards from national immunization programs. |
| Cold Chain Infrastructure Partnership | Solar direct-drive refrigeration deployment with sub-Saharan African ministries extends reach to last-mile health facilities. |
| Fill-Finish Automation Engineering | Specialized aseptic processing expertise for combination vaccines constrains capacity expansion at existing facilities. |
| Micro-Array Patch Delivery Development | Dissolvable microneedle technology eliminates cold chain dependence and enables community health worker administration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine manufacturing executives, regulatory affairs leads at CDSCO and ANVISA, UNICEF procurement officers, and hospital formulary directors with secondary validation against FDA filings, EMA submissions, WHO prequalification lists, and Gavi disbursement records. Bottom-up volume modeling from national immunization program coverage targets and top-down value triangulation from tender award disclosures were cross-referenced for convergence.
Segment-weighting applied product type, administration route, end user category, and packaging format dimensions across the analysis window, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from trend extrapolation of historical tender volumes and coverage expansion targets, incorporating aluminum adjuvant supply constraints and prequalification timeline friction as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under WHO prequalification backlog accumulation or sudden acellular pertussis antigen yield deterioration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market