
 Theophylline and Aminophylline Market | 2026-2036
Theophylline and Aminophylline Market Size, Share, and Industry Trends Forecast 2026-2036
Theophylline and Aminophylline Market Analytics
Market Context with Strategic Players
Project finance for active pharmaceutical ingredient facilities is tilting competitive advantage toward manufacturers with captive fermentation capacity. Pfizer Inc. leverages its integrated supply chain for theophylline precursors. Teva Pharmaceutical Industries Ltd anchors its position through vertical control over raw material sourcing. Cipla Ltd. specializes in high-volume oral dosage exports to regulated markets.
Technical Definition and Structural Segments
Theophylline and aminophylline are methylxanthine bronchodilators; theophylline occurs as a white crystalline powder with the molecular formula C₇H₈N₄O₂, while aminophylline combines theophylline with ethylenediamine to enhance aqueous solubility for intravenous administration. Both compounds function primarily as phosphodiesterase inhibitors that relax smooth muscle in the airways and pulmonary blood vessels. Extended-release oral formulations command the dominant share of value across product type segments due to their therapeutic convenience and compliance advantages in chronic asthma management. Hospital-based intravenous delivery retains critical importance in acute exacerbation settings, while homecare channels are gaining traction for maintenance therapy among stable COPD patients.
Regulatory Framework and Forward Outlook
FDA bioequivalence requirements for generic theophylline products shape formulation development timelines and ANDA approval pathways in the United States. India's CDSCO enforces phased manufacturing standards under Schedule M that govern domestic production and export eligibility for contract manufacturers. EMA stability testing guidelines for methylxanthine derivatives influence batch release protocols across European supply chains. Stakeholders must monitor evolving pharmacovigilance obligations for narrow-therapeutic-index drugs as regulators tighten post-market surveillance requirements.
Market Dynamics
Hospital procurement of extended-release theophylline formulations is compressing supplier margins while elevating quality certification requirements, forcing manufacturers to recalibrate production economics around narrow-therapeutic-index compliance.
Growth Catalysts
- CDSCO Schedule M enforcement:India's phased manufacturing standards are elevating export eligibility for contract API producers serving regulated markets.
- Homecare maintenance therapy:Stable COPD patients are transitioning from hospital-based nebulization to oral extended-release regimens.
- FDA bioequivalence tightening:Stricter ANDA approval pathways for generic bronchodilators are filtering out substandard formulation competitors.
Market Restraints
- Ethylenediamine supply volatility:Aminophylline production faces input cost pressure from concentrated petrochemical feedstock suppliers.
- Narrow therapeutic index:Theophylline's 10-20 mcg/mL blood concentration window necessitates costly therapeutic drug monitoring infrastructure.
- Inhaled corticosteroid substitution:Long-acting beta-agonist combination therapies are displacing methylxanthine first-line status in pediatric asthma protocols.
Strategic Opportunities
- EMA stability testing alignment:Batch release protocol harmonization opens European supply chain integration for Indian API manufacturers.
- Continuous manufacturing adoption:FDA's emerging quality-by-design framework rewards real-time release testing for extended-release tablet production.
- Veterinary bronchodilator applications:Equine recurrent airway obstruction therapy represents an underpenetrated prescription channel.
Industry Challenges
- Analytical method transfer complexity:Bioequivalence study protocol adaptation across CRO networks delays generic filing timelines.
- Phosphodiesterase-4 inhibitor patent cliffs:Roflumilast generic entry is fragmenting chronic obstructive pulmonary disease maintenance therapy market share.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Theophylline and Aminophylline Market |
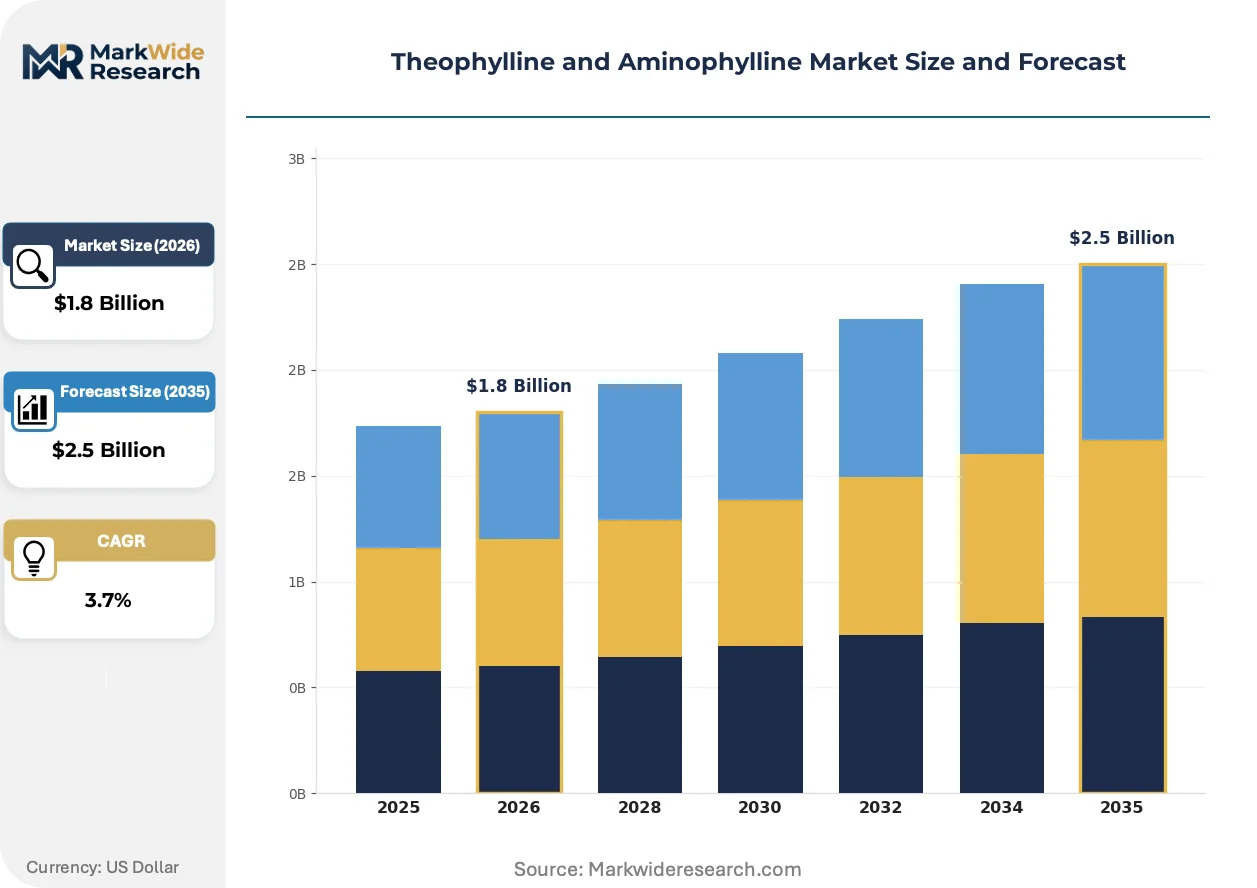
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Theophylline, Aminophylline, Extended Release, Injectable Therapy Area: Asthma, COPD, Pulmonary Disease, Allergic Rhinitis Delivery Mode: Oral, IV, Inhalation, Sublingual End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Sandoz AG, GlaxoSmithKline plc, Pfizer Inc., Dr. Reddy's Laboratories, AstraZeneca plc, Teva Pharmaceutical Industries Ltd, Cipla Ltd., Merck KGaA, Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Theophylline and Aminophylline Market Evolving Landscape
Formulation science is converging with regulatory science to redefine manufacturing economics, while procurement patterns in acute care settings are compressing traditional distribution hierarchies.
Hot-melt extrusion technology is hybridizing with conventional wet granulation for theophylline extended-release matrices. European contract manufacturers are retrofitting legacy solid-dose lines to accommodate thermoplastic polymer carriers. This convergence is hybridizing quality control protocols, forcing simultaneous validation of dissolution and thermal stability endpoints.
EMA's revised guideline on clinical investigation of medicinal products in the treatment of asthma is elevating exacerbation reduction as a primary endpoint. Phase III trial designs must now incorporate biomarker stratification, extending development timelines for novel methylxanthine derivatives. Pediatric indication expansions face the steepest compliance burden under this framework.
Hospital pharmacy consortia are consolidating theophylline tender awards around single-source extended-release suppliers. Group purchasing organizations are unbundling intravenous aminophylline from maintenance oral contracts, fragmenting vendor relationships. This concentration is most visible in United States academic medical centers with captive specialty pharmacy networks.
Theophylline and Aminophylline Market Segmentation
Methylxanthine bronchodilators serve distinct therapeutic protocols requiring formulation-specific manufacturing investments. Each segment demands tailored bioequivalence documentation and narrow-therapeutic-index compliance infrastructure.
Product Type:
After-sales service intensity varies sharply across formulation categories, with extended-release tablets requiring pharmacovigilance support and injectable lines demanding batch-specific stability counseling.
- Theophylline:Anhydrous base compound formulated as immediate-release tablets or oral solutions for chronic asthma maintenance. Demand concentrates in United States hospital formularies where therapeutic drug monitoring protocols are institutionalized; generic substitution pressures force manufacturers to maintain dedicated pharmacokinetic hotlines.
- Aminophylline:Theophylline-ethylenediamine complex providing enhanced aqueous solubility for parenteral administration. Indian contract manufacturers supply bulk API to European infusion bag compounders; ethylenediamine feedstock volatility necessitates long-term supply agreements with petrochemical intermediaries.
- Extended Release:Matrix-formulation tablets using hydroxypropyl methylcellulose or acrylic resin systems for 12-24 hour dosing intervals.
- Injectable:Sterile solution formulations for emergency department acute exacerbation management.
Extended Release holds the largest share; momentum sits with Injectable formulations in acute care consolidation.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute rescue protocols, with COPD commanding premium pricing for combination therapy positioning.
- Asthma:Chronic inflammatory airway disease requiring long-term bronchodilator prophylaxis. Pediatric allergists in Germany prescribe extended-release theophylline as third-line controller therapy; EMA pediatric investigation plan requirements extend development timelines for novel formulations.
- COPD:Progressive obstructive pathology with emphysematous and chronic bronchitic phenotypes. Homecare channels in Japan favor oral methylxanthines over nebulized alternatives for stable patients; reimbursement coding distinguishes maintenance from exacerbation therapy.
- Pulmonary Disease:Broader category encompassing interstitial lung disorders and pulmonary hypertension with bronchospastic components.
- Allergic Rhinitis:Upper airway inflammation with lower airway reactive overlap requiring decongestant-sparing approaches.
COPD holds the largest share; momentum sits with Asthma as biologic-sparing protocols gain traction.
Delivery Mode:
Application-specific bioavailability requirements dictate manufacturing site certification levels, with intravenous lines requiring aseptic processing investments that oral solid dose facilities cannot readily absorb.
- Oral:Tablet and liquid formulations for outpatient chronic therapy. United States Medicare Part D plans favor extended-release theophylline over immediate-release for adherence metrics; FDA bioequivalence studies must demonstrate comparable AUC profiles across fed and fasted states.
- IV:Intravenous infusion for hospitalized acute exacerbations. United Kingdom NHS hospital pharmacy consortia tender aminophylline ampoules through single-source agreements; batch release requires endotoxin testing per European Pharmacopoeia standards.
- Inhalation:Nebulized solutions for rapid bronchodilation in emergency settings.
- Sublingual:Rapid-dissolve formulations for patients with swallowing difficulties or NPO status.
Oral holds the largest share; momentum sits with IV as hospital consolidation elevates critical care procurement.
End User:
Customer type determines regulatory documentation burden, with hospital purchasers demanding FDA establishment inspection reports that retail pharmacies rarely require.
- Hospitals:Integrated health systems with captive specialty pharmacy networks. Academic medical centers in the United States unbundle intravenous aminophylline from oral maintenance contracts; group purchasing organizations impose narrow-therapeutic-index drug handling certification on vendors.
- Clinics:Outpatient pulmonary and allergy practices with limited formulary autonomy. Indian polyclinics prescribe generic theophylline for price-sensitive asthma patients; CDSCO Schedule M compliance determines supplier eligibility.
- Pharmacies:Community and mail-order dispensers with generic substitution protocols.
- Homecare:Durable medical equipment suppliers and visiting nurse services for stable COPD patients.
Hospitals hold the largest share; momentum sits with Homecare as remote patient monitoring expands maintenance therapy reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phased manufacturing standards and bioequivalence tightening are redrawing competitive boundaries across national supply chains. Hospital procurement consolidation and API export eligibility requirements are accelerating facility upgrades in key production centers.
United States
Academic medical centers in Boston and New York are unbundling intravenous aminophylline from oral maintenance contracts through group purchasing organizations. FDA bioequivalence standards for generic bronchodilators are forcing ANDA applicants to demonstrate fed-state and fasted-state pharmacokinetic equivalence. The Research Triangle Park cluster in North Carolina anchors clinical trial infrastructure for narrow-therapeutic-index drug development.
Germany
Pediatric allergists in Munich and Hamburg prescribe extended-release theophylline as third-line controller therapy for asthma patients. EMA stability testing guidelines for methylxanthine derivatives govern batch release protocols across Bavarian and Baden-Württemberg manufacturing sites. Frankfurt's pharmaceutical logistics hub coordinates temperature-controlled distribution for ethylenediamine-containing formulations.
India
Contract manufacturers in Hyderabad and Ahmedabad supply active pharmaceutical ingredients to European infusion bag compounders. CDSCO Schedule M enforcement is elevating export eligibility for API producers serving regulated markets. The Baddi-Barotiwala-Nalagarh belt in Himachal Pradesh concentrates oral solid dose capacity for high-volume theophylline exports.
Japan
Homecare channels in Tokyo and Osaka favor oral methylxanthines over nebulized alternatives for stable COPD patients. PMDA post-market surveillance requirements for narrow-therapeutic-index drugs mandate therapeutic drug monitoring infrastructure. The Kansai pharmaceutical corridor anchors extended-release formulation development for maintenance therapy regimens.
United Kingdom
NHS hospital pharmacy consortia tender aminophylline ampoules through single-source agreements in London and Manchester. European Pharmacopoeia endotoxin testing standards apply to batch release for intravenous formulations. The Cambridge life sciences cluster supports bioequivalence study protocol adaptation across contract research organizations.
Theophylline and Aminophylline Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers. Hospital procurement consolidation favors suppliers with integrated quality certification and pharmacovigilance infrastructure. The vendor base clusters around three strategic archetypes: multinational integrated pharmaceutical companies, regional generic specialists with API backward integration, and contract manufacturers with captive fermentation capacity. Dominant competitive moves include geographic expansion into veterinary bronchodilator applications and technology licensing for continuous manufacturing adoption.
Among multinational integrated players, Pfizer Inc. and GlaxoSmithKline plc occupy positions defined by supply chain control over theophylline precursors and hospital formulary relationships. Teva Pharmaceutical Industries Ltd exemplifies the regional generic specialist archetype through its vertical positioning in raw material sourcing. Indian contract manufacturers including Dr. Reddy's Laboratories and Cipla Ltd. represent the high-volume export-oriented tier serving regulated markets with Schedule M-compliant facilities.
| Leading Market Players |
|---|
| Sandoz AG |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Dr. Reddy's Laboratories |
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd |
| Cipla Ltd. |
| Merck KGaA |
| Hikma Pharmaceuticals PLC |
| Others |
Value Network & Pricing Analysis
The Baddi-Barotiwala-Nalagarh belt in Himachal Pradesh anchors global theophylline tablet capacity, and its Schedule M compliance upgrade trajectory directly shapes pricing power for export-grade formulations. Contract manufacturers with captive fermentation infrastructure command premium positioning against commodity API traders serving domestic Indian polyclinics.
Pricing Analysis
Certification level creates the primary spread across the value chain. FDA establishment inspection status and EMA GMP compliance separate premium-tier suppliers from standard-grade competitors in contract manufacturing. Pricing pressure stems from hospital pharmacy consortia unbundling intravenous aminophylline from oral maintenance contracts, compressing margins on sterile formulations. Pediatric allergists in Germany exhibit lowest price sensitivity due to narrow-therapeutic-index handling requirements, while Indian polyclinics drive aggressive generic substitution.
Supply Chain Analysis
Dr. Reddy's Laboratories, Cipla Ltd., and Teva Pharmaceutical Industries Ltd. hold dominant contract manufacturing capacity for methylxanthine APIs and finished dosages. Supply concentrates in India, the United States, and Germany, with Hyderabad and Ahmedabad clusters feeding European infusion bag compounders. Ethylenediamine feedstock draws from concentrated petrochemical intermediaries, creating single-source vulnerability for aminophylline production. Distribution runs through hospital group purchasing organizations in acute care and mail-order pharmacies for maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as homecare maintenance therapy displaces hospital-based nebulization, creating niche entry points for specialized oral formulation suppliers.
For Market Incumbents: Harden pharmacovigilance infrastructure around narrow-therapeutic-index compliance to defend against inhaled corticosteroid substitution in pediatric asthma protocols. Secure backward integration into theophylline precursor fermentation to offset ethylenediamine supply volatility. Anchor formulary position through therapeutic drug monitoring hotline services that generic substitutes cannot replicate. For New Entrants and Emerging Players: Veterinary bronchodilator applications for equine recurrent airway obstruction represent the most penetrable entry point, with limited incumbent specialization and prescription channel concentration. Target Japanese homecare channels for stable COPD oral maintenance therapy, where PMDA post-market surveillance requirements filter out undercapitalized competitors. Pursue technology licensing for continuous manufacturing adoption to qualify for FDA quality-by-design incentives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with Schedule M-compliant facilities and established European Pharmacopoeia batch release protocols. Long-term viability rests on API export eligibility to regulated markets rather than domestic volume scale. Watch EMA stability testing guideline revisions as inflection signal for European supply chain integration windows.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA quality-by-design framework rewards real-time release testing for extended-release tablet production. |
| EMA Stability Testing Alignment | Batch release protocol harmonization opens European supply chain integration for Indian API manufacturers. |
| Veterinary Bronchodilator Expansion | Equine recurrent airway obstruction therapy represents underpenetrated prescription channel with limited competition. |
| Homecare Channel Development | Remote patient monitoring infrastructure expands maintenance therapy reach for stable COPD patients. |
| Therapeutic Drug Monitoring Infrastructure | Narrow-therapeutic-index compliance creates service-based differentiation against commodity generic substitutes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ANDA filings, EMA submission databases, CDSCO manufacturing facility inspections, and hospital procurement contract records. Interviews with regulatory affairs leads, hospital formulary directors, contract manufacturing executives, and GPO contracts managers informed supply-side and demand-side dynamics. Bottom-up volume modeling triangulates against top-down value estimates across the projection horizon.
Forecast inputs include treatment line stratification, dosage form complexity, administration route infrastructure requirements, and regional regulatory cluster alignment. CAGRs derive from segment-level growth rate aggregation and cross-validation against historical methylxanthine prescription volume trajectories. The analytical framework incorporates therapeutic drug monitoring protocol penetration and bioequivalence study completion timelines as industry-specific forecast inputs.
Stress conditions across ethylenediamine feedstock price bands, FDA bioequivalence approval timelines, and inhaled corticosteroid substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding CDSCO Schedule M enforcement cadence and EMA guideline revision trajectories. Quarterly review of hospital pharmacy consortia tender awards and ANDA approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Skin Cancer Drugs Market