
 Global Circuit Protection Market | 2026-2036
Global Circuit Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Circuit Protection Market Intelligence
Customized system integration and design services for complex industrial applications is fragmenting the traditional component-centric business model. Schneider Electric SE leverages its digital platforms to capture value from integrated solutions. In parallel, Eaton Corporation plc sustains a strong position in mature circuit breaker and fuse segments through its extensive distribution network, while ABB Ltd. specializes in high-voltage applications for utilities.
Circuit protection encompasses devices engineered to interrupt fault currents like overloads or short circuits, preventing equipment damage and fire hazards. These components, such as fuses with specific amperage ratings, ensure operational safety in electrical systems. The solid state technology segment represents the fastest-growing, displacing electromechanical relays in sensitive applications like data centers. While circuit breakers command a large value share, fuses remain prevalent in residential and commercial buildings due to cost-effectiveness.
Product design is governed by standards from the International Electrotechnical Commission (IEC), which set global safety benchmarks. Regional mandates, including the EU's RoHS directive and UL standards in the United States, further influence material composition and market access. Stakeholder success depends on adapting product portfolios to meet rising cybersecurity and smart grid integration requirements.
Market Dynamics
The fundamental dynamic shaping the circuit protection market is the escalating power density and sensitivity of modern electronics. This requires a transition from slower, passive electromechanical devices to faster, intelligent solid-state systems capable of protecting critical infrastructure like data centers and renewable energy grids.
Growth Catalysts
- Smart Grid Modernization:Government-led initiatives to build intelligent power grids necessitate advanced circuit protection devices with communication capabilities for real-time monitoring and control, especially in markets undertaking significant grid upgrades like India and China.
- Electric Vehicle Infrastructure:The global expansion of EV charging stations creates a substantial new demand category for robust circuit breakers and surge protection devices designed to handle high-power, direct current charging cycles safely.
- Solid-State Technology Adoption:The inherent speed and reliability of solid-state relays and circuit breakers are driving their adoption in mission-critical applications such as telecommunications, aerospace, and automated manufacturing where downtime is unacceptable.
Market Restraints
- Raw Material Price Volatility:Price fluctuations in key conductive materials, particularly copper and silver, directly impact component manufacturing costs and create margin pressure for fuse and circuit breaker producers.
- High Cost of Retrofitting:Upgrading legacy industrial and commercial buildings with modern, smart circuit protection systems involves significant capital expenditure and operational disruption, slowing adoption in established facilities.
- Technical Miniaturization Limits:As electronic devices become smaller, designing effective thermal and overcurrent protection within shrinking physical footprints presents significant engineering and material science challenges, especially for high-power applications.
Strategic Opportunities
- Protection for Hydrogen Systems:The nascent hydrogen economy requires the development of specialized circuit protection solutions, including DC-rated breakers and fuses, that are certified for use in highly explosive environments.
- Integrated Cybersecurity Features:Embedding cybersecurity protocols directly into networked circuit protection devices creates a new value proposition, offering a unified defense against both electrical faults and malicious digital intrusions on critical infrastructure.
- Grid Expansion in Southeast Asia:Rapid industrialization and urbanization in countries like Vietnam and Indonesia create significant greenfield opportunities for a wide range of circuit protection components, from residential fuses to high-voltage utility switchgear.
Industry Challenges
- Engineering Talent Scarcity:A shortage of power electronics engineers with expertise in both high-voltage systems and digital control logic constrains the ability of firms to innovate and execute complex system integration projects.
- Complex Certification Pathways:Navigating the divergent and time-consuming certification requirements of bodies like the IEC, UL in the United States, and China's GB standards adds significant cost and delays to product launches.
- Legacy System Interoperability:Ensuring new intelligent protection devices can communicate and function reliably with older electromechanical components within a single electrical network remains a persistent and complex integration challenge for system designers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Circuit Protection Market |
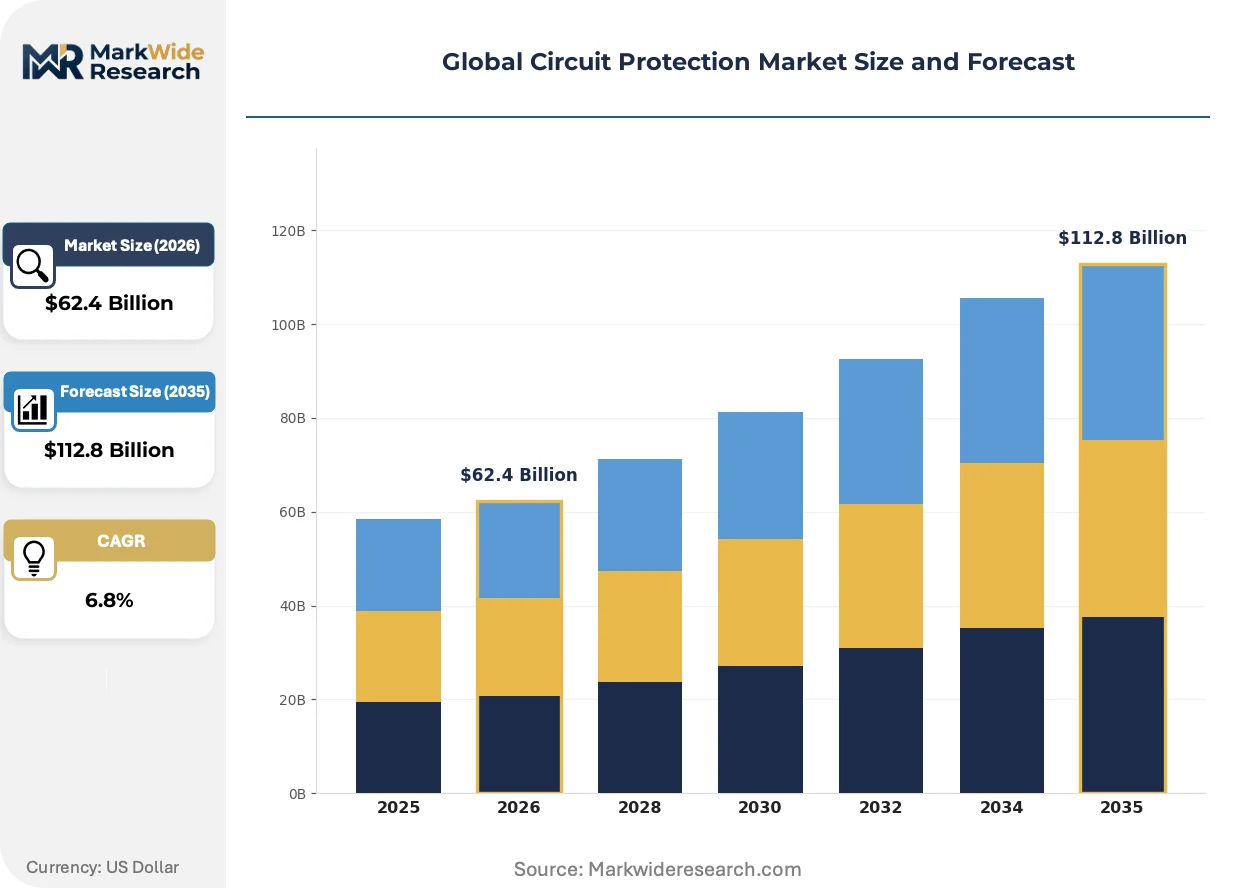
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Fuses, Relays, Surge Protectors, Thermal Protectors Technology: Electromechanical, Solid State, Thermal Magnetic, Hydraulic Magnetic, Hybrid Application: Residential, Commercial Buildings, Data Centers, Transportation Systems, Renewable Energy Facilities End User: Electric Utilities, OEM Manufacturers, Industrial Plants, Telecommunication Providers |
| Companies Covered | Siemens AG, Mitsubishi Electric Corporation, ABB Ltd., NXP Semiconductors N.V., Rockwell Automation Inc., Schneider Electric SE, General Electric Company, Bel Fuse Inc., Eaton Corporation plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Circuit Protection Market Strategic Shifts & Innovations
The evolution from passive safety components to active, intelligent grid management devices defines the market's trajectory. This shift is driven by the convergence of power electronics, digital communication, and demands for greater system resilience and efficiency across all end-use sectors.
Advanced solid-state circuit breakers utilize semiconductor technology like silicon carbide to interrupt fault currents in microseconds, far faster than traditional mechanical devices. Data centers and advanced manufacturing facilities are rapidly adopting these systems to protect sensitive servers and robotics. This technological shift is rendering obsolete slower electromechanical relays and molded case circuit breakers in applications where system uptime and equipment protection are paramount.
Regulatory frameworks promoting energy efficiency and grid stability are accelerating technology upgrades. The European Union's Green Deal, for instance, incentivizes investments in smart grids and renewable energy integration, which in turn require more sophisticated circuit protection. This policy most directly impacts the utility and industrial automation segments, which must invest in compliant hardware to meet new performance and reporting standards.
A notable behavioral change involves the move away from procuring discrete components toward sourcing pre-integrated protection modules. This trend disrupts traditional distributor-led sales channels, favoring system integrators and original equipment manufacturers who can deliver customized, pre-tested subsystems. This demand pattern is most pronounced in the industrial machinery and utility-scale solar energy sectors, where project complexity demands a more holistic approach to electrical safety.
Global Circuit Protection Market Segmentation
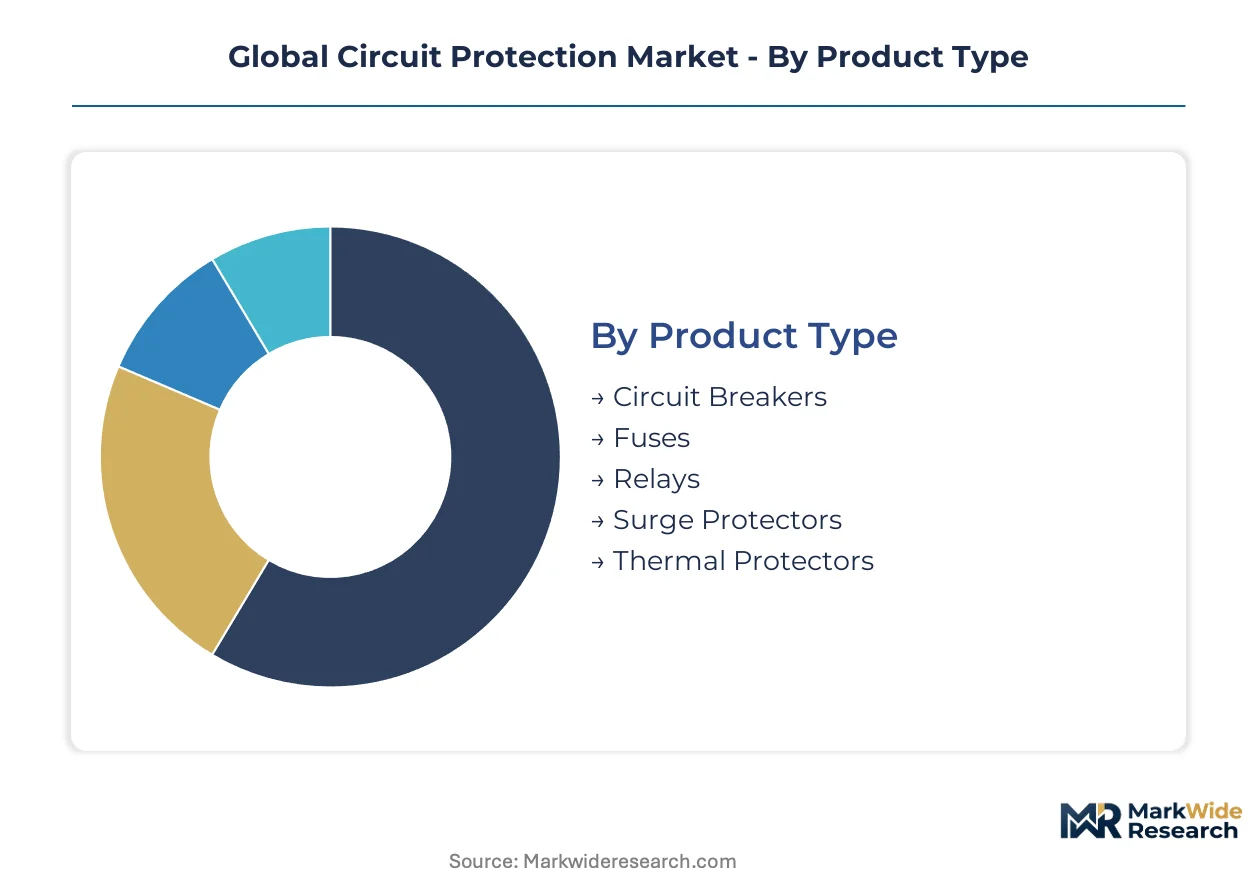
Circuit protection market segmentation reveals diverse product requirements driven by varying fault current magnitudes and operational environments. Understanding these distinctions helps manufacturers align product development with specific end-user needs and regulatory compliance.
Product Type:
The after-sales service intensity for circuit protection products varies significantly, reflecting their complexity and integration within electrical systems.
- Circuit Breakers:These electromechanical or solid-state devices automatically interrupt an electrical circuit during an overload or short circuit, protecting equipment and preventing hazards. Demand concentrates in industrial plants and utility infrastructure, driven by the need for robust, resettable protection in high-power systems.
- Fuses:Fuses contain a metal wire or strip that melts when excessive current flows through it, breaking the circuit and preventing damage. Their demand remains strong in residential and commercial buildings due to their cost-effectiveness and simplicity in protecting against overcurrents.
- Relays:These devices control an electrical circuit by opening or closing contacts, often used for switching high-power circuits with a low-power signal.
- Surge Protectors:Surge protectors divert excess voltage away from sensitive electronic equipment, safeguarding against transient power spikes.
- Thermal Protectors:These components respond to temperature changes, interrupting a circuit when overheating occurs to prevent equipment damage or fire.
By volume, Fuses lead. By growth pace, Circuit Breakers are ahead.
Technology:
Technology choices in circuit protection are fundamentally shaped by the application's sensitivity, speed requirements, and power density.
- Solid State:These advanced devices use semiconductor technology, like silicon carbide, to interrupt fault currents in microseconds, offering superior speed and reliability. Data centers and telecommunications facilities drive demand, requiring rapid response to protect sensitive electronics and ensure uptime.
- Electromechanical:Traditional electromechanical devices rely on mechanical movement to interrupt circuits, providing reliable protection but with slower response times compared to solid-state alternatives. Industrial plants and older infrastructure frequently employ these cost-effective solutions for general overcurrent protection.
- Thermal Magnetic:These circuit breakers combine thermal elements for overload protection and magnetic elements for short-circuit protection, commonly found in residential and commercial panels.
- Hydraulic Magnetic:Hydraulic magnetic breakers use a fluid-filled dashpot for time-delay characteristics, making them suitable for motor protection and other inductive loads.
- Hybrid:Hybrid circuit protection systems integrate both electromechanical and solid-state components, balancing cost, speed, and breaking capacity for specialized industrial applications.
Price differentiation across technologies reflects material costs and the complexity of integrated digital features.
Application:
Different applications dictate distinct circuit protection requirements, influencing product specification and certification pathways for various customer types.
- Data Centers:These facilities house critical computing infrastructure requiring ultra-fast and reliable circuit protection to prevent downtime and protect sensitive servers from power fluctuations. The escalating power density of modern electronics within these centers drives demand for advanced solid-state solutions.
- Renewable Energy Facilities:Solar farms and wind power installations demand specialized DC-rated circuit protection devices to manage high-power generation and grid integration. Regulatory incentives for clean energy across Europe and Asia accelerate deployment of these robust systems.
- Residential:Circuit protection in homes primarily involves fuses and circuit breakers designed for standard AC loads, ensuring safety from overloads and short circuits.
- Commercial Buildings:Office complexes and retail spaces utilize a mix of circuit breakers and surge protectors, balancing cost-effectiveness with enhanced safety for diverse electrical loads.
- Transportation Systems:Railways, electric vehicles, and maritime vessels require rugged, vibration-resistant circuit protection devices to ensure operational safety in dynamic environments.
Maturity levels vary significantly, with residential applications being highly established and renewable energy representing a rapidly expanding segment.
End User:
Margin structures within the circuit protection market are influenced by the technical demands and procurement volumes of distinct end-user segments.
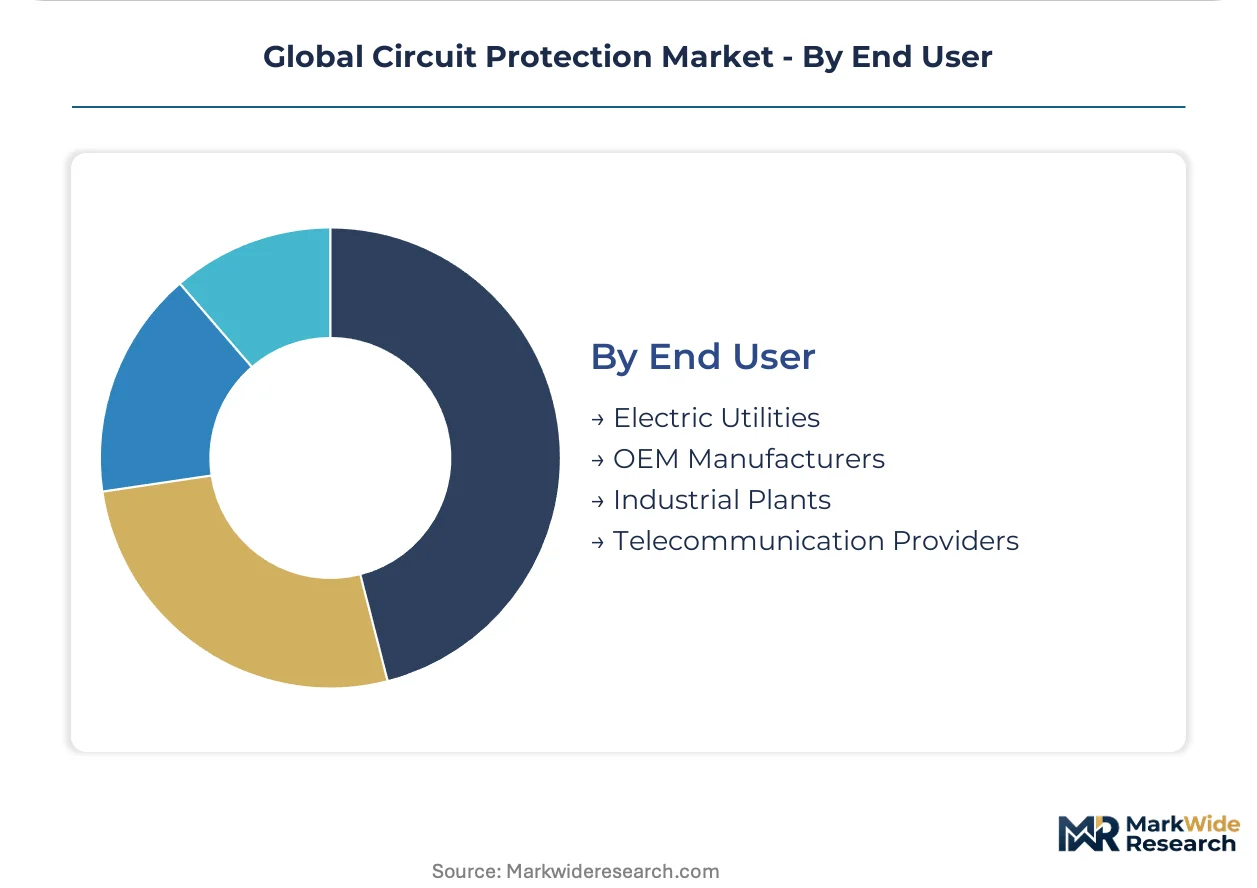
- Electric Utilities:These entities require high-voltage circuit breakers and advanced protection relays for grid infrastructure modernization and renewable energy integration. Government-led smart grid initiatives in India and China directly drive procurement for these critical components.
- OEM Manufacturers:Original Equipment Manufacturers integrate circuit protection components into their final products, such as industrial machinery, consumer electronics, and automotive systems. Their demand focuses on compact, cost-effective, and certified components for mass production.
- Industrial Plants:Factories and processing facilities use robust circuit breakers and fuses to protect heavy machinery and ensure continuous operation in demanding environments.
- Telecommunication Providers:These companies deploy specialized surge protection and fast-acting circuit breakers to safeguard sensitive network equipment from power disturbances.
Supply concentration is higher for utility-grade equipment, reflecting specialized manufacturing capabilities and stringent certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration for circuit protection components often reflects advanced manufacturing capabilities and significant infrastructure investments. China's extensive manufacturing sector and grid modernization initiatives drive substantial demand. This global market also sees robust activity across other key economies.
China
Demand in China stems from its extensive manufacturing sector and ongoing smart grid modernization initiatives. The country's GB standards dictate product specifications for electrical safety and market access. The Yangtze River Delta region, a hub for electronics manufacturing, experiences high demand for advanced circuit protection components.
United States
The United States market is driven by the expansion of data centers and the build-out of electric vehicle charging infrastructure. UL standards are critical for product certification and market entry for all electrical components. Silicon Valley and other technology clusters require sophisticated solid-state protection for sensitive computing equipment.
Germany
Germany's industrial automation sector and significant investments in renewable energy integration create strong demand for robust circuit protection. The EU Green Deal incentivizes technology upgrades in smart grids and industrial facilities. Bavaria, a center for advanced manufacturing, consistently requires high-performance protection for its machinery.
India
India's smart grid modernization programs and rapid industrialization are catalyzing demand for advanced circuit protection devices. The Central Electricity Authority (CEA) sets stringent guidelines for grid infrastructure and electrical safety. The Delhi-NCR region, with its growing industrial and commercial base, sees significant procurement of these critical components.
Vietnam
Rapid industrialization and urbanization in Vietnam are creating greenfield opportunities for a wide range of circuit protection components. The government's industrial policies support manufacturing expansion, which requires new electrical safety installations. Ho Chi Minh City, a major economic hub, drives demand for both residential and industrial protection solutions.
Global Circuit Protection Market Key Industry Players
Integrated solution providers and component-centric specialists split the market for circuit protection. The competitive structure features a tiered landscape, with large conglomerates offering broad portfolios alongside niche players focused on specific technologies. Strategic partnerships and targeted M&A activity are common competitive moves.
Global industrial conglomerates like Schneider Electric SE and ABB Ltd. exemplify the integrated solution provider archetype, leveraging their extensive digital platforms for complex industrial applications. Eaton Corporation plc sits within the component-centric segment, sustaining a strong position in mature circuit breaker and fuse markets through its broad distribution network.
| Leading Market Players |
|---|
| Siemens AG |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| NXP Semiconductors N.V. |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| General Electric Company |
| Bel Fuse Inc. |
| Eaton Corporation plc |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region, a hub for electronics manufacturing, significantly influences component availability and downstream pricing power in the global circuit protection market. Its high production capacity directly impacts cost structures for many device categories.
Pricing Analysis
IEC standards dictate the pricing tier structure for many circuit protection components, driving differentiation based on certification and performance. Pricing remains largely transactional per unit, with variations for customized solutions for industrial applications. Raw material price volatility, particularly for copper and silver, exerts significant margin pressure on fuse and circuit breaker producers. Residential consumers exhibit the highest price sensitivity, favoring cost-effective fuses, while data centers prioritize reliability and speed, accepting higher costs for solid-state devices.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, reflecting the capital intensity of component manufacturing and long procurement cycles for utility-grade equipment. Supply concentration centers on China, Germany, and the United States, reflecting specialized manufacturing capabilities. The market relies on key conductive materials like copper and silver, along with advanced semiconductors such as silicon carbide. Raw material price volatility poses a structural risk to consistent supply. Downstream distribution runs through system integrators and OEM manufacturers for complex, integrated solutions, while traditional distributors serve mature component segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global circuit protection market offers a compelling service-attach opportunity, with integrated system design and cybersecurity features expanding faster than hardware sales.
For Market Incumbents:
Build digital platform integration as a core moat, leveraging existing customer relationships for comprehensive solutions. Invest heavily in advanced R&D for silicon carbide-based solid-state devices, countering the threat of slower electromechanical technology displacement. Pursue strategic partnerships to enhance cybersecurity features within networked protection devices. Focus on certification investments to meet evolving standards like UL and IEC for new product categories.
For New Entrants and Emerging Players:
Establish a beachhead in specialized niches like protection for hydrogen systems, focusing on robust DC-rated breakers certified for explosive environments. Target greenfield opportunities in Southeast Asia's rapidly industrializing regions, offering comprehensive electrical safety installations for new factories. Develop a go-to-market strategy centered on rapid prototyping and specialized certification for high-power, sensitive applications like telecommunications infrastructure.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized solid-state component manufacturers with strong intellectual property in silicon carbide. Long-term viability rests on companies capable of integrating advanced digital features and cybersecurity into their core offerings for critical infrastructure. Identify acquisition targets that possess unique expertise in high-voltage DC protection or advanced sensor integration. The signal to watch is the accelerating adoption rate of silicon carbide devices in mission-critical data centers and renewable energy grids.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Expansion | Enhances value capture from integrated solutions and provides real-time monitoring capabilities for critical infrastructure. |
| Advanced Materials R&D | Accelerates development of faster, more reliable solid-state devices using silicon carbide for sensitive applications. |
| Specialized Certification Investment | Ensures market access and compliance for new applications like hydrogen systems and high-power EV charging infrastructure. |
| Strategic Acquisition of Solid-State Specialist | Gains access to cutting-edge semiconductor technology and engineering talent for next-generation protection devices. |
| Localized Manufacturing in Southeast Asia | Capitalizes on greenfield industrialization and urbanization opportunities, reducing logistics costs and improving regional responsiveness. |
Research Approach
A standing panel of power electronics engineers, utility procurement leads, data center architects, and OEM product managers provided ongoing calibration for market trends. This primary input was cross-referenced with secondary data from IEC standards, UL certifications, and government energy reports to ensure robust validation. The analysis employed both bottom-up and top-down triangulation to derive market sizing and growth projections.
Scenario-based modeling formed the analytical framework, projecting market evolution across the analysis window under various economic and technological assumptions. Segmentation dimensions included product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected shifts in end-use sector demand. Key forecast inputs included smart grid investment levels and electric vehicle infrastructure buildout.
Stress conditions across raw material price spikes and global trade policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Lowpass Filters Market
Electronic Components
Audio Transistors Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Breadboards Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Efuse Market