
 Multilayer Transparent Conductors Market | 2026-2036
Multilayer Transparent Conductors Market Size, Share, and Industry Trends Forecast 2026-2036
Multilayer Transparent Conductors Market Outlook
East Asian substrate producers is repositioning multilayer transparent conductor capacity toward flexible OLED-compatible formats. 3M Company leverages its polymer science heritage to dominate adhesive-integrated conductor stacks for automotive displays. Canatu Oy specializes in carbon nanobush films for curved touch surfaces, while Nitto Denko Corporation anchors supply of optically clear adhesives that bond conductor layers to cover glass.
Multilayer transparent conductors are laminated thin-film structures combining conductive oxides, metal grids, or nanomaterials with dielectric buffers, typically achieving sheet resistance below 100 ohms per square at visible-light transmission exceeding 85%. These structures enable simultaneous electrical conductivity and optical clarity in applications from foldable smartphones to building-integrated photovoltaics. Silver nanowires are capturing margin pools in flexible display applications where ITO fractures under bend stress, while sputtered ITO remains entrenched in rigid photovoltaic modules where process maturity outweighs material flexibility needs. Touch panels represent the largest volume application, though LED lighting is emerging as a cost-sensitive segment favoring printed conductor approaches.
FDA scrutiny of medical device touch interfaces is elevating electromagnetic shielding standards for hospital-grade displays, while EPA frameworks govern indium recovery from spent ITO sputtering targets in US manufacturing. REACH restrictions on indium compounds in Europe are redirecting R&D spending toward graphene and carbon nanotube alternatives with lower toxicity profiles. Stakeholders must monitor how EU Green Deal material passport requirements reshape supplier qualification timelines for multilayer conductor imports.
Market Dynamics
Touch panel manufacturers are accelerating procurement of silver nanowire alternatives as REACH compliance in Europe and stricter hazardous substance rules force substitution away from indium-tin oxide, while South Korea's display cluster concentrates demand around Samsung and LG supply chains.
Growth Catalysts
- EU REACH restrictions on indium compounds:Chemical safety frameworks are redirecting R&D spending toward graphene and carbon nanotube alternatives with lower toxicity profiles, expanding addressable markets for novel conductor architectures.
- Foldable smartphone display demand:Mechanical stress tolerance requirements are pulling silver nanowire networks into flexible OLED-compatible formats where sputtered ITO fractures under repeated bending cycles.
- South Korean cluster procurement:Samsung and LG supply chains are consolidating vendor qualification programs, creating volume anchors that amortize specialized coating equipment across multi-year contracts.
Market Restraints
- Indium supply concentration:Primary indium extraction ties to zinc mining operations in China, creating price volatility exposure for ITO-dependent manufacturers without backward integration into raw material streams.
- Sputtering equipment capex intensity:Vacuum deposition systems for oxide conductors require cleanroom infrastructure and target recycling protocols that lock smaller entrants out of cost-competitive production.
- Silver nanowire oxidation sensitivity:Atmospheric degradation of metallic nanostructures necessitates barrier film encapsulation, adding processing steps that compress margins in cost-sensitive LED lighting segments.
Strategic Opportunities
- Building-integrated photovoltaics:Architectural glass manufacturers are specifying multilayer conductor stacks for semi-transparent solar facades, opening volume channels outside consumer electronics procurement cycles.
- EU Green Deal material passports:Supplier qualification timelines for multilayer conductor imports are reshaping toward documented circularity credentials, favoring early adopters of closed-loop indium recovery.
- Automotive display integration:Curved dashboard surfaces and head-up projection systems are creating specifications for conformable conductor films that tolerate thermal cycling across vehicle lifespans.
Industry Challenges
- Cleanroom operator scarcity:Thin-film lamination processes require technicians trained in particle-controlled environments, with talent pipelines concentrated around established semiconductor manufacturing regions.
- Cross-layer optical matching:Refractive index engineering between dielectric buffers and conductive layers demands computational modeling capabilities that smaller converters license from specialized software vendors.
- FDA electromagnetic shielding certification:Hospital-grade display interfaces face extended validation timelines for medical device touch integration, compressing product launch windows against consumer electronics refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multilayer Transparent Conductors Market |
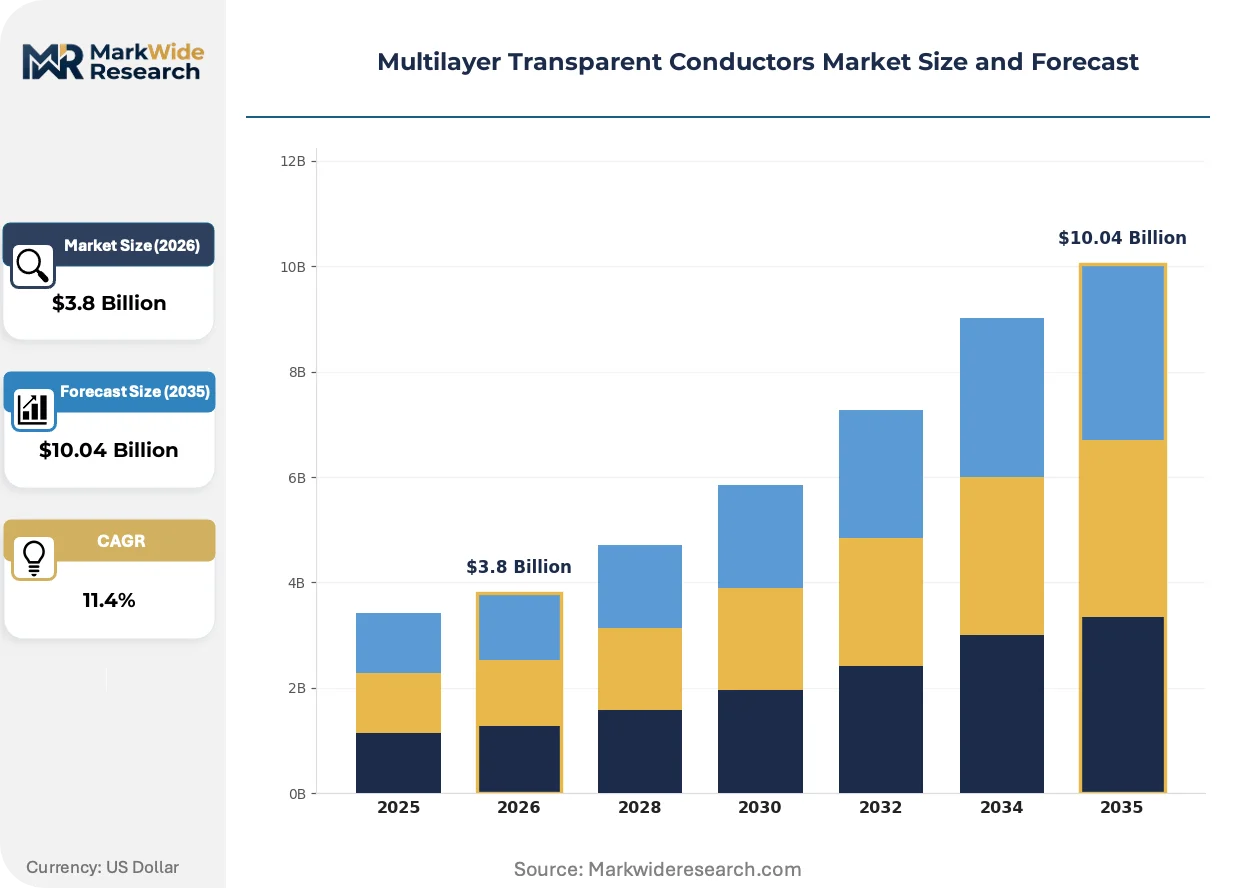
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
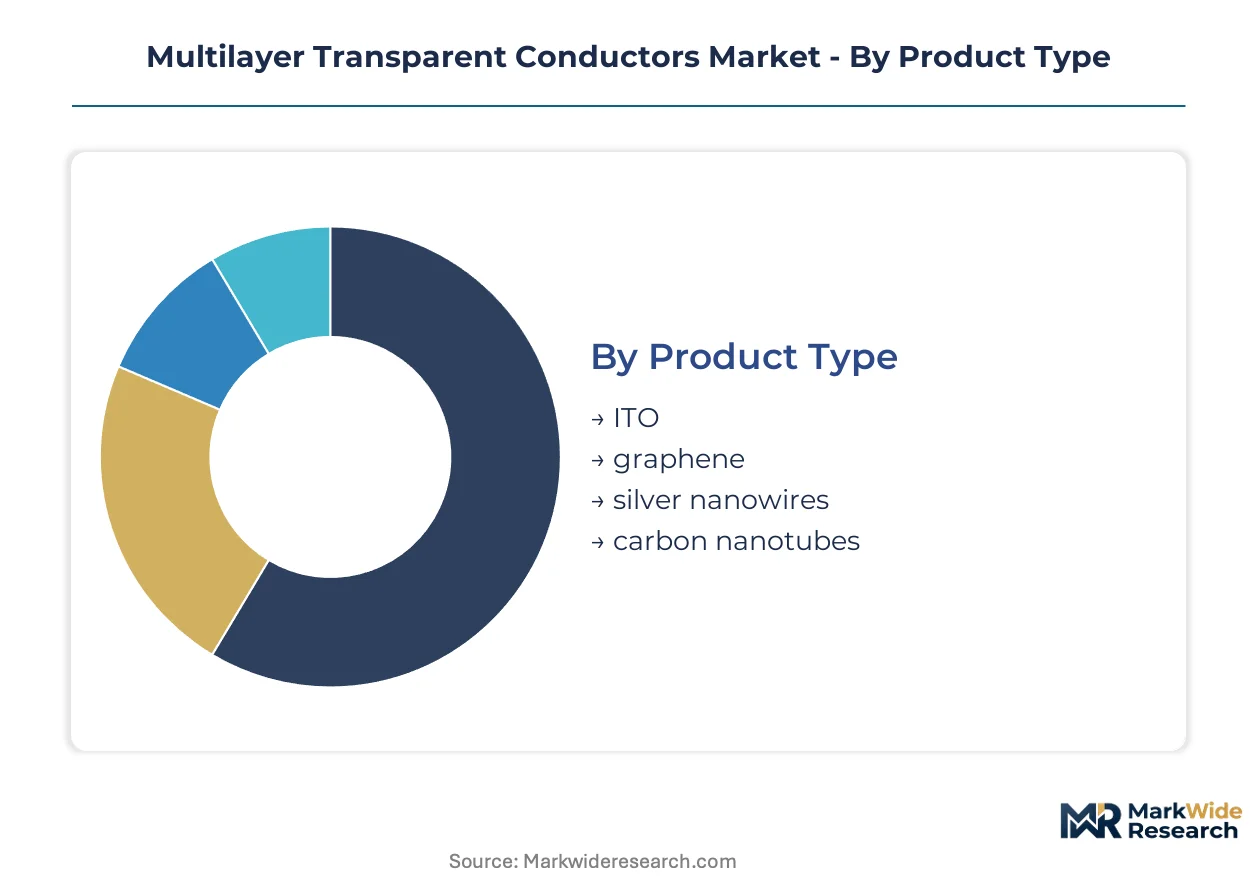
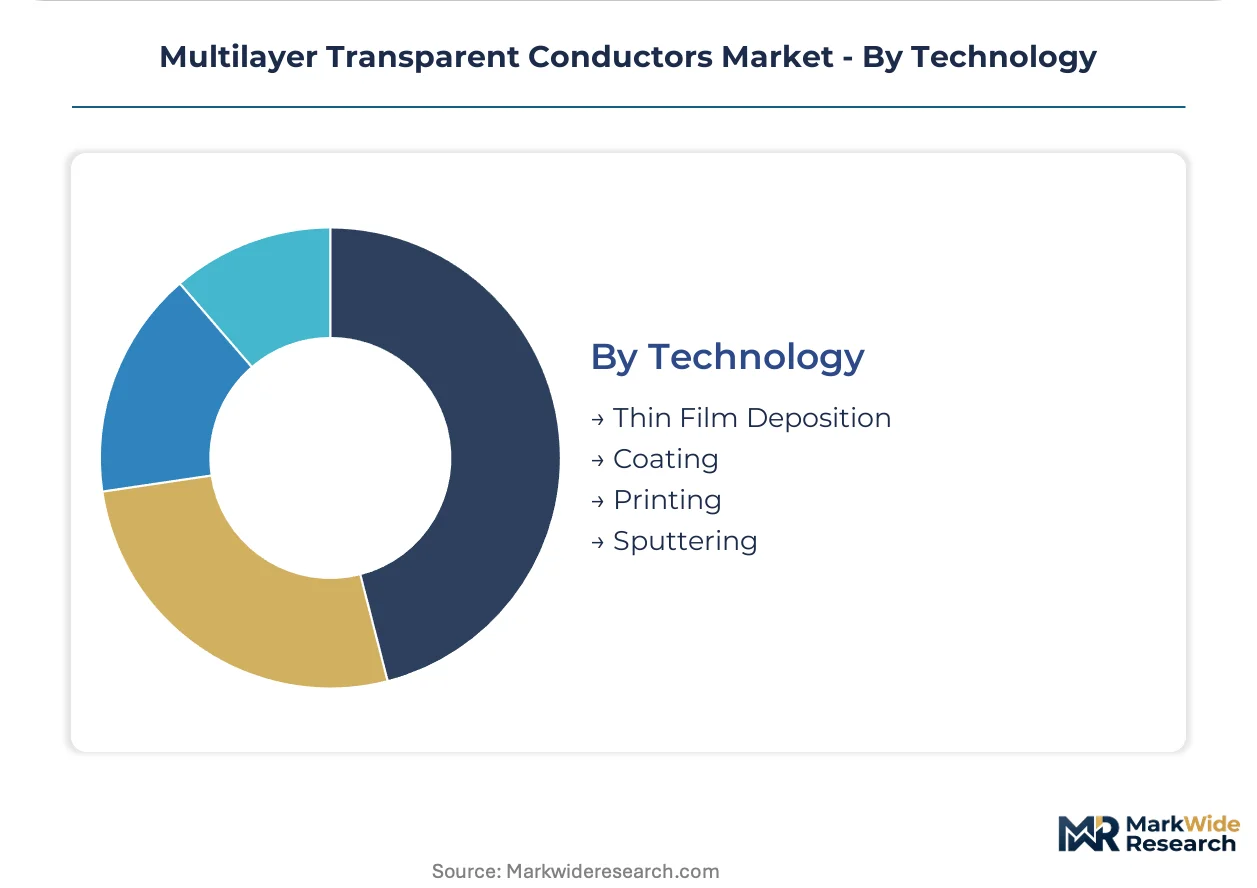
| Segmentation | Product Type: ITO, graphene, silver nanowires, carbon nanotubes Application: Displays, photovoltaics, touch panels, LED lighting End User: Consumer Electronics, Automotive, Solar Power, Aerospace Technology: Thin Film Deposition, Coating, Printing, Sputtering |
| Companies Covered | 3M Company, Canatu Oy, Nitto Denko Corporation, DuPont Teijin Films, Toyobo Corporation, Fujifilm Holdings Corporation, Dontech Inc, Thin Film Devices Inc., C3Nano Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multilayer Transparent Conductors Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to restructure how transparent conductor layers are specified, laminated, and recovered across electronics and energy applications.
Silver nanowire networks are modularizing conductor deposition into roll-to-roll compatible processes that bypass vacuum sputtering infrastructure. Automotive tier-one suppliers are qualifying these films for curved center-stack displays at accelerated timelines compared to traditional ITO glass. This modularization is compressing capital barriers for mid-scale converters entering the automotive supply chain.
REACH restrictions on indium compounds are forcing formulation changes across European manufacturing footprints. ECHA substance evaluation protocols are extending safety data sheet requirements for sputtering target suppliers, elevating documentation burdens for importers. Display module assemblers in Germany and the Netherlands are diversifying qualified material sources toward carbon-based alternatives to preempt authorization delays.
Buyer consolidation around South Korean display clusters is concentrating procurement leverage among a narrowing vendor base. Specification-setting power has migrated from substrate producers to integrated panel manufacturers with captive optical design capabilities. Taiwan-based touch sensor suppliers are responding by deepening technical service relationships with secondary smartphone brands outside the Samsung-LG orbit.
Multilayer Transparent Conductors Market Segmentation
Material selection in multilayer transparent conductors hinges on balancing optical transmission targets against mechanical flexibility requirements. Each segmentation dimension reveals distinct procurement patterns across rigid versus conformable application environments.
Product Type:
Customization intensity varies sharply across this category, from commodity sputtered oxides to bespoke nanomaterial formulations requiring application-specific stabilization chemistry.
- ITO:Sputtered indium-tin oxide dominates rigid display modules with sheet resistance below 50 ohms per square at 90% visible transmission. Procurement concentrates in South Korean panel fabs where Samsung and LG supply chains amortize vacuum deposition equipment across multi-year contracts. REACH restrictions on indium compounds are accelerating substitution timelines in European manufacturing footprints.
- Silver nanowires:Randomly oriented metallic nanowire networks achieve comparable conductivity to ITO at superior bend radii below 3mm. Demand clusters in flexible OLED touch stacks where mechanical stress tolerance outweighs material cost premiums. Nitto Denko Corporation and Canatu Oy anchor supply of adhesive-integrated nanowire films for curved automotive surfaces.
- Graphene:Single-layer carbon lattices offer theoretical carrier mobility exceeding 200,000 cm²/V·s, though commercial films struggle with uniform large-area deposition.
- Carbon nanotubes:Interwoven semiconducting and metallic nanotube bundles provide intermediate conductivity with lower raw material toxicity profiles than indium-based alternatives.
Leading the category by volume: ITO. Expanding most quickly: silver nanowires.
Application:
Volume concentration tracks display industry procurement cycles, while emerging segments favor printed conductor approaches that bypass vacuum infrastructure.
- Displays:Smartphone, tablet, and monitor panels consume the largest material volumes, with specification-setting power migrating from substrate producers to integrated panel manufacturers with captive optical design capabilities. East Asian substrate producers are repositioning capacity toward flexible OLED-compatible formats.
- Touch panels:Capacitive sensor layers represent the most mature application segment, though foldable device architectures are forcing qualification of mechanically tolerant conductor architectures. FDA scrutiny of medical device touch interfaces is elevating electromagnetic shielding standards for hospital-grade displays.
- Photovoltaics:Building-integrated solar facades specify semi-transparent conductor stacks with tuned absorption spectra for architectural glass applications.
- LED lighting:Cost-sensitive luminaire manufacturers favor printed conductor grids that tolerate higher sheet resistance in exchange for process simplicity.
Touch panels anchor procurement volume. Photovoltaics applications are gaining share fastest as architectural specifications proliferate.
End User:
Customer sophistication determines qualification timelines, with automotive and aerospace segments imposing extended validation protocols that compress product launch windows against consumer electronics refresh cycles.
- Consumer Electronics:Smartphone and tablet manufacturers drive the largest absolute volumes, with procurement consolidating around South Korean and Chinese display clusters. 3M Company leverages polymer science heritage to dominate adhesive-integrated conductor stacks for premium device segments.
- Automotive:Curved dashboard surfaces and head-up projection systems demand conformable conductor films that tolerate thermal cycling across vehicle lifespans. Tier-one suppliers are qualifying silver nanowire networks at accelerated timelines compared to traditional ITO glass.
- Solar Power:Utility-scale and distributed photovoltaic installations specify conductor stacks optimized for infrared transmission and outdoor durability.
- Aerospace:Avionics display applications impose stringent electromagnetic interference shielding requirements with extended certification timelines.
Consumer electronics commands the largest share. Automotive applications are climbing the fastest as cockpit digitization accelerates.
Technology:
Capital intensity separates the category, with vacuum-based methods locking out smaller entrants while roll-to-roll compatible processes modularize market entry.
- Sputtering:Vacuum deposition of oxide targets achieves the most uniform thin-film morphology for high-performance applications. Cleanroom infrastructure and target recycling protocols create barriers to cost-competitive production for converters without semiconductor manufacturing heritage.
- Thin Film Deposition:Chemical vapor and atomic layer methods enable angstrom-scale thickness control for dielectric buffer engineering between conductive layers.
- Coating:Slot-die and gravure methods apply nanowire or carbon-based inks onto flexible substrates at throughputs exceeding vacuum-limited alternatives.
- Printing:Screen and inkjet deposition of metallic grids targets cost-sensitive LED lighting segments where line width tolerance relaxes relative to display applications.
Sputtering dominates value capture. Coating methods are expanding most quickly as roll-to-roll infrastructure amortizes across flexible electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary indium extraction ties to zinc mining operations concentrated in southern China, creating supply chain dependencies that ripple through conductor manufacturing clusters across East Asia and beyond.
China
Domestic zinc smelters in Yunnan and Guangxi provinces feed raw indium to sputtering target producers serving display panel fabs. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity standards for vacuum deposition facilities. Shenzhen and Dongguan house roll-to-roll coating converters supplying flexible electronics manufacturers with silver nanowire films.
South Korea
Samsung Display and LG Display procurement programs anchor regional demand for ITO and nanowire conductor stacks. The Ministry of Trade, Industry and Energy administers national strategic technology designations that channel R&D subsidies toward OLED-compatible materials. Gyeonggi Province clusters substrate laminators and optical adhesive specialists within two-hour logistics radius of panel fabs.
United States
EPA frameworks govern indium recovery from spent sputtering targets at manufacturing facilities in Arizona and Texas. FDA scrutiny of medical device touch interfaces elevates electromagnetic shielding certification requirements for hospital-grade displays. The Pacific Northwest hosts specialty chemical formulators developing barrier film encapsulants for silver nanowire oxidation protection.
Germany
REACH restrictions on indium compounds redirect formulation R&D toward carbon nanotube alternatives at chemical companies in North Rhine-Westphalia. ECHA substance evaluation protocols extend safety data sheet requirements for importers of sputtering targets. Stuttgart's automotive engineering ecosystem drives qualification timelines for curved dashboard conductor films.
Japan
METI industrial technology roadmaps prioritize domestic supply chain resilience for display materials amid geopolitical supply risks. Osaka-based polymer scientists advance optically clear adhesive formulations that bond conductor layers to cover glass. Nagoya's automotive tier-one suppliers accelerate validation of conformable films for head-up projection systems.
Multilayer Transparent Conductors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue flexible format specialization and carbon-based material platforms. The vendor base stratifies across three maturity levels: integrated chemical conglomerates with polymer science heritage, mid-scale converters with roll-to-roll infrastructure, and nanomaterial specialists with application-specific stabilization chemistry. Two competitive vectors dominate: strategic partnerships between substrate producers and panel manufacturers, and geographic expansion of coating capacity toward automotive qualification hubs.
Among diversified chemical conglomerates, 3M Company and Nitto Denko Corporation exemplify the adhesive-integrated conductor stack archetype, leveraging polymer formulation capabilities to capture value at the materials interface. Canatu Oy occupies a specialist position within the carbon nanobush film segment, representing the nanomaterial-native competitive approach. These three anchors illustrate how competitive positioning diverges between scale-driven integrated suppliers and technology-focused niche players.
| Leading Market Players |
|---|
| 3M Company |
| Canatu Oy |
| Nitto Denko Corporation |
| DuPont Teijin Films |
| Toyobo Corporation |
| Fujifilm Holdings Corporation |
| Dontech Inc |
| Thin Film Devices Inc. |
| C3Nano Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal material passport requirements gate qualified supply access and premium-tier pricing for multilayer transparent conductor imports, forcing documentation of circularity credentials that smaller converters cannot meet. Buyers with verified closed-loop indium recovery systems command pricing premiums from European display module assemblers facing REACH authorization delays.
Pricing Analysis
Warranty and technical service bundling separates premium conductor stack suppliers from unbundled commodity providers in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with FDA electromagnetic shielding tiers commanding highest premiums. Cost compression in standard-grade ITO sputtering targets intensifies as South Korean panel fabs consolidate vendor qualification programs. LED lighting luminaire manufacturers exhibit greatest price sensitivity, tolerating higher sheet resistance in exchange for printed conductor process simplicity.
Supply Chain Analysis
Domestic-content mandates in South Korea's national strategic technology designations are reshaping sourcing toward Gyeonggi Province substrate laminators within two-hour logistics radius of Samsung and LG panel fabs. Primary indium extraction draws from zinc mining operations in China, with secondary refining concentrated in Yunnan and Guangxi provinces. Silver nanowire dispersion chemistry and optically clear adhesive formulations rest on Japanese and German chemical company supply. Single-source vulnerability concentrates in sputtering target recycling protocols. Distribution runs through East Asian display cluster procurement programs with captive optical design capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance burdens and sputtering equipment capex intensity force weaker players without semiconductor manufacturing heritage toward exit.
For Market Incumbents: Deploy backward integration into indium recovery streams to preempt EU Green Deal material passport disqualification. 3M Company and Nitto Denko Corporation demonstrate how polymer science heritage captures value at adhesive-conductor interfaces; emulate this capability anchoring against carbon nanotube substitute threats. Capacity expansion in Gyeonggi Province laminator clusters amortizes coating equipment across multi-year Samsung-LG contracts. For New Entrants and Emerging Players: The price-point gap between premium FDA-certified medical display conductors and economy LED lighting printed grids offers white-space targeting. Automotive curved dashboard qualification timelines present the most penetrable segment, as tier-one suppliers accelerate silver nanowire validation compared to traditional ITO glass. Pursue roll-to-roll coating infrastructure partnerships with Pacific Northwest barrier film encapsulant developers to bypass vacuum sputtering barriers. For Investors and Strategic Acquirers: South Korean national strategic technology designation announcements are the leading indicator that procurement leverage is concentrating among integrated panel manufacturers with captive optical design capabilities. Long-term viability favors mid-scale converters with existing roll-to-roll infrastructure and automotive qualification relationships over nanomaterial specialists without application-specific stabilization chemistry. Watch for ECHA substance evaluation protocol extensions as signals of authorization delay severity driving substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Recovery | Closed-loop sputtering target recycling satisfies EU Green Deal material passport requirements for European display imports. |
| Roll-to-Roll Coating Capacity Expansion | Modular deposition infrastructure bypasses vacuum sputtering barriers for automotive curved surface qualification. |
| FDA Electromagnetic Shielding Certification | Hospital-grade display validation opens premium pricing tiers beyond consumer electronics procurement cycles. |
| Carbon Nanotube Formulation R&D Partnership | REACH-compliant alternatives redirect spending from indium compounds toward lower-toxicity conductor architectures. |
| Gyeonggi Province Logistics Hub Establishment | Proximity to Samsung and LG panel fabs reduces qualification timeline risk for substrate laminators. |
Study Parameters
Independent corroboration across plant managers at thin-film deposition facilities, procurement leads at South Korean display panel fabs, and technical R&D directors at adhesive formulators underwrites the qualitative findings. Primary interviews with cleanroom operators, optical design engineers at integrated panel manufacturers, and barrier film encapsulant specialists combined with secondary validation from SEC 10-K filings, customs trade data, and ECHA substance evaluation protocols. Bottom-up capacity assessments and top-down demand modeling triangulate market sizing.
Rate-of-change decomposition across material type, application environment, end-user sophistication, and deposition technology dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories weighted by pricing tier evolution. Inputs include sputtering equipment installation databases, roll-to-roll coating line announcements, and REACH authorization timelines for indium compounds. Modeled outputs reflect assumptions about substitution elasticity between ITO and silver nanowires, automotive qualification velocity, and European regulatory stringency progression across the analysis window.
Inputs from ECHA substance evaluation protocols and South Korean national strategic technology designation announcements were available through the study window; gaps in private sputtering target recycling rate disclosures introduce uncertainty bands around circularity credential valuations. Forecasts reflect assumptions about regulatory enforcement consistency and automotive tier-one supplier validation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Electric Capacitor Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Power Inductors Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Audio Transistors Market
Electronic Components
Docking Station Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Primary Charge Roller Market
Electronic Components
SAW Filters Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Loudspeaker Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Coin Battery Holder Market