
 Graphics Add-In Board (AIB) Market | 2026-2036
Graphics Add-In Board (AIB) Market Size, Share, and Industry Trends Forecast 2026-2036
Graphics Add-In Board (AIB) Market Intelligence
PCI-SIG compliance certification is bifurcating the vendor landscape into qualified tier-one suppliers and marginal assemblers. Nvidia Corporation leverages its CUDA software ecosystem to sustain pricing power across datacenter and consumer tiers. Advanced Micro Devices Inc. competes on raw compute-per-watt metrics, while AsusTek Computer Inc. differentiates through thermal design and factory overclocking variants.
A graphics add-in board is a removable expansion card housing a graphics processing unit, video memory, and power delivery circuitry on a printed circuit board, designed to render visual output and accelerate parallel compute workloads via PCIe bus interface. Gaming graphics cards dominate unit volume, yet professional graphics command substantially higher average selling prices due to ISV certification requirements and ECC memory support. AI-enhanced technology represents the fastest-growing segment as tensor cores enable inference acceleration beyond traditional rasterization, while workstation graphics maintain stable replacement cycles tied to enterprise IT budgets.
EPA ENERGY STAR specifications and EU RoHS substance restrictions constrain PCB material selection and power supply design across export-bound production. The FCC's electromagnetic interference thresholds govern retail distribution in the United States, while China's GB standards mandate domestic testing protocols for products sold through local channels. Stakeholders must monitor evolving export control classifications for advanced GPUs, as semiconductor trade policy increasingly determines which architectures reach specific national markets and end-user categories.
Market Dynamics
AI-enhanced GPU architectures are decomposing the traditional bifurcation between consumer gaming and datacenter compute, forcing thermal design and memory subsystems to serve both inference acceleration and rasterization workloads simultaneously.
Growth Catalysts
- EU RoHS substance restrictions:These directives accelerate PCB material substitution toward halogen-free laminates, creating compliant supplier ecosystems that capture export-bound assembly contracts.
- Esports tournament infrastructure:Broadcast-grade rendering requirements in competitive gaming venues sustain hardware refresh cycles that outpace traditional consumer replacement patterns.
- Tensor core proliferation:Dedicated matrix multiplication units in modern GPU dies enable inference workloads previously executed on discrete AI accelerators, expanding addressable compute markets.
Market Restraints
- Advanced packaging substrate shortage:Taiwan-based ABF substrate suppliers constrain high-end GPU output, creating allocation bottlenecks for chips exceeding 600mm² die area.
- FCC electromagnetic interference thresholds:These certification requirements extend retail distribution timelines by 8-12 weeks for non-compliant PCB layouts, compressing product launch windows.
- Cloud gaming substitution:NVIDIA GeForce Now and Xbox Cloud Gaming reduce local GPU requirements for casual players, eroding entry-level discrete card demand.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:This incentive framework attracts GPU assembly capacity away from traditional China-based operations, diversifying geographic risk exposure.
- Edge AI inference nodes:Retail analytics and smart manufacturing deployments require low-latency vision processing, creating demand for compact, fan-cooled AIB variants.
- PCIe 5.0 signal integrity certification:Early compliance with this interface standard opens enterprise storage and networking acceleration markets beyond traditional graphics workloads.
Industry Challenges
- High-speed memory PHY design expertise:GDDR6X and HBM3 interface engineering talent concentrates within a handful of semiconductor design houses, constraining in-house GPU development programs.
- ISV workstation certification timelines:Autodesk, Dassault Systèmes, and Siemens validation protocols extend professional graphics product cycles by 6-9 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphics Add-In Board (AIB) Market |
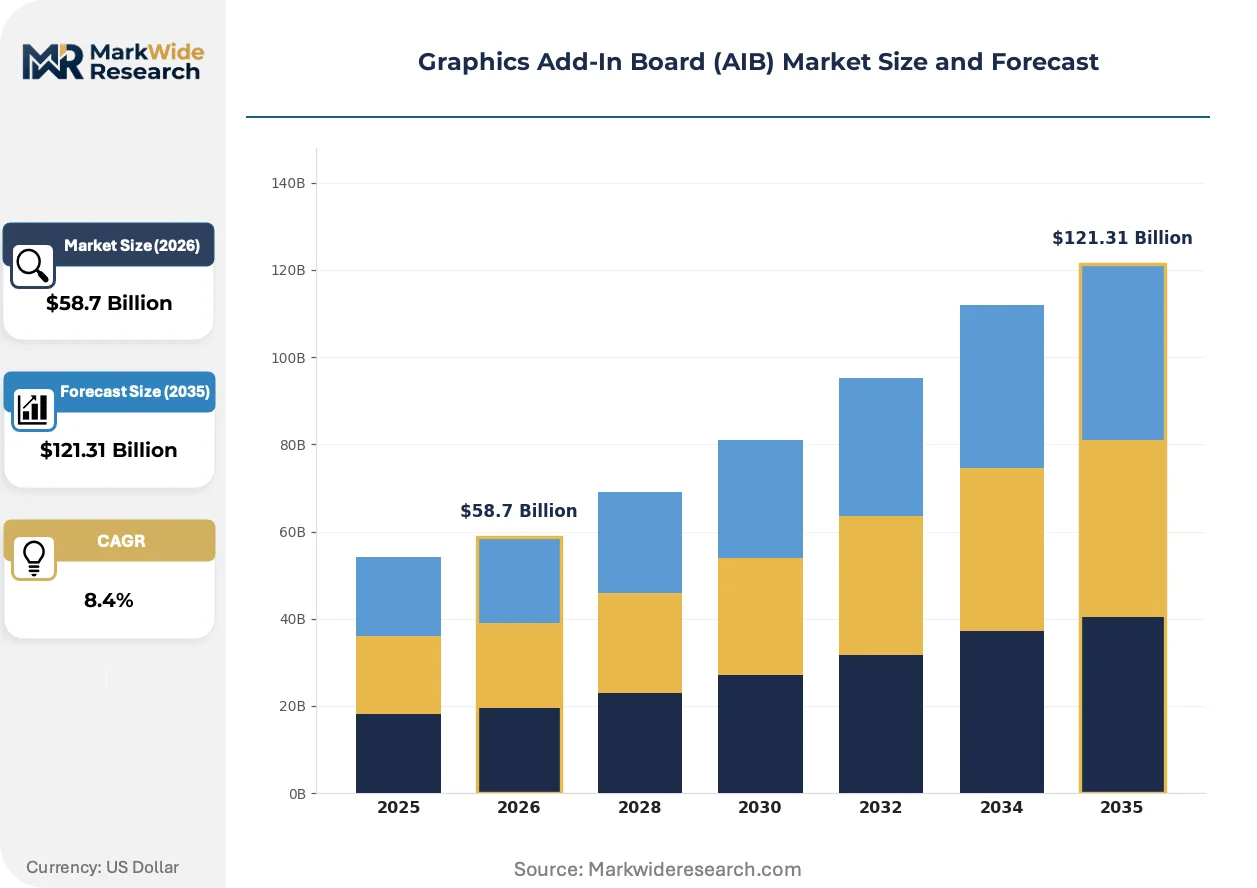
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Graphics, Workstation Graphics, Gaming Graphics, Professional Graphics Technology: GPUs, Dedicated, Integrated, AI-Enhanced End User: Gaming Enthusiasts, Content Creators, Engineers, Data Scientists Distribution Channel: Online Retail, Brick-and-Mortar, Value-Added Resellers, Direct Sales |
| Companies Covered | Nvidia Corporation, Advanced Micro Devices Inc., Intel Corporation, AsusTek Computer Inc., Micro-Star International Co., Gigabyte Technology Co. Ltd., EVGA Corporation, Sapphire Technology, ZOTAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphics Add-In Board (AIB) Market Strategic Shifts & Innovations
Chiplet-based GPU architectures are fragmenting monolithic die designs into modular compute and memory tiles, enabling yield recovery and process node mixing that alters cost structures across performance tiers.
Multi-die packaging technology is decomposing the traditional monolithic GPU into discrete compute chiplets and I/O dies connected via organic interposers. Datacenter operators and hyperscale cloud providers are adopting these configurations for training cluster deployments. This decomposition is compressing the economic viability of large-reticle monolithic designs below 5nm process nodes.
EPA ENERGY STAR specifications for computers and displays now encompass idle power draw metrics for discrete graphics subsystems. These thresholds force VRM design changes and multi-phase power gating implementations that increase BOM costs by 8-15%. Gaming-oriented AIB vendors face the steepest compliance burden as factory overclocked variants exceed baseline power budgets.
Enterprise procurement teams are consolidating GPU purchases through cloud service provider marketplaces rather than direct OEM relationships. This channel shift compresses distributor margins and transfers lifecycle support obligations to hyperscale operators. The phenomenon is most visible in North American financial services and media production verticals where CapEx-to-OpEx conversion drives preference for subscription-based GPU access.
Graphics Add-In Board (AIB) Market Segmentation
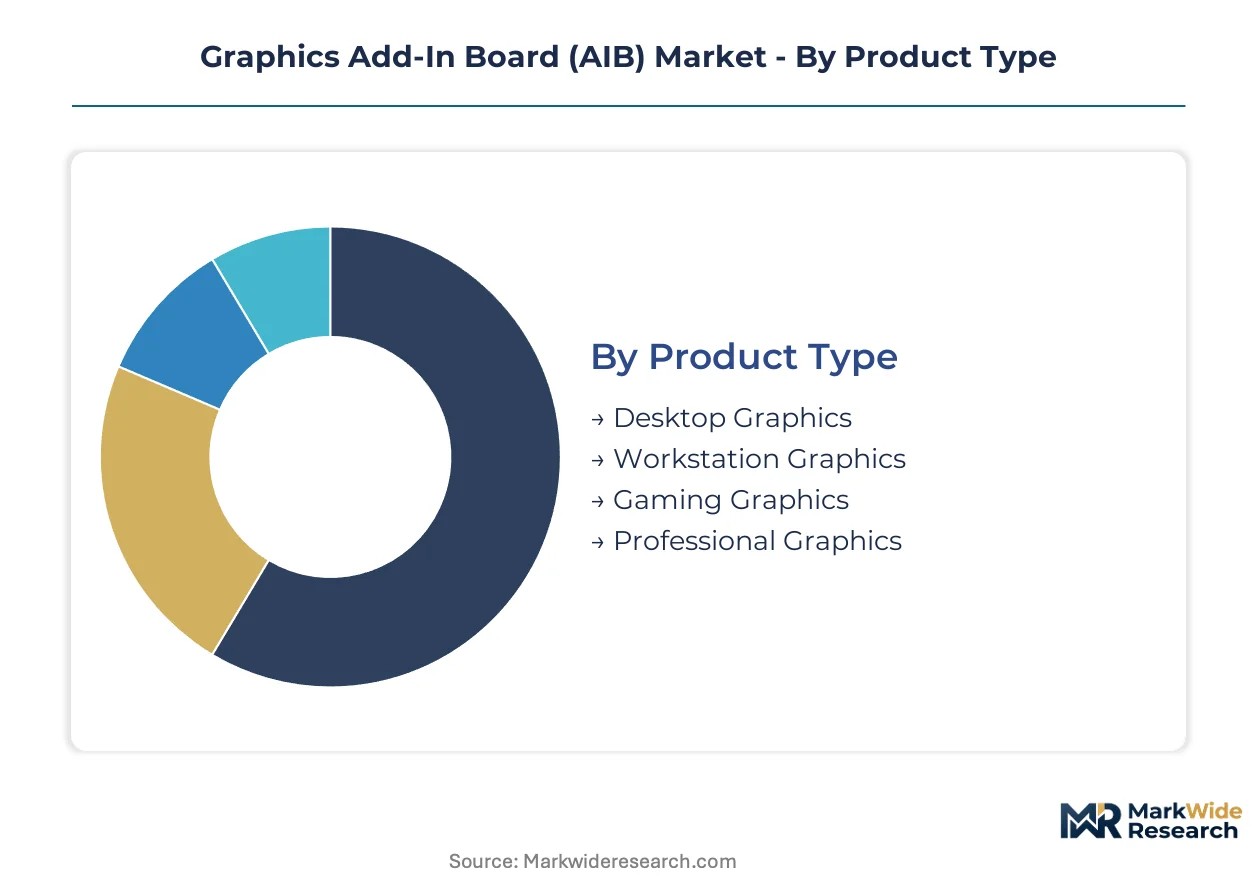
Graphics AIB segmentation reveals distinct channel pathways where gaming SKUs flow through online retail while professional cards route through value-added resellers. Understanding these channel-segment pairings exposes margin structures and inventory velocity differences across the market.
Product Type:
Gaming graphics cards move fastest through e-commerce channels with minimal configuration, whereas workstation and professional variants require VAR-assisted sales cycles with ISV certification validation.
- Desktop Graphics:Entry-level discrete GPUs for general-purpose display output and light multimedia acceleration. Corporate refresh cycles in Germany and the United States sustain volume as enterprise IT departments standardize on certified driver stacks.
- Gaming Graphics:High-refresh-rate capable boards with factory overclocked VRM designs and enhanced thermal solutions. Esports venue deployments across China and South Korea drive above-replacement-cycle demand for broadcast-grade rendering fidelity.
- Workstation Graphics:ISV-certified boards with ECC memory support and optimized drivers for CAD/CAM applications. Autodesk and Dassault Systèmes validation requirements extend sales cycles but command premium pricing through specialized distribution.
- Professional Graphics:Datacenter-facing accelerators with tensor core arrays for inference and training workloads. Hyperscale cloud provider procurement in the United States and China is concentrating demand for multi-GPU rack configurations.
Gaming graphics dominates installed base. Professional graphics is where expansion concentrates.
Technology:
Cost tier stratification separates commodity integrated solutions from premium AI-enhanced architectures with dedicated matrix multiplication units.
- GPUs:General-purpose parallel processors with programmable shader architectures spanning consumer to enterprise tiers. Raw compute-per-watt metrics from AMD and Nvidia define competitive positioning across price bands.
- AI-Enhanced:Tensor core-equipped dies enabling mixed-precision inference acceleration beyond traditional rasterization pipelines. Edge AI deployments in retail analytics and smart manufacturing are climbing the fastest for compact fan-cooled variants.
- Dedicated:Discrete boards with local frame buffer memory and independent power delivery, distinct from CPU-integrated alternatives. Enthusiast builders in Taiwan and Japan sustain demand for modular upgrade paths.
- Integrated:CPU-die graphics with shared system memory and minimal thermal envelope. Cloud gaming substitution from NVIDIA GeForce Now and Xbox Cloud Gaming is compressing entry-level discrete card addressable market.
Dedicated architectures command revenue concentration. AI-Enhanced is gaining share fastest.
End User:
Customer type determines support infrastructure requirements, with data scientists demanding API-level assistance that gaming enthusiasts rarely utilize.
- Gaming Enthusiasts:Performance-sensitive consumers prioritizing frame latency and thermal headroom for competitive titles. Tournament infrastructure investments in South Korea and China sustain hardware refresh velocity above consumer electronics norms.
- Data Scientists:ML practitioners requiring CUDA or ROCm ecosystem compatibility for model training and inference pipelines. Enterprise procurement consolidation through cloud marketplaces is transferring lifecycle support obligations to hyperscale operators.
- Content Creators:Video production and 3D rendering professionals leveraging GPU acceleration for viewport performance and encode throughput. Adobe and Blackmagic Design software optimization drives preference for specific board SKUs.
- Engineers:CAD and simulation users dependent on ISV-certified drivers for geometric modeling and finite element analysis. Siemens and PTC validation protocols constrain board selection to workstation-class product lines.
Gaming enthusiasts anchor volume shipments. Data scientists represent the steepest expansion trajectory.
Distribution Channel:
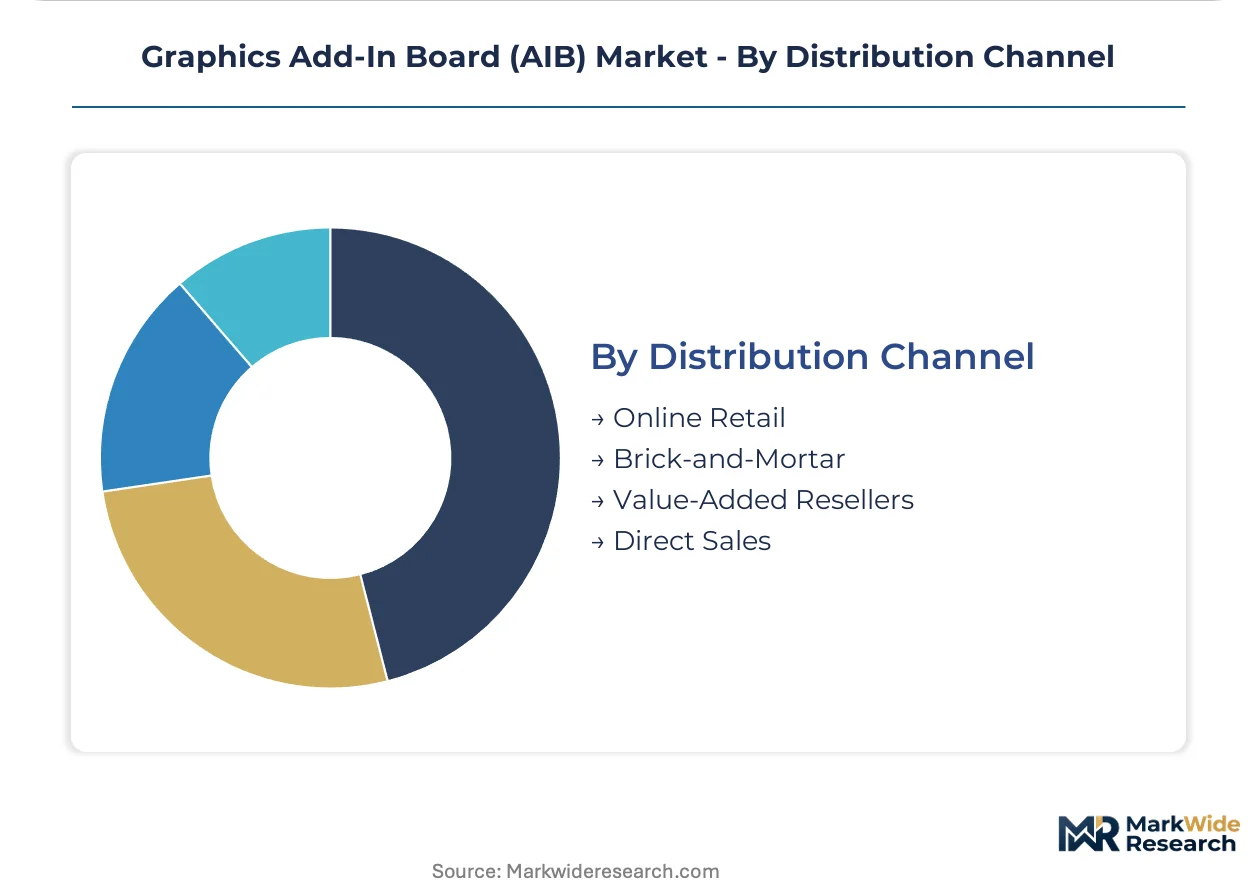
Geographic concentration of procurement decision-making shapes channel viability, with direct sales gaining traction where hyperscale operators consolidate GPU purchases.
- Online Retail:E-commerce platforms with standardized SKUs and rapid inventory turnover for consumer segments. Amazon and Newegg distribution in the United States compresses distributor margins through price transparency.
- Value-Added Resellers:Technical consultancies providing ISV certification verification and deployment support for professional graphics. CDW and SHI International in North America maintain relationships with enterprise procurement teams.
- Direct Sales:Manufacturer-to-hyperscale arrangements bypassing traditional distribution for datacenter GPU allocations. Google Cloud and AWS procurement teams in the United States negotiate multi-year supply agreements directly with Nvidia.
- Brick-and-Mortar:Physical retail with immediate availability and hands-on product comparison for enthusiast buyers. Micro Center and regional electronics chains in Germany and the United States serve builder communities with component selection support.
Online retail dominates unit velocity. Direct sales is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud procurement teams in the United States concentrate datacenter GPU demand, while gaming enthusiasts in China and South Korea drive consumer refresh cycles above replacement norms.
United States
Enterprise procurement consolidation through AWS and Google Cloud marketplaces transfers lifecycle support obligations to hyperscale operators. The FCC's electromagnetic interference thresholds govern retail distribution timelines for PCB layouts. Austin and Santa Clara host design engineering clusters where thermal solution vendors co-locate with GPU architecture teams.
China
GB standards mandate domestic testing protocols for products sold through local channels, constraining import velocity. Esports venue deployments across Shanghai and Shenzhen sustain above-replacement-cycle demand for broadcast-grade rendering fidelity. Beijing's MIIT oversees semiconductor trade policy classifications that determine which GPU architectures reach specific national markets.
Germany
Corporate refresh cycles in enterprise IT departments standardize on certified driver stacks for general-purpose display output. The EU RoHS substance restrictions accelerate PCB material substitution toward halogen-free laminates across export-bound assembly. Munich and Stuttgart concentrate CAD/CAM software optimization teams that constrain board selection to workstation-class product lines.
South Korea
Tournament infrastructure investments in Seoul sustain hardware refresh velocity above consumer electronics norms for competitive gaming. The country's national electronics regulator enforces electromagnetic compatibility certification parallel to FCC thresholds. Busan-Ulsan hosts memory packaging facilities where GDDR6X and HBM3 interface engineering talent concentrates.
India
The PLI scheme for electronics manufacturing attracts GPU assembly capacity away from traditional China-based operations. BIS certification requirements extend product launch timelines for import-dependent supply chains. Karnataka and Tamil Nadu emerging as electronics manufacturing clusters where contract assemblers establish surface-mount technology lines.
Graphics Add-In Board (AIB) Market Key Industry Players
Player mix skews toward semiconductor design houses with captive software ecosystems and thermal-solution specialists with factory overclocking capabilities. The vendor base separates into three tiers: fabless GPU architects controlling compute IP, board partners differentiating through VRM design and cooling subsystems, and system integrators bundling discrete cards with complete builds. Competitive moves center on PCIe 5.0 signal integrity certification for enterprise storage acceleration and chiplet-based packaging partnerships that decompose monolithic die designs.
Within the fabless tier, Nvidia Corporation and Advanced Micro Devices Inc. occupy positions defined by CUDA versus ROCm ecosystem control, while AsusTek Computer Inc. anchors the board-partner segment through thermal design differentiation. Intel Corporation represents a third architectural force with integrated-to-discrete GPU transition exposure. These three exemplify how software stack investment and foundry access separate sustainable pricing power from commodity assembly margin pressure.
| Leading Market Players |
|---|
| Nvidia Corporation |
| Advanced Micro Devices Inc. |
| Intel Corporation |
| AsusTek Computer Inc. |
| Micro-Star International Co. |
| Gigabyte Technology Co. Ltd. |
| EVGA Corporation |
| Sapphire Technology |
| ZOTAC |
| Others |
Cost & Logistics Intelligence
EU RoHS substance restrictions gate both supplier qualification and price differentiation simultaneously, as halogen-free laminate certification becomes a prerequisite for export-bound assembly contracts while premium thermal solutions command markups for compliant variants.
Pricing Analysis
Long-term foundry service agreements with Taiwan Semiconductor Manufacturing Company carry wafer-cost indexation tied to node maturity curves. Three-tier pricing structure across AI-enhanced datacenter accelerators, ISV-certified workstation boards, and consumer gaming SKUs separates premium tensor-core dies from standard rasterization units. Cost compression in entry-level discrete cards is intensifying because cloud gaming substitution erodes addressable demand. Gaming enthusiasts exhibit lowest price sensitivity for factory-overclocked variants, while corporate IT procurement teams drive hardest bargain on certified driver-stack deployments.
Supply Chain Analysis
ABF substrate fabrication in Taiwan constrains high-end GPU output for dies exceeding 600mm² reticle limits. Taiwan, South Korea, and the United States anchor wafer fabrication, memory packaging, and design engineering respectively. GDDR6X PHY engineering, HBM3 stack assembly, and organic interposer sourcing feed from concentrated specialist houses. Single-source vulnerability in advanced packaging substrates threatens allocation stability for chiplet-based architectures. Distribution runs through direct hyperscale procurement for datacenter tiers and e-commerce platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscale cloud marketplace procurement, as AWS and Google Cloud consolidate datacenter GPU purchasing and transfer lifecycle support obligations away from traditional OEM channels.
For Market Incumbents: Fortify CUDA and ROCm software ecosystem lock-in through API-level optimization partnerships with Autodesk and Dassault Systèmes, defending against emerging chiplet-based entrants threatening compute-per-watt parity. Deepen backward integration into thermal solution design to capture margin from factory-overclocked gaming variants. Prioritize PCIe 5.0 signal integrity certification to open enterprise storage acceleration markets beyond graphics workloads. For New Entrants and Emerging Players: Lead with edge AI inference nodes for retail analytics and smart manufacturing deployments, where compact fan-cooled AIB variants face limited incumbent specialization. India's PLI scheme for electronics manufacturing offers the most penetrable geographic entry point, diverting assembly capacity from China-based operations. Pursue ISV workstation certification for Siemens and PTC validation protocols as the primary go-to-market credibility mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed thermal solution specialists holding factory-overclocking IP and VRM design expertise. Long-term viability hinges on software ecosystem control rather than discrete hardware margins, favoring architects with captive developer platforms over board-level assemblers. Monitor export control classification shifts for advanced GPUs as the critical inflection signal for addressable market expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based Architecture Partnership | Enables yield recovery and process node mixing for datacenter training clusters at hyperscale operators. |
| PCIe 5.0 Signal Integrity Certification | Opens enterprise storage and networking acceleration markets beyond traditional rasterization workloads. |
| ISV Workstation Certification Investment | Extends sales cycles through Autodesk validation but commands premium pricing via specialized distribution. |
| Halogen-Free Laminate Supplier Qualification | Captures export-bound assembly contracts under EU RoHS substance restriction compliance requirements. |
| Direct Hyperscale Procurement Agreement | Bypasses distributor margin compression by negotiating multi-year GPU allocations with AWS and Google Cloud. |
Research Approach
A standing panel of GPU architecture engineers, thermal solution designers, hyperscale procurement officers, and ISV certification managers provided ongoing calibration against secondary validation from SEC 10-K filings, hyperscaler capex disclosures, Taiwan trade statistics, and PCI-SIG compliance registries. Bottom-up unit shipment estimates triangulated with top-down semiconductor revenue analysis.
Consistency checks validated volume and value outputs against foundry utilization reports, memory vendor shipment data, and channel inventory surveys across the projection horizon. Segmentation modeling spanned product type, technology tier, end-user archetype, and distribution channel, with CAGR derivation anchored in replacement cycle analysis and AI workload penetration curves. Foundry capacity allocation schedules and export control classification timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC electromagnetic interference thresholds, EU RoHS substance restrictions, and China's GB standards; material policy shifts would require re-modeling of supply availability and market access assumptions. Practitioners should keep alternative scenarios live as semiconductor trade policy classifications and advanced packaging substrate allocation protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
IF Digital Attenuator Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Coin Battery Holder Market
Electronic Components
USB Retimer Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
AC Adapter Market
Electronic Components
Audio Transistors Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Switch Diode Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Dual Relay Board Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market