
 Audio Transistors Market | 2026-2036
Audio Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Transistors Market Outlook
REACH compliance is expanding the cost-of-entry calculus for audio transistor suppliers targeting European professional audio markets. Texas Instruments leverages its analog design heritage to sustain premium positioning in high-fidelity amplification circuits. ON Semiconductor anchors North American supply security through in-house fabrication of discrete audio-grade semiconductors. STMicroelectronics competes across bipolar junction and field effect transistor portfolios with manufacturing scale in European precision electronics clusters.
Audio transistors are discrete semiconductor devices engineered for signal amplification and switching in sound reproduction systems, typically specified by noise figures below 1 dB and thermal stability across operating temperatures. These components serve the primary commercial purpose of converting low-level audio signals into amplified output without harmonic distortion in professional mixing consoles, consumer amplifiers, and broadcast transmission chains. Field effect transistors command margin pools in premium professional audio equipment where impedance matching and thermal noise suppression determine purchasing decisions, while bipolar junction transistors retain volume leadership in cost-sensitive consumer electronics applications. LDMOS technology is gaining structural share in broadcast and telecommunication audio amplification where RF integration and power efficiency requirements intersect.
The EPA governs hazardous substance reporting for semiconductor manufacturing facilities operating in United States audio component supply chains. ECHA administers REACH substance restrictions affecting epoxy molding compounds and lead-frame plating chemistry used in European-sourced transistors. Japan's METI coordinates industrial standards through JIS specifications that define electrical parameter testing protocols for audio-grade discrete semiconductors. Stakeholders must monitor evolving substance restriction schedules and regional certification reciprocity agreements to preserve market access across fragmented regulatory jurisdictions.
Market Dynamics
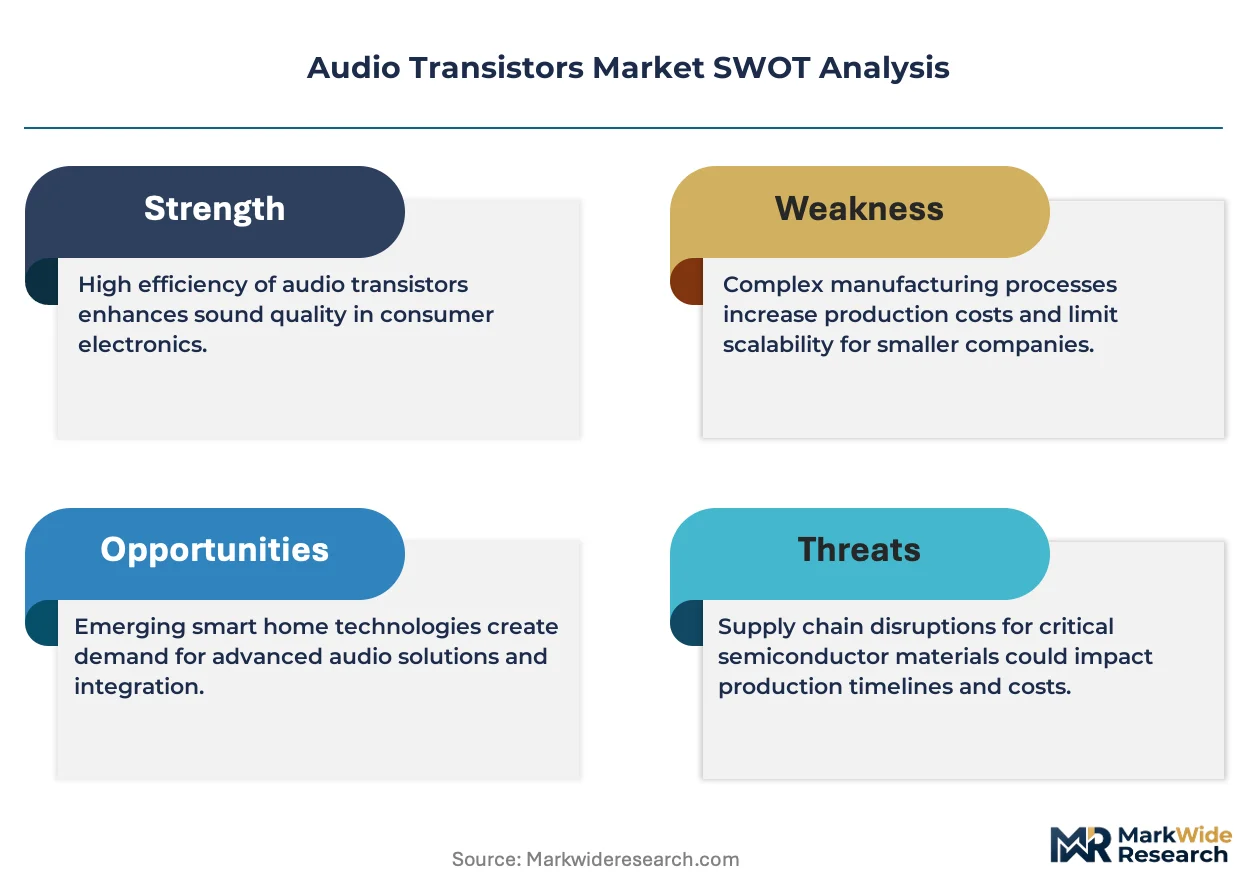
Professional audio equipment manufacturers are consolidating procurement around high-fidelity transistors with sub-1 dB noise figures, compressing supplier margins while elevating technical qualification barriers for new entrants.
Growth Catalysts
- Studio-grade amplifier demand:Professional mixing console manufacturers in Germany's precision electronics corridor are expanding orders for thermally stable discrete semiconductors specified for 24-bit audio paths.
- F-Gas Regulation compliance:The European Union's tightening material restrictions on semiconductor packaging compounds are accelerating qualification of alternative epoxy molding formulations.
- LDMOS RF integration:Broadcast transmission chains are specifying laterally diffused metal-oxide semiconductors that combine audio amplification with RF power efficiency in single-device architectures.
Market Restraints
- Epoxy compound cost volatility:REACH substance restrictions on halogenated flame retardants are inflating input costs for European-sourced transistor housings.
- Fabrication concentration:In-house production of audio-grade discretes anchors with ON Semiconductor and Texas Instruments, limiting second-source options for precision bipolar junction transistors.
- Thermal noise floor limitation:Bipolar junction transistors cannot achieve the impedance matching performance of field effect transistors in premium professional equipment, constraining their addressable market.
Strategic Opportunities
- India precision electronics manufacturing:The PLI scheme is attracting semiconductor packaging investments that could serve professional audio OEMs seeking geographic diversification beyond European supply clusters.
- Automotive infotainment integration:Electric vehicle cabin audio systems are specifying broadcast-grade amplification chains that bridge consumer and professional performance tiers.
- Dual carbon convergence:China's MEE efficiency mandates and EU Green Deal alignment are creating certification reciprocity pathways for low-thermal-resistance transistor designs.
Industry Challenges
- Analog design talent scarcity:Audio transistor specification engineering requires expertise in harmonic distortion measurement that semiconductor programs no longer emphasize.
- REACH certification timelines:ECHA substance restriction updates are forcing 18-24 month requalification cycles that delay product launches for European professional audio markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Transistors Market |
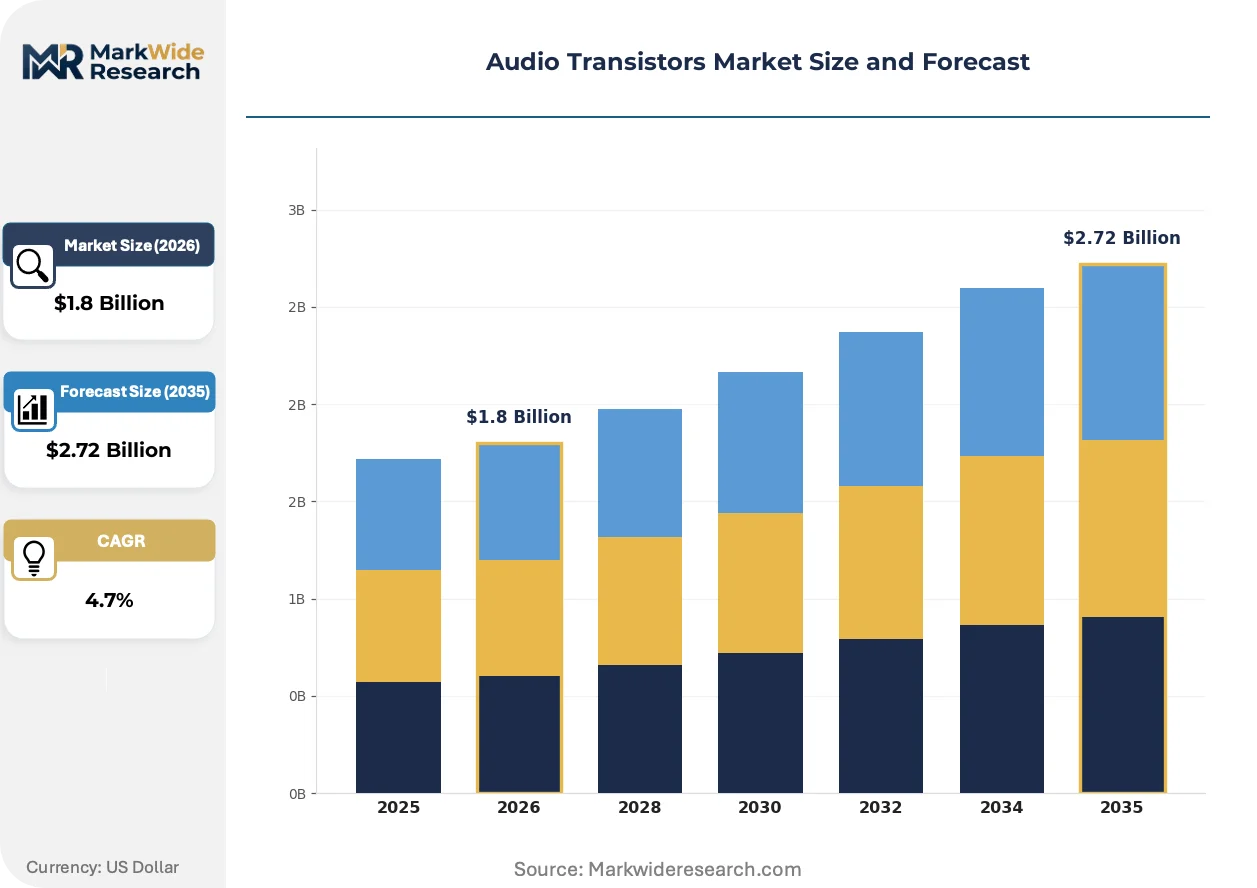
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistors, Field Effect Transistors, IGBT, LDMOS Application: Professional Audio Equipment, Consumer Electronics, Musical Instruments, Telecommunication Devices End User: Audio Engineers, Home Users, Recording Studios, Broadcast Media Technology: Analog, Digital, Hybrid, RF |
| Companies Covered | Texas Instruments, ON Semiconductor, STMicroelectronics, Infineon Technologies, Vishay Intertechnology, NXP Semiconductors, Microchip Technology, Renesas Electronics, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Transistors Market Strategic Shifts
Signal fidelity requirements are bifurcating the component base, with professional audio demanding discrete architectures while consumer electronics integrates functions into system-on-chip designs.
Silicon-germanium heterojunction bipolar transistors are overtaking conventional silicon bipolar designs in studio-grade microphone preamplifiers. High-end recording equipment manufacturers in Nashville and London are specifying SiGe devices for their superior noise figure performance at low collector currents. This material transition is compressing the viable supplier base to foundries with compound semiconductor capability.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon use in semiconductor manufacturing process gases. ECHA enforcement is compelling transistor packaging facilities to validate alternative die-attach adhesives and molding compound chemistries. Professional audio equipment OEMs in Germany are demanding full material disclosure documentation that extends supply chain traceability requirements to third-tier chemical suppliers.
Direct procurement from discrete semiconductor foundries is displacing traditional distribution channels for high-volume professional audio OEMs. Mid-tier amplifier manufacturers in Shenzhen and Seoul are establishing captive supplier relationships that bypass authorized distributors for audio-grade field effect transistors. This channel compression is most visible in the broadcast transmission segment, where equipment makers consolidate annual volumes to negotiate wafer-start allocations directly.
Audio Transistors Market Segmentation
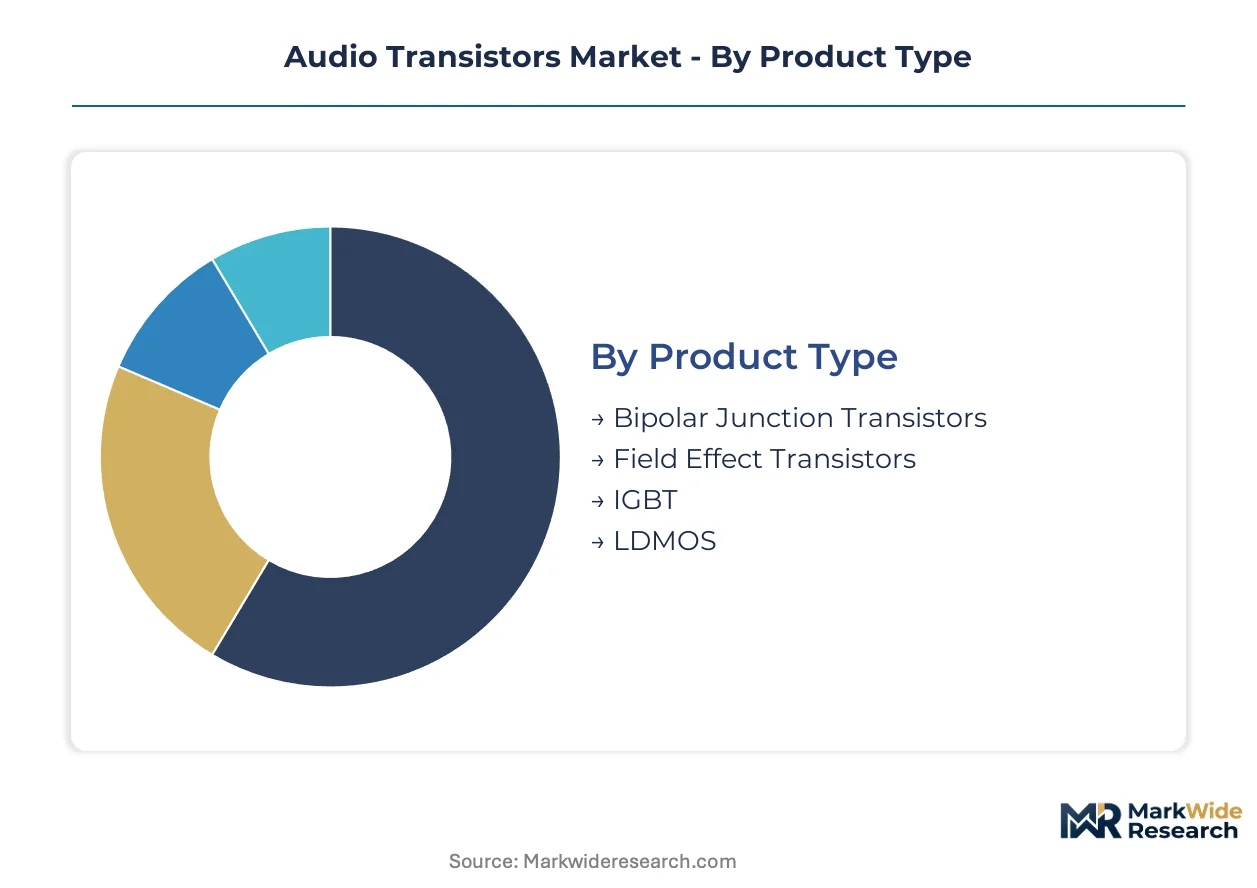
Audio transistor procurement patterns diverge sharply between discrete architectures for professional signal chains and integrated solutions for consumer electronics. Understanding where each segment sits on this integration spectrum determines supplier qualification requirements and margin capture potential.
Product Type:
Integration depth varies dramatically across transistor architectures, with some technologies engineered for standalone amplification stages while others serve embedded RF-audio convergence applications.
- Bipolar Junction Transistors:Silicon-based current-controlled devices deliver high transconductance for low-source-impedance audio stages. Consumer amplifier manufacturers in Shenzhen specify these for cost-sensitive Class AB output sections where thermal stability trumps noise performance.
- Field Effect Transistors:Voltage-controlled operation enables superior input impedance matching for high-impedance microphone preamplifiers. German precision electronics OEMs around Munich source discrete FETs for 24-bit studio consoles where sub-1 dB noise figures determine purchasing decisions.
- IGBT:Insulated-gate bipolar devices combine MOSFET input characteristics with bipolar output capability for high-power broadcast transmitters.
- LDMOS:Laterally diffused metal-oxide semiconductors integrate audio amplification with RF power efficiency in single-device architectures for telecommunications infrastructure.
Bipolar junction transistors lead volumes today; LDMOS is gaining share fastest in broadcast-telecom convergence applications.
Application:
Cost tier differentiation separates premium professional equipment from mass-market consumer electronics, with pricing power concentrated in certification-intensive studio-grade segments.
- Professional Audio Equipment:Studio-grade mixing consoles, broadcast transmission chains, and live sound reinforcement systems demand discrete transistor architectures with documented harmonic distortion specifications. REACH compliance documentation requirements from ECHA elevate supplier qualification barriers for European professional audio OEMs.
- Consumer Electronics:Integrated amplifier modules and soundbar systems prioritize cost optimization over discrete component performance. Home theater manufacturers in Seoul specify system-on-chip audio solutions that embed transistor functions within broader semiconductor packages.
- Musical Instruments:Guitar amplifiers and synthesizers require thermally rugged discrete semiconductors for overdriven signal characteristics.
- Telecommunication Devices:Base station audio processing and network infrastructure equipment specify RF-integrated transistor technologies.
Professional audio equipment commands premium pricing tiers; consumer electronics dominates unit volumes.
End User:
Customer type determines technical specification intensity, with commercial users demanding traceable performance documentation absent from residential purchasing decisions.
- Audio Engineers:Professional sound designers and mixing specialists specify transistors by measured noise figure and harmonic distortion parameters. London and Nashville recording facility procurement teams require batch-level electrical test data that consumer channels never demand.
- Recording Studios:Commercial audio production facilities consolidate annual transistor purchases through direct foundry relationships that bypass distribution markups.
- Home Users:Residential amplifier purchasers rely on finished product specifications without component-level technical evaluation.
- Broadcast Media:Television and radio transmission operators specify LDMOS devices for combined audio-RF amplification in transmission chains.
Home users represent the largest addressable population; recording studios deliver highest per-transistor revenue.
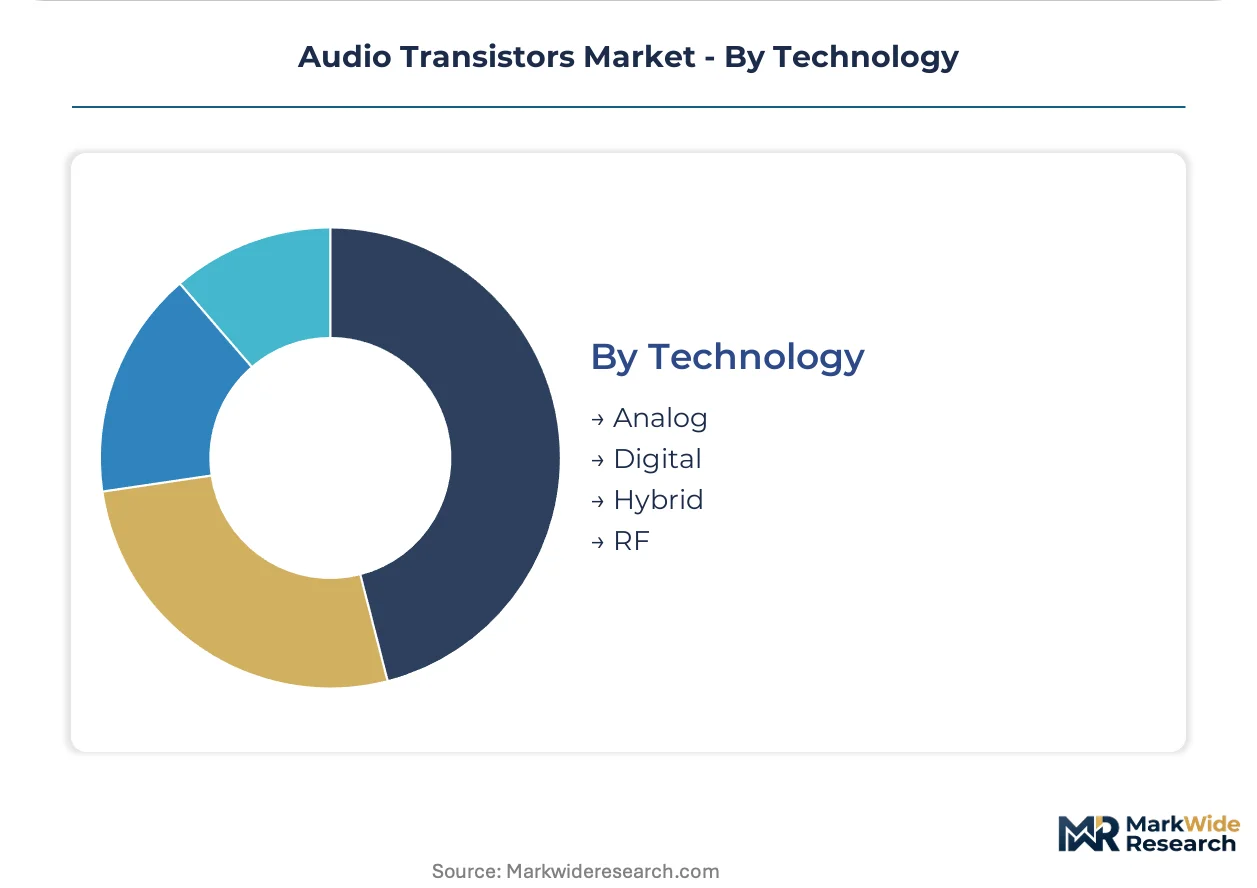
Technology:
Supply concentration for precision analog designs creates sourcing constraints as semiconductor education programs deemphasize discrete component engineering.
- Analog:Continuous signal amplification remains essential for professional audio paths where digital conversion introduces unacceptable latency. Discrete analog transistor fabrication concentrates with established suppliers possessing legacy process expertise that foundry newcomers cannot replicate quickly.
- Digital:Class D amplification and digital signal processing integration reduces discrete transistor counts in consumer audio applications.
- Hybrid:Mixed-signal architectures combine analog front-end transistors with digital control loops for adaptive bias systems.
- RF:Radio-frequency integrated transistor technologies serve telecommunications infrastructure requiring audio-bandwidth signal processing.
Analog technology anchors professional audio procurement; digital integration expands most quickly in consumer electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analog design engineers concentrate in Germany's precision electronics corridor and Japan's semiconductor clusters, anchoring professional audio transistor specification expertise in these geographies. Foundry capacity for discrete semiconductors distributes across East Asian manufacturing centers and European packaging facilities. Regulatory divergence between REACH substance restrictions and Asia-Pacific efficiency mandates shapes regional qualification requirements.
Germany
Studio-grade mixing console manufacturers in Munich and Nuremberg drive procurement of thermally stable bipolar junction transistors for 24-bit audio paths. ECHA REACH compliance documentation requirements extend supply chain traceability to third-tier chemical suppliers. Bavaria's precision electronics manufacturing corridor anchors European professional audio OEM consolidation around discrete semiconductor architectures.
United States
High-end recording equipment manufacturers in Nashville specify silicon-germanium heterojunction bipolar transistors for low-noise microphone preamplifiers. EPA hazardous substance reporting governs semiconductor fabrication facilities serving domestic audio component supply chains. Greater Austin's analog design talent pool sustains captive supplier relationships for broadcast-grade amplification chains.
Japan
Discrete audio-grade semiconductor fabrication concentrates in legacy process facilities with expertise in harmonic distortion measurement protocols. METI coordinates JIS electrical parameter testing standards that define professional audio transistor specifications. Tokyo-Osaka industrial corridor maintains foundry relationships for thermally rugged devices serving musical instrument amplifier manufacturers.
China
Mid-tier amplifier manufacturers in Shenzhen establish direct procurement relationships with discrete semiconductor foundries for field effect transistors. MEE efficiency mandates and dual carbon convergence goals create certification reciprocity pathways for low-thermal-resistance transistor designs. Pearl River Delta packaging investments serve professional audio OEMs seeking geographic diversification beyond European supply clusters.
India
PLI scheme incentives attract semiconductor packaging investments targeting professional audio equipment supply chains. BIS industrial standards coordination supports domestic qualification of epoxy molding compound alternatives for transistor housings. Karnataka and Tamil Nadu precision electronics manufacturing clusters develop capabilities to serve studio-grade amplifier OEMs with REACH-compliant component sourcing.
Audio Transistors Market Competitive Environment
The competitive structure tilts toward integrated device manufacturers with legacy analog process expertise. Discrete audio-grade semiconductor fabrication concentrates with established suppliers possessing in-house bipolar junction and field effect transistor capabilities. Three archetypes dominate: precision analog specialists with foundry control, diversified semiconductor conglomerates with professional audio divisions, and RF-integrated device manufacturers serving broadcast-telecom convergence. Capacity expansion in European packaging facilities and strategic partnerships for compound semiconductor access represent the dominant competitive moves.
Among diversified semiconductor manufacturers, Texas Instruments, ON Semiconductor, and STMicroelectronics occupy positions reflecting their analog design heritage and fabrication scale. Texas Instruments exemplifies the precision analog specialist archetype through its sustained premium positioning in high-fidelity amplification circuits. ON Semiconductor represents integrated device manufacturing with in-house fabrication of discrete audio-grade semiconductors anchoring North American supply security. STMicroelectronics sits within the European manufacturing scale tier, competing across bipolar junction and field effect transistor portfolios with production facilities in precision electronics clusters.
| Leading Market Players |
|---|
| Texas Instruments |
| ON Semiconductor |
| STMicroelectronics |
| Infineon Technologies |
| Vishay Intertechnology |
| NXP Semiconductors |
| Microchip Technology |
| Renesas Electronics |
| Toshiba Corporation |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin price indices cascading through semiconductor packaging supply chains stratify audio transistor procurement into performance-certified premium tiers and commodity-grade economy segments. REACH compliance costs for halogenated flame retardant alternatives concentrate pricing power with European packaging facilities serving German precision audio OEMs.
Pricing Analysis
Unbundled component sales dominate professional audio channels where discrete transistor specifications command premium multiples over integrated consumer solutions. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European sourcing from Asian contract manufacturing and undifferentiated spot-market procurement. Cost compression in economy tiers intensifies because mid-tier amplifier manufacturers in Shenzhen consolidate volumes for direct foundry negotiations. Consumer electronics OEMs exhibit highest price sensitivity; German studio-grade console manufacturers demonstrate lowest sensitivity where noise figure certification determines supplier selection.
Supply Chain Analysis
Single-source vulnerability sits with ON Semiconductor's in-house fabrication of precision bipolar junction transistors for North American professional audio security. Manufacturing gravity centers on Germany, Japan, and the United States for discrete audio-grade semiconductors, with packaging operations distributed across Malaysia and Thailand. Raw material dependencies include high-purity silicon wafers, gold wire bonding materials, and epoxy molding compounds. Tariff exposure on semiconductor process equipment imports threatens capacity expansion timelines. Distribution runs through authorized distributors for low-volume specialty orders; direct foundry relationships displace intermediaries for high-volume professional audio OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH substance restriction timelines drive 18-24 month requalification cycles that consolidate procurement around pre-certified incumbent suppliers.
For Market Incumbents: Lock in analog design talent through captive relationships with legacy semiconductor engineering programs at Munich and Austin technical universities. Defend margin position by expanding in-house fabrication capacity for silicon-germanium heterojunction devices before compound semiconductor foundry access becomes a binding constraint. Threat substitution from system-on-chip integration in consumer tiers demands discrete performance differentiation through documented harmonic distortion specifications. For New Entrants and Emerging Players: Enter via India's PLI scheme packaging investments to serve European professional audio OEMs seeking geographic diversification beyond German supply clusters. Target automotive infotainment integration as the most penetrable bridge segment between consumer cost structures and professional performance requirements. White-space opportunity sits with broadcast-grade LDMOS devices where RF-audio convergence specifications remain undersupplied. Go-to-market angle: certification reciprocity documentation for dual carbon convergence pathways between China's MEE efficiency mandates and EU Green Deal alignment. For Investors and Strategic Acquirers: Asymmetric upside sits with precision analog specialists possessing legacy bipolar junction transistor process expertise that semiconductor education programs no longer replicate. Long-term viability favors integrated device manufacturers with captive fabrication rather than fabless competitors exposed to foundry allocation volatility. Acquisition target archetype: European packaging facilities with validated REACH-compliant epoxy molding compound formulations. Signal to watch: ECHA substance restriction updates accelerating consolidation among second-tier suppliers unable to absorb requalification costs.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Investment | ECHA substance restriction updates force 18-24 month requalification cycles that pre-certified suppliers exploit. |
| Silicon-Germanium Process Capability Expansion | Foundry access for heterojunction bipolar transistors compresses viable supplier base to compound semiconductor specialists. |
| Direct Foundry Relationship Establishment | Bypassing authorized distributors captures margin compression from channel consolidation in broadcast transmission segments. |
| India PLI Scheme Packaging Investment | Geographic diversification beyond European supply clusters attracts professional audio OEM procurement migration. |
| Analog Design Talent Captive Programs | Semiconductor education deemphasis on discrete component engineering creates irreplaceable legacy expertise pools. |
Study Parameters
Coverage spans Germany, United States, Japan, China, and India, with primary inputs from each regional precision electronics cluster. Primary interviews combined insights from professional audio equipment procurement managers, discrete semiconductor foundry operations directors, analog design engineering leads, and epoxy molding compound technical specialists. Secondary validation drew from ECHA REACH substance restriction databases, METI JIS standard publications, SEC semiconductor manufacturer filings, and customs trade records for discrete semiconductor imports. Bottom-up transistor shipment data triangulated against top-down professional audio equipment production estimates.
Granularity-level modeling operated at product architecture, application tier, end-user type, and regional regulatory cluster dimensions. Volume and value outputs across the projection horizon reflect segment-specific growth trajectories derived from equipment manufacturer procurement surveys and foundry capacity utilization disclosures. CAGRs were computed from annual shipment estimates cross-referenced against amplifier production data from German and Japanese precision electronics OEMs. Industry-specific forecast inputs included REACH compliance timeline assumptions and PLI scheme incentive disbursement patterns.
Inputs from ECHA regulatory filings and foundry capacity announcements were available through the study window; gaps in third-tier chemical supplier disclosure introduce uncertainty bands around REACH compliance cost projections. Forecasts reflect assumptions about substance restriction implementation schedules and reciprocity agreement negotiations that could accelerate or delay certification pathways. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Fixed Capacitor Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Impulse Relays Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Braking Resistors Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Global Suction Tube Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Global Capacitor Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Digital Potentiometer Market