
 Global Surge Protection Devices Market | 2026-2036
Global Surge Protection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surge Protection Devices Market Foresight
Electrical distributor networks across Europe and North America is fragmenting as direct-to-contractor digital platforms gain share. Schneider Electric leverages its integrated energy management portfolio to sustain channel loyalty among large electrical contractors. Siemens anchors its position through specification-grade engineering relationships with utility providers and industrial EPC firms. Phoenix Contact differentiates via modular DIN-rail systems that dominate machine-builder segments across German-speaking markets.
Surge protection devices are engineered electrical safety components designed to clamp transient overvoltages—typically limiting surge currents from 1 kA to over 100 kA—thereby shielding downstream equipment from lightning-induced or switching-induced damage. Metal oxide varistors remain the dominant core technology due to their cost-scalable clamping characteristics across residential through industrial voltage classes. Surge arresters command the largest product-type revenue pool given their mandatory deployment across transmission and distribution networks, while hybrid technology configurations are gaining fastest in data center and renewable energy applications where multi-stage protection architectures reduce downtime risk. Silicon avalanche diodes occupy premium niches requiring sub-nanosecond response times in telecommunications carrier infrastructure.
UL 1449 in the United States, IEC 61643 standards under the IEC framework, and CE marking requirements under EU directives collectively shape product certification pathways and market access conditions for surge protection device manufacturers. China's GB standards and NMPA-equivalent quality supervision protocols add compliance layers for equipment imported into utility-scale projects. Stakeholders must monitor evolving grid-code harmonization between IEC and national variants, as divergence in test-waveform requirements continues to fragment product platform strategies.
Market Dynamics
Grid modernization mandates across Germany, the United States, and China are forcing simultaneous upgrades to distribution-level protection equipment, creating synchronized demand pulses that strain varistor supply chains and compress certification timelines for multi-standard product platforms.
Growth Catalysts
- IEC 61643 harmonization pressure:European utilities are accelerating arrester replacement cycles to meet tightened clamping voltage tolerances, pulling forward industrial procurement.
- Data center buildouts:Hyperscale operators in Virginia and Frankfurt are mandating hybrid SPD architectures with remote monitoring capabilities for all new substations.
- Silicon carbide integration:Wide-bandgap semiconductors in renewable inverters are driving demand for faster-response protection modules in solar and wind installations.
Market Restraints
- Zinc oxide supply concentration:Varistor-grade ceramic powder production clusters in China's Hunan province, exposing global manufacturers to export quota volatility.
- UL 1449 Edition 5 testing costs:The revised surge-current waveform requirements have doubled third-party certification expenses for mid-tier suppliers.
- Gas discharge tube substitution:Telecommunications infrastructure in Japan is migrating to GDT-based protection for RF applications, eroding MOV market share in 5G base stations.
Strategic Opportunities
- India's CEA grid resilience mandate:The Central Electricity Authority's 2023 directive on distribution transformer protection creates a compliance-driven entry window for certified suppliers.
- EV charging infrastructure:DC fast-charger OEMs in South Korea and Germany are specifying integrated SPD modules with thermal disconnect features.
- Digital distributor platforms:Direct-to-contractor procurement in North America is bypassing traditional electrical distribution networks, lowering customer acquisition costs for modular DIN-rail specialists.
Industry Challenges
- EMC testing talent scarcity:Laboratories capable of IEC 61000-4-5 surge immunity validation face 14-month backlogs, delaying product launches.
- Legacy panel integration:Retrofit SPD deployment in aging US commercial buildings requires custom busbar configurations that void existing UL listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surge Protection Devices Market |
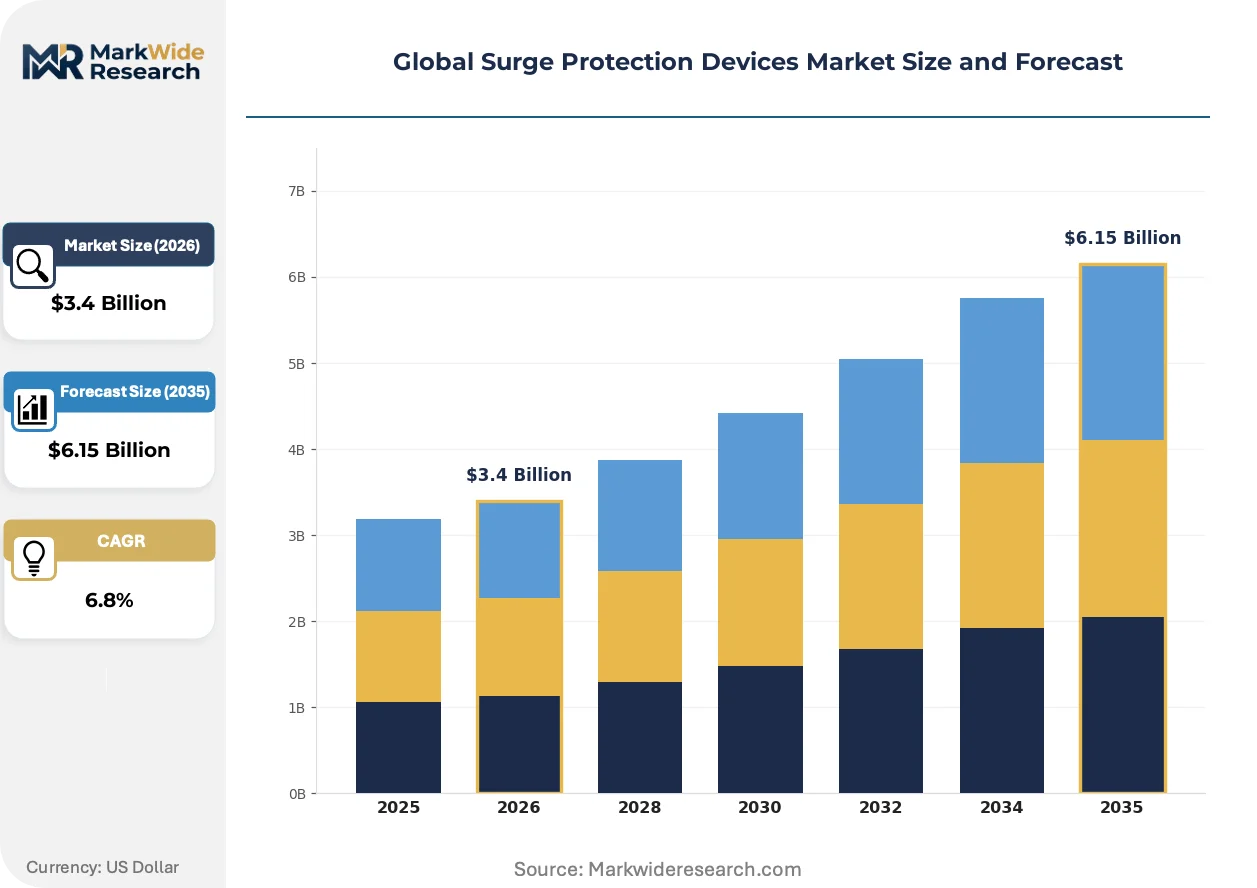
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surge Arresters, Metal Oxide Varistors, Gas Discharge Tubes, Silicon Avalanche Diodes Technology: Thermal Disconnection, Spark Gap, Hybrid, Solid State, Thyristor Controlled Application: Telecommunication Equipment, Renewable Energy Systems, Data Centers, Commercial Electrical Systems, Residential Electronic Devices End User Industry: Utility Providers, Data Processing Centers, Telecommunications Carriers, Commercial Complexes, Home Automation Providers |
| Companies Covered | ABB Ltd., CITEL Inc., Schneider Electric, DEHN SE, Legrand, Eaton Corporation, Phoenix Contact, Siemens, Littelfuse, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surge Protection Devices Market Shifts & Advancements
Intelligent protection systems with embedded diagnostics are displacing passive components across critical infrastructure, while regulatory divergence between IEC and national test standards fragments product development roadmaps.
Hybrid surge protection combining metal oxide varistors with silicon avalanche diodes is digitizing condition monitoring in data center power distribution units. Amazon Web Services and Equinix facilities in Northern Virginia and Frankfurt are deploying these modules at scale. The technology is digitizing maintenance scheduling by transmitting clamping event counts and thermal degradation data to facility management platforms, compressing unplanned downtime intervals.
China's GB/T 18802 standard revisions are tightening residual voltage requirements for Class I SPDs used in utility-scale solar farms. The State Grid Corporation of China has accelerated procurement timelines to lock in pre-change inventory. Domestic manufacturers with in-house testing laboratories are capturing specification authority that foreign competitors struggle to match.
Electrical contractors in Germany and the United States are unbundling surge protection from turnkey panel contracts, purchasing modules separately through digital procurement platforms. This pattern concentrates specification authority with consulting engineers rather than distributor sales staff. The shift is most visible in commercial construction verticals where design-build contracts dominate project delivery.
Global Surge Protection Devices Market Segmentation
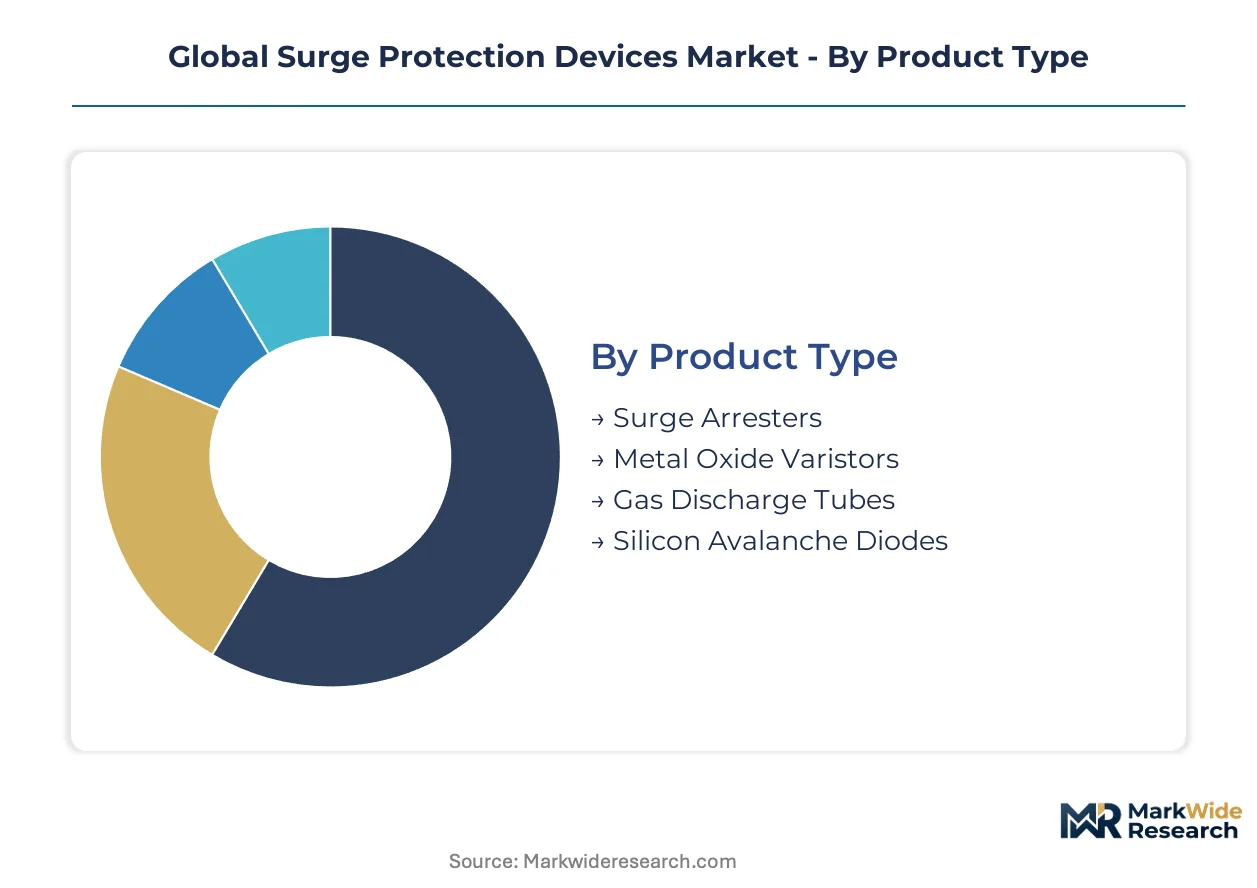
Surge protection device manufacturers must align product architectures with distinct maintenance lifecycles and replacement protocols across customer segments. Varistor-based systems require periodic thermal monitoring, while hybrid configurations demand firmware updates and diagnostic calibration that reshape service revenue models.
Product Type:
After-sales service intensity varies sharply across product categories, with arresters demanding scheduled inspection intervals and MOV modules driving predictable replacement part revenue.
- Surge Arresters:High-voltage ceramic-housed units clamp lightning-induced transients across transmission and distribution networks. State Grid Corporation of China and Germany's TenneT mandate these for all new substation installations, with replacement cycles accelerating under tightened IEC 61643-11 clamping voltage tolerances.
- Metal Oxide Varistors:Zinc oxide ceramic discs provide cost-scalable overvoltage protection from residential 120V through industrial 480V classes. Demand concentrates in the United States and China where panel OEMs specify MOV modules for commercial building retrofits, though Hunan province supply concentration exposes procurement to export quota volatility.
- Gas Discharge Tubes:Hermetically sealed noble-gas devices handle high-current RF protection in telecommunications infrastructure.
- Silicon Avalanche Diodes:Sub-nanosecond response semiconductors serve precision telecommunications carrier equipment.
Surge arresters hold the largest share; momentum sits with silicon avalanche diodes in 5G base station deployments.
Technology:
Cost tier differentiation separates premium intelligent systems from commodity passive components, with hybrid architectures commanding three-to-four times the unit economics of spark-gap alternatives.
- Thermal Disconnection:Fusible links integrated into MOV housings prevent fire propagation during end-of-life thermal runaway. South Korean DC fast-charger OEMs now specify these modules as standard, driven by KBA-equivalent electrical safety mandates for EV infrastructure.
- Hybrid:Multi-stage architectures combining MOV primary clamping with silicon avalanche diode secondary protection enable remote condition monitoring. Amazon Web Services and Equinix facilities in Northern Virginia and Frankfurt deploy these at scale, transmitting clamping event counts to facility management platforms.
- Spark Gap:Air-gap breakdown devices provide economical high-current handling for industrial motor protection.
- Solid State:Semiconductor-only designs eliminate mechanical wear for mission-critical medical and aviation electronics.
- Thyristor Controlled:Gate-triggered crowbar circuits divert massive surge currents in heavy industrial and railway traction systems.
Thermal disconnection is gaining specification authority fastest in transportation electrification; hybrid systems dominate data center procurement.
Application:
Customer type fragmentation separates specification-grade engineering relationships from price-sensitive procurement, with data center operators prioritizing uptime guarantees over capital expenditure minimization.
- Data Centers:Hyperscale facilities require multi-stage protection with embedded diagnostics at substation and rack-level distribution. Virginia's Loudoun County and Frankfurt's Kelsterbach cluster operators mandate remote monitoring capabilities, compressing unplanned downtime intervals through predictive maintenance scheduling.
- Renewable Energy Systems:Solar and wind inverters demand faster-response protection modules as silicon carbide wide-bandgap semiconductors proliferate. China's GB/T 18802 revisions are tightening residual voltage requirements for utility-scale solar farms, accelerating domestic procurement timelines.
- Telecommunication Equipment:5G base stations and carrier infrastructure prioritize sub-nanosecond response protection.
- Commercial Electrical Systems:Panel-integrated SPDs serve retail, healthcare, and education verticals with standardized surge current ratings.
- Residential Electronic Devices:Consumer-grade power strips and HVAC protection modules compete on cost-per-outlet metrics.
Data centers hold the largest share; renewable energy systems are climbing the fastest on capacity addition trajectories.
End User Industry:
Supply concentration among zinc oxide ceramic powder producers in China's Hunan province shapes procurement risk profiles for utility-scale buyers, while data processing centers prioritize vendor technical support capabilities.
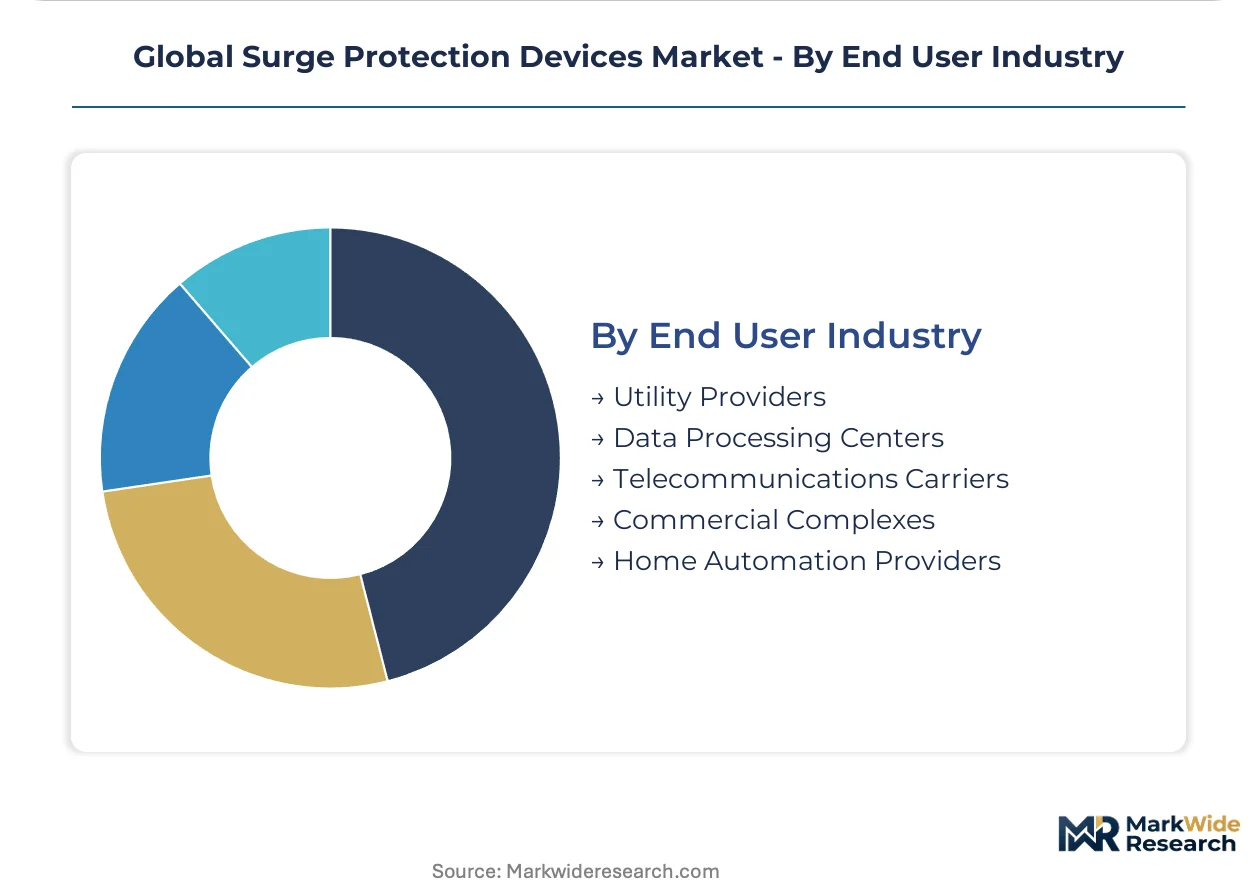
- Utility Providers:Transmission and distribution operators specify arresters for grid modernization mandates across Germany, the United States, and China. Synchronized upgrade timelines are straining varistor supply chains and compressing multi-standard certification windows.
- Data Processing Centers:Hyperscale and colocation operators unbundle surge protection from turnkey electrical contracts, purchasing modules separately through digital procurement platforms. This pattern concentrates specification authority with consulting engineers rather than distributor sales staff.
- Telecommunications Carriers:5G network densification drives demand for compact, high-reliability protection in outdoor small cell installations.
- Commercial Complexes:Design-build contractors in Germany and the United States specify DIN-rail modules for new construction and retrofit applications.
- Home Automation Providers:Smart panel and energy management system integrators source compact SPDs for residential load centers.
Utility providers hold the largest share; data processing centers are expanding most quickly on hyperscale buildout trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NFPA standards revisions in the United States are synchronizing procurement cycles across utility and data center verticals, compressing certification timelines for multi-standard product platforms. Germany's TenneT and China's State Grid Corporation are executing parallel grid modernization mandates that strain varistor supply chains. Industrial clusters in Northern Virginia, Frankfurt, and Shanghai are absorbing disproportionate volumes of hybrid protection systems.
United States
Data center operators in Loudoun County, Virginia mandate remote-monitoring hybrid SPD architectures for new substations. UL 1449 Edition 5 testing requirements have doubled third-party certification costs, squeezing mid-tier suppliers. Texas and California utilities are accelerating arrester replacement cycles under tightened IEEE standards.
Germany
TenneT's transmission network upgrades are pulling forward industrial procurement of specification-grade arresters. IEC 61643 harmonization pressure is forcing faster clamping voltage tolerance compliance. The Kelsterbach data center cluster near Frankfurt is deploying hybrid protection modules at scale for predictive maintenance scheduling.
China
State Grid Corporation procurement timelines have accelerated to lock in pre-change inventory ahead of GB/T 18802 residual voltage revisions. Hunan province's zinc oxide ceramic powder concentration exposes global manufacturers to export quota volatility. Utility-scale solar farms in western provinces are driving Class I SPD demand under tightened standards.
India
The Central Electricity Authority's 2023 distribution transformer protection directive creates compliance-driven entry windows for certified suppliers. Maharashtra and Gujarat industrial corridors are modernizing panel infrastructure with DIN-rail modules. Domestic manufacturers with in-house testing laboratories are capturing specification authority.
South Korea
DC fast-charger OEMs are specifying integrated SPD modules with thermal disconnect features under KBA-equivalent electrical safety mandates. The Seoul Capital Area's EV infrastructure buildout is concentrating demand for transportation-grade protection. Busan-Ulsan manufacturing clusters are sourcing compact modules for charging station integration.
Global Surge Protection Devices Market Competitive Landscape
Diversified electrical conglomerates and specialized protection technology firms split the market between integrated energy management portfolios and modular component expertise. The vendor base stratifies across specification-grade engineering relationships, distribution channel loyalty programs, and direct-to-contractor digital platforms. Three archetypes dominate: integrated energy management providers, modular DIN-rail specialists, and utility-focused arrester manufacturers. Competitive positioning hardens through specification authority capture with consulting engineers and backward integration into varistor-grade ceramic powder production.
Among diversified electrical conglomerates, Schneider Electric, Siemens, and ABB Ltd. exemplify the integrated energy management archetype, anchoring positions through specification-grade relationships with utility providers and industrial EPC firms. Within the specialized tier, Phoenix Contact and DEHN SE occupy positions as modular DIN-rail and protection technology specialists respectively. Littelfuse, Inc. and CITEL Inc. represent the component-focused vector serving telecommunications and industrial verticals. These named entities illustrate how competitive positioning fragments across channel strategies rather than product performance differentiation alone.
| Leading Market Players |
|---|
| ABB Ltd. |
| CITEL Inc. |
| Schneider Electric |
| DEHN SE |
| Legrand |
| Eaton Corporation |
| Phoenix Contact |
| Siemens |
| Littelfuse, Inc. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility amplifies price spreads between standard MOV modules and configured-to-order hybrid systems, compressing margins for distributors while rewarding manufacturers with captive zinc oxide ceramic powder production in China's Hunan province.
Pricing Analysis
Configured-to-order hybrid SPD architectures command substantial premiums over standard MOV modules, with price differentiation anchored in UL 1449 Edition 5 certification tier and embedded remote monitoring firmware. Three-tier pricing structure across premium, standard, and economy levels stratifies by response time specification and thermal disconnect integration. Cost compression in the standard MOV tier is intensifying because mid-tier suppliers absorb doubled third-party certification expenses. Commercial electrical contractors exhibit highest price sensitivity, while hyperscale data center operators prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Contract manufacturing capacity for surge protection device assembly concentrates with Foxconn Interconnect Technology, Jabil Circuit, and regional EMS providers in Dongguan and Penang. Geographic supply concentration centers on China for zinc oxide varistor-grade ceramic powder, Germany for specification-grade engineering, and South Korea for silicon avalanche diode fabrication. Raw material dependencies rest on Hunan province zinc concentrate, Taiwan semiconductor substrates, and Japanese noble gases for gas discharge tube production. Single-source vulnerability in varistor-grade ceramic powder exposes procurement to export quota volatility. Distribution runs through direct-to-contractor digital platforms that bypass traditional electrical distributor networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as procurement authority shifts from distributor sales staff to consulting engineers, creating niche entry points for modular specialists and certification-focused challengers.
For Market Incumbents: Harden specification authority with consulting engineers by embedding diagnostic firmware as standard across hybrid product lines. Deepen backward integration into varistor-grade ceramic powder production to neutralize Hunan supply concentration risk. Capture channel loyalty through integrated energy management portfolios that bundle surge protection with power distribution units. For New Entrants and Emerging Players: Pursue India's CEA compliance-driven entry window by accelerating IEC 61643-11 certification timelines ahead of domestic competitors. Target digital procurement platforms serving commercial electrical contractors in Germany and the United States, where specification authority has decoupled from traditional distribution. Anchor go-to-market strategy through DIN-rail module specialization with thermal disconnect features for EV charging infrastructure. For Investors and Strategic Acquirers: Modular DIN-rail specialists with in-house EMC testing capabilities represent the most defensible acquisition archetype as laboratory backlogs extend certification timelines. Long-term viability rests on capturing specification authority with hyperscale data center operators and utility providers executing synchronized grid modernization mandates. Monitor IEC 61643 and GB/T 18802 harmonization progress as inflection indicator for multi-standard product platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Varistor Ceramics | Captive supply of Hunan-grade zinc oxide powder neutralizes export quota volatility for global manufacturers. |
| Hybrid Architecture Certification Acceleration | Pre-positioning for UL 1449 Edition 5 and IEC 61643-11 convergence captures data center procurement cycles. |
| Digital Platform Channel Partnership | Direct-to-contractor integration in North America bypasses fragmenting electrical distributor networks. |
| EMC Testing Laboratory Acquisition | In-house IEC 61000-4-5 validation capacity eliminates 14-month third-party backlogs delaying product launches. |
| India CEA Compliance Pre-Certification | Early certification alignment with Central Electricity Authority mandates secures distribution transformer protection market entry. |
Research Methodology
The analysis maps surge arrester, MOV module, gas discharge tube, and silicon avalanche diode sub-sectors, each validated through plant engineers at utility providers, procurement leads at hyperscale data center operators, specification engineers at electrical contractors, and aftermarket service heads at industrial EPC firms. Primary interview insights triangulate against IEC certification databases, UL 1449 Edition 5 test records, State Grid Corporation procurement disclosures, and customs trade data for zinc oxide ceramic powder. Bottom-up unit economics and top-down grid infrastructure investment flows converge through iterative stakeholder cross-checking.
Assumptions around IEC 61643 harmonization timelines, GB/T 18802 residual voltage revision implementation, and zinc oxide export quota stability remained fixed across the analysis window, while silicon carbide inverter penetration rates and data center buildout trajectories varied under sensitivity scenarios. Segmentation modeling spans product type, technology tier, application vertical, and end-user industry, with CAGRs derived from deployment volume trajectories and replacement cycle compression. Grid modernization mandate synchronization across Germany, the United States, and China, alongside hyperscale facility certification requirements in Northern Virginia and Frankfurt, anchor demand-side forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, freight rate volatility on Asia-Europe corridors, or rare earth export policy shifts would shift the trajectory. Forecasts reflect these documented assumptions and industry-specific risk factors including EMC testing capacity constraints and regulatory divergence between IEC and national test standards. Quarterly review of certification timeline backlogs, varistor-grade ceramic powder export volumes, and hyperscale data center permitting activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market