
 Lowpass Filters Market | 2026-2036
Lowpass Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Lowpass Filters Market Insights
The EU Green Deal's extended producer responsibility mandates for electronics is shifting procurement criteria across European OEM supply chains. Analog Devices leverages its precision signal-processing heritage to dominate high-end industrial applications. Texas Instruments competes through integrated filter-plus-amplifier solutions that reduce board space in automotive designs. Murata Manufacturing anchors Asian supply networks with ceramic-based passive filter expertise.
A lowpass filter is an electronic circuit that attenuates signal frequencies above a specified cutoff threshold while passing lower-frequency components with minimal insertion loss, typically implemented using resistor-capacitor networks, active operational amplifier stages, or digital signal-processing algorithms. Its primary purpose is to eliminate high-frequency noise, prevent aliasing in data acquisition systems, and ensure spectral purity in RF transmission chains. Passive filter configurations retain cost advantages in high-volume consumer electronics where space constraints are secondary to unit economics. Active Sallen-Key topologies capture expanding margin pools in medical instrumentation and precision test equipment demanding sharper roll-off characteristics. Digital filter implementations are displacing analog equivalents in software-defined radio platforms where reprogrammability outweighs power consumption penalties.
The Federal Communications Commission's emission standards in the United States, the EU's Radio Equipment Directive with CE marking requirements, and China's GB standards administered by the Ministry of Industry and Information Technology collectively dictate spurious suppression levels and interoperability testing protocols that filter manufacturers must satisfy for market access. REACH substance restrictions in Europe further constrain dielectric material selections and plating chemistries in ceramic and thin-film constructions. Stakeholders must weigh the trade-off between analog filter performance maturity and digital implementation flexibility when architecting next-generation RF front ends.
Market Dynamics
5G telecommunications infrastructure buildouts in South Korea are accelerating demand for high-performance RF signal conditioning components, while the EU Green Deal's electronics sustainability mandates push manufacturers toward lead-free solder and reduced-power designs.
Growth Catalysts
- South Korean 5G deployment:Telecommunications infrastructure buildouts in Seoul and Busan are accelerating demand for high-performance RF signal conditioning components with stringent spurious suppression requirements.
- EU Green Deal mandates:Extended producer responsibility regulations are shifting procurement criteria across European OEM supply chains toward lead-free solder and reduced-power filter designs.
- Shenzhen manufacturing concentration:Contract assemblers in China's electronics manufacturing cluster serve global OEMs, creating economies of scale for passive filter component production.
Market Restraints
- Palladium and silver price volatility:Precious metal plating chemistries in ceramic and thin-film constructions face input cost instability that compresses margins on high-volume consumer electronics contracts.
- REACH substance restrictions:European chemical regulations constrain dielectric material selections in ceramic constructions, forcing reformulation cycles that extend qualification timelines.
- Digital filter substitution:Software-defined radio platforms in military and telecommunications applications are displacing analog equivalents where reprogrammability outweighs power consumption penalties.
Strategic Opportunities
- Medical instrumentation expansion:Active Sallen-Key topologies capture expanding margin pools in precision test equipment demanding sharper roll-off characteristics and lower noise floors.
- Automotive radar integration:Texas Instruments and competitors are targeting integrated filter-plus-amplifier solutions that reduce board space in advanced driver-assistance system designs.
- China dual carbon alignment:MIIT energy efficiency standards are creating procurement preferences for reduced-power filter architectures in domestic telecommunications equipment.
Industry Challenges
- RF front-end integration complexity:System architects must weigh trade-offs between analog filter performance maturity and digital implementation flexibility when architecting next-generation architectures.
- Multi-jurisdiction certification timelines:Simultaneous compliance with FCC emission standards, EU Radio Equipment Directive CE marking, and China GB standards extends product launch cycles.
- Thin-film process talent scarcity:Specialized expertise in ceramic and thin-film construction techniques is concentrating at established Asian suppliers, limiting new entrant capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lowpass Filters Market |
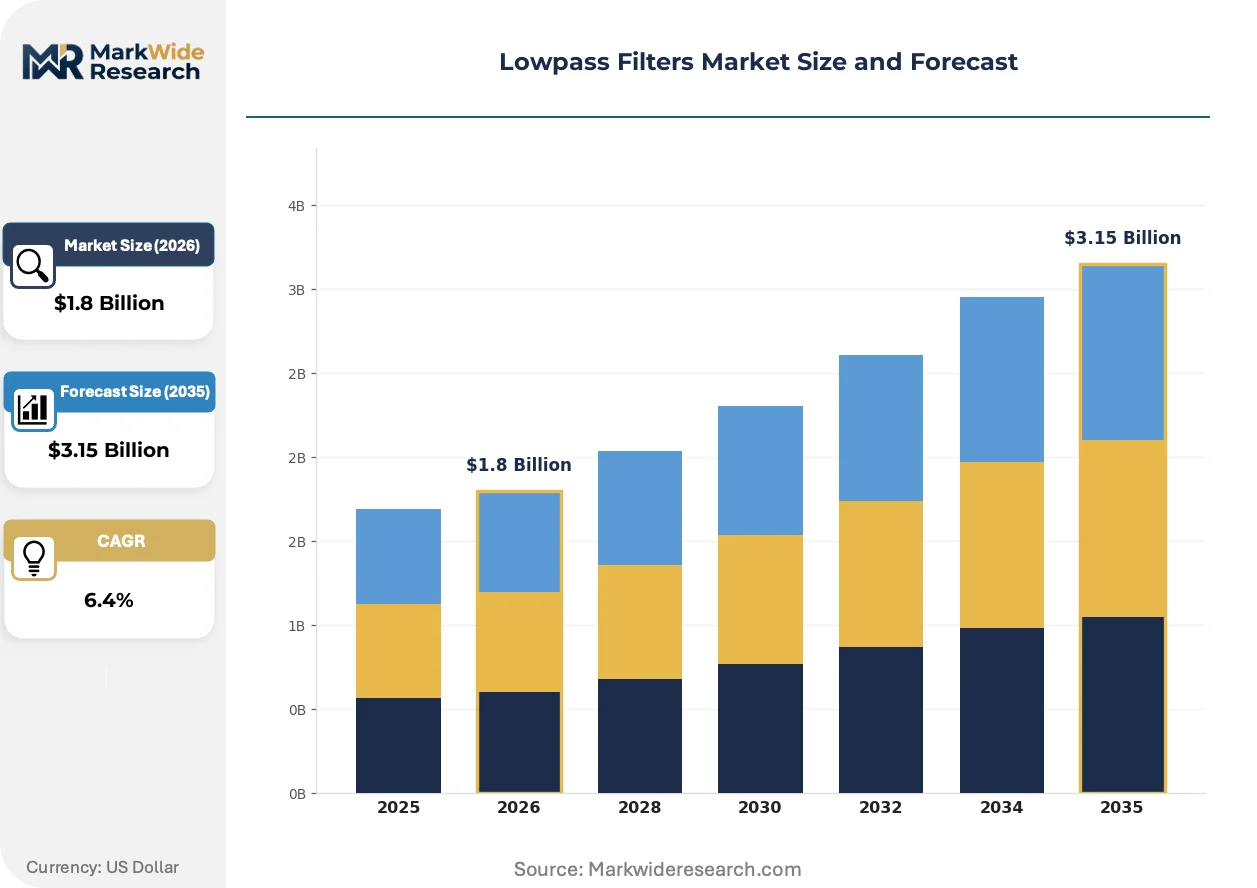
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Filters, Passive Filters, Digital Filters, Analog Filters Technology: RC Circuits, Active Feedback, Sallen-Key, Biquad Application: Audio Processing, RF Communication, Data Acquisition, Signal Conditioning End User: Telecommunications, Consumer Electronics, Automotive, Industrial |
| Companies Covered | Analog Devices, Texas Instruments, Murata Manufacturing, TDK Corporation, Qorvo, Skyworks Solutions, STMicroelectronics, Mini-Circuits, Maxim Integrated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lowpass Filters Market Trends and Innovations
Active filter topologies are unifying signal conditioning functions that previously required discrete component chains, compressing board real estate while sharpening frequency selectivity in precision applications.
Monolithic integration of operational amplifier stages with passive networks is unifying amplification and filtering functions into single-package solutions. Medical instrumentation manufacturers in Germany and Switzerland are adopting these configurations fastest, replacing discrete resistor-capacitor ladders that occupied multiple square centimeters of PCB area. The structural consequence is unifying what were separate component procurement decisions into single-source vendor relationships with analog semiconductor specialists.
REACH substance restrictions in Europe are constraining dielectric material selections and plating chemistries in ceramic and thin-film constructions. Manufacturers must reformulate formulations containing restricted substances or relocate production to jurisdictions with less stringent chemical regulations. Passive filter suppliers serving automotive and industrial OEMs are responding by accelerating qualification of alternative ceramic compositions at facilities in Japan and South Korea.
Buyer consolidation among contract electronics manufacturers is compressing vendor negotiation cycles and unbundling after-sales technical support from component pricing. Shenzhen-based assemblers serving global OEMs now specify filter performance parameters directly rather than deferring to subsystem suppliers. This pattern is most visible in telecommunications infrastructure procurement, where five contract manufacturers account for the majority of RF component demand.
Lowpass Filters Market Segmentation
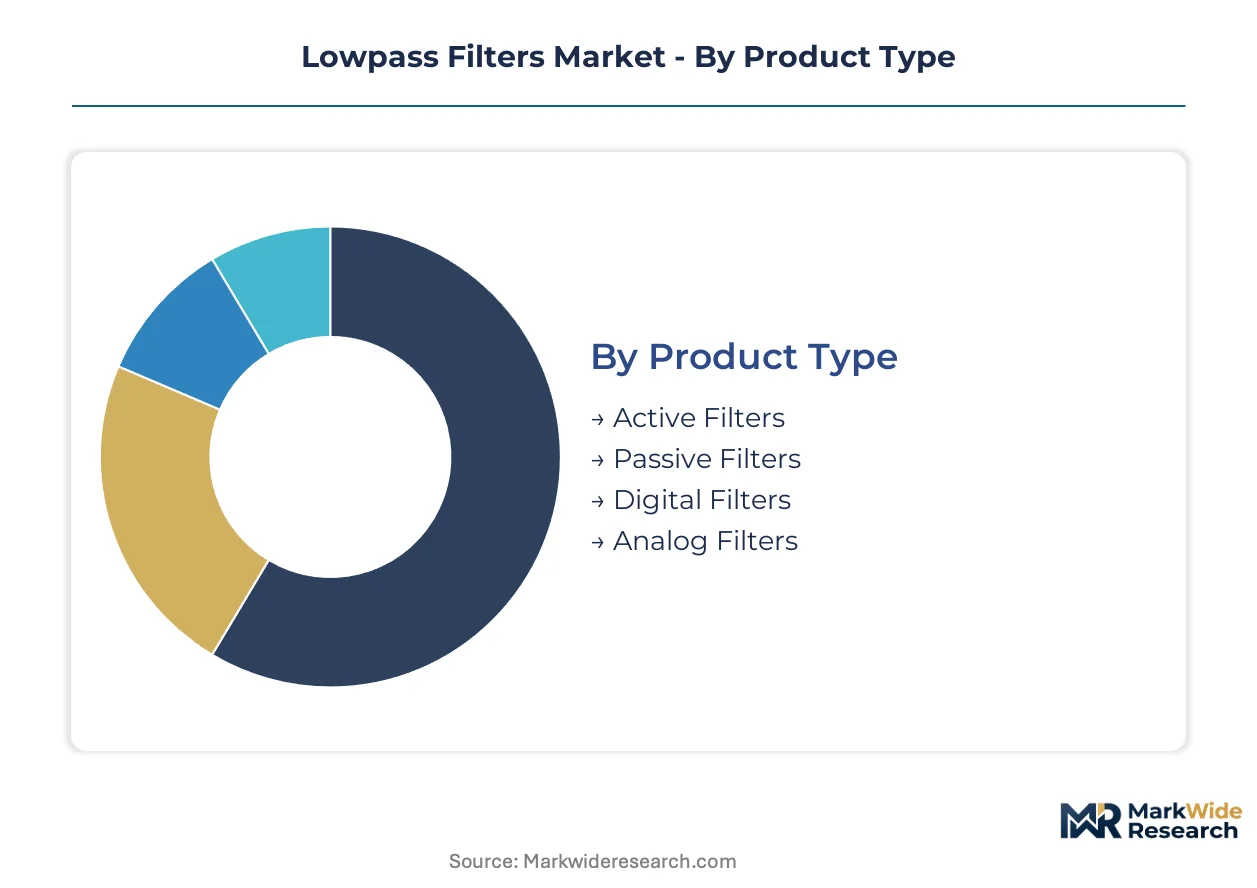
Lowpass filter architectures diverge sharply across performance tiers and integration requirements. Procurement decisions hinge on balancing passive simplicity against active precision and digital flexibility.
Product Type:
Volume concentrates in legacy passive configurations while premium pools form around digitally programmable variants.
- Active Filters:Operational amplifier stages with RC networks deliver precise gain control and sharp roll-off characteristics. Demand concentrates in German and Swiss medical instrumentation manufacturers replacing discrete component ladders with single-package solutions. MIIT energy efficiency standards in China are accelerating procurement preferences for reduced-power active architectures in domestic telecommunications equipment.
- Passive Filters:Resistor-capacitor and inductor-capacitor networks without amplification stages dominate high-volume consumer electronics where unit economics outweigh space constraints. Shenzhen contract assemblers serving global OEMs specify passive filter parameters directly, compressing vendor negotiation cycles.
- Digital Filters:Software-implemented algorithms in DSP cores or FPGAs enable reprogrammable frequency response without hardware redesign. Military and telecommunications platforms in South Korea are displacing analog equivalents where spectral agility outweighs power penalties.
- Analog Filters:Continuous-time signal processing circuits retain performance maturity in RF front ends where latency budgets preclude digital conversion. FCC emission standards and EU Radio Equipment Directive CE marking requirements sustain qualification investment in proven analog topologies.
Today's leader: Passive Filters. Tomorrow's challenger: Digital Filters.
Technology:
Cost tier stratification separates commodity RC implementations from precision active topologies commanding design service premiums.
- RC Circuits:Simple resistor-capacitor networks form the foundational passive implementation with minimal component count. Consumer electronics manufacturers in Shenzhen prioritize these configurations for cost-sensitive audio and power supply applications.
- Active Feedback:Operational amplifier-based designs with negative feedback enable tunable Q factors and gain without inductors. RF communication infrastructure in Seoul and Busan leverages these for intermediate frequency stages requiring stable center frequencies.
- Sallen-Key:Unity-gain active topology cascades second-order sections for steep roll-off with minimal sensitivity to component tolerances. German precision test equipment manufacturers are adopting Sallen-Key configurations fastest for their lower noise floors and sharper selectivity.
- Biquad:State-variable active filter architecture provides independent control over frequency, Q, and gain parameters. Industrial automation OEMs favor biquad implementations where multiple filter characteristics must track across temperature extremes.
RC Circuits anchor unit economics. Sallen-Key captures margin expansion in precision segments.
Application:
Customer type fragmentation splits between consumer volume plays and industrial specification-driven procurement.
- Audio Processing:Anti-aliasing and reconstruction filtering for analog-to-digital and digital-to-analog conversion stages. Professional audio equipment manufacturers in Japan specify tight passband ripple tolerances for studio monitoring applications.
- RF Communication:Spurious suppression and image rejection in transmitter and receiver signal chains. South Korean 5G infrastructure buildouts are accelerating demand for high-performance RF signal conditioning components with stringent suppression requirements.
- Data Acquisition:Anti-aliasing protection preceding analog-to-digital converters in sensor interfaces and measurement systems. Industrial IoT deployments across China's manufacturing belt require robust filtering for noisy factory environments.
- Signal Conditioning:Sensor output filtering and noise reduction in measurement and control systems. Automotive radar integration programs are targeting combined filter-plus-amplifier solutions that reduce board space in advanced driver-assistance system designs.
RF Communication commands specification premiums. Audio Processing defends volume base.
End User:
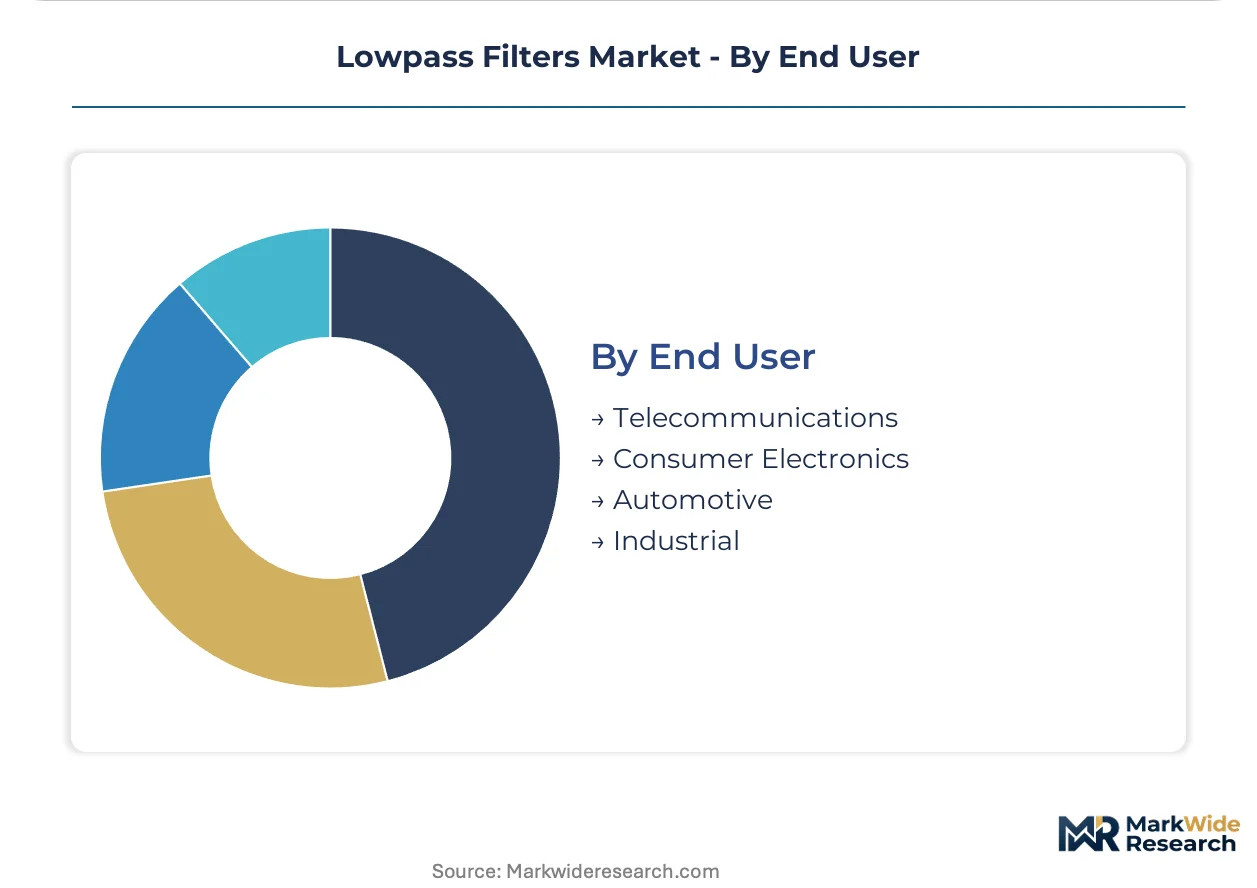
Supply concentration patterns align with geographic manufacturing clusters and regulatory jurisdiction density.
- Telecommunications:Base station and network infrastructure equipment requiring carrier-grade spectral purity. EU Green Deal extended producer responsibility mandates are shifting European OEM procurement criteria toward lead-free solder and reduced-power designs.
- Consumer Electronics:Smartphones, wearables, and home entertainment systems where miniaturization and cost dominate. REACH substance restrictions constrain dielectric material selections in ceramic constructions serving this segment.
- Automotive:Advanced driver-assistance systems, infotainment, and power electronics with AEC-Q200 qualification requirements. Texas Instruments and competitors target integrated solutions that compress board real estate in space-constrained vehicle architectures.
- Industrial:Factory automation, process control, and test equipment demanding extended temperature ranges and long-term availability. Thin-film process expertise concentrates at established Asian suppliers, limiting new entrant capabilities in precision industrial grades.
Telecommunications sets performance benchmarks. Automotive is climbing fastest on electrification and autonomy investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thin-film process engineers concentrate at established Asian suppliers, limiting new entrant capabilities while anchoring precision filter production in specific metropolitan clusters. Shenzhen contract assemblers serve global OEMs directly. Seoul and Busan infrastructure buildouts accelerate demand for RF signal conditioning.
United States
Defense and aerospace prime contractors in California and Texas drive demand for military-grade spectral purity components. FCC emission standards dictate spurious suppression levels for all RF equipment market access. Boston-area precision instrumentation manufacturers specify active Sallen-Key topologies for medical device applications.
China
MIIT energy efficiency standards create procurement preferences for reduced-power filter architectures in domestic telecommunications equipment. Dual carbon alignment policies pressure manufacturers toward lead-free solder transitions. Shenzhen electronics manufacturing cluster concentrates contract assembler activity serving global OEM volume requirements.
South Korea
Seoul and Busan 5G infrastructure buildouts accelerate demand for high-performance RF signal conditioning components with stringent suppression requirements. MFDS medical device regulations shape dielectric material selections for healthcare instrumentation. Daegu-Gyeongbuk manufacturing belt hosts ceramic substrate fabrication for passive filter networks.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify AEC-Q200 qualified components for advanced driver-assistance system integration. REACH substance restrictions constrain plating chemistries in ceramic and thin-film constructions. Stuttgart precision test equipment manufacturers adopt active Sallen-Key configurations for sharper roll-off characteristics.
Japan
METI industrial policy supports domestic production of high-reliability passive components for automotive and industrial applications. JIS standards govern dielectric material specifications in ceramic filter constructions. Kyoto-Osaka manufacturing corridor retains specialized expertise in monolithic ceramic fabrication for high-frequency applications.
Lowpass Filters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the filter value chain. Integrated device manufacturers with captive fabrication capacity face pressure from fabless specialists outsourcing to foundry partners. Three archetypes dominate: analog semiconductor conglomerates with signal-processing heritage, passive component specialists with ceramic expertise, and RF front-end integrators targeting module-level solutions. Capacity expansion in Asian ceramic substrate facilities and strategic partnerships between filter suppliers and contract assemblers represent the dominant competitive moves reshaping supply relationships.
Within the analog semiconductor tier, Analog Devices and Texas Instruments exemplify integrated signal-conditioning strategies that compress board real estate through unified amplification and filtering functions. Murata Manufacturing anchors the passive component specialist archetype with ceramic-based expertise concentrated in Asian supply networks. These three companies occupy positions spanning precision industrial applications, automotive integration programs, and high-volume consumer electronics procurement respectively.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| Murata Manufacturing |
| TDK Corporation |
| Qorvo |
| Skyworks Solutions |
| STMicroelectronics |
| Mini-Circuits |
| Maxim Integrated |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-based contract assemblers unbundling after-sales technical support from component pricing are forcing passive filter suppliers to absorb service costs or relocate production to lower-cost jurisdictions, compressing margins on high-volume consumer electronics contracts while creating procurement leverage for buyers.
Pricing Analysis
Bundled engineering support versus unbundled component-only pricing splits the market between premium active filter suppliers and commodity passive producers. Pricing stratifies across precision medical-grade, industrial-qualified, and economy consumer tiers, with REACH compliance costs and precious metal volatility driving differentiation. Cost compression in consumer-grade ceramic constructions is intensifying because palladium and silver plating chemistries face input instability. Contract electronics manufacturers in Shenzhen exhibit the highest price sensitivity, while German precision test equipment OEMs prioritize roll-off performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor hub-and-spoke patterns serving Asian manufacturing clusters. Production concentrates in China, Japan, and South Korea, with thin-film process expertise concentrating at established Asian suppliers. Raw material dependencies include palladium and silver plating chemistries, alumina ceramic substrates, and precision-wound inductor wire. Single-source vulnerability in specialized ceramic fabrication creates structural risk. Distribution runs through contract assembler direct procurement channels that bypass traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal extended producer responsibility mandates impose lead-free solder and reduced-power design costs on European suppliers, while Chinese manufacturers capture margin through MIIT energy efficiency procurement preferences without equivalent compliance burdens.
For Market Incumbents: Cement dominance in high-end industrial applications by deepening captive supply of precision thin-film ceramic substrates and accelerating qualification of alternative dielectric formulations ahead of REACH substance restriction expansions. Digital filter substitution in software-defined radio platforms represents the primary substitution threat requiring defensive R&D investment in reprogrammable analog-digital hybrid architectures. For New Entrants and Emerging Players: Enter via medical instrumentation expansion in Germany and Switzerland where active Sallen-Key topology demand outpaces established supplier capacity, and via automotive radar integration programs seeking combined filter-plus-amplifier solutions. The precision test equipment segment offers the most penetrable white space due to incumbent capacity constraints and specification complexity barriers. A technical sales force embedding with Bavarian automotive OEM engineering teams provides the strongest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless filter design specialists possessing RF front-end integration capabilities but lacking captive fabrication capacity, as analog semiconductor conglomerates seek module-level solution providers. Long-term viability hinges on positioning within software-defined radio migration paths rather than legacy analog replacement cycles. Thin-film process talent scarcity at established Asian suppliers signals inflection when acquisition multiples compress for precision passive specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Ceramic Substrate Facilities | Murata Manufacturing and TDK Corporation anchor Asian supply networks with expanded monolithic ceramic fabrication for high-frequency 5G applications. |
| Backward Integration into Thin-Film Process Equipment | Specialized expertise in ceramic construction techniques concentrates at Japanese and South Korean suppliers, limiting new entrant replication. |
| Strategic Partnership with Contract Assemblers | Shenzhen-based assemblers serving global OEMs now specify filter parameters directly, compressing traditional distributor channels. |
| Green Manufacturing Transition | EU Green Deal mandates push manufacturers toward lead-free solder and reduced-power designs across European OEM supply chains. |
| Product Launch of Digital-Analog Hybrid Architectures | Software-defined radio platforms in South Korean military and telecommunications applications displace pure analog equivalents where spectral agility outweighs power penalties. |
Research Methodology
Coverage spans the United States, China, South Korea, Germany, and Japan, with primary inputs from each market's telecommunications infrastructure developers, medical instrumentation manufacturers, automotive OEM procurement teams, and contract electronics assemblers. The approach combines structured interviews with RF system architects, passive component procurement leads, and thin-film process engineers with secondary validation through FCC emission standard filings, EU Radio Equipment Directive CE marking databases, MIIT GB standard publications, and customs trade data for ceramic filter imports. Bottom-up demand modeling from end-use application consumption triangulates against top-down supply-side capacity assessments across Asian ceramic substrate facilities.
Granularity-level framing models active, passive, digital, and analog filter architectures at the product-type dimension; RC circuit, active feedback, Sallen-Key, and biquad implementations at the technology dimension; and telecommunications, consumer electronics, automotive, and industrial end-users at the customer-segment dimension. CAGRs derive from segment-level growth rate assumptions weighted by base-year revenue allocation, with RF communication infrastructure buildout intensity, REACH substance restriction compliance timelines, and software-defined radio penetration rates serving as key forecast inputs across the projection horizon.
Inputs from telecommunications equipment manufacturers and precision instrumentation OEMs were available through the study window; gaps in contract assembler inventory positioning data introduce uncertainty bands around short-term demand fluctuation estimates. Forecasts reflect documented assumptions regarding 5G deployment cadence, regulatory qualification timelines, and precious metal price trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Power Amplifier Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Global Suction Tube Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Automation Component Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Film Capacitor Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Structural Electronics Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Americas MPU Market