
 Global Circuit Breakers Market | 2026-2036
Global Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Circuit Breakers Market Analysis
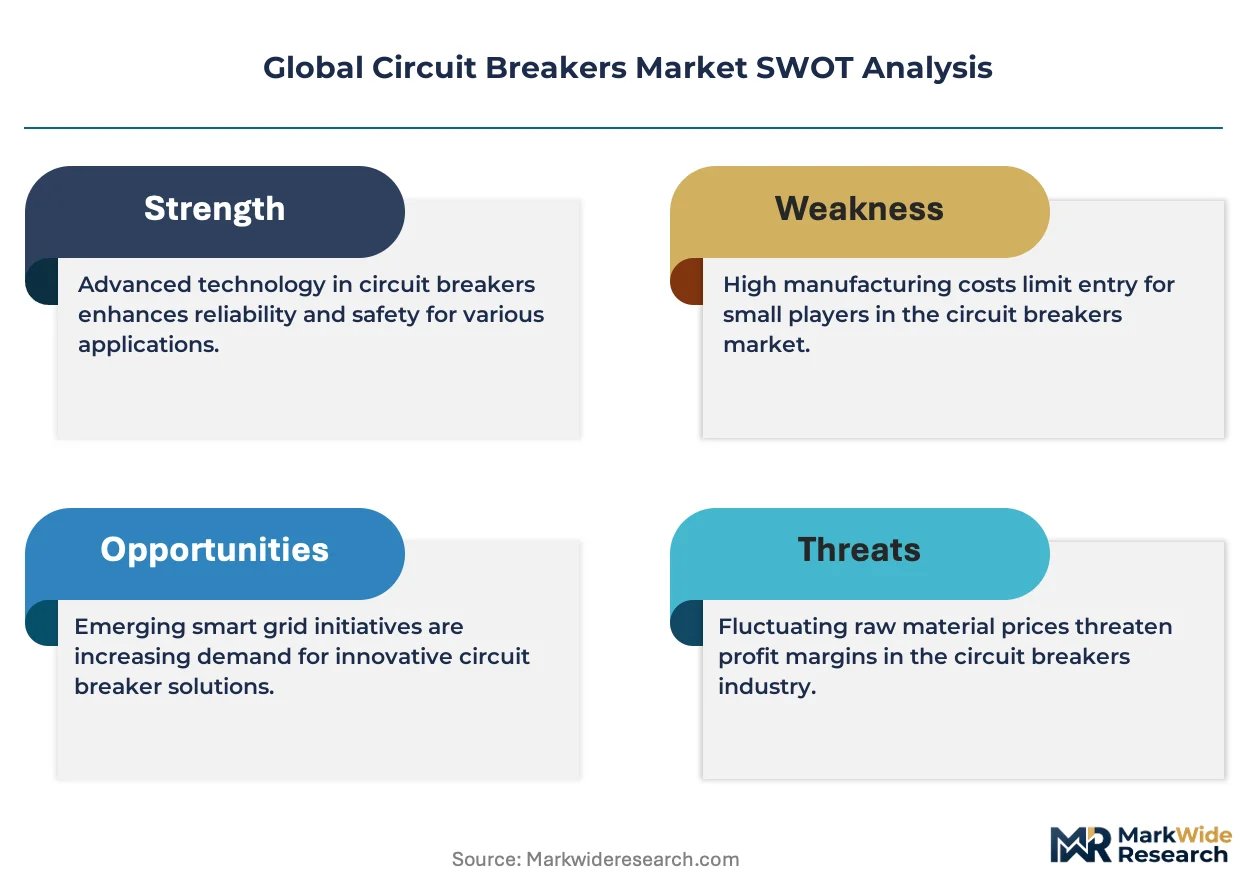
A widening capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in circuit breaker supply. ABB Ltd leverages captive semiconductor fabrication for solid-state breaker modules, sustaining technology leadership in medium-voltage applications. Siemens AG anchors European utility contracts through extensive testing laboratory networks, while Chint Electric competes on cost-optimized molded case platforms across emerging Asian infrastructure markets.
A circuit breaker is an electromechanical or solid-state protective device designed to interrupt fault currents exceeding rated thresholds, typically specified by breaking capacity in kiloamperes and voltage class. Its primary purpose is to prevent thermal damage to conductors and equipment by automatically isolating overloaded or short-circuit conditions within electrical distribution systems. Molded case circuit breakers occupy the largest volume share across commercial and light industrial installations, where standardization drives procurement efficiency. Air circuit breakers command premium positioning in heavy industrial and utility segments due to higher interrupting ratings and maintainable arc chute assemblies. Electronic trip unit technology is displacing thermal magnetic mechanisms in precision-critical applications, creating margin concentration among firmware-capable suppliers.
The US National Electrical Code, enforced by local authorities having jurisdiction, mandates arc fault circuit interrupter protection in residential branch circuits, directly stimulating miniature circuit breaker demand. European REACH and RoHS frameworks restrict hazardous substances in breaker housings and contact materials, compelling reformulation of thermoset composites and silver alloy contacts. Stakeholders must monitor evolving grid code harmonization between IEEE and IEC standards, as divergence in fault current testing protocols threatens to fragment product certification requirements and complicate multinational deployment strategies.
Market Dynamics
Solid-state interruption technology is bifurcating procurement patterns between legacy electromechanical suppliers and semiconductor-capable entrants, forcing capital reallocation toward silicon carbide fabrication and embedded firmware development.
Growth Catalysts
- Grid Modernization Mandates:China's dual carbon goals and India's National Electricity Policy are accelerating high-voltage switching equipment procurement for renewable integration corridors.
- Residential Safety Codes:The US National Electrical Code mandates arc fault circuit interrupter protection in new residential branch circuits, directly stimulating miniature circuit breaker volume.
- Silver Alloy Contact Materials:Advanced metallurgy in vacuum interrupters extends operational life cycles for medium-voltage distribution networks.
Market Restraints
- Copper and Rare Earth Volatility:Contact assembly and magnetic core materials face input cost swings that compress assembler margins.
- IEC-UL Protocol Divergence:Fault current testing standard fragmentation between European and North American certification bodies complicates multinational product deployment.
- Integrated Semiconductor Supply:Captive silicon carbide wafer production concentrates among a limited supplier base, constraining solid-state breaker module availability.
Strategic Opportunities
- Data Center Power Distribution:Hyperscale facility construction in Germany and the Netherlands creates demand for intelligent rack-level protection with remote monitoring capabilities.
- EU Green Deal Alignment:F-Gas Regulation phase-down and circular economy requirements favor refurbishment services and recyclable thermoset housing designs.
- Digital Twin Integration:Convergence of breaker telemetry with asset management software enables predictive maintenance contracts in industrial verticals.
Industry Challenges
- Firmware Development Talent:Electronic trip unit programming and cybersecurity hardening require scarce embedded systems engineers.
- Multi-Standard Certification Timelines:Simultaneous IEC 60947 and UL 489 approval processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Circuit Breakers Market |
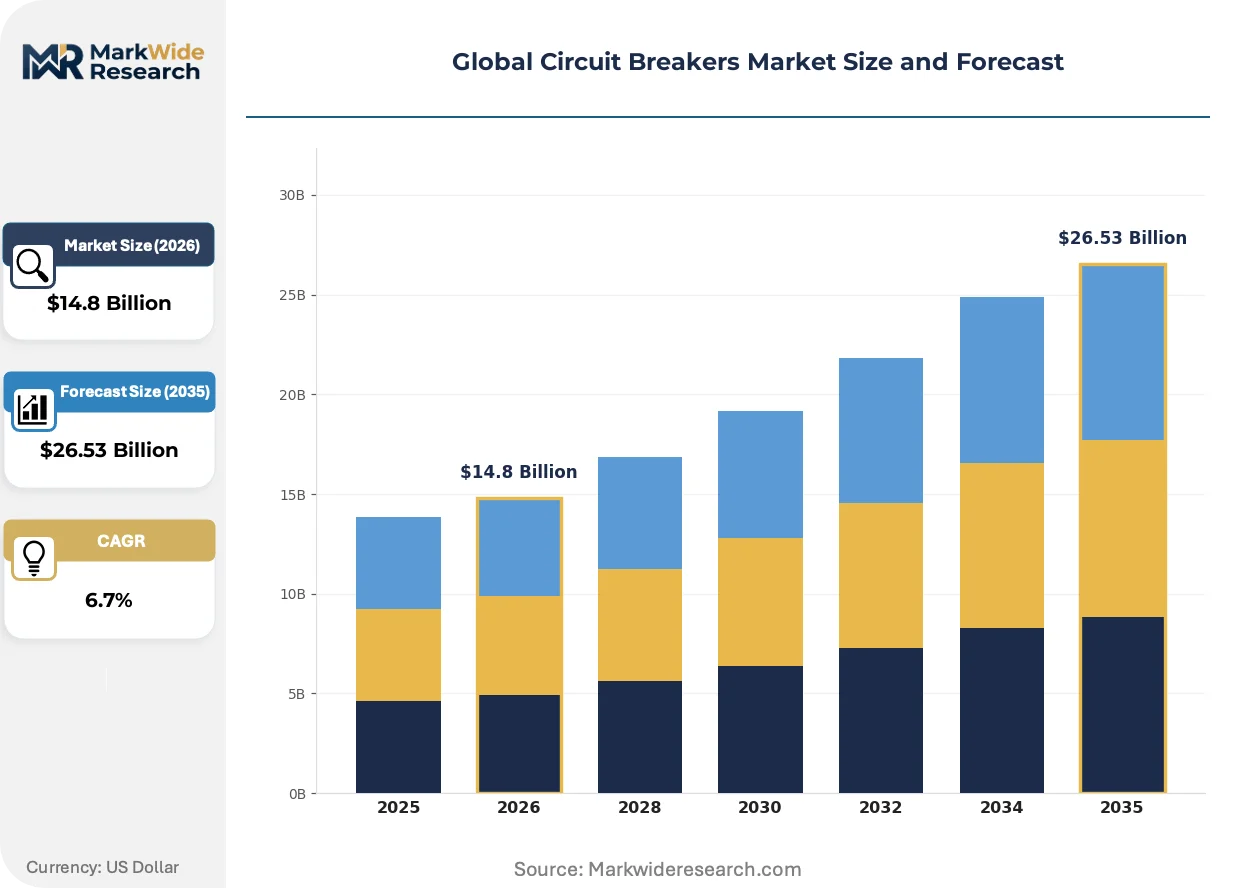
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Molded Case Circuit Breaker, Air Circuit Breaker, Earth Leakage Circuit Breaker End User: Residential, Commercial, Industrial, Utility Installation Type: Panel Mounted, DIN Rail Mounted, Surface Mounted, Flush Mounted Technology: Hydraulic Magnetic, Electronic, Hybrid, Thermal Magnetic |
| Companies Covered | Eaton Corporation plc, General Electric Company, ABB Ltd, Chint Electric, Toshiba Corporation, Schneider Electric SE, Mitsubishi Electric Corporation, Larsen & Toubro Limited, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Circuit Breakers Market Emerging Trajectories
Electrification intensity across transportation, heating, and industrial processes is expanding breaker duty cycles and fault current magnitudes beyond legacy equipment ratings.
Silicon carbide power semiconductors enable sub-millisecond fault interruption without mechanical wear. Data center operators and electric vehicle charging infrastructure developers are adopting these modules for high-frequency switching operations. The technology is bifurcating supplier capabilities between electromechanical incumbents and semiconductor-native entrants.
REACH and RoHS frameworks restrict hazardous substances in breaker housings and contact materials across European markets. Manufacturers are reformulating thermoset composites and migrating to cadmium-free silver alloys to maintain market access. Molded case product lines face the steepest compliance-driven redesign cycles.
Utility procurement departments are unbundling after-sales service contracts from equipment purchases. European transmission system operators now separately negotiate maintenance, spare parts, and firmware upgrade agreements. This behavioral shift compresses upfront equipment margins while expanding recurring revenue pools for service-capable suppliers.
Global Circuit Breakers Market Segmentation
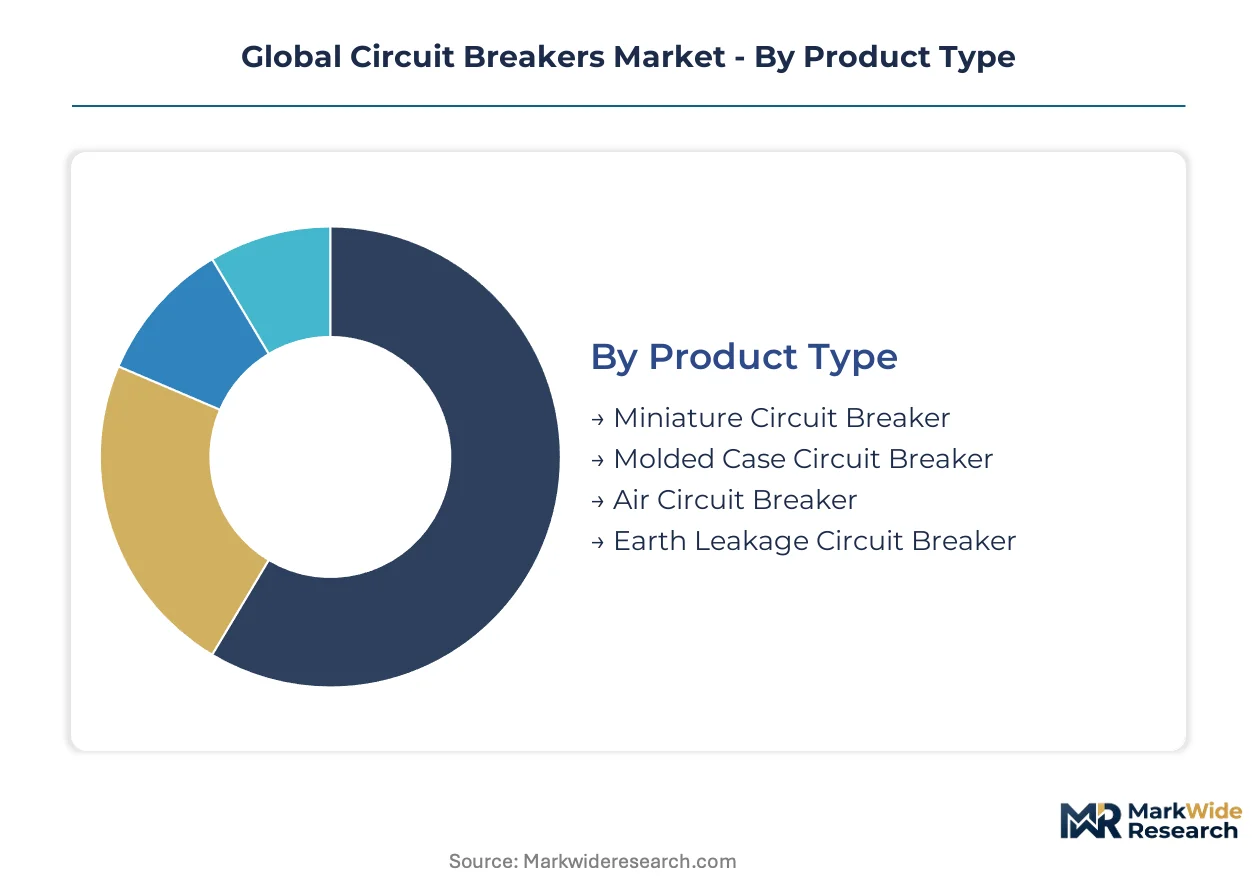
Segmentation in circuit breakers tracks divergent margin structures across electromechanical and solid-state technologies. Procurement patterns split between standardized volume products and engineered solutions requiring certification complexity. Understanding these divides exposes where supplier capabilities concentrate versus where price competition erodes returns.
Product Type:
Margin pools concentrate in medium-voltage platforms where arc interruption engineering creates defendable differentiation.
- Molded Case Circuit Breaker:Thermoset composite housings enclose thermal-magnetic or electronic trip mechanisms rated up to 2,500 amperes. Commercial and light industrial installations in India and Germany drive procurement through standardization economies and IEC 60947-2 certification requirements.
- Air Circuit Breaker:Open-frame designs with maintainable arc chute assemblies deliver interrupting capacities exceeding 100 kiloamperes for heavy industrial and utility applications. European transmission system operators specify these for primary distribution substations where fault current magnitudes demand serviceable contact systems.
- Miniature Circuit Breaker:DIN-rail mountable units protect residential branch circuits up to 125 amperes. US National Electrical Code AFCI mandates sustain volume in North American housing construction.
- Earth Leakage Circuit Breaker:Residual current detection modules prevent electrocution hazards in wet-location installations. Indian urban electrification programs and European workplace safety directives stimulate replacement cycles.
Air circuit breakers hold installed capacity in utility infrastructure. Molded case circuit breakers are rotating up the share rankings through Asian manufacturing scale.
End User:
Volume concentration sits with residential and commercial segments, while margin capture favors industrial and utility procurement.
- Industrial:Process manufacturing, mining, and oil & gas operations specify high-duty-cycle breakers with electronic trip programming and communication capabilities. German chemical complexes and Chinese steel mills drive demand for predictive maintenance integration.
- Utility:Transmission and distribution system operators procure high-voltage switching equipment for grid modernization and renewable integration corridors. China's State Grid and India's Power Grid Corporation anchor procurement for 72.5kV and above ratings.
- Commercial:Office buildings, retail centers, and healthcare facilities prioritize compact footprint and selective coordination. Standardized molded case platforms dominate through distributor channel procurement.
- Residential:Single-family and multi-family construction consumes miniature circuit breakers with AFCI and GFCI protection. US housing starts and Indian affordable housing programs shape regional demand patterns.
Utility contracts sustain premium pricing through service bundling. Industrial segments are expanding fastest through digital twin integration requirements.
Installation Type:
Mounting configuration determines channel access and aftermarket attachment rates.
- DIN Rail Mounted:Standardized 35mm rail systems enable rapid installation and modular expansion in industrial control panels and commercial distribution boards. European IEC 60715 compliance drives specification lock-in.
- Panel Mounted:Bolted-frame designs secure high-current breakers in switchgear assemblies requiring seismic rating and busbar integration. US utility substations and Chinese manufacturing facilities specify these for structural integrity.
- Surface Mounted:Enclosed housings protect breakers in outdoor or corrosive environments. Indian infrastructure and Middle East construction projects drive tropicalized enclosure demand.
- Flush Mounted:Recessed installation in walls or columns serves aesthetic requirements in commercial and high-end residential settings. European architectural specifications favor these for space optimization.
DIN rail mounting holds installed capacity across retrofit markets. Panel mounting is climbing fastest through utility-scale renewable integration projects.
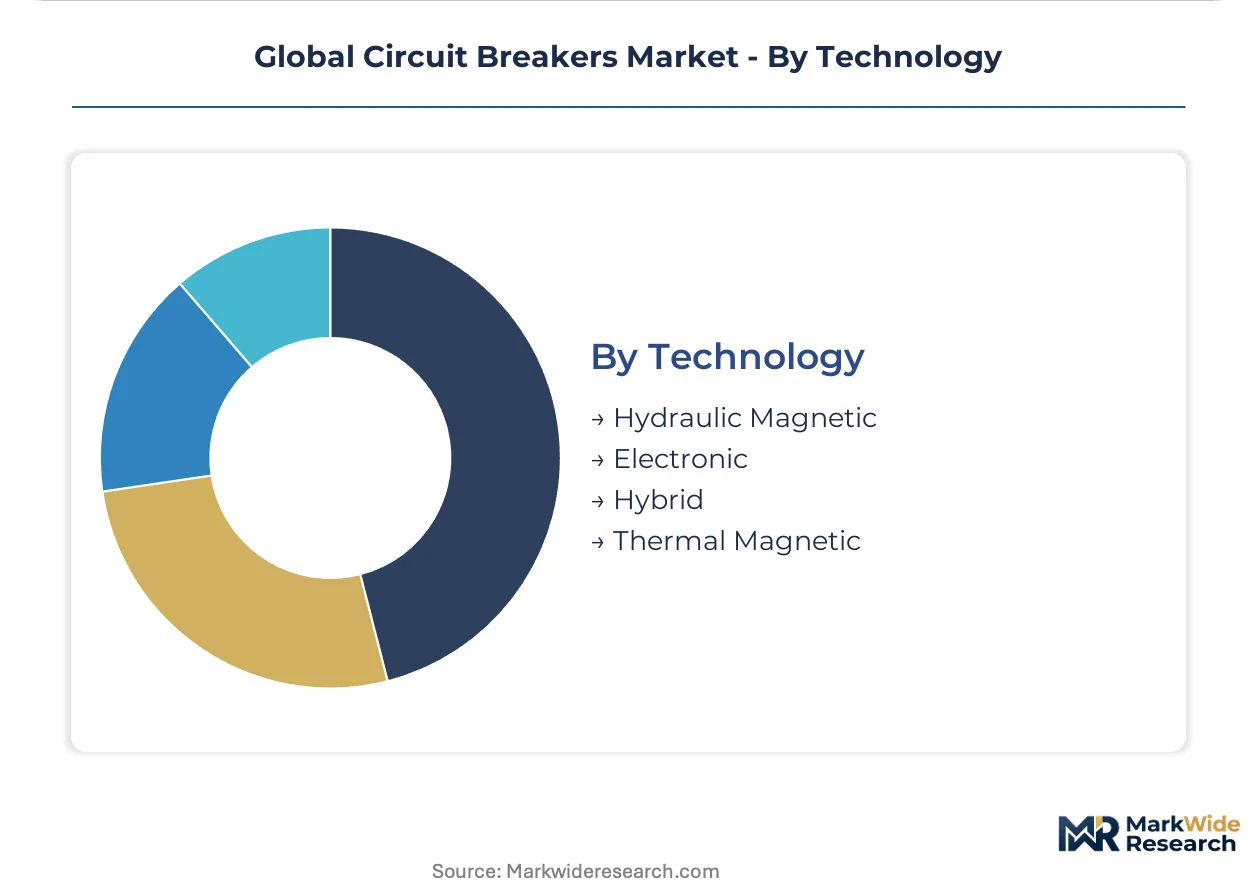
Technology:
Capability bifurcation separates firmware-enabled suppliers from thermal-magnetic assemblers.
- Electronic:Microprocessor-based trip units enable adjustable time-current curves, zone-selective interlocking, and communication protocols. Data center operators in Germany and the Netherlands specify these for intelligent power distribution.
- Thermal Magnetic:Bimetallic strips and magnetic solenoids provide cost-effective overcurrent protection without external power requirements. Residential and standard commercial applications sustain volume through price-sensitive procurement.
- Hydraulic Magnetic:Temperature-independent magnetic delay mechanisms suit marine, military, and extreme environment applications. Offshore platforms and defense contractors specify these for environmental immunity.
- Hybrid:Combinations of electronic sensing with electromechanical interruption bridge cost and precision requirements. Emerging Asian infrastructure markets adopt these for mid-tier industrial applications.
Electronic trip units hold margin concentration through firmware differentiation. Hybrid architectures are gaining share fastest in cost-optimized precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in high-voltage switching equipment tilt toward surplus positions in China and Germany, while India and the United States absorb significant inbound shipments to satisfy grid modernization timelines. Trade flows concentrate where domestic fabrication capacity lags renewable integration procurement schedules.
China
State Grid Corporation drives procurement of 72.5kV and above ratings for ultra-high-voltage transmission corridors connecting western renewable bases to eastern load centers. The dual carbon goals mandate accelerate substation automation upgrades. Manufacturing clusters in Jiangsu and Zhejiang provinces supply molded case platforms for domestic infrastructure and Southeast Asian export markets.
United States
Utility-scale solar and offshore wind interconnection projects stimulate demand for medium-voltage vacuum interrupters across Texas and California independent system operator territories. The National Electrical Code AFCI mandates sustain miniature circuit breaker volume in residential construction. Midwest industrial corridors specify electronic trip units for predictive maintenance integration in automotive and food processing facilities.
Germany
Transmission system operators unbundle service contracts from equipment purchases, compressing upfront margins while expanding recurring revenue pools. The EU F-Gas Regulation phase-down favors refurbishment services for existing switchgear installations. Industrial clusters in North Rhine-Westphalia deploy intelligent rack-level protection in hyperscale data centers near Frankfurt and Amsterdam connectivity hubs.
India
Power Grid Corporation anchors procurement for renewable integration corridors under the National Electricity Policy. The Bureau of Indian Standards mandates IEC 60947-2 certification for imported switching equipment, extending approval timelines for non-domestic suppliers. Manufacturing concentrations in Pune and Chennai produce cost-optimized molded case platforms for urban electrification programs and Middle East export contracts.
Japan
Earthquake-resistant specifications for nuclear restart facilities and urban substations sustain demand for hydraulic magnetic mechanisms with environmental immunity. The Ministry of Economy, Trade and Industry promotes solid-state interruption technology demonstration projects. Industrial concentrations in Osaka and Nagoya supply hybrid architectures for precision-critical manufacturing automation.
Global Circuit Breakers Market Vendor Landscape
Concentration sits with diversified electrical equipment conglomerates possessing captive semiconductor fabrication and extensive testing laboratory networks. The vendor base stratifies across three tiers: integrated manufacturers with upstream silicon carbide control, regional assemblers competing on cost-optimized platforms, and semiconductor-native entrants disrupting legacy electromechanical architectures. Dominant competitive moves include strategic partnerships for firmware development and geographic expansion through localized certification acquisition.
Within the integrated manufacturer tier, ABB Ltd and Siemens AG exemplify archetypes combining captive supply chain control with service bundling capabilities. Chint Electric occupies a position among Asia-based cost-optimized platform specialists. These three anchors illustrate how competitive positioning diverges between firmware-enabled precision suppliers and scale-driven standard product fabricators across divergent procurement channels.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| General Electric Company |
| ABB Ltd |
| Chint Electric |
| Toshiba Corporation |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Larsen & Toubro Limited |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
IEC 60947-2 and UL 489 certification tiers gate both supplier qualification and price differentiation simultaneously, creating parallel barriers that compress margins for uncertified assemblers while sustaining premiums for firmware-capable integrated manufacturers. Buyers face stark trade-offs between standardized molded case platforms and configured-to-order electronic trip units.
Pricing Analysis
Configured-to-order pricing for electronic trip units commands spreads of 40-60% above standard thermal-magnetic platforms, with premium-mid-economy pricing differentiation anchored in certification grade and after-sales service bundling. Project-based contract structures dominate utility procurement, while distributor channels move transactional volume for residential and commercial segments. Price erosion runs through Asian molded case assemblers facing copper and silver alloy cost compression. Residential contractors exhibit highest price sensitivity; data center operators and transmission system operators demonstrate lowest sensitivity due to predictive maintenance integration requirements.
Supply Chain Analysis
Silicon carbide wafer fabrication concentrates in Japan, Germany, and the United States, creating single-source vulnerability for solid-state breaker module production. Contact assembly draws from Chinese silver alloy processing and Chilean copper cathode supply. Tariff exposure on magnetic core laminations threatens margin stability for European and North American electromechanical manufacturers. Distribution runs through authorized distributor networks for standard products, while engineered solutions deploy through direct specification engineering with utility and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology bifurcation between electromechanical legacy and solid-state architectures fragments procurement patterns, creating service-layer and geographic niches for specialized entrants. Firmware development talent scarcity further splinters competitive boundaries.
For Market Incumbents: Secure captive silicon carbide supply through backward integration or long-term offtake agreements with Japanese and German wafer fabricators. Invest in cybersecurity-hardened firmware development teams to defend against semiconductor-native entrants disrupting medium-voltage applications. Certification investment in simultaneous IEC-UL approval processes protects multinational contract eligibility.
For New Entrants and Emerging Players: Firmware upgrade and predictive maintenance service layers present under-served recurring revenue pools where European transmission system operators unbundle contracts from equipment purchases. Target Indian urban electrification programs and Middle East export corridors with cost-optimized hybrid architectures bridging thermal-magnetic reliability and electronic precision. Go-to-market through localized certification acquisition accelerates Bureau of Indian Standards approval timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state breaker sub-segments as silicon carbide fabrication and embedded systems engineering concentrate capability among limited suppliers. Long-term viability favors integrated manufacturers with upstream semiconductor control and extensive testing laboratory networks. Acquisition target archetype: regional assemblers possessing IEC certification infrastructure but lacking firmware capabilities, positioned for technology injection. Signal to watch: utility procurement unbundling rates accelerating beyond European markets into Asian grid modernization programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Supply | Captive wafer access secures solid-state breaker module availability against supply concentration in Japan and Germany. |
| Cybersecurity-Hardened Firmware Development | Embedded systems engineering capabilities differentiate electronic trip units for data center and utility predictive maintenance contracts. |
| Simultaneous IEC-UL Certification Investment | Dual approval processes unlock multinational deployment without 8-14 month launch cycle penalties from sequential submissions. |
| Service Contract Unbundling Capture | After-sales maintenance and firmware upgrade agreements expand recurring revenue pools as European transmission system operators separate procurement. |
| Localized Certification Acquisition | Bureau of Indian Standards infrastructure accelerates market entry for India's renewable integration corridor procurement. |
Methodological Framework
Operator-level perspectives from utility planning officers, industrial maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from IEC standard documentation, UL certification databases, customs and trade flow records, and SEC filings from diversified electrical equipment conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested volume and value outputs against commodity price volatility scenarios and regulatory harmonization trajectories. Segmentation dimensions modeled include product type, end user vertical, installation configuration, and technology architecture across the projection horizon. CAGRs derived from installed base replacement cycles, renewable integration procurement schedules, and electrification intensity trends in transportation and heating applications.
Forecasts assume regulatory continuity in IEC, UL, and REACH frameworks; material policy shifts in arc fault protection mandates or hazardous substance restrictions would require re-modeling. Specific risks include copper and rare earth price volatility, semiconductor supply concentration, and grid code divergence between IEEE and IEC testing protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Current Clamps Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Europe Electric Insulator Market