
 Household Appliances Electric Commutators Market | 2026-2036
Household Appliances Electric Commutators Market Size, Share, and Industry Trends Forecast 2026-2036
Household Appliances Electric Commutators Market Insights
Multi-source procurement for copper-alloy lamination sets is decoupling from traditional captive motor production in major appliance supply chains. Nidec Corporation leverages in-house sintering capacity to anchor high-volume contracts with washing machine OEMs in Asia. Johnson Electric Holdings Limited competes through specialized commutator designs for compact refrigerator compressors, while Mabuchi Motor Co., Ltd. sustains cost leadership in fractional horsepower motors for blenders and small appliances.
Household appliances electric commutators are electromechanical rotary switches composed of segmented copper bars insulated by mica or resin-bonded fiber, engineered to reverse current direction in armature windings at speeds typically ranging from 2,000 to 20,000 RPM. Their primary commercial purpose is to deliver reliable torque conversion and speed control in universal motors, brushless DC motors, and AC induction motors powering domestic equipment. Brushless DC technology leads segment value as appliance OEMs prioritize energy efficiency and electromagnetic compatibility compliance, while AC induction commutators retain volume dominance in cost-sensitive refrigerator and microwave applications where mature manufacturing tolerances preserve margin pools. Stepper motor commutators occupy a narrower but expanding niche in precision-controlled appliance subsystems.
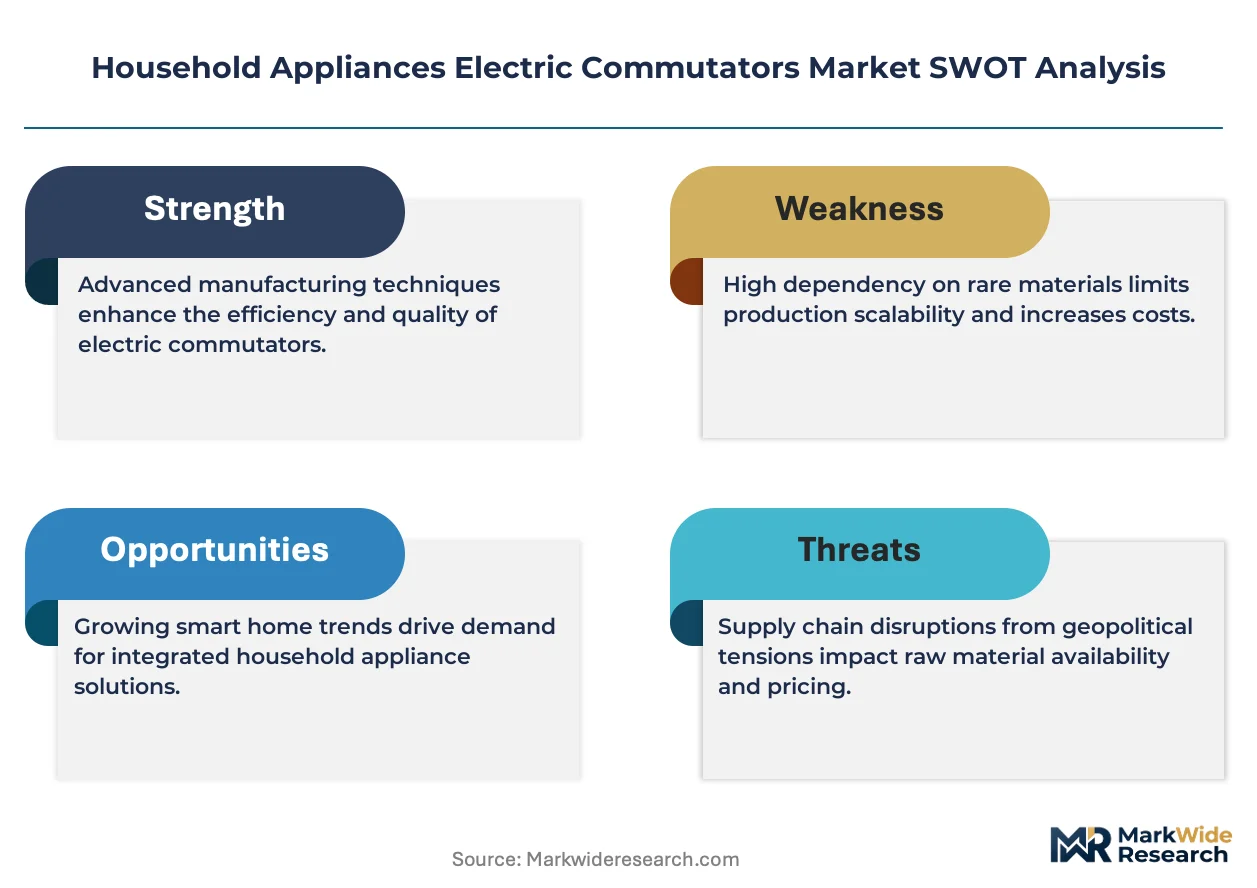
The EU Ecodesign Directive and REACH chemical compliance frameworks constrain material selection for commutator insulation and contact alloys in European markets, while China's GB motor efficiency standards and the US Department of Energy appliance standards mandate minimum performance thresholds that elevate copper-grade specifications. Japan's METI Top Runner program similarly drives incremental efficiency gains in motor-commutator pairings for premium appliance exports. Stakeholders must monitor evolving rare-earth magnet supply constraints and copper price volatility as these material dynamics increasingly determine sourcing economics and design trade-offs across motor-commutator architectures.
Market Dynamics
Brushless DC motor architectures are displacing universal motor designs across premium appliance tiers, forcing commutator suppliers to reconfigure copper-alloy specifications and insulation systems for higher switching frequencies and reduced electromagnetic interference.
Growth Catalysts
- EU Ecodesign Directive:Mandated motor efficiency tiers are accelerating copper-grade upgrades in washing machine and dishwasher platforms across European manufacturing clusters.
- China GB motor efficiency standards:Tiered minimum performance thresholds are elevating procurement specifications for sintered copper commutators in domestic appliance production.
- Brushless DC technology:Energy efficiency imperatives and electromagnetic compatibility requirements are expanding addressable demand for precision-engineered commutator segments in high-RPM applications.
Market Restraints
- Copper price volatility:Raw material cost swings compress margin pools for laminated copper bar producers serving cost-sensitive refrigerator and microwave motor platforms.
- Rare-earth magnet supply concentration:Neodymium and dysprosium sourcing bottlenecks constrain brushless DC motor scaling, indirectly capping commutator upgrade cycles in premium appliance tiers.
- REACH chemical compliance:Restricted substance lists for mica and resin-bonded fiber insulation materials extend qualification timelines for European market entry.
Strategic Opportunities
- US Department of Energy appliance standards:Tightening federal efficiency mandates create procurement upgrade cycles for copper-alloy commutators in domestic washing machine and compressor motor rebuild programs.
- Stepper motor precision subsystems:Smart appliance actuator integration opens niche demand for micro-commutator architectures in programmable oven controls and automated dispensing systems.
- Japan METI Top Runner program:Export-oriented efficiency benchmarking drives premium-tier motor-commutator pairing specifications for high-end appliance markets.
Industry Challenges
- Sintering process engineering talent:Specialized metallurgical expertise for copper-alloy powder compaction remains concentrated among legacy motor component suppliers, constraining new entrant scale-up.
- Multi-jurisdiction certification timelines:Parallel UL, VDE, and CCC safety approvals for revised insulation systems extend product launch cycles by twelve to eighteen months.
- Legacy AC induction motor integration:Mature refrigerator and microwave platforms resist brushless DC retrofit economics, trapping commodity commutator suppliers in price-competitive volume segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Appliances Electric Commutators Market |
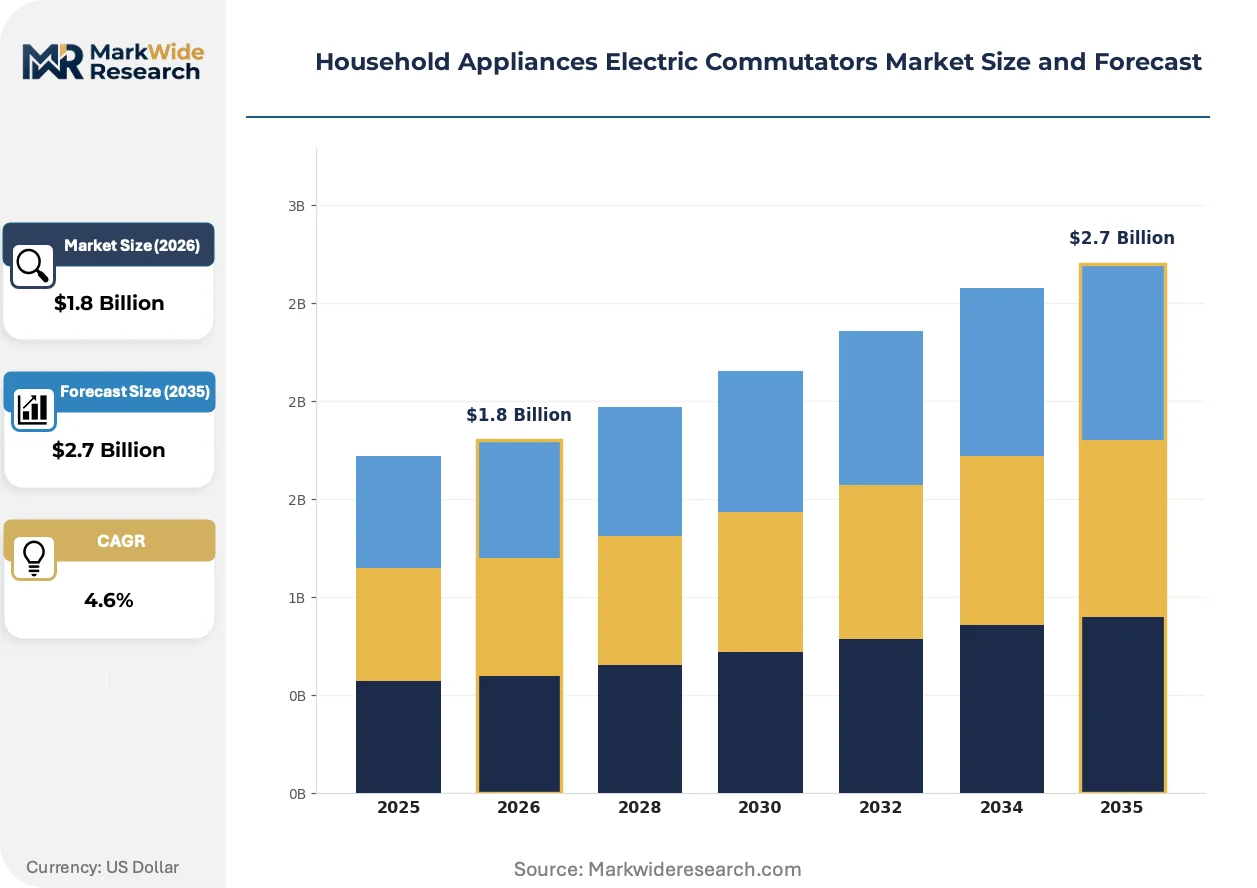
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Refrigerators, Microwaves, Blenders Technology: Brushless DC, Stepper Motors, AC Induction, Servo Motors End User: Residential Users, Commercial Kitchens, Industrial Facilities, Small Enterprises Distribution Channel: Online Retailers, Appliance Stores, Wholesalers, Direct Sales |
| Companies Covered | Nidec Corporation, Panasonic Corporation, Siemens AG, Johnson Electric Holdings Limited, Mitsubishi Electric Corporation, ABB Group, Toshiba Corporation, Mabuchi Motor Co., Ltd., Bosch Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Appliances Electric Commutators Market Trends and Innovations
Copper-alloy metallurgy and digital motor control integration are converging to redefine commutator performance specifications, while procurement patterns shift toward captive motor-commutator subsystem sourcing.
Silver-graphite brush materials paired with high-conductivity copper lamiations are electrifying contact reliability in brushless DC platforms operating above fifteen thousand RPM. Washing machine OEMs in Germany and South Korea are qualifying these architectures for direct-drive drum motors. The technology is electrifying supplier selection criteria away from pure cost metrics toward lifetime arc-erosion performance guarantees.
China's GB standards for permanent magnet motor efficiency are compressing allowable copper loss thresholds in domestic appliance manufacturing. MIIT enforcement of tiered efficiency labels is disqualifying legacy aluminum-bar commutator designs from subsidized procurement programs. Compressor motor suppliers in Qingdao and Hefei are responding with accelerated copper-alloy redesigns and in-house sintering investments.
Appliance OEMs are consolidating motor-commutator procurement into single-source subsystem contracts with tier-one suppliers. This pattern is displacing traditional component spot-buying through independent distributors in North American aftermarket channels. The consolidation is most visible in residential HVAC and washing machine service networks where inventory carrying costs and technical support liabilities are being pushed upstream.
Household Appliances Electric Commutators Market Segmentation
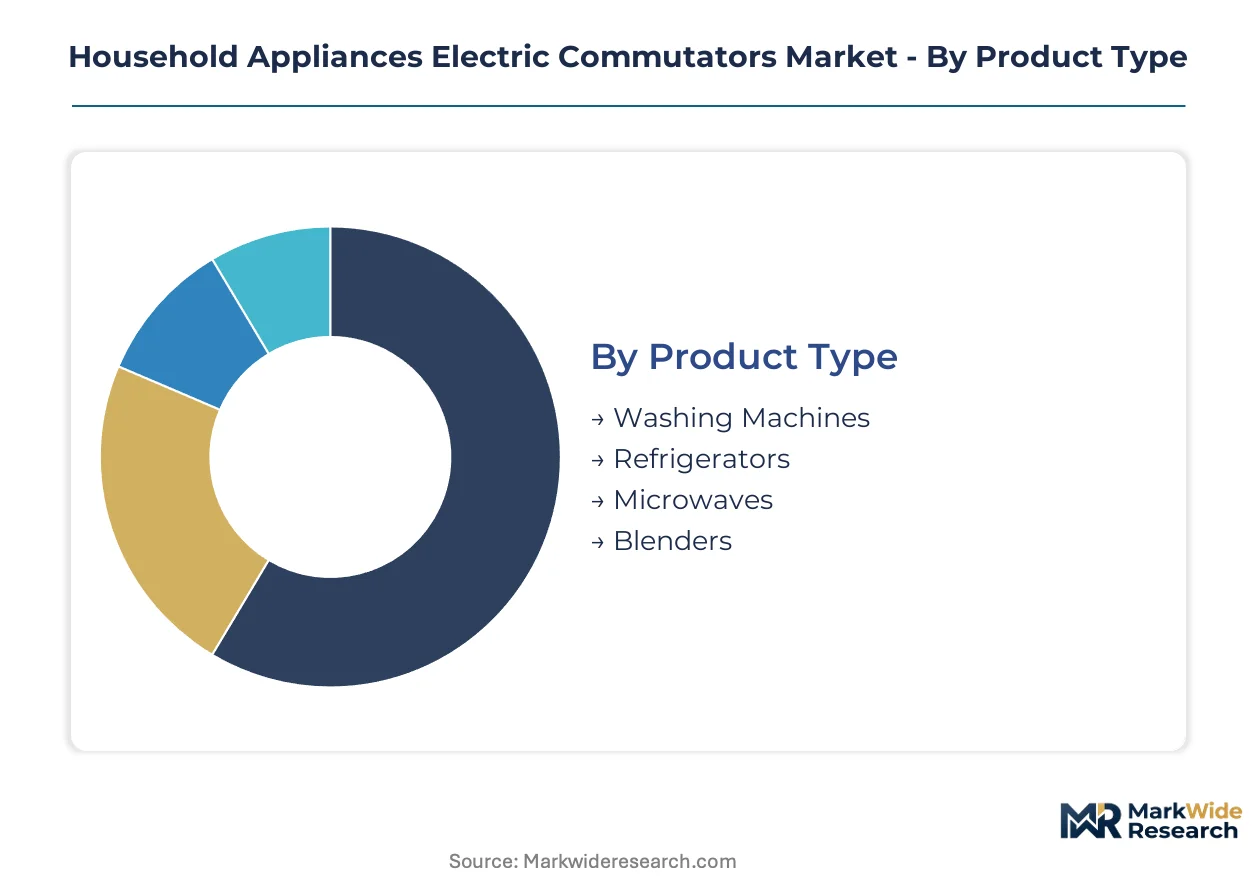
Commutator procurement patterns diverge sharply across appliance platforms, with motor architecture choices and distribution channel configurations determining copper-alloy specifications and supplier relationships. Understanding these segment boundaries reveals where efficiency mandates and aftermarket service economics reshape sourcing decisions.
Product Type:
Copper-grade specifications and lamination complexity scale with motor torque requirements and duty cycle intensity across domestic appliance categories.
- Washing Machines:Direct-drive drum motors demand high-conductivity copper segments with silver-graphite brush pairings for 15,000+ RPM operation. German and South Korean OEMs are qualifying these architectures under EU Ecodesign Directive tiers, compressing procurement timelines for sintered alloy suppliers.
- Refrigerators:Compressor motors rely on mature AC induction designs with aluminum-bar commutators in cost-sensitive platforms. China's GB motor efficiency standards are disqualifying legacy designs from subsidized procurement, forcing copper-alloy redesigns in Qingdao and Hefei manufacturing clusters.
- Microwaves:Turntable and fan motors use fractional horsepower universal motor commutators with resin-bonded fiber insulation.
- Blenders:High-RPM universal motor designs prioritize compact lamination sets with enhanced arc-erosion resistance for intermittent duty cycles.
Washing machines lead on scale; refrigerators lead on momentum as efficiency standards force copper upgrades.
Technology:
Motor-commutator pairing architectures determine switching frequency tolerance, electromagnetic compatibility compliance, and rare-earth material dependencies.
- Brushless DC:Electronic commutation eliminates mechanical wear but requires precision-engineered copper segments for sensorless control integration. Premium washing machine and HVAC platforms in Germany and the United States are adopting these architectures under tightening federal efficiency mandates.
- Stepper Motors:Micro-commutator designs enable precision positioning in smart appliance actuators. Programmable oven controls and automated dispensing systems in Japan's METI Top Runner-certified exports are expanding addressable demand for segmented copper bar architectures with enhanced step accuracy.
- AC Induction:Simplified commutator designs serve cost-driven refrigerator and microwave platforms where mature manufacturing tolerances preserve margin pools.
- Servo Motors:Closed-loop control integration demands high-frequency switching capability with advanced insulation systems for position-critical subsystems.
AC induction dominates current volume; stepper motors are gaining share fastest in precision-controlled smart appliance segments.
End User:
Service network density and replacement cycle economics segment procurement patterns across residential, commercial, and industrial installation bases.
- Residential Users:OEM-installed commutators in washing machines and refrigerators drive primary demand, with aftermarket replacement concentrated in urban service corridors. North American networks are consolidating inventory carrying costs upstream through single-source subsystem contracts with tier-one motor suppliers.
- Commercial Kitchens:High-duty-cycle blenders and microwave platforms demand enhanced thermal management in copper-alloy specifications. Food service operators in the United States prioritize extended warranty coverage over upfront component costs.
- Industrial Facilities:Heavy-duty washing equipment requires oversized commutator segments with reinforced mica insulation for continuous operation.
- Small Enterprises:Cost-sensitive procurement favors standard-grade aluminum-bar designs with distributor spot-buying patterns.
Residential users anchor volume concentration; commercial kitchens show steepest expansion trajectory as food service automation accelerates.
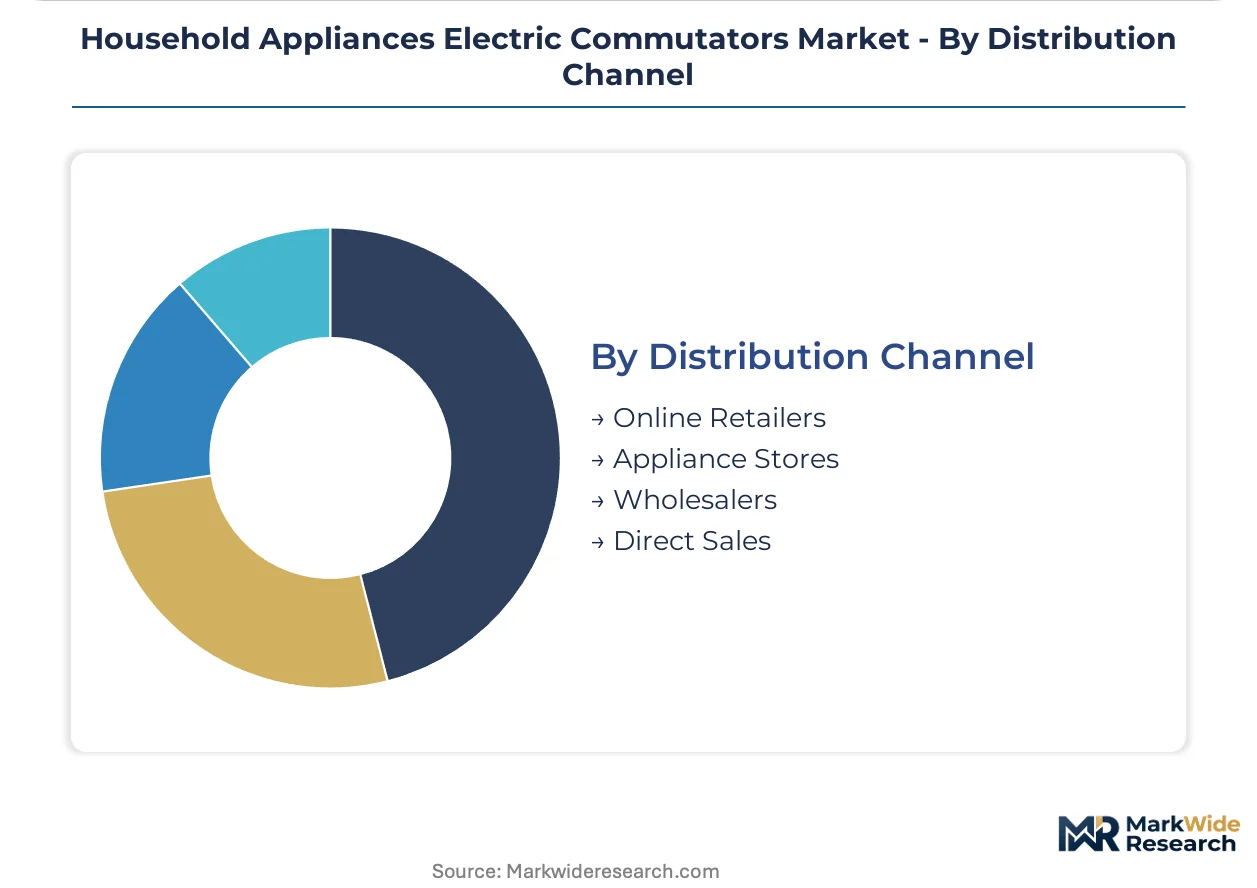
Distribution Channel:
Channel configuration determines technical support liabilities, inventory carrying costs, and qualification documentation requirements for insulation system certifications.
- Online Retailers:Aftermarket commutator sales for DIY repair segments are expanding through e-commerce platforms with standardized SKU catalogs. REACH compliance documentation for European shipments creates fulfillment complexity that favors established distributors with pre-qualified insulation systems.
- Appliance Stores:Branded service networks in Germany and the United States are shifting procurement to captive motor-commutator subsystems, displacing independent component spot-buying.
- Wholesalers:Volume aggregation for repair contractors maintains relevance in HVAC and commercial kitchen service corridors.
- Direct Sales:OEM subsystem contracts with Nidec Corporation and Johnson Electric Holdings Limited bypass traditional distribution for high-volume washing machine and refrigerator programs.
Appliance stores retain the largest transaction scale; online retailers are climbing the fastest as DIY repair penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Qingdao-Hefei manufacturing corridor anchors global household appliances electric commutators production volume. Appliance OEM procurement clusters in Germany's Baden-Württemberg and the United States' Midwest industrial belt concentrate copper-alloy specification demand. Regulatory divergence across efficiency mandates and chemical compliance frameworks segments supplier qualification pathways by destination market.
China
MIIT enforces tiered GB motor efficiency standards that disqualify legacy aluminum-bar commutator designs from subsidized procurement programs. Domestic washing machine and refrigerator production in Qingdao and Hefei manufacturing clusters drives copper-alloy redesign demand. Sintering capacity investments by tier-one motor suppliers are compressing qualification timelines for high-conductivity lamination sets.
Germany
EU Ecodesign Directive efficiency tiers mandate copper-grade upgrades in washing machine and dishwasher platforms across European manufacturing clusters. REACH chemical compliance frameworks constrain mica and resin-bonded fiber insulation material selection for commutator producers. Stuttgart-based appliance OEMs are qualifying silver-graphite brush pairings for direct-drive drum motors operating above fifteen thousand RPM.
United States
Department of Energy appliance standards tighten federal efficiency mandates for washing machine and compressor motor rebuild programs. Residential HVAC and washing machine service networks in the Midwest industrial belt are consolidating inventory carrying costs upstream through single-source subsystem contracts. UL safety approvals for revised insulation systems extend product launch cycles by twelve to eighteen months.
Japan
METI Top Runner program drives incremental efficiency gains in motor-commutator pairings for premium appliance exports. Nagoya and Osaka industrial corridors concentrate precision-engineered commutator segment production for high-RPM applications. Domestic OEMs prioritize electromagnetic compatibility compliance in brushless DC architectures for smart appliance actuator integration.
South Korea
Domestic washing machine OEMs are accelerating procurement of brushless DC commutators as global efficiency standards tighten. Gyeonggi-do manufacturing clusters specialize in compact lamination sets for high-RPM universal motor applications. Export-oriented production networks align copper-alloy specifications with EU Ecodesign Directive and US Department of Energy compliance thresholds.
Household Appliances Electric Commutators Market Competitive Landscape
Global majors compete with regional champions across motor-commutator subsystem integration and copper-alloy metallurgy specialization. Market structure tilts toward tier-one captive suppliers with in-house sintering capacity, while independent component distributors lose share in North American aftermarket channels. Strategic archetypes include integrated motor-commutator subsystem providers, specialized copper-alloy fabricators, and fractional horsepower cost leaders. Dominant competitive moves span backward integration into powder metallurgy and single-source OEM contracting that displaces spot-buying patterns.
Within the integrated subsystem tier, Nidec Corporation and Johnson Electric Holdings Limited exemplify scale-driven positions, while Mabuchi Motor Co., Ltd. occupies a cost-leadership archetype in fractional horsepower segments. Japanese and European-origin entities anchor premium-tier specification demand, whereas Chinese fabricators concentrate on volume-responsive copper-alloy redesigns. Each archetype faces distinct pressure: integrated players must defend sintering process engineering talent, while cost leaders navigate copper price volatility in commodity refrigerator and microwave motor platforms.
| Leading Market Players |
|---|
| Nidec Corporation |
| Panasonic Corporation |
| Siemens AG |
| Johnson Electric Holdings Limited |
| Mitsubishi Electric Corporation |
| ABB Group |
| Toshiba Corporation |
| Mabuchi Motor Co., Ltd. |
| Bosch Limited |
| Others |
Pricing and Supply Chain Analysis
Captive motor-commutator subsystem sourcing by tier-one OEMs anchors both supply positioning and pricing power in this market. Nidec Corporation and Johnson Electric Holdings Limited leverage in-house sintering capacity to lock in multi-year contracts, compressing margin pools for independent distributors while copper-alloy grade specifications determine tier placement.
Pricing Analysis
Copper price pass-through mechanics dominate transactional pricing for laminated bar producers serving refrigerator and microwave motor platforms. Three-tier pricing structure across premium, standard, and economy levels separates silver-graphite brush pairings for brushless DC architectures from resin-bonded fiber insulated aluminum bars. Cost compression in economy tiers is intensifying because China's GB standards disqualify legacy designs from subsidized procurement. Small enterprise buyers in distributor spot-buying channels exhibit highest price sensitivity, while German washing machine OEMs prioritize lifetime arc-erosion guarantees over unit cost.
Supply Chain Analysis
China's domestic-content requirements for MIIT-subsidized motor procurement are reshaping sourcing patterns toward Qingdao and Hefei manufacturing clusters. Raw material flows draw from Chilean copper concentrate, domestic rare-earth magnet processing, and Japanese silver-graphite brush imports. Single-source vulnerability concentrates in neodymium and dysprosium supply chains feeding brushless DC motor scaling. Distribution runs through direct OEM subsystem contracts that displace independent aftermarket channels in North American service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in copper-alloy redesigns for efficiency-compliant platforms, as sintering process expertise commands premium pricing power against commodity aluminum-bar competitors.
For Market Incumbents: Hedge against rare-earth magnet supply concentration by securing long-term offtake agreements with dysprosium processors. Deepen backward integration into powder metallurgy capacity in China's manufacturing corridor to defend against emerging Chinese fabricators with state-backed sintering investments. Prioritize UL and VDE certification maintenance for revised insulation systems as REACH compliance timelines extend European market entry barriers. For New Entrants and Emerging Players: Launch via online retail channels targeting DIY repair segments with REACH-pre-qualified insulation system SKUs for European aftermarket fulfillment. White-space opportunities concentrate in stepper motor micro-commutators for Japan's METI Top Runner-certified smart appliance exports, where precision-engineered segment demand outpaces incumbent capacity. Target commercial kitchen service corridors in the United States with extended warranty bundling that shifts technical support liabilities upstream. For Investors and Strategic Acquirers: Consolidation pressure builds where sintering process engineering talent concentrates among legacy motor component suppliers with captive OEM relationships. Long-term viability favors integrated subsystem providers with backward integration into copper-alloy powder compaction and single-source contracting discipline. Acquisition target archetype: mid-tier fabricators with MIIT-aligned GB standard compliance and existing Qingdao-Hefei production footprint. Watch copper price volatility spikes and MIIT enforcement intensity as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sintering Capacity | In-house copper-alloy powder compaction secures multi-year washing machine OEM contracts against spot-buying competitors. |
| Silver-Graphite Brush Material Qualification | German and South Korean OEMs prioritize 15,000+ RPM arc-erosion performance for direct-drive drum motor adoption. |
| REACH-Compliant Insulation System Investment | Pre-qualified mica and resin-bonded fiber documentation accelerates European aftermarket e-commerce fulfillment timelines. |
| Single-Source Subsystem Contracting | Captive motor-commutator procurement displaces independent distributors in Midwest HVAC and washing machine service networks. |
| Stepper Motor Micro-Commutator Development | Precision positioning architectures capture smart appliance actuator demand from Japan's METI Top Runner export programs. |
Research Methodology
Multiple input streams — primary interviews with motor procurement directors, plant engineers at Qingdao and Hefei manufacturing clusters, and aftermarket service network managers — were reconciled against secondary validation from MIIT GB standard filings, UL certification databases, and copper trade flow records. Bottom-up segment sizing across product type, technology, and end-user dimensions was cross-checked with top-down market aggregation from appliance production data.
Historical shipment trajectories were cross-referenced against expert panel inputs from commutator metallurgy specialists and OEM platform engineers to derive expansion rates across the analysis window. Segmentation modeling incorporated motor architecture choice, copper-alloy grade tier, distribution channel configuration, and regional regulatory cluster. CAGRs were computed from reconciled volume and value projections, with sensitivity testing against copper price scenarios and rare-earth magnet supply disruption assumptions.
Several conditions sit outside the modeled scope, including speculative rare-earth substitution breakthroughs and unannounced REACH substance list revisions. Forecasts reflect documented assumptions about MIIT enforcement continuity and EU Ecodesign Directive tier implementation schedules. A small set of named triggers — copper price volatility spikes, neodymium export quota shifts, and UL/VDE approval timeline extensions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coaxial Attenuators Market
Electronic Components
Resonators Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Intel Motherboards Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Operational Amplifier Market
Electronic Components
Motherboard Battery Market
Electronic Components
Capacitor Kits Market
Electronic Components
Pneumatic Components Market
Electronic Components
United States MLCC Market
Electronic Components
Efuse Market
Electronic Components
Battery Holders Market