
 United States Radiation-Hardened Electronics Market | 2026-2036
United States Radiation-Hardened Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Radiation-Hardened Electronics Market Intelligence
QML Class V qualification is reorganizing supplier hierarchies across the United States radiation-hardened electronics landscape. Texas Instruments leverages captive foundry access to sustain die-level hardness certification for military-grade analog components. BAE Systems anchors its position through in-house silicon-on-sapphire fabrication serving classified satellite payloads. Honeywell International differentiates via integrated microelectromechanical systems that combine radiation sensing with signal conditioning in single packages.
Radiation-hardened electronics encompass semiconductor devices and integrated circuits engineered to withstand ionizing radiation doses exceeding 100 krad(Si), total dose effects, and single-event upsets through specialized fabrication processes such as silicon-on-insulator or epitaxial layer hardening. These components enable reliable operation in environments where standard commercial-grade semiconductors would experience threshold voltage shifts, leakage current degradation, or catastrophic latch-up failures. Microprocessors and FPGAs command the deepest qualification investment cycles, with silicon-on-insulator technology capturing expanding share as foundries migrate from bulk CMOS for improved single-event upset immunity. Power amplifiers built on gallium nitride substrates represent the fastest-expanding technology tier, driven by radar and electronic warfare transmitters demanding higher power density at millimeter-wave frequencies.
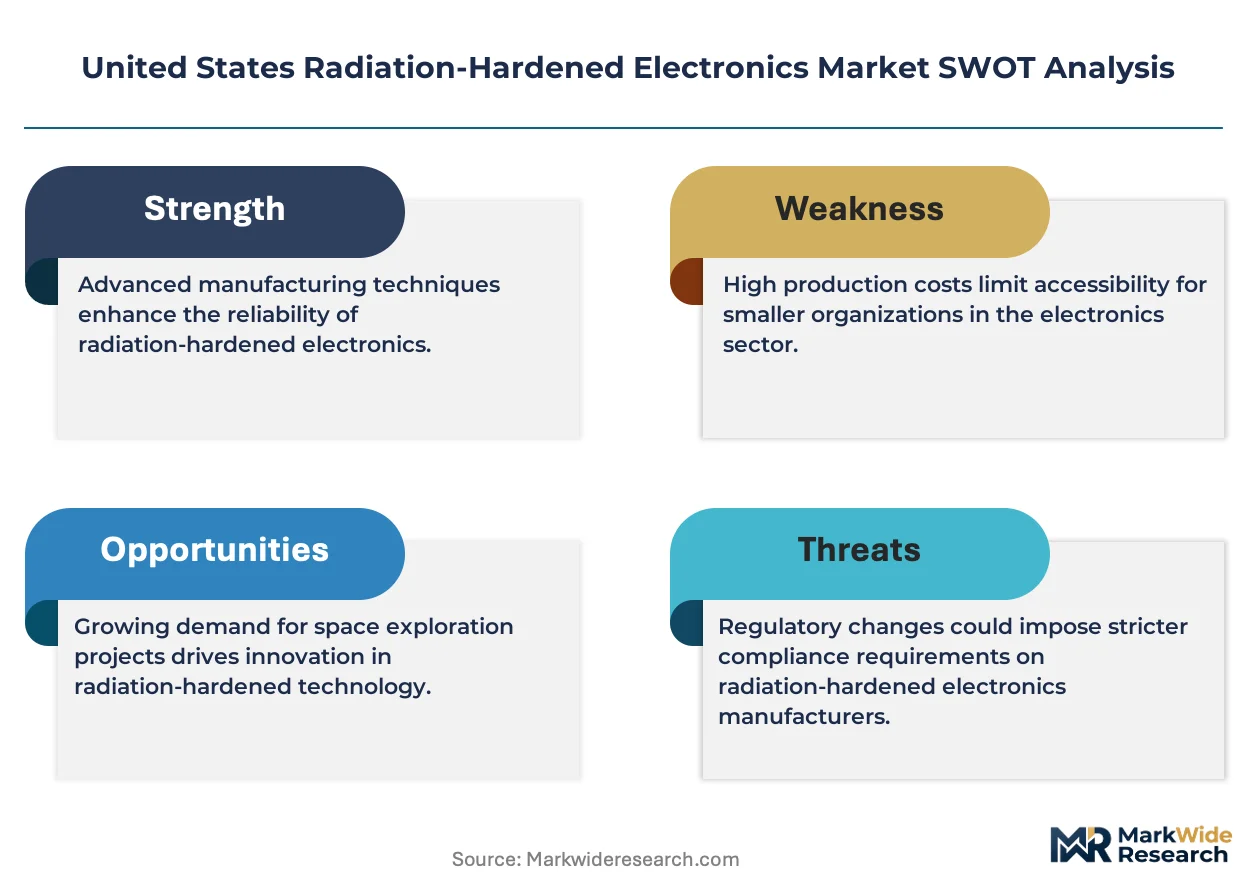
FAA licensing requirements for commercial space launch vehicles shape component traceability standards, while DoD MIL-PRF-38535 establishes baseline qualification protocols for defense-destined devices. The Department of Commerce Bureau of Industry and Security administers Export Administration Regulations that restrict gallium nitride and silicon carbide device shipments to designated countries, constraining foreign market access for domestic manufacturers. Stakeholders must monitor evolving NASA Class S qualification demands for Artemis lunar infrastructure and next-generation Mars missions, where extended radiation exposure durations exceed traditional geostationary orbit hardness benchmarks.
Market Dynamics
QML Class V qualification requirements are compressing supplier tiers across the United States radiation-hardened electronics landscape, forcing tier-two manufacturers to abandon discrete logic lines or pursue captive foundry partnerships to maintain defense contract eligibility.
Growth Catalysts
- DoD Satellite Constellation Procurement:The Department of Defense is accelerating hardened component purchases for proliferated low-Earth-orbit architectures, creating sustained demand for radiation-tolerant FPGAs and power management ICs.
- FAA Commercial Space Licensing:Expanded launch vehicle certification requirements are mandating component traceability standards that favor qualified domestic suppliers over unvetted imports.
- Silicon-on-Insulator Migration:Foundry process upgrades from bulk CMOS to SOI technology are improving single-event upset immunity without requiring full redesign cycles.
Market Restraints
- Domestic Foundry Concentration:Radiation-hardened wafer fabrication concentrates at three US-based facilities, creating geographic supply risk for die-level hardness certification.
- Gallium Nitride Export Controls:Department of Commerce Bureau of Industry and Security restrictions under EAR Category 9 constrain foreign revenue streams for GaN power amplifier manufacturers.
- Epitaxial Layer Cost Volatility:Specialized substrate hardening processes require high-purity silicon boules subject to energy-intensive production cost swings.
Strategic Opportunities
- Artemis Lunar Infrastructure:NASA Class S qualification demands for extended-duration Mars and lunar missions exceed traditional geostationary hardness benchmarks, opening new specification tiers.
- MEMS-Radhard Convergence:Integrated microelectromechanical systems combining radiation sensing with signal conditioning enable single-package solutions for distributed satellite payloads.
- Texas and California Clusters:Aerospace corridor concentration around Houston satellite operations and Los Angeles prime contractors supports regional supplier co-location strategies.
Industry Challenges
- QML Class V Certification Timelines:Military-grade qualification cycles extending 18-24 months delay revenue recognition for new device introductions.
- Radiation Effects Simulation Talent:Shortage of engineers trained in total dose and single-event effect modeling constrains design team scaling.
- Legacy MIL-STD-883 Integration:New silicon-on-sapphire devices must maintain backward compatibility with established test protocols originally developed for bipolar technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Radiation-Hardened Electronics Market |
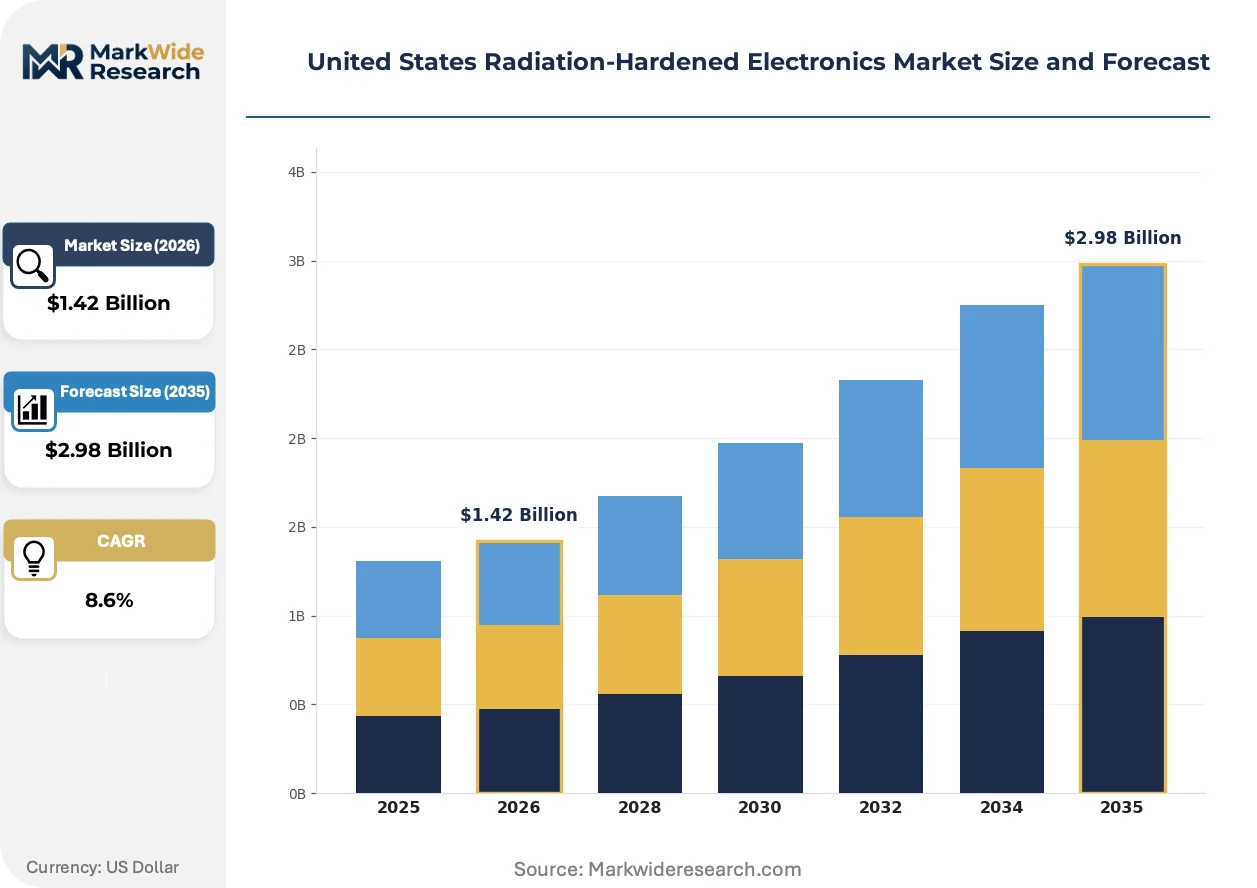
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, FPGAs, Power Amplifiers, Sensors Technology: Silicon On Insulator, Gallium Nitride, CMOS, Bipolar End User: Aerospace, Defense, Nuclear, Space Exploration Application: Satellite Systems, Medical Equipment, Automotive Safety, Robotics |
| Companies Covered | Texas Instruments, Teledyne Technologies, Honeywell International, TTM Technologies, Northrop Grumman Corporation, Microchip Technology, Analog Devices, Advanced Micro Devices, BAE Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Radiation-Hardened Electronics Market Strategic Shifts & Innovations
Process architecture choices are redrawing competitive boundaries across the United States radiation-hardened electronics market. Three developments are compressing traditional supplier hierarchies and enabling new qualification pathways.
Gallium nitride power amplifiers are displacing traveling-wave tube transmitters in radar and electronic warfare systems. Pentagon procurement offices are mandating solid-state replacements for legacy vacuum tube architectures in next-generation electronic attack platforms. This displacement is collapsing the historical separation between semiconductor and tube-based transmitter supply chains.
DoD MIL-PRF-38535 revision cycles are tightening baseline qualification protocols for defense-destined devices. The updated specification framework is eliminating grandfathered test methodologies and requiring enhanced single-event latch-up screening. Prime contractors in California and Colorado are responding by consolidating vendor lists to suppliers with demonstrated Revision K compliance.
Qualification-driven procurement preferences are restructuring component sourcing patterns. Satellite prime contractors are bypassing distribution channels to engage directly with qualified manufacturers for long-lead FPGA and memory orders. This disintermediation is most visible in geostationary communications satellite programs where component pedigree requirements exceed standard commercial aerospace practices.
United States Radiation-Hardened Electronics Market Segmentation
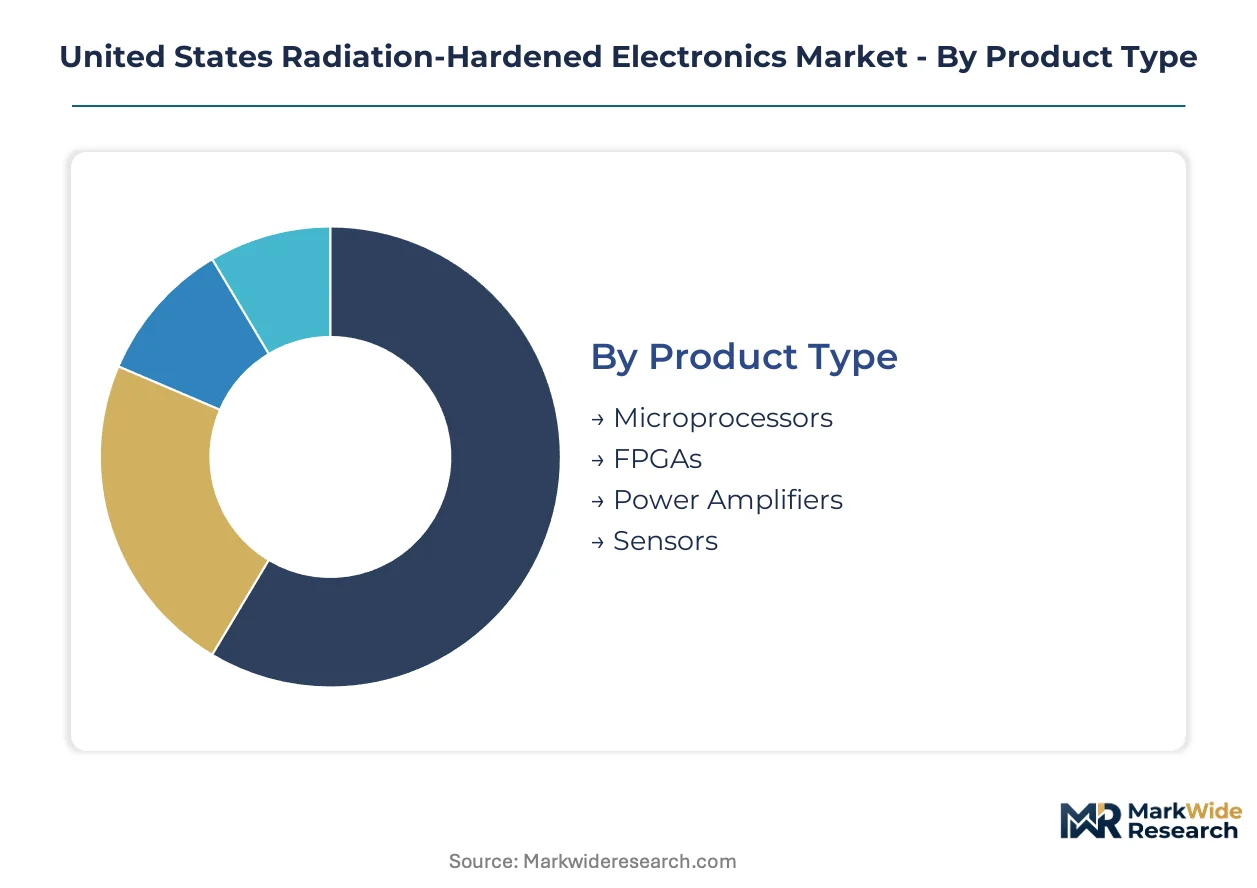
Radiation-hardened electronics procurement splits sharply between domestic defense programs and export-constrained commercial sales. Segment boundaries align with qualification tiers that determine foundry access and contract eligibility across federal and commercial buyers.
Product Type:
Domestic demand concentrates in defense-certified components where QML Class V qualification creates captive supply chains. Export-led segments face Bureau of Industry and Security licensing thresholds that restrict foreign shipment volumes.
- Microprocessors:Complex instruction-set architectures fabricated on radiation-tolerant process nodes enable satellite command-and-control functions. DoD proliferated low-Earth-orbit architectures are absorbing multi-core hardened processors for constellation management in California and Colorado operations centers.
- FPGAs:Field-programmable gate arrays with configurable logic blocks support mission-specific reconfiguration without full ASIC redesign cycles. Lockheed Martin Space and Northrop Grumman are qualifying high-density SRAM-based FPGAs for geostationary payload signal processing in Los Angeles County.
- Power Amplifiers:Solid-state GaN and GaAs devices replace traveling-wave tubes in radar transmitters.
- Sensors:Integrated MEMS devices combine radiation detection with environmental monitoring for distributed satellite payloads.
Microprocessors hold the largest share; momentum sits with power amplifiers as solid-state radar displacement accelerates.
Technology:
Process migration costs stratify supplier tiers, with SOI and GaN requiring capital-intensive foundry upgrades that CMOS and bipolar legacy lines avoid.
- Silicon On Insulator:Buried oxide layers eliminate latch-up paths and reduce single-event upset susceptibility versus bulk CMOS. Texas Instruments and Honeywell International are expanding SOI wafer starts for military-grade analog and mixed-signal components in Dallas and Phoenix facilities.
- Gallium Nitride:Wide bandgap properties enable power density at millimeter-wave frequencies exceeding silicon limitations. Pentagon electronic warfare programs are mandating GaN transmitters for next-generation jamming platforms, though EAR Category 9 controls constrain non-allied foreign sales.
- CMOS:Bulk complementary metal-oxide-semiconductor persists in cost-sensitive radiation-tolerant applications.
- Bipolar:Junction-isolated technologies maintain legacy program compatibility for established satellite bus designs.
Silicon-on-insulator dominates defense procurement; gallium nitride is expanding most quickly as radar solid-state conversion proceeds.
End User:
Customer concentration varies by funding source, with federal programs offering volume stability and commercial space presenting qualification pathway risks.
- Aerospace:Commercial satellite operators and launch vehicle manufacturers require component traceability for FAA licensing compliance.
- Defense:Pentagon procurement offices specify hardened components for strategic systems, nuclear command-and-control, and tactical communications. The Department of Defense accounts for the dominant qualification volume through Space Development Agency and Space Force constellation programs.
- Nuclear:Reactor instrumentation and waste handling robotics demand extended total-dose tolerance beyond space benchmarks.
- Space Exploration:NASA Class S qualification for Artemis lunar infrastructure and Mars missions exceeds traditional geostationary hardness requirements.
Defense commands the largest share; space exploration is gaining share fastest as lunar mission timelines compress.
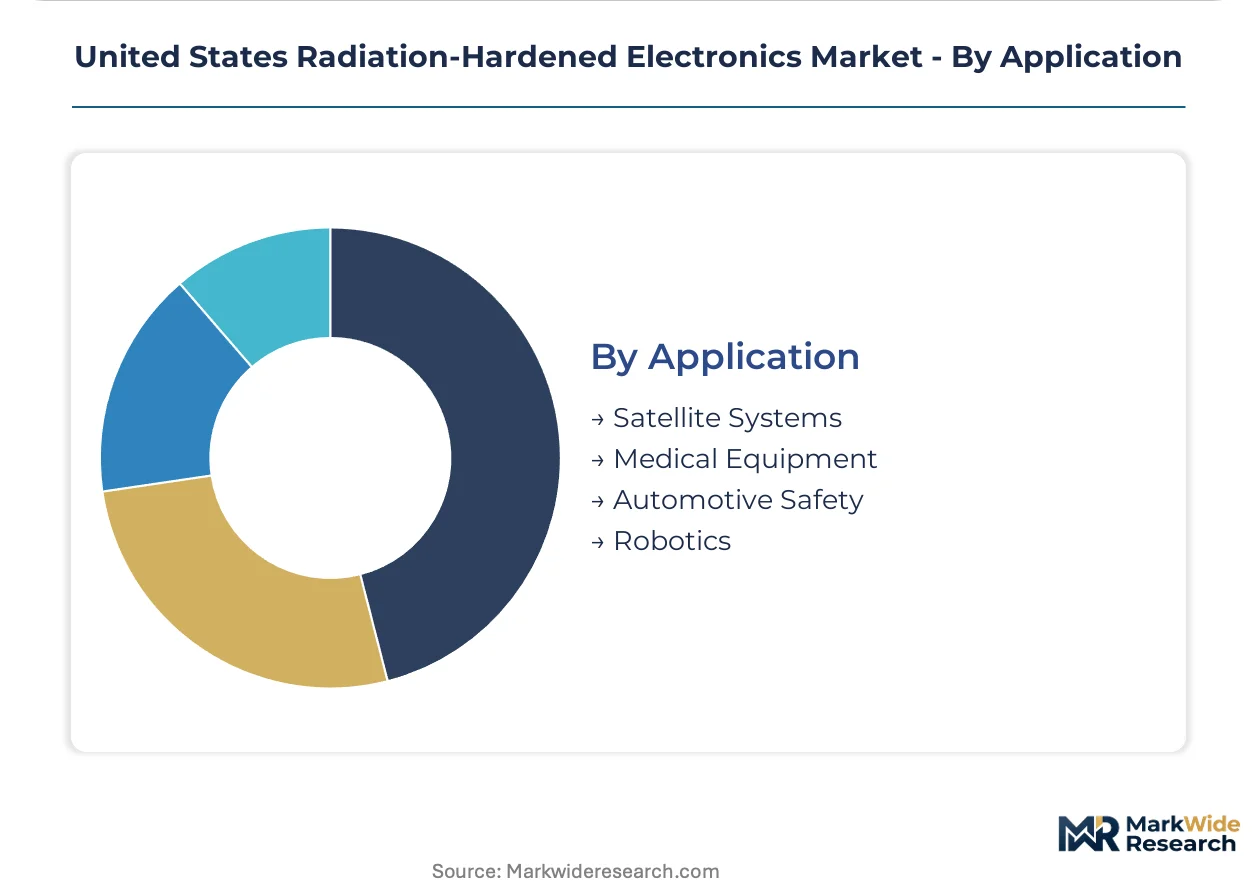
Application:
Application-specific qualification cycles range from 18-month satellite component approvals to multi-year medical device certifications.
- Satellite Systems:Geostationary communications, navigation constellations, and Earth observation platforms drive the deepest qualification investment cycles. SpaceX Starlink and Amazon Project Kuiper are qualifying radiation-tolerant power management ICs for low-Earth-orbit mass production in Redmond and Hawthorne facilities.
- Medical Equipment:Radiation therapy devices and imaging systems require hardened electronics for precision dose delivery and detector signal integrity. Varian Medical Systems and Elekta are sourcing radiation-tolerant ADCs and DACs for linear accelerator control systems.
- Automotive Safety:Autonomous vehicle sensor fusion and battery management systems are emerging qualification targets.
- Robotics:Nuclear decommissioning and deep-space exploration robotics demand extended radiation tolerance with mechanical durability.
Satellite systems hold the largest share; medical equipment is climbing the fastest as radiotherapy precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three US-based foundry facilities concentrate wafer fabrication for radiation-hardened components, creating geographic supply risk while anchoring qualification capacity in specific metro corridors. Defense procurement flows through distinct regional clusters tied to prime contractor presence and federal research infrastructure.
California
SpaceX Starlink and Lockheed Martin Space drive qualification volumes for low-Earth-orbit and geostationary missions in Los Angeles County. FAA commercial space licensing requirements shape component traceability standards for Hawthorne and Redondo Beach operations. The aerospace corridor from El Segundo to Sunnyvale hosts concentrated FPGA and power management IC validation activity.
Texas
Texas Instruments leverages captive foundry access in Dallas for die-level hardness certification of military-grade analog components. Space Development Agency constellation programs route procurement through Houston satellite operations centers. The Dallas-Phoenix manufacturing axis supports expanding silicon-on-insulator wafer starts for mixed-signal defense applications.
Colorado
Northrop Grumman and Ball Aerospace anchor strategic systems procurement in the Denver-Boulder corridor. DoD MIL-PRF-38535 Revision K compliance requirements drive vendor consolidation toward qualified suppliers with demonstrated screening protocols. Prime contractors in Colorado Springs and Westminster are consolidating vendor lists for next-generation nuclear command-and-control platforms.
Arizona
Honeywell International operates integrated microelectromechanical systems fabrication in Phoenix for radiation sensing and signal conditioning packages. NASA Class S qualification demands for Artemis lunar infrastructure route through Tucson and Tempe research partnerships. The Phoenix metro supports single-package solutions for distributed satellite payloads requiring extended total-dose tolerance.
Virginia
BAE Systems maintains classified satellite payload fabrication in Manassas and Arlington for silicon-on-sapphire components. Department of Commerce Bureau of Industry and Security export control frameworks under EAR Category 9 administer technology transfer restrictions from Northern Virginia offices. The Dulles corridor hosts concentrated electronic warfare and radar transmitter qualification activity for Pentagon procurement offices.
United States Radiation-Hardened Electronics Market Key Industry Players
Concentration sits with diversified defense primes and captive-foundry semiconductor manufacturers that control qualification pathways. The vendor base compresses into tier-one suppliers with demonstrated QML Class V compliance and tier-two specialists pursuing strategic partnerships for foundry access. Two archetypes dominate: integrated defense conglomerates with in-house fabrication and analog-focused semiconductor houses with radiation-hardened process lines. Competitive moves center on captive foundry partnerships and direct procurement relationships that bypass distribution channels.
Within the integrated defense tier, Northrop Grumman Corporation and BAE Systems exemplify prime contractors that anchor classified payload supply chains through captive fabrication capabilities. Texas Instruments represents the semiconductor archetype with sustained die-level hardness certification for military-grade analog components. These three occupy positions that illustrate the market's bifurcation between systems-integrated and component-specialized competitive vectors.
| Leading Market Players |
|---|
| Texas Instruments |
| Teledyne Technologies |
| Honeywell International |
| TTM Technologies |
| Northrop Grumman Corporation |
| Microchip Technology |
| Analog Devices |
| Advanced Micro Devices |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with domestic foundries lock in wafer starts at fixed unit economics while insulating qualified suppliers from gallium nitride substrate cost volatility. These arrangements bind Space Development Agency procurement offices and satellite prime contractors to 18-24 month qualification cycles that embed die-level hardness certification premiums into component pricing.
Pricing Analysis
DoD MIL-PRF-38535 dictates the pricing tier structure across radiation-hardened electronics procurement. Three-tier pricing separates QML Class V certified devices from Class Q commercial-grade alternatives and unscreened industrial components. Price differentiation hinges on total dose tolerance certification and single-event upset screening stringency. Cost compression in GaN power amplifiers is intensifying because Pentagon electronic warfare programs are mandating solid-state transmitter displacement. Commercial satellite operators exhibit highest price sensitivity, while nuclear command-and-control platforms prioritize pedigree over unit cost.
Supply Chain Analysis
Inventory buffers for high-purity silicon boules and specialized epitaxial substrates stretch lead times beyond standard commercial semiconductor cycles. Wafer fabrication concentrates in the United States at Dallas, Phoenix, and Manassas facilities. The supply chain draws from domestic silicon foundries, gallium nitride substrate vendors, and ceramic packaging specialists. Single-source vulnerability sits with qualified SOI wafer suppliers subject to Department of Commerce Bureau of Industry and Security export licensing. Distribution runs through direct procurement relationships that bypass distribution channels for long-lead FPGA and memory orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-on-insulator process migration and gallium nitride transmitter displacement are compressing traditional supplier hierarchies faster than qualification cycles can absorb. Pentagon procurement offices are rewriting electronic warfare specifications around solid-state architectures that collapse historical semiconductor-vacuum tube boundaries.
For Market Incumbents: Shield classified payload market share through accelerated QML Class V Revision K compliance investment before vendor consolidation hardens. Captive foundry partnerships with Dallas and Phoenix facilities anchor die-level hardness certification capacity that emerging competitors cannot replicate. Threat vectors include Space Development Agency direct procurement relationships that disintermediate traditional distribution channels. For New Entrants and Emerging Players: Lead with MEMS-radhard convergence applications where integrated radiation sensing and signal conditioning packages face lighter qualification burdens than discrete logic lines. Medical equipment radiotherapy precision requirements present the most penetrable segment, with Varian Medical Systems and Elekta sourcing radiation-tolerant ADCs outside defense procurement cycles. Go-to-market positioning should emphasize FDA licensing compliance pathways that parallel FAA commercial space traceability standards. For Investors and Strategic Acquirers: Capital is best deployed toward analog-focused semiconductor houses with demonstrated military-grade process lines and captive foundry access. Long-term viability across the projection horizon rests on qualification pathway control rather than volume scale. The signal to monitor is NASA Class S specification releases for Artemis lunar infrastructure, which will exceed traditional geostationary hardness benchmarks and open new specification tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Partnership | Texas Instruments sustains die-level hardness certification through Dallas facility control. |
| QML Class V Revision K Compliance | Northrop Grumman consolidates vendor lists toward qualified suppliers with demonstrated screening. |
| Silicon-on-Sapphire Fabrication Investment | BAE Systems anchors classified satellite payload supply chains through Manassas in-house production. |
| MEMS-Radhard Integration | Honeywell International combines radiation sensing with signal conditioning in single Phoenix packages. |
| Direct Procurement Relationship | SpaceX Starlink bypasses distribution for long-lead power management IC qualification volumes. |
Research Approach
Operator-level perspectives from satellite procurement officers, foundry process engineers, radiation effects modeling specialists, and defense contract administrators anchored the qualitative base. Primary interviews with Space Development Agency program managers and NASA Class S qualification leads combined with secondary validation from DoD MIL-PRF-38535 revision documentation, FAA commercial space licensing records, and Department of Commerce Bureau of Industry and Security EAR Category 9 rulings. Bottom-up component demand modeling and top-down defense budget allocation analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against gallium nitride export control tightening, SOI foundry capacity expansion delays, and Artemis mission timeline acceleration scenarios. Segmentation dimensions modeled include product type, fabrication technology, end-user funding source, and application-specific qualification cycle length. CAGRs were derived from defense procurement flow projections and commercial space launch licensing trends. Industry-specific inputs encompassed Pentagon electronic warfare transmitter displacement schedules and NASA extended-duration radiation exposure benchmarks.
The analysis sits within stated boundaries; outcomes outside sustained DoD constellation funding or relaxed export licensing thresholds would require recalibration. Forecasts reflect assumptions regarding qualification cycle stability and foundry capacity utilization. Specific risks that could revise projections include single-event latch-up screening protocol changes or gallium nitride substrate supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Audio Capacitor Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Docking Station Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Power Inductors Market
Electronic Components
Global Circuit Protection Market