
 Bluetooth Adapter Market | 2026-2036
Bluetooth Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Adapter Market Outlook
Retail shelf space for standalone Bluetooth adapters is narrowing as e-commerce direct-to-consumer channels capture volume. Qualcomm Technologies Inc. leverages its Snapdragon portfolio to dominate premium USB-C and embedded module segments. Broadcom Inc. sustains design wins in laptop OEM reference platforms through integrated Wi-Fi and Bluetooth combo silicon. ASUS competes in the gaming peripheral niche with specialized low-latency PCIe cards.
A Bluetooth adapter is a compact radio transceiver module that converts non-Bluetooth host devices into Bluetooth-capable endpoints, typically operating in the 2.4 GHz ISM band with output power classes from Class 1 to Class 3. Its primary commercial purpose is to enable wireless audio streaming, peripheral pairing, and machine-to-machine communication in hardware lacking native Bluetooth support. USB Adapters retain the largest revenue pool among product types due to plug-and-play retrofit demand across desktop and legacy automotive head units. BLE connectivity is displacing Classic Bluetooth in medical devices and industrial sensor networks where power budgets constrain battery life. Embedded Modules command superior margins as they require FCC and ETSI pre-certification, raising barriers for second-tier suppliers.
The Federal Communications Commission governs RF emissions and spectrum allocation for adapters sold in the United States, while the Bluetooth Special Interest Group enforces trademark licensing and protocol compliance worldwide. The European Telecommunications Standards Institute harmonizes testing regimes that determine CE marking eligibility for radio equipment. Stakeholders must monitor evolving spectrum reallocation debates and energy-efficiency labeling requirements that could reshape product design priorities.
Market Dynamics
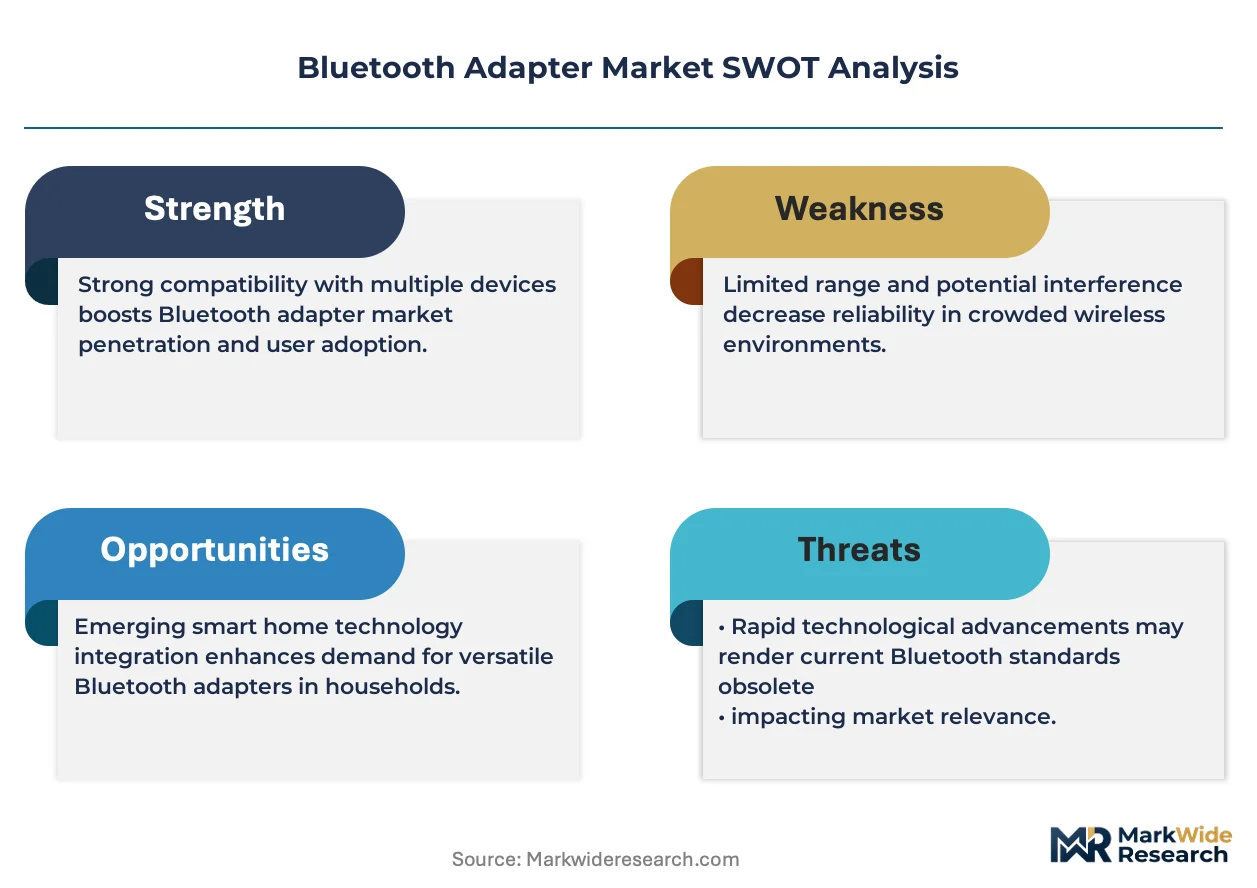
BLE 5.3 certification mandates from the Bluetooth Special Interest Group are compressing design cycles across OEM supply chains while fragmenting vendor qualification pools. This regulatory tightening intersects with manufacturing concentration in East Asian contract foundries to create supply bottlenecks for pre-certified modules.
Growth Catalysts
- Wireless Audio Retrofit Demand:Legacy automotive head units and desktop systems lacking native Bluetooth capability drive plug-and-play USB adapter procurement. Consumer electronics retailers report sustained attach rates for dongle solutions.
- BLE Protocol Migration:Medical device manufacturers and industrial sensor networks are transitioning from Classic Bluetooth to BLE to extend battery life in power-constrained deployments. This shift expands addressable hardware for low-energy transceiver modules.
- CE Marking Harmonization:ETSI testing regime standardization reduces country-by-country certification burden for radio equipment vendors targeting European Union member states. Pre-certified modules gain faster market entry.
Market Restraints
- Silicon Supply Concentration:Contract manufacturing for adapter chipsets clusters in China, South Korea, and Vietnam. Geopolitical friction or logistics disruption at any node propagates through finished goods availability.
- Spectrum Congestion:The 2.4 GHz ISM band hosts Wi-Fi, Zigbee, and microwave emissions alongside Bluetooth traffic. Interference degradation in dense urban environments limits reliable operating range for Class 2 and Class 3 devices.
- Native Integration Substitution:Laptop and smartphone OEMs increasingly embed combo Wi-Fi/Bluetooth silicon directly onto motherboards. Standalone adapter demand faces structural compression as new hardware ships with built-in capability.
Strategic Opportunities
- Industrial IoT Sensor Networks:Factory automation and predictive maintenance deployments in Germany and Japan require ruggedized BLE modules for asset tracking. Embedded solutions command margin premiums over consumer-grade dongles.
- Gaming Peripheral Low-Latency Niche:PCIe card form factors with specialized antenna configurations address competitive gaming segments where audio synchronization tolerance measures below 20 milliseconds. This application remains underpenetrated by generic USB adapters.
- FCC Pre-Certification Services:Second-tier module vendors can capture value by offering bundled RF compliance testing for customers lacking in-house regulatory expertise. This service layer differentiates commodity hardware.
Industry Challenges
- RF Engineering Talent Scarcity:Antenna design and electromagnetic compatibility testing require specialized skill sets. Vendors compete for limited pools of engineers familiar with ETSI and FCC filing procedures.
- Protocol Stack Integration Complexity:BLE 5.3 introduces extended advertising and periodic synchronization features that complicate firmware development. Smaller design houses struggle to maintain qualified software teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Adapter Market |
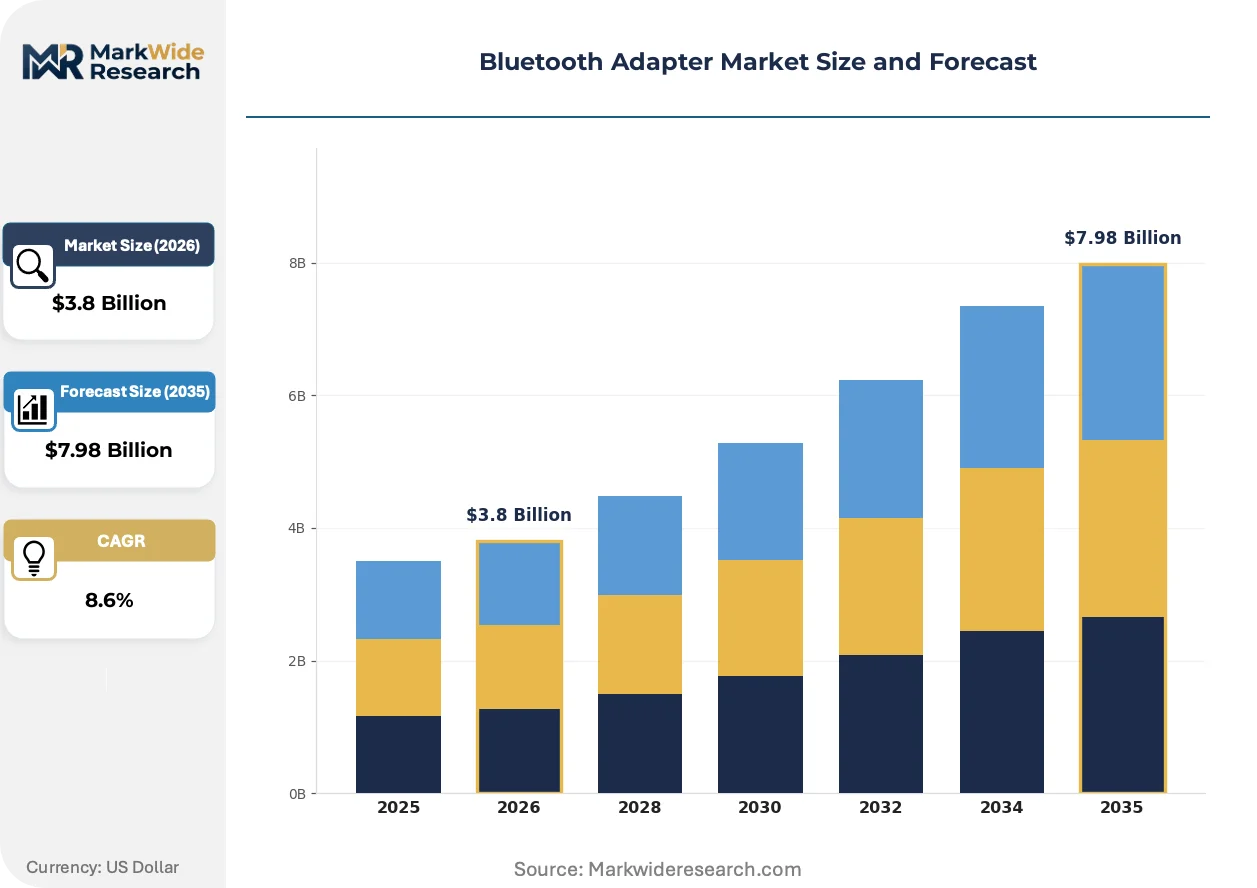
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Adapters, PCIe Cards, Audio Adapters, Embedded Modules End User: Consumer Electronics, Automotive Systems, Industrial Applications, Medical Devices Connectivity: Classic Bluetooth, BLE, Dual-Mode, Mesh Networking Form Factor: External, Internal, Dongle, PCB Mounted |
| Companies Covered | Qualcomm Technologies Inc., Broadcom Inc., Intel Corporation, Realtek Semiconductor Corp., ASUS, Logitech, Avantree, UGREEN, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Adapter Market Strategic Shifts
Protocol convergence and procurement channel migration are restructuring how Bluetooth capability reaches end devices. Three developments warrant particular attention.
USB-C connector standardization is collapsing the legacy USB-A adapter segment as laptop and mobile device ports transition universally. Peripheral OEMs are phasing out Mini-USB and Micro-USB variants from active product lines. The structural consequence is inventory compression across retail channels still holding obsolete form factors.
REACH substance restrictions in the European Union are forcing solder alloy reformulations and halogen-free substrate adoption in PCB manufacturing. Module vendors must requalify thermal profiles and reliability testing under revised material constraints. Medical and automotive embedded modules face the steepest compliance timeline pressure given extended certification cycles.
Direct-to-consumer e-commerce is displacing brick-and-mortar electronics retail as the primary volume channel for standalone adapters. Amazon and specialized audio equipment marketplaces capture search-driven purchases that previously flowed through big-box store shelf space. This shift is most visible in North American and Western European consumer segments where Prime membership penetration exceeds fifty percent.
Bluetooth Adapter Market Segmentation
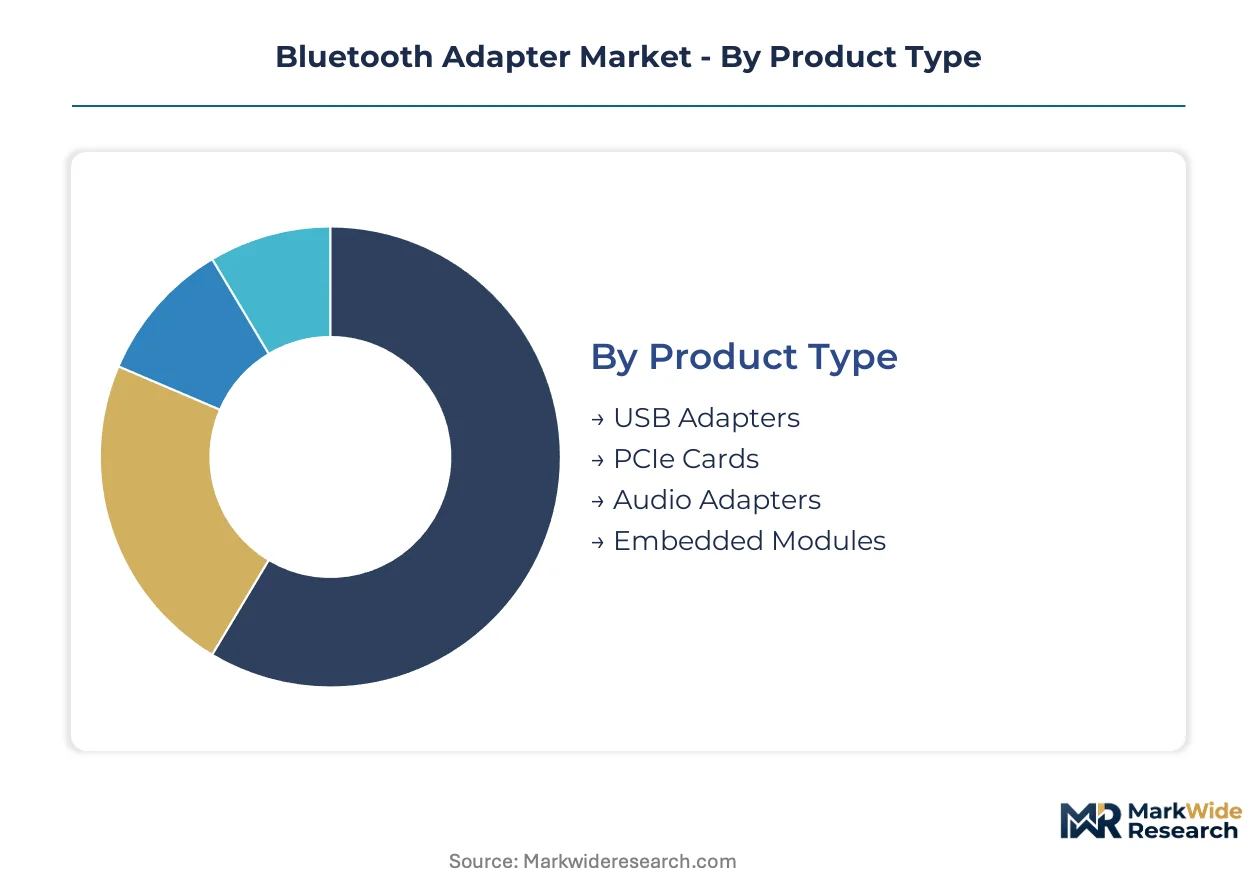
Segmentation in the Bluetooth Adapter Market reveals how hardware form, deployment context, and protocol architecture shape procurement patterns. Distinct technical requirements across automotive retrofit, industrial sensor networks, and consumer audio drive divergent product specifications and margin structures.
Product Type:
Use-case spectrum spans plug-and-play consumer retrofits to deeply integrated industrial subsystems requiring pre-certified RF modules.
- USB Adapters:Compact dongle transceivers with integrated antenna assemblies enable immediate Bluetooth capability for desktop PCs and legacy automotive head units. Demand concentrates in North American and Western European consumer channels where e-commerce platforms capture the majority of volume for plug-and-play retrofit solutions.
- Embedded Modules:Surface-mount transceiver packages with FCC and ETSI pre-certification integrate directly into OEM motherboard designs. Medical device manufacturers in Germany and Japan favor these for extended battery life in power-constrained diagnostic equipment, accepting margin premiums for regulatory compliance bundling.
- PCIe Cards:Low-latency expansion cards with specialized antenna configurations serve competitive gaming segments.
- Audio Adapters:Dedicated streaming bridges for legacy speaker systems and automotive infotainment retrofits.
Established volume favors USB Adapters; emerging adoption favors Embedded Modules.
End User:
Cost tier stratification separates high-volume consumer price points from ruggedized industrial specifications demanding extended temperature ranges.
- Consumer Electronics:Desktop audio streaming and peripheral pairing applications dominate procurement through Amazon and direct-to-consumer channels. Gaming peripheral manufacturers specify sub-20 millisecond latency tolerances that generic USB dongles cannot satisfy, creating specification premiums for specialized hardware.
- Industrial Applications:Factory automation deployments in Germany and Japan require BLE modules for asset tracking and predictive maintenance sensor networks. Ruggedized form factors with IP67 ratings and extended operating temperature ranges command substantial margin premiums over consumer-grade alternatives.
- Automotive Systems:Aftermarket head unit retrofits and fleet telematics integration.
- Medical Devices:Portable diagnostic equipment and patient monitoring systems.
Consumer Electronics maintains the broadest installed base; Industrial Applications delivers the steepest expansion trajectory.
Connectivity:
Protocol maturity curves determine where Classic Bluetooth persists versus where BLE displacement accelerates.
- BLE:Low-energy protocol stacks with extended advertising and periodic synchronization features enable multi-year battery life in sensor networks. Medical device manufacturers and industrial IoT deployments in Japan and Germany are transitioning from Classic Bluetooth to capture power budget advantages.
- Dual-Mode:Simultaneous Classic Bluetooth and BLE support maintains backward compatibility while enabling low-energy peripheral discovery. Automotive infotainment systems and premium consumer audio equipment specify dual-mode silicon to bridge legacy smartphone pairing with modern peripheral ecosystems.
- Classic Bluetooth:Legacy audio streaming protocol with higher power consumption profiles.
- Mesh Networking:Many-to-many node communication for building automation and smart lighting.
Dual-Mode captures the largest current revenue pool; BLE is gaining share fastest in net-new deployments.
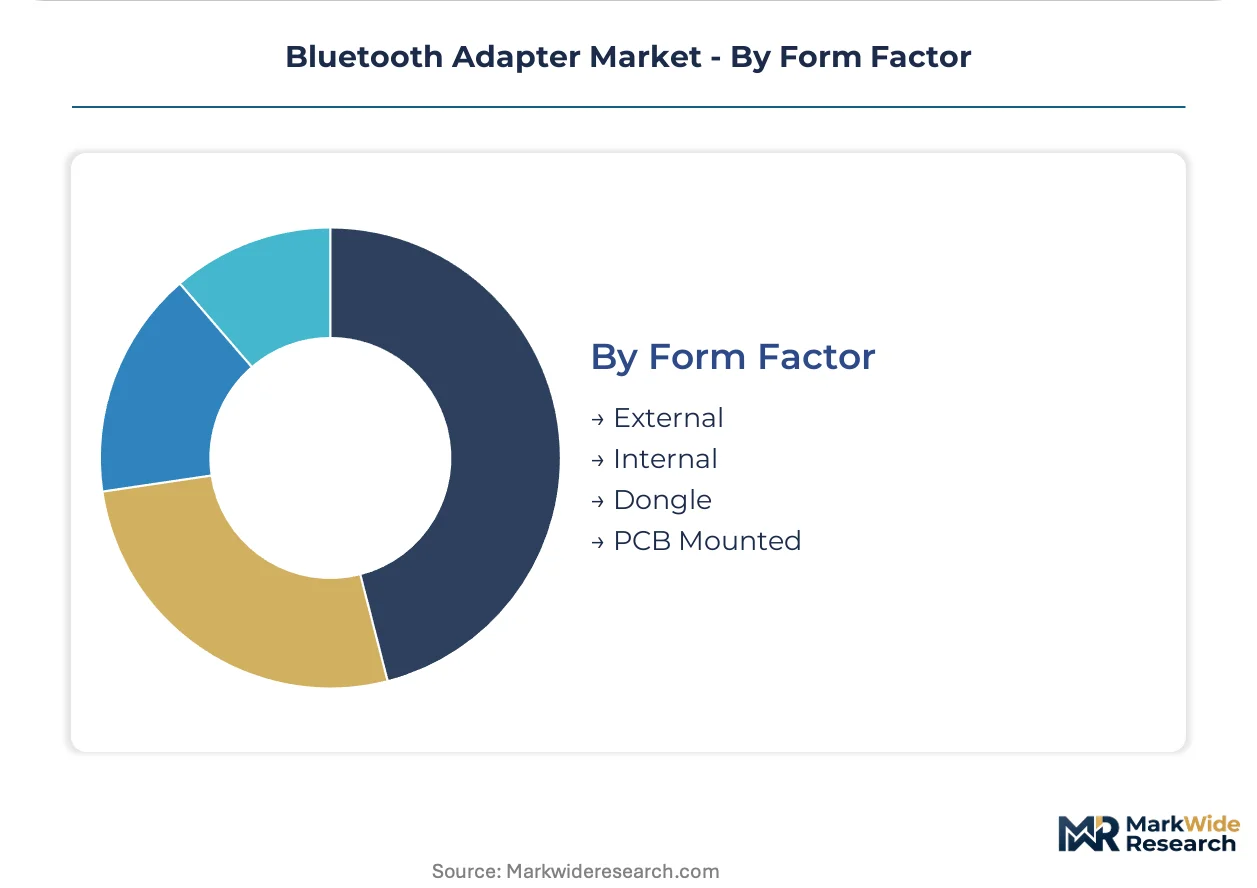
Form Factor:
Supply concentration in East Asian contract foundries shapes which physical configurations achieve cost-competitive scale.
- External:Self-contained housings with integrated antennas and USB or audio jack terminations. Retail channel inventory in North America and Western Europe has compressed around USB-C variants as USB-A and legacy Mini-USB form factors phase out of active manufacturing.
- PCB Mounted:Bare module assemblies for direct solder attachment to host system boards. Contract manufacturers in China, South Korea, and Vietnam concentrate output of PCB-mounted solutions for laptop OEM reference platforms and industrial controller integration.
- Dongle:Compact removable form factors optimized for portability and multi-device switching.
- Internal:Chassis-integrated solutions with cabled antenna extensions for metal-enclosure environments.
PCB Mounted dominates OEM integration volume; External configurations face structural compression from native motherboard integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen-Dongguan electronics corridor anchors East Asian contract manufacturing for Bluetooth adapter chipsets and finished assemblies. Rotterdam's port infrastructure underwrites European distribution logistics for pre-certified RF modules. The Dubai-Jebel Ali logistics hub facilitates Middle East re-export of consumer-grade dongles.
United States
FCC RF emissions governance shapes adapter certification timelines for desktop and automotive retrofit segments. The Inflation Reduction Act's domestic manufacturing incentives intersect with adapter production only indirectly through broader electronics reshoring initiatives. Austin and Raleigh-Durham host RF engineering talent pools serving module vendors seeking FCC pre-certification expertise.
Germany
Industrial IoT sensor networks in factory automation drive BLE module procurement for asset tracking and predictive maintenance. ETSI harmonized testing regimes determine CE marking eligibility, compressing country-by-country approval burdens. Munich and Stuttgart industrial clusters concentrate medical device manufacturers transitioning from Classic Bluetooth to BLE for power-constrained diagnostic equipment.
China
MIIT spectrum allocation and GB standards compliance govern domestic adapter sales while contract foundries in Shenzhen and Dongguan produce chipsets for global export. The dual carbon goals policy framework pressures manufacturing energy efficiency without directly targeting adapter specifications. Shanghai and Beijing host Bluetooth SIG certification facilities serving Asia-Pacific vendor qualification.
Japan
METI industrial policy supports BLE migration in medical devices and manufacturing sensor networks through standardization incentives. JIS certification requirements add a secondary compliance layer for radio equipment vendors beyond ETSI baselines. Osaka-Kansai manufacturing clusters specialize in ruggedized embedded modules for automotive and industrial applications.
South Korea
MFDS medical device regulations intersect with BLE adapter deployment in portable diagnostic equipment. Samsung and LG supply chain ecosystems create captive demand for combo Wi-Fi/Bluetooth silicon in consumer electronics. Seoul Capital Area semiconductor fabrication facilities produce adapter chipsets alongside memory and display components.
Bluetooth Adapter Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the RF silicon and certification services layer. The vendor base concentrates around three strategic archetypes: fabless semiconductor designers holding protocol stack IP, contract manufacturers offering bundled regulatory compliance, and peripheral OEMs differentiating through low-latency gaming specialization. Dominant competitive moves include strategic partnerships between chipset vendors and laptop reference platform designers, plus backward integration by module suppliers into FCC pre-certification service offerings.
Within the fabless semiconductor tier, Qualcomm Technologies Inc. and Broadcom Inc. occupy positions defined by Snapdragon and combo silicon portfolios respectively. ASUS exemplifies the gaming peripheral specialization archetype through low-latency PCIe card differentiation. Realtek Semiconductor Corp. anchors the cost-optimized USB adapter segment serving high-volume consumer retrofit demand.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Broadcom Inc. |
| Intel Corporation |
| Realtek Semiconductor Corp. |
| ASUS |
| Logitech |
| Avantree |
| UGREEN |
| Microchip Technology |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Shenzhen-Dongguan contract foundries for BLE 5.3 pre-certified modules compresses margin flexibility across all pricing tiers while amplifying exposure to export-control friction. This concentration dynamic forces tier spreads that reward FCC/ETSI bundling premiums at the top and punish undifferentiated USB-A dongle inventory at the bottom.
Pricing Analysis
Volume-discount tiering structures stratify across pre-certified embedded modules, gaming-specialized PCIe cards, and commodity USB dongles. FCC and ETSI certification bundling commands premium positioning in medical and automotive embedded segments, while undifferentiated consumer-grade dongles face cost compression from USB-C transition obsolescence. Pricing pressure stems from native Bluetooth integration in laptop and smartphone motherboards eroding standalone adapter attach rates. Industrial IoT buyers exhibit lowest price sensitivity due to ruggedization requirements, whereas consumer retail channels show acute sensitivity to sub-dollar unit differentials.
Supply Chain Analysis
Export-control regime restrictions on RF semiconductor manufacturing equipment limit capacity expansion at contract foundries in China, South Korea, and Vietnam. Adapter chipset production draws from silicon wafers, 2.4 GHz antenna substrates, and halogen-free PCB laminates subject to REACH compliance timelines. Single-source vulnerability concentrates in Shenzhen-Dongguan assembly corridors where geopolitical friction propagates through finished goods availability. Distribution runs through Rotterdam for European pre-certified modules and Dubai-Jebel Ali for Middle East consumer re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native Bluetooth integration in consumer electronics presents a substitution threat that incumbent adapter vendors must navigate through specialization and service-layer differentiation. Defense requires abandoning commodity dongle exposure while capturing value from regulatory complexity.
For Market Incumbents: Pre-empt margin erosion by backward integration into FCC pre-certification service offerings that differentiate commodity hardware. Retreat from USB-A consumer dongle inventory and redirect capacity toward ruggedized BLE modules for German and Japanese industrial IoT deployments. Certification bundling creates defensive moats that native silicon integration cannot replicate.
For New Entrants and Emerging Players: Build out low-latency gaming peripheral specialization where sub-20 millisecond audio synchronization tolerances remain underpenetrated by generic USB adapters. Target PCIe card form factors with specialized antenna configurations for competitive gaming segments. Go-to-market leverage comes through direct-to-consumer e-commerce channels that bypass compressed retail shelf space.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors module vendors with captive regulatory expertise and pre-certified RF portfolios. Long-term viability hinges on industrial IoT sensor network penetration rather than consumer audio retrofit cyclicality. Watch BLE protocol migration velocity in medical devices as the inflection signal for embedded module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FCC Pre-Certification Service Launch | Captures margin from second-tier module vendors lacking in-house RF compliance expertise. |
| USB-C Form Factor Transition | Phases out obsolete USB-A inventory while aligning with laptop OEM port standardization roadmaps. |
| Industrial IoT Module Specialization | Targets German factory automation clusters requiring IP67-rated ruggedization and extended temperature ranges. |
| Gaming Peripheral Low-Latency Development | Addresses competitive segments where audio synchronization tolerance measures below 20 milliseconds. |
| REACH Compliance Material Requalification | Enables continued CE marking eligibility through halogen-free substrate and solder alloy reformulations. |
Study Parameters
Desk research of Bluetooth SIG certification databases, FCC equipment authorization records, and ETSI harmonized standards preceded structured interviews with RF module design engineers, contract manufacturing procurement leads, and industrial IoT systems integrators. Primary fieldwork captured qualification timelines and pre-certification cost structures across Shenzhen-Dongguan, Seoul Capital Area, and Osaka-Kansai manufacturing clusters. Secondary validation drew from customs trade flows, semiconductor foundry capacity disclosures, and medical device OEM regulatory filings. Bottom-up unit economics triangulated against top-down market sizing across product type and end-user segments.
Assumptions held fixed include BLE 5.3 certification mandate adherence timelines, REACH substance restriction phase-in schedules, and USB-C connector transition velocity in consumer electronics. The analytical framework modeled volume and value across the projection horizon through protocol migration curves, native integration substitution rates, and industrial IoT deployment trajectories. Segmentation dimensions spanned product type, end-user vertical, connectivity protocol, and geographic regulatory cluster. CAGRs derived from weighted average of adoption curve inflections and replacement cycle dynamics. Forecast inputs incorporated FCC certification backlog durations and ETSI testing regime harmonization progress.
Stress conditions across tariff exposure on Chinese contract manufacturing, semiconductor equipment export-control tightening, and spectrum reallocation debates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding protocol transition velocity and regulatory compliance timelines. Material shifts in native Bluetooth integration rates or BLE certification mandate delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
PTC Resettable Device Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Loudspeaker Market
Electronic Components
Timing Relay Market
Electronic Components
SAW Filters Market
Electronic Components
Digital Pulse Mixer Market
Electronic Components
Docking Station Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Display Port Adapters Market
Electronic Components
Global Capacitor Market
Electronic Components
AC Adapter Market
Electronic Components
Capacitor Kits Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Wireless Charging Stand Market