
 Efuse Market | 2026-2036
Efuse Market Size, Share, and Industry Trends Forecast 2026-2036
Efuse Market Analysis
Multi-source procurement among automotive OEMs is broadening the vendor landscape for programmable efuse solutions. Texas Instruments Incorporated leverages its analog foundry depth to sustain design-in relationships with Detroit-based EV platforms. Infineon Technologies AG anchors European supply chains through its SiC-integrated efuse portfolios. STMicroelectronics competes on MEMS-based architectures that occupy industrial automation sockets.
An efuse is a semiconductor-based programmable fuse element fabricated on CMOS or BCD processes, typically rated from milliamps to tens of amps, that enables one-time or reconfigurable trimming of resistance, voltage thresholds, or memory states for circuit calibration and protection. Its primary purpose spans power management precision, overcurrent isolation, and post-manufacturing device personalization across analog and mixed-signal systems. Smart Efuses command margin pools in automotive battery management systems where firmware-adjustable trip points reduce hardware redundancy. Passive Efuses retain volume dominance in consumer electronics cost-optimized designs. Active Efuses lead growth in telecommunications infrastructure demanding hot-swap protection with telemetry feedback.
FCC equipment authorization rules shape electromagnetic compatibility thresholds for efuse-integrated power modules sold into US telecommunications infrastructure. EPA automotive efficiency standards indirectly drive efuse complexity by mandating finer-grained power distribution control in electrified drivetrains. ISO 26262 functional safety requirements compel automotive-grade efuse suppliers to demonstrate fault coverage metrics. Stakeholders must weigh MEMS versus pure semiconductor technology bets as hybrid architectures gain traction in aerospace and defense qualification pipelines.
Market Dynamics
Automotive powertrain electrification is forcing efuse architectures toward firmware-adjustable protection thresholds that eliminate redundant hardware. Tier-1 suppliers now specify programmable trip points across battery management systems, compressing design cycles for analog foundry partners.
Growth Catalysts
- China's dual carbon goals:Stricter EV safety mandates from MEE are reshaping procurement standards for battery isolation circuits. Domestic OEMs now require efuse-integrated power distribution modules.
- Telecommunications infrastructure:FCC equipment authorization rules for electromagnetic compatibility are accelerating hot-swap protection deployments. Active efuses with telemetry feedback dominate 5G base station builds.
- MEMS-semiconductor hybridization:Aerospace and defense qualification pipelines are validating mixed architectures for extreme environment reliability. Dual-technology sourcing is expanding vendor qualification lists.
Market Restraints
- Foundry concentration:BCD process capacity constraints in Taiwan and South Korea are extending lead times for automotive-grade efuse wafers. Multi-source qualification remains incomplete.
- Silicon carbide integration costs:SiC-efuse co-packaging requires specialized packaging substrates that inflate bill-of-materials by 40-60% versus discrete solutions.
- ISO 26262 compliance burden:Functional safety documentation requirements are extending automotive design-in cycles by 18-24 months for new supplier entrants.
Strategic Opportunities
- Industrial automation retrofits:Legacy motor control systems in Germany and Japan are creating aftermarket demand for programmable overcurrent protection. MEMS-based efuse sockets offer drop-in replacement paths.
- India PLI scheme:Domestic electronics manufacturing incentives are attracting efuse packaging and test investments. Local value-add requirements favor joint ventures with Indian EMS providers.
- Solid-state battery architectures:Next-generation cell chemistries require finer-grained fuse granularity than conventional PTC devices. Efuse arrays enable cell-level isolation without mechanical breakers.
Industry Challenges
- Mixed-signal design talent scarcity:BCD process expertise for efuse analog-digital integration concentrates among senior engineers at established IDMs. University pipeline output lags demand.
- Automotive qualification timelines:AEC-Q100 stress testing and PPAP documentation create 30-36 month paths to production revenue for new efuse variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Efuse Market |
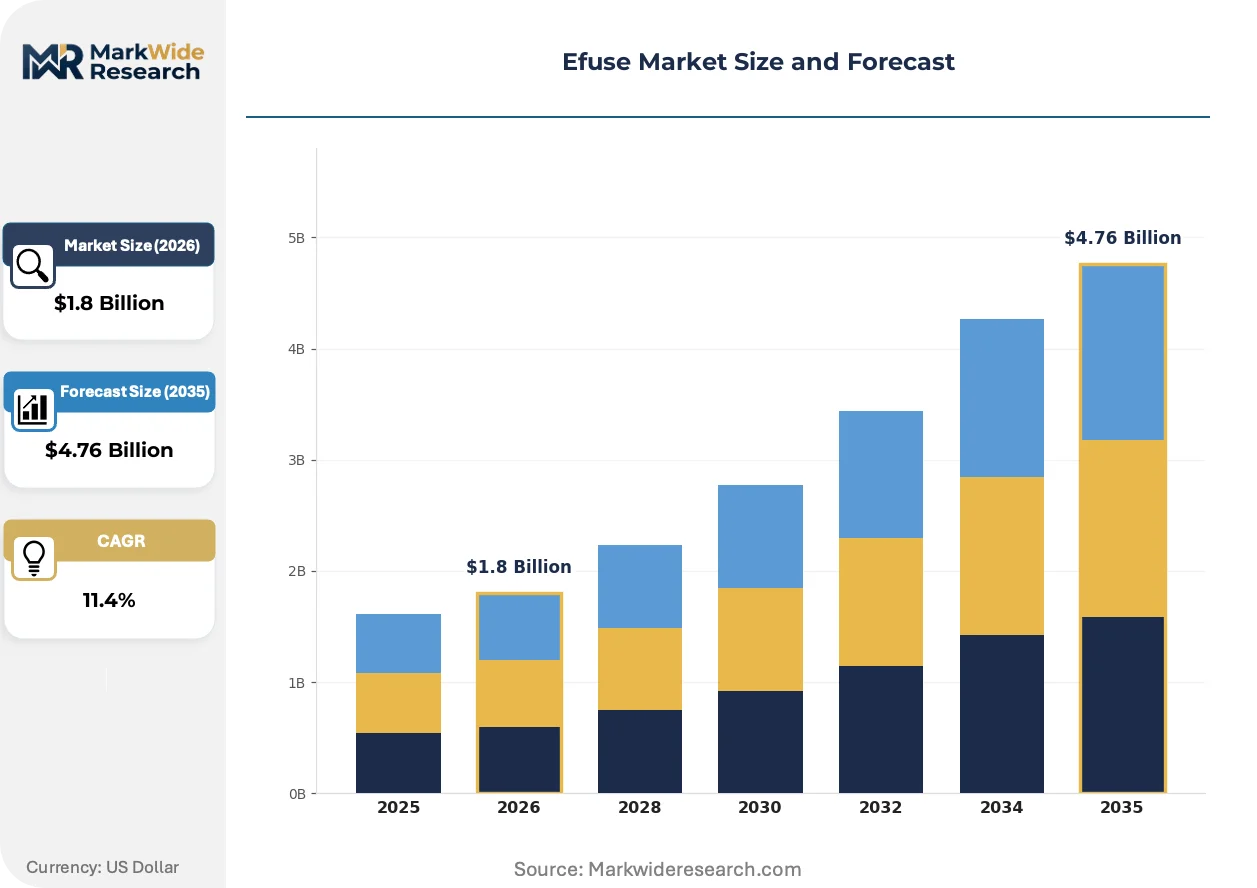
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Efuses, Passive Efuses, Smart Efuses, High Voltage Efuses End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Power Management, Voltage Regulation, Overcurrent Protection, Circuit Protection Technology: MEMS, Semiconductor, Hybrid, Integrated Circuit |
| Companies Covered | Littelfuse, Inc., Texas Instruments Incorporated, Toshiba Electronic Devices & Storage Corporation, Semiconductor Components Industries, LLC, Alpha and Omega Semiconductor, Analog Devices, Inc., Infineon Technologies AG, STMicroelectronics, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Efuse Market Emerging Trajectories
Silicon carbide integration is compressing the boundary between power switching and protection functions. Efuse vendors are repositioning around system-level power management rather than discrete component supply.
Monolithic SiC-efuse co-packaging is consolidating protection and switching into single-die solutions for 800V automotive architectures. EV platform teams at Detroit-based OEMs are adopting these integrated modules to reduce magnetic component count. The technology is consolidating tier-2 supplier roles into fewer system-level providers.
EU Green Deal battery passport requirements are mandating component-level traceability across cell management systems. Efuse suppliers must now embed unique identifiers readable through power line communication. Automotive battery pack assemblers in Germany and Poland are retooling procurement specifications to capture this data layer.
Long-term service contracts are displacing spot purchasing for telecommunications infrastructure efuse modules. Network equipment buyers now prioritize 10-year availability guarantees over unit cost minimization. This pattern is most visible in North American 5G rural deployment programs where FAA tower lighting regulations extend equipment lifecycles.
Efuse Market Segmentation
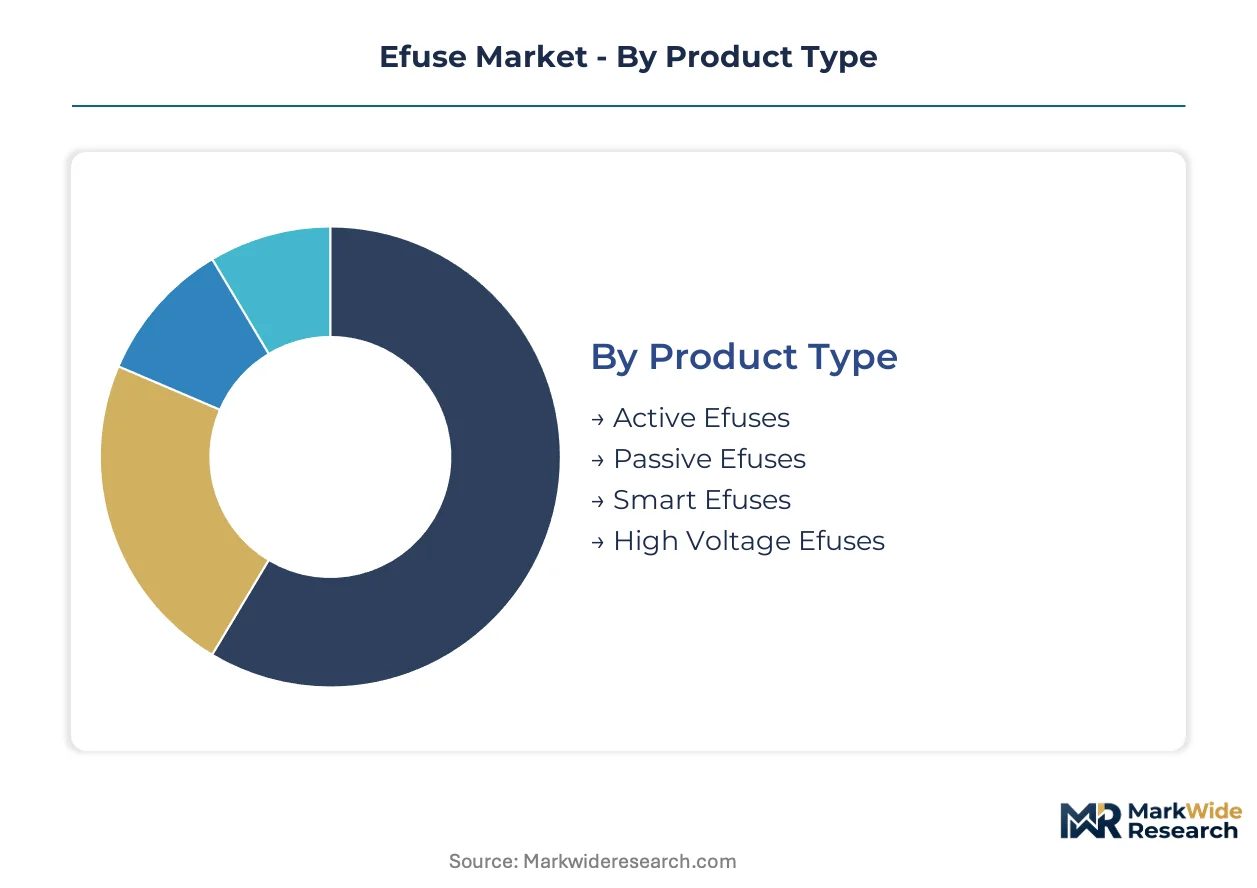
Efuse architectures diverge sharply across voltage ratings and programmability levels, creating distinct margin pools for suppliers. Procurement teams segment sourcing strategies by integration complexity and end-use safety requirements.
Product Type:
Supply concentration for automotive-grade programmable variants rests with analog foundries possessing BCD process depth.
- Active Efuses:These devices incorporate integrated sensing and control circuitry enabling real-time telemetry feedback. Demand concentrates in North American 5G rural deployment programs where FAA tower lighting regulations extend equipment lifecycles and mandate hot-swap protection with diagnostic visibility.
- Smart Efuses:Firmware-adjustable trip points enable post-deployment threshold calibration without hardware swaps. Battery management system procurement at Detroit-based EV platforms favors these solutions to reduce redundant protection circuitry.
- Passive Efuses:One-time programmable elements fabricated on standard CMOS processes serve cost-optimized consumer electronics.
- High Voltage Efuses:Rated for 800V automotive architectures, these require specialized isolation structures and qualification protocols.
Passive Efuses absorb the bulk of installed capacity; Smart Efuses are expanding most quickly.
End User:
Cost tier stratification separates safety-critical automotive qualification from high-volume consumer electronics price sensitivity.
- Automotive:ISO 26262 functional safety requirements compel AEC-Q100 stress testing and PPAP documentation, creating 30-36 month paths to production revenue. China's MEE stricter EV safety mandates are reshaping procurement standards for battery isolation circuits.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize millimeter-scale form factors and sub-dollar unit economics.
- Telecommunications:FCC equipment authorization rules for electromagnetic compatibility accelerate deployments with telemetry feedback. Network equipment buyers now prioritize 10-year availability guarantees over unit cost minimization.
- Industrial Equipment:Legacy motor control systems in Germany and Japan are creating aftermarket demand for programmable overcurrent protection.
Automotive commands the steepest expansion trajectory; Consumer Electronics retains volume dominance.
Application:
Application selection correlates with voltage granularity requirements and response speed specifications.
- Power Management:EPA automotive efficiency standards indirectly drive complexity by mandating finer-grained power distribution control in electrified drivetrains. Efuse arrays enable precision trimming of voltage rails across multiple load domains.
- Overcurrent Protection:Solid-state battery architectures require finer-grained fuse granularity than conventional PTC devices, enabling cell-level isolation without mechanical breakers.
- Voltage Regulation:Post-manufacturing device personalization spans analog and mixed-signal systems requiring tight threshold accuracy.
- Circuit Protection:Hot-swap scenarios in telecommunications infrastructure demand sub-millisecond trip response with self-resetting capability.
Power Management absorbs the bulk of design-in activity; Overcurrent Protection is climbing the fastest.
Technology:
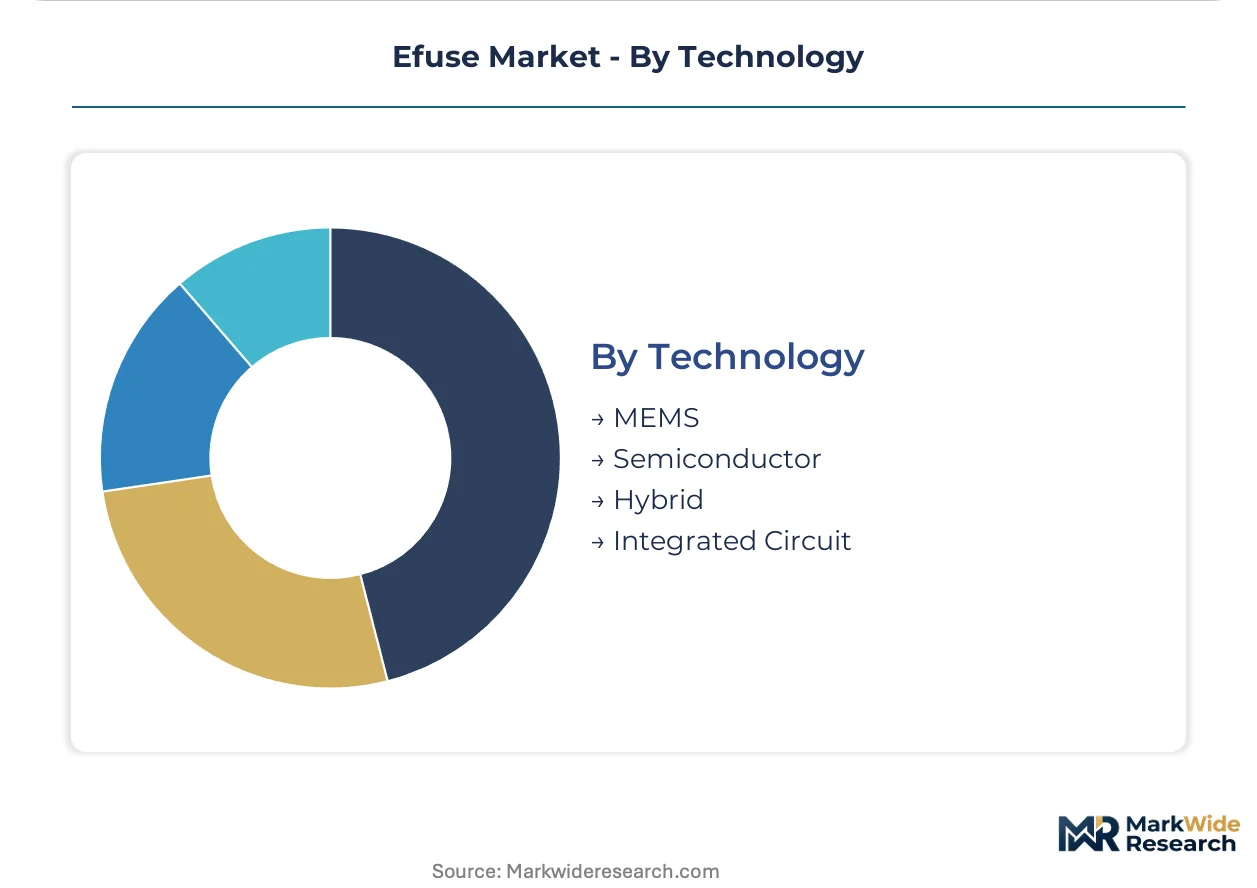
Technology bets concentrate on MEMS versus pure semiconductor tradeoffs as hybrid architectures gain traction.
- Semiconductor:CMOS and BCD process implementations dominate volume production, with capacity constraints in Taiwan and South Korea extending lead times for automotive-grade wafers.
- MEMS:Microelectromechanical structures occupy industrial automation sockets offering drop-in replacement paths for legacy electromechanical breakers.
- Hybrid:Aerospace and defense qualification pipelines are validating mixed architectures for extreme environment reliability, expanding vendor qualification lists.
- Integrated Circuit:Monolithic co-packaging of protection and switching functions consolidates tier-2 supplier roles into fewer system-level providers.
Semiconductor technology absorbs the bulk of wafer starts; Hybrid architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and telecommunications infrastructure are concentrating efuse procurement across East Asian semiconductor clusters, German automotive hubs, and North American 5G deployment corridors.
China
Domestic OEMs are accelerating efuse-integrated power distribution module procurement under MEE stricter EV safety mandates. The dual carbon goals framework is reshaping battery isolation circuit standards. Yangtze River Delta semiconductor foundries are expanding BCD process capacity to serve Tier-1 automotive suppliers.
Germany
Automotive battery pack assemblers are retooling procurement specifications to capture EU Green Deal battery passport traceability requirements. Legacy motor control systems are creating aftermarket demand for programmable overcurrent protection. Industrial clusters in Bavaria and Baden-Württemberg are validating MEMS-based efuse architectures for automation retrofits.
United States
FCC equipment authorization rules for electromagnetic compatibility are accelerating hot-swap protection deployments in 5G rural infrastructure. FAA tower lighting regulations are extending equipment lifecycles and mandating telemetry feedback capabilities. Detroit-based EV platforms are adopting firmware-adjustable trip point solutions to reduce hardware redundancy.
South Korea
BCD process capacity constraints are extending lead times for automotive-grade efuse wafers serving domestic and export markets. Foundry partners are prioritizing multi-source qualification for battery management system suppliers. Seoul Capital Area semiconductor manufacturing clusters are concentrating analog-digital integration expertise.
Japan
METI industrial efficiency standards are indirectly driving finer-grained power distribution control requirements in factory automation systems. Legacy electromechanical breaker replacement programs are expanding MEMS-based efuse sockets. Kansai and Chubu industrial corridors are hosting qualification pipelines for extreme environment reliability architectures.
Efuse Market Vendor Landscape
Strategic partnerships dominate the current landscape as analog foundries align with automotive platform teams to compress design-in cycles. The vendor base concentrates among integrated device manufacturers with BCD process depth, fabless specialists licensing analog IP, and diversified semiconductor conglomerates with SiC packaging capabilities. Three archetypes define competitive positioning: analog-centric IDMs, power semiconductor diversifiers, and MEMS-semiconductor hybrid specialists. Portfolio diversification toward system-level power management and geographic expansion into Indian EMS joint ventures represent the dominant competitive vectors.
Within the analog-centric IDM tier, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions sustained by foundry depth and design-in relationships with automotive platforms. Infineon Technologies AG anchors the power semiconductor diversifier archetype through European supply chain integration. STMicroelectronics exemplifies the MEMS-based architecture path for industrial automation applications.
| Leading Market Players |
|---|
| Littelfuse, Inc. |
| Texas Instruments Incorporated |
| Toshiba Electronic Devices & Storage Corporation |
| Semiconductor Components Industries, LLC |
| Alpha and Omega Semiconductor |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| ABB |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot indices and BCD process capacity utilization rates cascade through automotive-grade efuse supply chains, compressing margins for fabless entrants while amplifying pricing power for integrated device manufacturers with captive foundry access.
Pricing Analysis
Volume-massive passive efuses absorb thin margins in consumer electronics, while programmable smart variants command premium positioning in automotive battery management systems. Three-tier pricing structure across AEC-Q100 certified, industrial-grade, and commercial-grade tiers separates procurement pools. Pricing pressure stems from foundry concentration in Taiwan and South Korea extending lead times and inflating wafer costs. Consumer electronics OEMs exhibit acute price sensitivity, whereas Detroit-based EV platforms prioritize firmware-adjustable trip points over unit economics.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke fulfillment patterns for efuse modules serving telecommunications infrastructure. Manufacturing concentrates in Taiwan, South Korea, and China, with BCD process capacity constraints creating single-source vulnerability for automotive-grade wafers. Raw material dependencies span silicon substrates, copper leadframes, and specialized molding compounds. Distribution runs through authorized distributors and direct OEM contracts, with long-term service contracts displacing spot purchasing in 5G infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ISO 26262 functional safety documentation creates an 18-24 month barrier-to-entry moat for automotive-grade efuse suppliers, entrenching incumbents with established AEC-Q100 qualification pipelines.
For Market Incumbents: Deepen backward integration into BCD process capacity through foundry partnerships in South Korea and Taiwan, insulating against wafer shortage risks. Prioritize MEMS-semiconductor hybrid R&D to capture aerospace qualification pipelines before specialty entrants consolidate dual-technology sockets. For New Entrants and Emerging Players: Launch via joint ventures with Indian EMS providers under PLI scheme incentives, exploiting domestic value-add requirements that favor local packaging partnerships. Target industrial automation retrofits in Germany and Japan where legacy motor control systems create white-space demand for programmable overcurrent protection without automotive qualification burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor analog-centric IDMs with established Detroit design-in relationships and captive BCD capacity. Long-term viability hinges on system-level power management repositioning rather than discrete component supply. Watch for FAA tower lighting regulation amendments as signal for telecommunications infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Partnership | Secures BCD wafer allocation for automotive-grade efuse production against Taiwan capacity constraints. |
| MEMS-Semiconductor Hybrid Development | Opens aerospace and defense qualification pipelines requiring extreme environment reliability. |
| Indian PLI Joint Venture | Captures domestic electronics manufacturing incentives favoring local packaging investments. |
| Firmware-Adjustable Trip Point Launch | Addresses Detroit EV platform demand for post-deployment calibration without hardware swaps. |
| Battery Passport Traceability Integration | Aligns with EU Green Deal requirements for component-level identification in German pack assembly. |
Methodological Framework
SEC 10-K filings, customs trade databases, and AEC-Q100 qualification registries formed the secondary backbone, cross-referenced with primary interviews spanning Tier 1 automotive supplier procurement leads, analog foundry process engineers, telecommunications infrastructure buyers, and industrial automation retrofit specialists. Bottom-up demand modeling triangulated against top-down semiconductor industry revenue allocations.
Historical trendline analysis of automotive electronics content per vehicle and telecommunications infrastructure capex patterns anchored the projection framework across voltage rating, programmability level, end-use safety tier, and technology architecture segments. CAGRs derived from elasticity-adjusted adoption curves incorporating EPA automotive efficiency standard trajectories and FCC equipment authorization rule evolution.
Foundry capacity expansion delays, MEE regulatory amendments, and solid-state battery chemistry transitions are the dominant revision risks to modeled outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Crystal Oscillators Market
Electronic Components
Dual Relay Board Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Loudspeaker Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Braking Resistors Market
Electronic Components
Electronic Wipe Market
Electronic Components
Automation Component Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Battery Holders Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Power Resistor Market