
 Global Chocolate Sprinkles Market | 2026-2036
Global Chocolate Sprinkles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chocolate Sprinkles Market Foresight
EU F-Gas Regulation is pivoting refrigeration-dependent chocolate processing toward lower-impact cooling systems, raising capital requirements for new entrants. Carroll Industries leverages captive cocoa butter refining to sustain margin control across European supply chains. Twinkle Sprinkles anchors its position through specialized enrobing technology for uniform shell thickness. Girrbach dominates artisan channel distribution in German-speaking markets through direct bakery relationships.
Chocolate sprinkles consist of confectionery particulates manufactured through extrusion or panning of tempered chocolate mass into standardized shapes, typically 2–8 mm in length with fat content between 25% and 35% to ensure snap resistance and melt stability in ambient storage. Their primary commercial function is to provide visual differentiation, textural contrast, and flavor layering across finished desserts and baked goods. Milk chocolate sprinkles still occupy the largest volume share due to cost-efficient cocoa solid ratios and universal palate compatibility, though vegan chocolate sprinkles are recording the fastest trajectory as plant-based fat systems from oat and coconut sources displace dairy inclusions. Application through baked goods concentrates the deepest margin pools, since industrial croissant and muffin lines require calibrated dosing consistency that commands technical premiums over decorative ice cream topping uses.
FDA oversight of confectionery labeling in the United States, EFSA purity criteria for vegetable fats in chocolate products, and BIS packaging standards in India collectively determine which formulations cross borders and which face reformulation costs. REACH chemical compliance in Europe further constrains coating agents and surface gloss compounds, pushing manufacturers toward audited supply chains. Stakeholders must monitor how divergent clean-label thresholds across FDA, EFSA, and BIS jurisdictions fragment product portfolios and force regional SKU proliferation without scale economies.
Market Dynamics
EU F-Gas Regulation is forcing chocolate processors to abandon hydrofluorocarbon cooling systems, raising capital barriers for new entrants while advantaging incumbents with captive low-impact refrigeration infrastructure.
Growth Catalysts
- Clean-label ingredient mandates:EFSA purity criteria for vegetable fats are pushing manufacturers toward audited supply chains that command technical premiums from industrial bakeries.
- Artisan bakery expansion:Western Europe's premium decoration ingredient demand is concentrating in Germany's Rhine-Ruhr manufacturing belt, creating localized volume anchors.
- Plant-based fat systems:Oat and coconut-derived alternatives are displacing dairy inclusions, opening formulation white space for vegan chocolate sprinkles.
Market Restraints
- Cocoa butter price volatility:Input cost swings constrain margin predictability for processors lacking captive refining capabilities.
- Supply concentration risk:Cologne-centered confectionery clusters create geographic vulnerability to regional logistics disruptions.
- REACH compliance friction:ECHA chemical restrictions on coating agents force reformulation cycles that fragment product portfolios.
Strategic Opportunities
- Underpenetrated Indian market:BIS packaging standards compliance opens pathways for exporters meeting local purity thresholds.
- Enrobing technology convergence:Specialized shell-thickness control systems are enabling premium uniform-coating applications in artisan channels.
- Direct bakery distribution:Bypassing traditional wholesale layers captures margin pools in German-speaking markets through relationship-based supply contracts.
Industry Challenges
- Refrigeration retrofit capex:F-Gas Regulation compliance demands capital-intensive cooling system overhauls for tempering and storage operations.
- SKU proliferation complexity:Divergent FDA, EFSA, and BIS clean-label thresholds force regional formulation variants without scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chocolate Sprinkles Market |
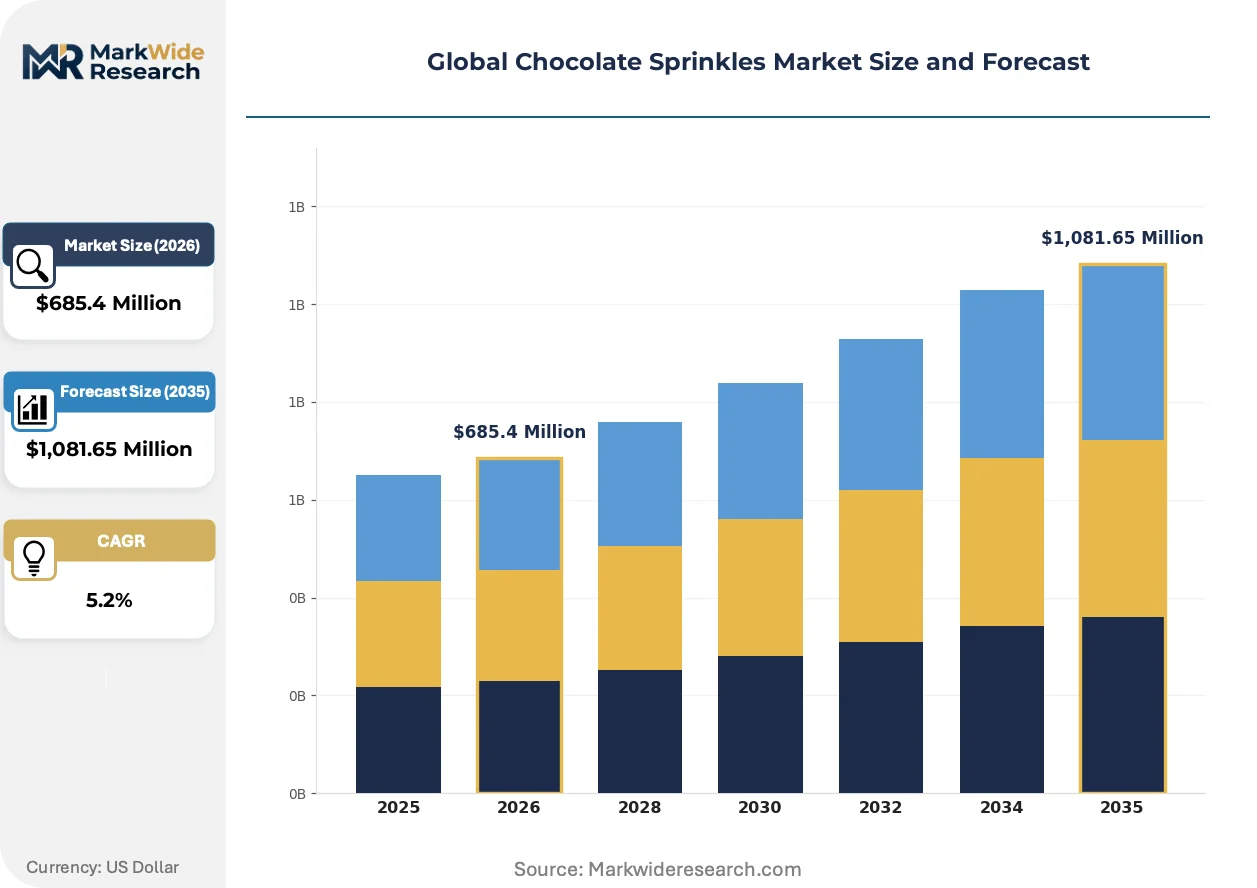
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Chocolate Sprinkles, Dark Chocolate Sprinkles, White Chocolate Sprinkles, Ruby Chocolate Sprinkles, Vegan Chocolate Sprinkles Application: Baked Goods, Ice Cream Decoration, Confectionery Toppings, Beverage Garnishing, Pastry Decoration Packaging Type: Plastic Bottles, Sachets, Glass Jars, Box Packs, Recyclable Pouches Customer Type: Artisan Bakers, Dessert Cafes, Food Service Providers, Supermarkets, Specialty Retailers |
| Companies Covered | Carroll Industries, Twinkle Sprinkles, Candy Manufacturer, Girrbach, CNS Confectionery, Mamy Sugarcraft, Sweets Indeed, Sprinkle Company, Cake Craft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chocolate Sprinkles Market Shifts & Advancements
Processing technology and regulatory compliance frameworks are compressing competitive advantage timelines, forcing simultaneous investment in equipment automation and supply chain transparency.
Specialized enrobing systems with real-time shell-thickness monitoring are electrifying quality consistency standards across premium decoration segments. Artisan bakeries in Western Europe are adopting these systems fastest, replacing manual dosing methods. The technology is compressing defect-rate differentials between mid-tier and premium producers.
REACH chemical compliance is tightening coating agent specifications across European manufacturing. ECHA audits now cover surface gloss compounds previously exempt from scrutiny. Small-scale processors without reformulation capabilities are exiting the market or seeking toll-manufacturing partnerships.
Industrial croissant and muffin lines are consolidating supplier relationships around calibrated dosing consistency. Technical premiums for precision-engineered particulates are displacing commodity decorative toppings in high-volume baking operations. This procurement compression is most visible in Germany's industrial bakery clusters.
Global Chocolate Sprinkles Market Segmentation
Chocolate sprinkles segment along four functional axes that determine procurement economics and margin capture. Product formulation dictates input cost structures and regulatory compliance burdens. Application specificity drives technical specification requirements and pricing power. Packaging format shapes distribution channel access and shelf-life performance. Customer type determines volume scale and relationship intensity.
Product Type:
Formulation chemistry and fat-system composition define the technical differentiation axis across product types.
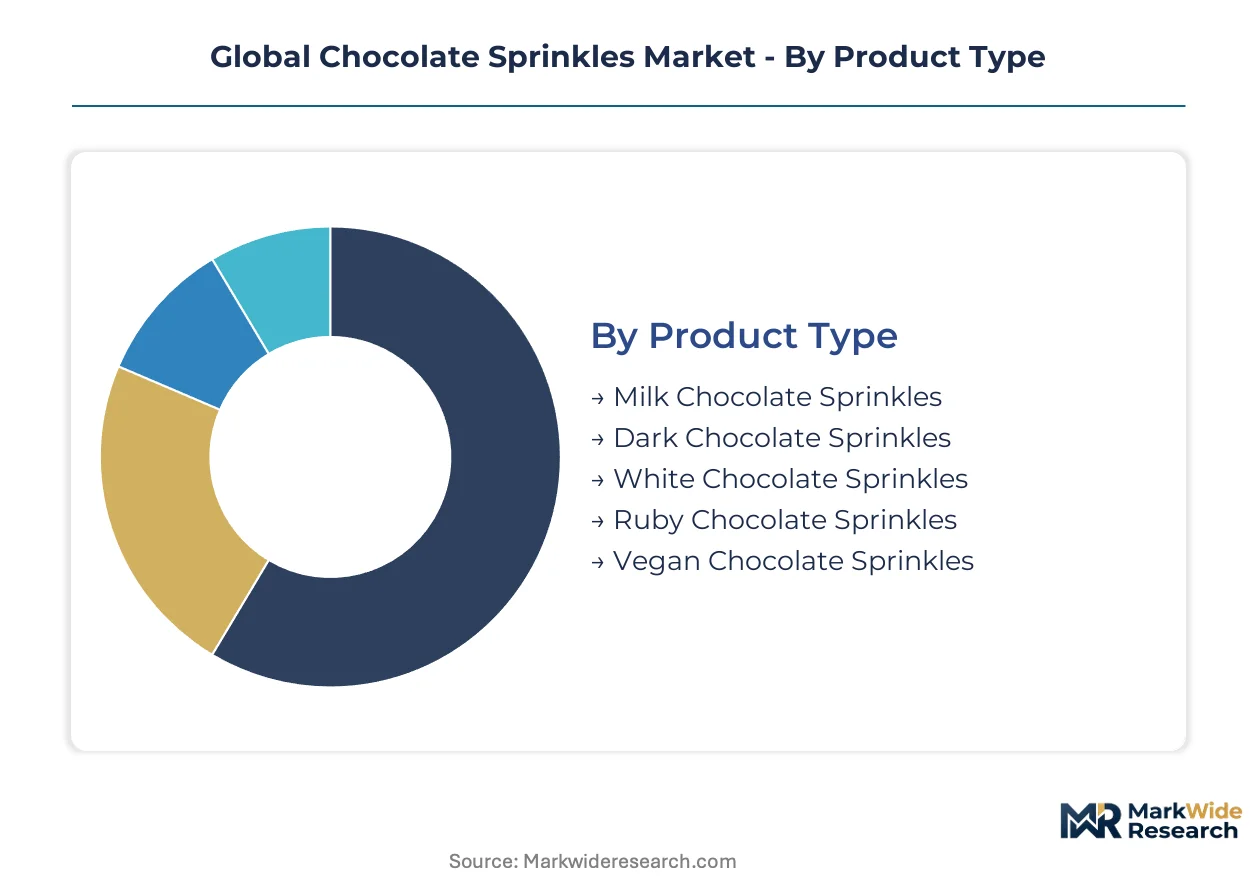
- Milk Chocolate Sprinkles:Cocoa butter ratios between 25% and 30% deliver cost-efficient snap resistance and ambient stability. Industrial croissant and muffin lines in Germany's Rhine-Ruhr belt source these for calibrated dosing consistency that commands technical premiums.
- Vegan Chocolate Sprinkles:Plant-based fat systems from oat and coconut sources displace dairy inclusions entirely. Artisan bakeries across Western Europe are expanding procurement fastest as clean-label mandates from EFSA tighten formulation standards.
- Dark Chocolate Sprinkles:Higher cocoa solid content provides bitter flavor layering for premium dessert applications.
- White Chocolate Sprinkles:Cocoa butter base without cocoa solids offers neutral color contrast in decorative applications.
- Ruby Chocolate Sprinkles:Ruby cocoa bean derivatives deliver distinctive pink hue without artificial colorants.
Milk chocolate sprinkles lead on scale; vegan chocolate sprinkles lead on momentum.
Application:
End-use functionality determines specification stringency and supplier qualification requirements.
- Baked Goods:Tempered chocolate mass requires 2–8 mm length standardization for automated dosing on industrial lines. This segment concentrates the deepest margin pools since precision-engineered particulates displace commodity toppings in high-volume operations.
- Ice Cream Decoration:Fat content above 30% ensures melt resistance during frozen storage and consumption. Demand clusters around dessert cafes seeking visual differentiation through textural contrast.
- Confectionery Toppings:Surface gloss compounds from REACH-compliant coating agents satisfy ECHA audit requirements for European manufacturing.
- Beverage Garnishing:Rapid dissolution characteristics suit hot chocolate and coffee applications.
- Pastry Decoration:Uniform shell thickness from specialized enrobing technology enables premium artisan channel positioning.
Baked goods applications dominate volume capture; beverage garnishing exhibits steepest expansion trajectory.
Packaging Type:
Material specification and unit economics shape channel accessibility and sustainability positioning.
- Plastic Bottles:Polypropylene construction delivers moisture barrier performance for ambient storage. Supermarkets and specialty retailers in German-speaking markets favor this format for shelf visibility and resealability.
- Recyclable Pouches:Mono-material structures comply with EU packaging waste directives and EFSA contact material criteria. Food service providers are consolidating procurement around these formats fastest.
- Sachets:Single-serve portions suit food service portion control and sampling programs.
- Glass Jars:Premium positioning supports artisan bakery and gift market channels.
- Box Packs:Corrugated secondary packaging enables bulk logistics efficiency for industrial users.
Plastic bottles maintain volume leadership; recyclable pouches gain share fastest.
Customer Type:
Procurement scale and relationship architecture determine supplier engagement models.
- Artisan Bakers:Direct distribution relationships bypass wholesale layers to capture margin pools in German-speaking markets. These customers demand calibrated dosing consistency and specialized enrobing quality.
- Supermarkets:Private-label programs and SKU proliferation requirements fragment product portfolios without scale economies. BIS packaging standards in India and FDA labeling in the United States impose divergent compliance costs.
- Dessert Cafes:Premium decoration ingredient specifications prioritize visual differentiation and flavor layering.
- Food Service Providers:Volume contracts and logistics integration favor standardized packaging formats.
- Specialty Retailers:Curated assortment strategies support premium and novel product introductions.
Supermarkets anchor volume scale; artisan bakers drive margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate sprinkles production originated in European confectionery traditions before industrial scaling spread to North American and Asian markets. Manufacturing gravity now concentrates in specific national clusters where regulatory frameworks and ingredient supply chains intersect.
Germany
Artisan bakeries in the Rhine-Ruhr belt drive premium decoration ingredient procurement. EFSA purity criteria for vegetable fats enforce audited supply chain requirements. Cologne-centered confectionery clusters process calibrated dosing systems for industrial croissant and muffin lines.
United States
FDA labeling mandates shape cross-border formulation standards for chocolate products. Clean-label thresholds fragment product portfolios between domestic and export variants. Midwest industrial baking corridors source precision-engineered particulates for high-volume automated lines.
India
BIS packaging standards determine which exporters access domestic food service channels. Dessert cafe expansion in metropolitan centers accelerates decorative topping demand. Maharashtra and Gujarat host emerging toll-manufacturing partnerships for regional formulation compliance.
United Kingdom
EFSA-aligned post-Brexit food standards maintain REACH chemical restrictions on coating agents. London and Southeast England concentrate specialty retailer procurement for premium gift market channels. Direct bakery distribution models bypass traditional wholesale layers.
Netherlands
Randstad logistics infrastructure supports European distribution hub functions for confectionery ingredients. EU packaging waste directives drive mono-material recyclable pouch adoption. Food service providers consolidate procurement around sustainability-compliant formats fastest.
Global Chocolate Sprinkles Market Competitive Landscape
The competitive structure tilts toward specialized mid-cap processors with captive supply chain control. Incumbents leverage established refrigeration infrastructure to absorb F-Gas Regulation compliance costs that burden new entrants. Three archetypes dominate: vertically integrated cocoa processors, enrobing technology specialists, and artisan channel distributors. Capacity expansion and direct bakery relationship building constitute the primary competitive moves.
Among integrated processors, Carroll Industries exemplifies upstream control through captive cocoa butter refining. Twinkle Sprinkles occupies the technology-specialist position with enrobing system capabilities. Girrbach anchors the artisan distribution archetype through German-speaking market penetration. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Carroll Industries |
| Twinkle Sprinkles |
| Candy Manufacturer |
| Girrbach |
| CNS Confectionery |
| Mamy Sugarcraft |
| Sweets Indeed |
| Sprinkle Company |
| Cake Craft |
| Others |
Supply & Pricing Matrix
Specialized enrobing technology adoption across Western European artisan bakeries is compressing defect-rate differentials while simultaneously raising capital barriers for processors lacking real-time shell-thickness monitoring capabilities. This equipment convergence concentrates margin capture among incumbents with installed automation base, forcing mid-tier competitors toward toll-manufacturing arrangements or exit.
Pricing Analysis
Service-and-equipment bundling versus unbundled commodity supply splits the market into two distinct pricing architectures. Three-tier pricing structure across premium enrobed, standard extruded, and economy panning levels reflects technical specification divergence and dosing consistency requirements. Cost compression in economy tiers is intensifying because cocoa butter price volatility squeezes processors without captive refining. Industrial croissant and muffin lines exhibit lowest price sensitivity due to technical premium tolerance, while dessert cafes and specialty retailers face highest sensitivity to input cost pass-through.
Supply Chain Analysis
EFSA purity certification and REACH coating-agent compliance now gate supplier qualification for European manufacturing access, filtering small-scale processors from approved vendor lists. Germany, Belgium, and the Netherlands anchor production concentration around the Rhine-Ruhr belt and Randstad logistics corridor. Cocoa butter, plant-based fat systems from oat and coconut sources, and REACH-compliant surface gloss compounds constitute critical input dependencies. Single-source vulnerability clusters around Cologne-centered confectionery infrastructure exposed to regional logistics disruption. Distribution runs through direct bakery relationships in German-speaking markets and wholesale layers elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global chocolate sprinkles market functions as a regulatory compounder where EU F-Gas refrigeration mandates and escalating EFSA clean-label thresholds continuously requalify supplier rosters and concentrate demand among compliant incumbents.
For Market Incumbents: To counter refrigeration retrofit capex burdens on new entrants, prioritize capacity expansion in Rhine-Ruhr belt locations with installed low-impact cooling infrastructure. Deepen upstream control over cocoa butter refining to insulate margin predictability from input volatility. Direct bakery relationship building in German-speaking markets captures margin pools bypassing wholesale intermediaries.
For New Entrants and Emerging Players: BIS packaging standards compliance in India opens a window for exporters meeting local purity thresholds through toll-manufacturing partnerships in Maharashtra and Gujarat. Target dessert cafe expansion in Indian metropolitan centers as the most penetrable demand cluster. Pursue calibrated dosing consistency specialization for industrial baked goods lines where technical premiums displace commodity supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among small-scale European processors lacking REACH reformulation capabilities and facing ECHA audit pressure. Five-to-ten-year viability favors mid-cap specialists with captive supply chain control and installed enrobing automation. Watch for F-Gas Regulation enforcement acceleration as inflection indicator for incumbent advantage crystallization.
| Strategic Initiative | Industry Significance |
|---|---|
| Enrobing Technology Investment | Real-time shell-thickness monitoring compresses defect rates and qualifies premium artisan channel access. |
| Captive Cocoa Butter Refining | Upstream control insulates margin predictability from commodity price swings in global cocoa markets. |
| Direct Bakery Distribution Buildout | Relationship-based supply contracts in German-speaking markets bypass wholesale margin extraction. |
| REACH Compliance Reformulation | ECHA-aligned coating agent portfolios maintain European manufacturing access as audits tighten. |
| Indian Toll-Manufacturing Partnership | BIS standards compliance through Maharashtra and Gujarat partnerships unlocks underpenetrated food service channels. |
Research Methodology
Bottom-up baked goods and ice cream decoration demand modeling reconciled against top-down cocoa butter supply and confectionery processing capacity tracking forms the analytical core of this study. Primary interviews with artisan bakery owners, industrial croissant line procurement managers, enrobing equipment engineers, and EFSA regulatory affairs consultants combined with secondary validation from customs trade data, ECHA substance registration databases, BIS packaging standard filings, and EU F-Gas Regulation implementation reports. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical production volume and value trendlines across milk chocolate, vegan, dark, white, and ruby formulation categories established baseline growth patterns. Segmentation modeling spanned product type, application specificity, packaging format, and customer archetype across the projection horizon. CAGR derivation incorporated cocoa butter price elasticity, clean-label mandate adoption curves, and artisan bakery expansion rates in Western Europe and India. Enrobing technology penetration rates and F-Gas refrigeration retrofit timelines served as industry-specific forecast inputs.
Revisions become necessary when EFSA purity criteria enforcement accelerates, REACH chemical restrictions expand to additional coating agents, or cocoa supply disruptions materialize in West African origin regions. A model refresh is warranted upon material change in EU F-Gas Regulation compliance deadlines or BIS packaging standards implementation pace in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
CBD-Infused Confectionery Market
Confectionery
Middle East Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Real and Compound Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
Sugar Confectionery Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Green Tea Chocolate Market
Confectionery
Ruby Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Confectionery Fillings Market