
 Real and Compound Chocolate Market | 2026-2036
Real and Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Real and Compound Chocolate Market Intelligence
Cocoa butter alternatives derived from shea and palm fractions is repositioning cost structures across industrial chocolate formulations. Barry Callebaut AG leverages its integrated bean-to-bar infrastructure to secure supply continuity for premium couverture lines. Cargill Incorporated anchors North American industrial demand through its broad compound chocolate portfolio. Nestlé S.A. differentiates via proprietary chocolate flavor systems that command preferential placement in retail confectionery.
Real and compound chocolate encompasses cocoa-derived and cocoa-equivalent fat systems formulated for confectionery, baking, and coating applications, with compound variants substituting cocoa butter with vegetable fats to achieve specific melting profiles and cost targets. The category serves industrial food manufacturers, artisan bakeries, and retail confectioners requiring controlled viscosity, snap, and bloom resistance in finished goods. Real chocolate and couverture segments retain the highest margin pools due to cocoa butter content and premium positioning, while compound chocolate and chips forms capture volume leadership in mass-market bakery and coating applications. Distribution through specialty stores and online channels is expanding as artisan producers and small-batch buyers seek direct sourcing relationships.
FDA standards of identity in the United States and EFSA labeling requirements under the EU Green Deal shape product formulation decisions and cross-border market access for chocolate manufacturers. BIS quality benchmarks in India and FSSAI food safety protocols further define import and domestic production standards across major consumption centers. Stakeholders must monitor evolving deforestation regulations and fat-origin disclosure mandates to anticipate reformulation costs and sourcing realignments.
Market Dynamics
The EU Green Deal's deforestation-free sourcing mandates are forcing cocoa supply chains toward traceability investments and fat-origin disclosure systems, compressing margins for non-compliant suppliers while rewarding integrated bean-to-bar operators.
Growth Catalysts
- EU Green Deal traceability mandates:Deforestation-free certification requirements are accelerating investments in supply chain transparency platforms and farm-level monitoring systems across West African sourcing corridors.
- India food processing expansion:Domestic chocolate ingredient consumption is scaling as bakery and confectionery manufacturing clusters multiply in Maharashtra and Gujarat.
- Shea butter fractionation advances:Improved enzymatic interesterification processes are expanding cocoa butter equivalent functionality in temperate-climate coating applications.
Market Restraints
- Cocoa butter price volatility:Constrained grindings in Côte d'Ivoire and Ghana are amplifying input cost swings for premium couverture formulations.
- West African supply concentration:Over 60% of global cocoa bean output originates from two countries, creating geographic risk exposure for chocolate manufacturers.
- Technical bloom limitations:Compound chocolate's fat polymorphism constraints restrict shelf-life performance in ambient-temperature retail environments.
Strategic Opportunities
- India domestic ingredient demand:Underdeveloped per-capita chocolate consumption relative to Southeast Asian benchmarks signals volume expansion potential for compound coating suppliers.
- Clean-label coating systems:Regulatory tailwinds from FDA and EFSA disclosure requirements are opening formulation windows for palm-free and shea-forward compound alternatives.
- Direct-to-artist distribution:Specialty e-commerce platforms are disintermediating traditional ingredient distributors for small-batch chocolatiers and boutique bakeries.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in cocoa butter equivalent flavor masking and mouthfeel engineering remains concentrated among legacy European suppliers.
- Retrofitting capex burdens:Existing compound lines require substantial modification to process next-generation shea-palm fat blends with precise melting profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real and Compound Chocolate Market |
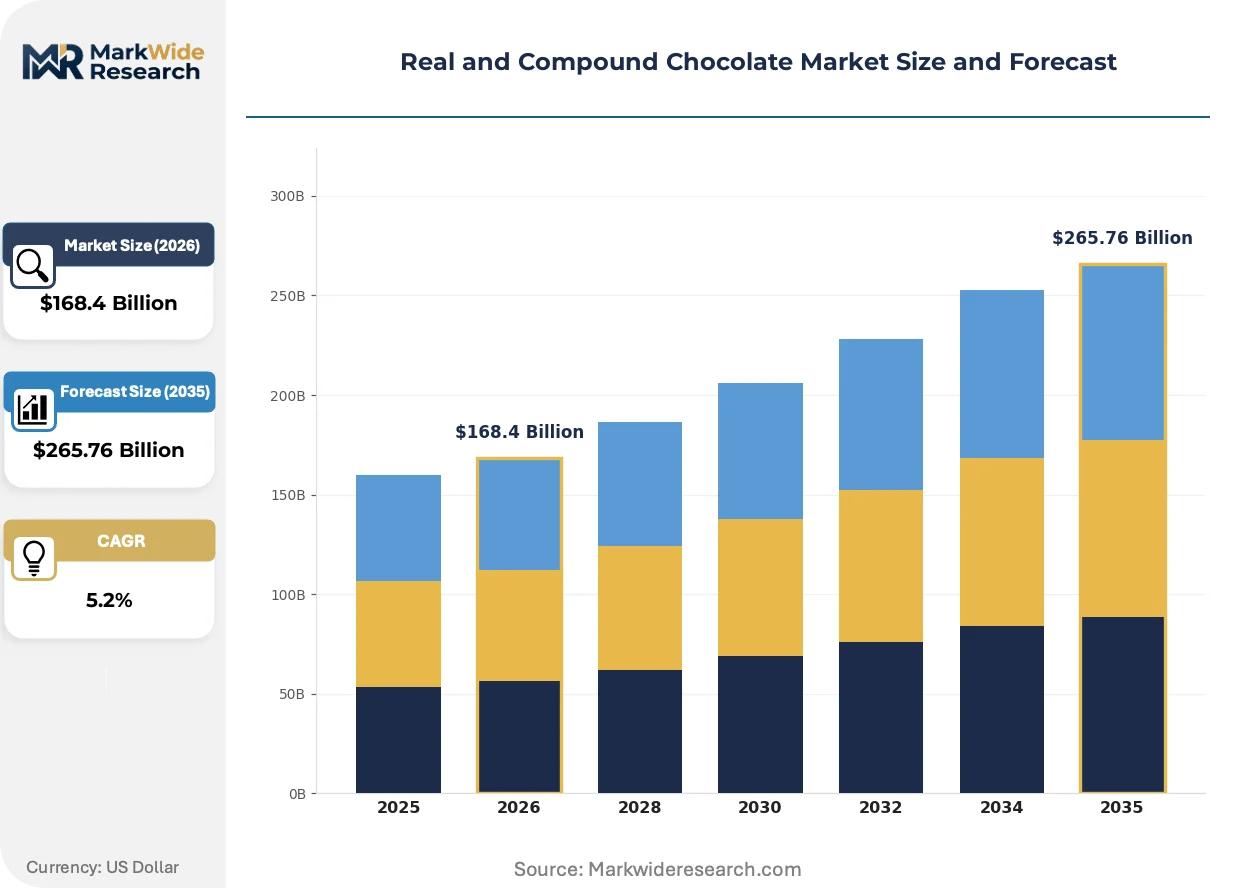
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $265.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real Chocolate, Compound Chocolate, Couverture, Baking Chocolate Form: Bar, Chips, Powder, Blocks Application: Confectionery, Baking, Dessert, Coating Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Barry Callebaut AG, Cargill Incorporated, Mars Incorporated, Puratos Group, Fuji Oil Company Limited, Mondelez International, Nestlé S.A., Ferrero Group, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real and Compound Chocolate Market Strategic Shifts & Innovations
Formulation science and procurement transparency are converging to reshape competitive advantage in chocolate ingredient supply, with sustainability verification and functional fat chemistry emerging as primary differentiation vectors.
Precision fermentation-derived cocoa butter equivalents are overtaking conventional shea interesterification in premium compound formulations. Artisan chocolatiers in Switzerland and Belgium are piloting these lipids for couverture applications demanding precise snap and gloss retention. The technology is compressing the performance gap between compound and real chocolate in temperate-climate distribution.
REACH chemical disclosure expansions and EFSA fat-origin labeling requirements are mandating granular supply chain documentation across EU import channels. Industrial chocolate manufacturers must now map shea nut provenance to specific cooperative aggregators in Burkina Faso and Mali. Couverture and compound coating segments serving EU retail private-label accounts face the steepest compliance cost escalations.
Direct sourcing contracts between artisan bakeries and specialty compound suppliers are displacing traditional foodservice distribution tiers. Small-batch buyers in urban clusters across Germany, France, and the Netherlands are negotiating volume commitments with regional chocolate ingredient specialists. This channel disintermediation is most pronounced in metropolitan confectionery corridors where traceability storytelling commands shelf price premiums.
Real and Compound Chocolate Market Segmentation
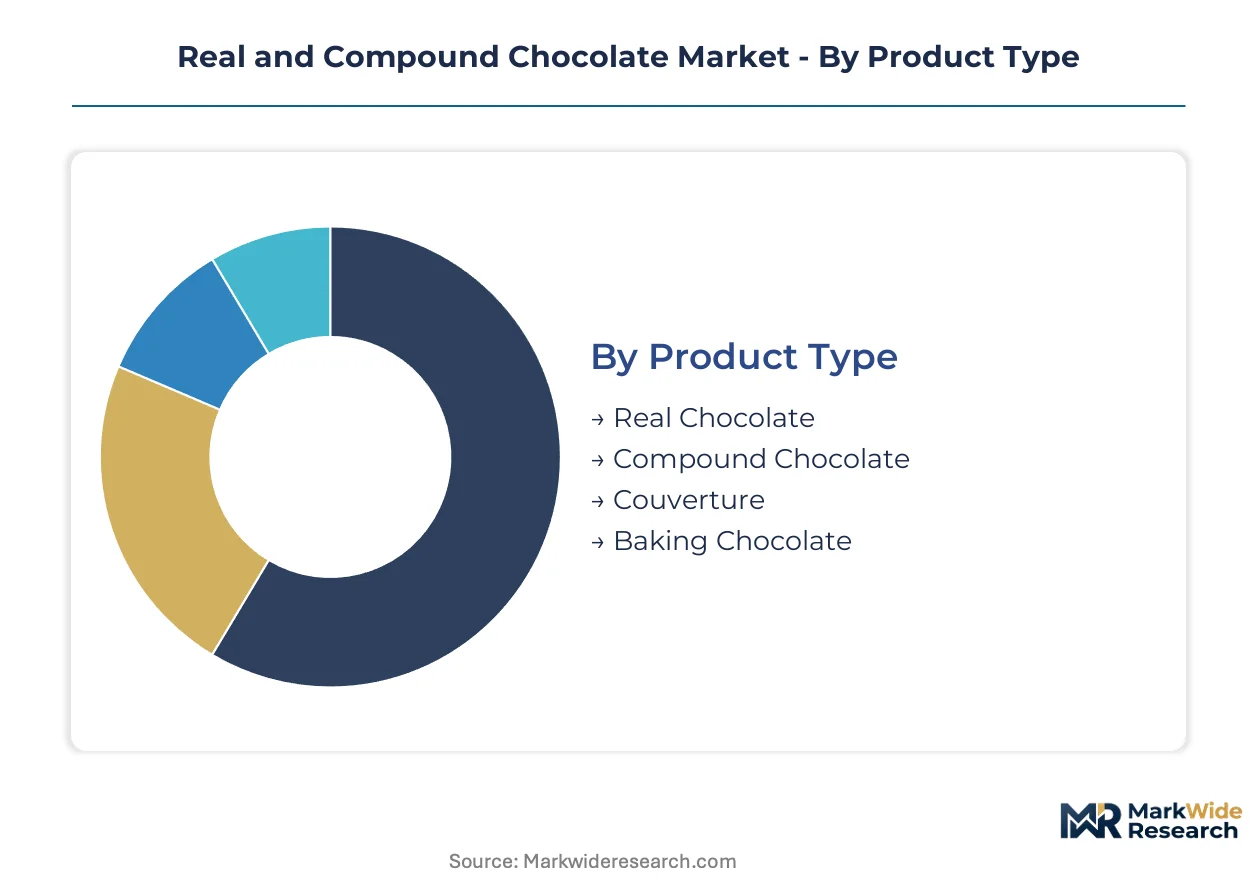
Segmentation in real and compound chocolate markets reveals how fat chemistry, physical form, and channel economics partition value capture. Manufacturers configure production assets around specific melting profiles and viscosity specifications that align with end-use processing requirements.
Product Type:
Supply concentration in West African cocoa grindings disproportionately shapes cost structures across product tiers, with butter content determining margin exposure to bean price volatility.
- Real Chocolate:Cocoa butter-based formulations with minimum cocoa solid thresholds defined by FDA and EFSA standards of identity. European artisan confectioners in Belgium and Switzerland anchor premium demand, though EU Green Deal traceability mandates are elevating compliance costs for couverture applications.
- Compound Chocolate:Vegetable fat systems substituting cocoa butter with shea or palm fractions to achieve targeted melting points and cost positions. Industrial bakery manufacturers in India and Germany drive volume absorption, with Maharashtra processing clusters scaling domestic compound consumption for coating applications.
- Couverture:High-cocoa butter content (>31%) delivering superior snap and gloss for tempering applications. French and Belgian chocolatiers maintain formulation leadership despite input cost pressures.
- Baking Chocolate:Unsweetened or low-sugar blocks formulated for high-heat stability in industrial oven environments. North American commercial bakeries represent the core demand concentration.
Compound chocolate absorbs the bulk of installed capacity; real chocolate is expanding most quickly as premium positioning justifies butter cost exposure.
Form:
Physical configuration dictates processing equipment compatibility and melting control precision across manufacturing scales.
- Bar:Standardized ingots for artisan tempering and small-batch confectionery. Specialty stores in urban German and Dutch clusters are disintermediating traditional distribution for direct bar sourcing.
- Chips:Drop-form stabilized morsels engineered for heat resistance in cookie and muffin applications. Mass-market bakery manufacturers in India and the United States represent the dominant consumption base.
- Powder:De-fatted or full-fat cocoa preparations for beverage and dry-mix integration. Industrial foodservice channels concentrate demand for beverage fountain systems.
- Blocks:Large-format industrial inputs requiring mechanical breaking before melting. Commercial confectionery operations in Côte d'Ivoire and Ghana grinding facilities favor block formats for efficiency.
Chips command the greatest production volume; powder is climbing the fastest as functional beverage applications multiply.
Application:
End-use thermal processing requirements determine fat polymorphism specifications and shelf-life engineering priorities.
- Confectionery:Tempered shells, ganaches, and pralines demanding precise snap and gloss retention. Swiss and Belgian artisan producers maintain technical leadership despite shea butter equivalent encroachment.
- Baking:Heat-stable inclusions and coatings surviving oven temperatures above 180°C. Industrial manufacturers in Gujarat and Maharashtra are scaling compound chip consumption for biscuit and bread applications.
- Dessert:Mousse, sauce, and frozen preparations requiring rapid melt and clean flavor release. French patisserie channels concentrate premium demand.
- Coating:Enrobing and dipping applications where fat bloom resistance determines retail shelf acceptance. Ambient-temperature distribution in Indian retail environments favors compound coating formulations.
Coating applications absorb the bulk of installed capacity; baking is gaining share fastest as processed food manufacturing expands in South Asia.
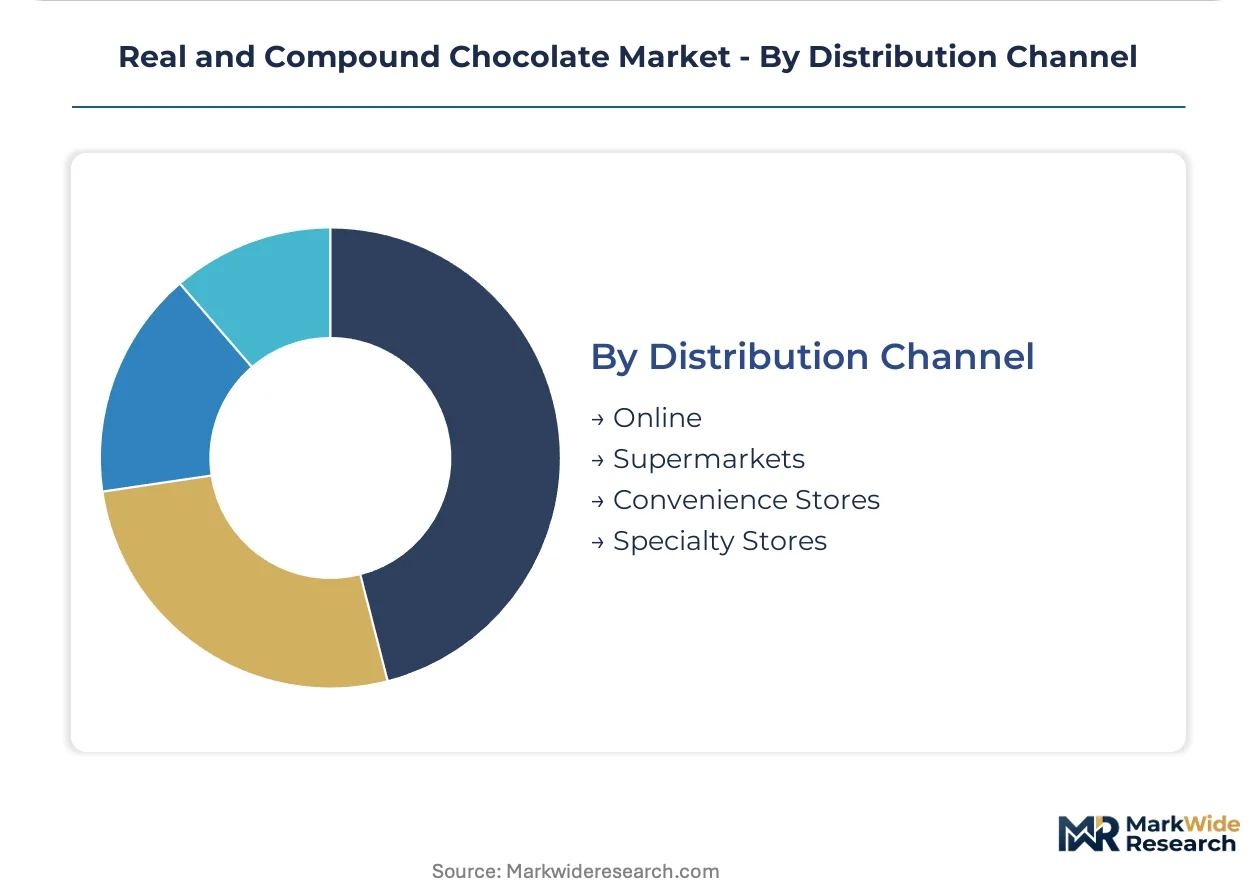
Distribution Channel:
Channel selection determines traceability documentation depth and minimum viable order economics for supplier relationships.
- Online:Direct-to-artist platforms enabling small-batch procurement with provenance storytelling. Urban confectionery corridors in Amsterdam, Berlin, and Paris are shifting volume toward specialty e-commerce.
- Supermarkets:Mass-market retail private-label sourcing with consolidated volume and price compression. REACH and EFSA disclosure requirements are elevating compliance costs for EU supermarket suppliers.
- Convenience Stores:Impulse confectionery and snack baking segments with limited shelf-space competition. Indian urban convenience formats are scaling chocolate ingredient trial packs.
- Specialty Stores:Professional ingredient suppliers serving artisan chocolatiers and boutique bakeries with technical consultation. German and French metropolitan clusters concentrate specialty channel density.
Supermarkets absorb the bulk of installed capacity; online channels are expanding most quickly as disintermediation accelerates in European artisan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra have concentrated Indian chocolate ingredient manufacturing, drawing compound coating suppliers toward duty-advantaged processing hubs. These zones anchor South Asian expansion while EU traceability mandates reshape European sourcing patterns.
United States
Industrial bakery manufacturers in the Midwest drive compound chip absorption for cookie and bread applications. FDA standards of identity govern cocoa solid thresholds across interstate commerce. Chicago and Minneapolis processing corridors concentrate North American chocolate ingredient distribution infrastructure.
Germany
Artisan chocolatiers in Cologne and Hamburg sustain premium couverture demand despite input cost pressures. REACH chemical disclosure expansions mandate granular fat-origin documentation for EU import channels. The Ruhr industrial basin hosts major compound chocolate grinding and formulation facilities.
India
Maharashtra and Gujarat food processing clusters scale domestic compound consumption for biscuit coating and confectionery applications. FSSAI food safety protocols define import and domestic production standards for chocolate ingredients. Mumbai-Pune manufacturing corridors attract multinational ingredient suppliers establishing regional blending operations.
Belgium
Artisan praline producers in Brussels and Liège maintain technical leadership in tempered shell applications. EU Green Deal deforestation-free certification requirements accelerate farm-level monitoring investments across West African sourcing corridors. The Port of Antwerp anchors European cocoa bean import and processing logistics.
Brazil
Confectionery manufacturers in São Paulo state drive compound chocolate absorption for tropical-climate distribution. ANVISA labeling requirements shape product formulation decisions for domestic retail placement. The Campinas industrial district concentrates South American chocolate ingredient processing capacity.
Real and Compound Chocolate Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated bean-to-bar operators commanding premium couverture positioning while toll processors capture volume in industrial compound formulations. Market structure tilts toward consolidation at the top tier, where five operators control the majority of cocoa grinding capacity, while mid-tier specialists fragment across regional bakery supply. Three archetypes dominate: vertically integrated cocoa processors, specialty fat chemistry houses, and artisan-facing ingredient distributors. Competitive moves center on traceability platform investments and enzymatic interesterification licensing to secure next-generation coating formulations.
Among Swiss and Belgian integrated processors, Barry Callebaut AG and Cargill Incorporated exemplify the bean-to-bar archetype with captive West African sourcing infrastructure. Fuji Oil Company Limited occupies a position within the Asian fat chemistry specialist tier, representing palm and shea fractionation capabilities that serve temperate-climate coating applications. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in ingredient supply.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill Incorporated |
| Mars Incorporated |
| Puratos Group |
| Fuji Oil Company Limited |
| Mondelez International |
| Nestlé S.A. |
| Ferrero Group |
| The Hershey Company |
| Others |
Cost & Logistics Intelligence
EU Green Deal deforestation-free certification requirements gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant traders while rewarding integrated bean-to-bar operators with preferential placement in EU retail channels.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, while spot inventory commands discounts due to quality uncertainty and limited traceability documentation. Three-tier pricing structure across premium, standard, and economy levels reflects cocoa butter content, certification grade, and provenance granularity. Pricing pressure stems from cocoa butter volatility in Côte d'Ivoire and Ghana grindings, compressing margins for couverture specialists. Industrial bakery manufacturers in India exhibit highest price sensitivity, while Swiss and Belgian artisan chocolatiers prioritize quality grade over cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from EU retail private-label buyers require chocolate manufacturers to maintain approved supplier rosters across Côte d'Ivoire, Ghana, and Ecuador origins. Raw material dependencies center on cocoa beans, shea nuts from Burkina Faso and Mali, and palm oil fractions from Southeast Asian processing hubs. Single-source vulnerability in West African bean supply creates geographic risk exposure amplified by climate variability. Distribution runs through Antwerp and Hamburg port complexes for European industrial buyers, with Mumbai-Pune corridors serving South Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around traceability-capable operators, with EU Green Deal compliance costs forcing sub-scale compound chocolate toll processors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into West African farm-level monitoring systems to secure deforestation-free certification pipelines. Acquire enzymatic interesterification capabilities from Asian fat chemistry specialists to control next-generation coating formulation costs. Prioritize captive supply of shea fractions from Burkina Faso cooperative networks to offset palm oil price volatility.
For New Entrants and Emerging Players: Precision fermentation-derived cocoa butter equivalents offer a technology-first wedge into premium compound formulations for temperate-climate distribution. Target underdeveloped per-capita consumption in Indian secondary cities where domestic food processing clusters lack technical formulation support. Deploy direct-to-artist e-commerce platforms with provenance storytelling to disintermediate traditional specialty distributors in German and Dutch urban corridors.
For Investors and Strategic Acquirers: First-mover announcements of farm-level blockchain traceability deployments are the leading indicator that margin compression has peaked for integrated operators. Mid-tier compound chocolate toll processors with Maharashtra or Gujarat facility footprints represent acquisition targets for multinational ingredient suppliers seeking South Asian manufacturing scale. Watch for regulatory enforcement actions by EFSA on fat-origin labeling as the inflection signal for compliance-cost driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Farm-Level Traceability Platform Deployment | EU Green Deal compliance secures retail channel access for premium couverture lines. |
| Enzymatic Interesterification Licensing | Shea butter fractionation advances unlock temperate-climate coating performance parity. |
| Direct-to-Artist E-Commerce Launch | Specialty channel disintermediation captures margin from urban artisan chocolatiers. |
| Maharashtra Blending Facility Expansion | Domestic Indian compound production reduces import duty exposure for biscuit coatings. |
| Precision Fermentation Partnership | Biotech-derived cocoa butter equivalents compress real-compound performance gaps. |
Research Approach
Multi-period observation of cocoa butter price spreads, EU import certification volumes, and Indian food processing capacity utilization anchored the trend analysis, supplemented by interviews with cocoa procurement directors, compound chocolate plant managers, artisan chocolatier founders, FSSAI regulatory affairs leads, and specialty ingredient distributors. Secondary validation drew from customs trade data, FDA standards of identity filings, EFSA disclosure requirement updates, and BIS quality benchmark publications. Bottom-up facility capacity estimates triangulated against top-down consumption modeling across bakery, confectionery, and coating applications.
Segment-weighting applied product type, physical form, end-use application, and distribution channel dimensions across the projection horizon. CAGRs derived from elasticity-adjusted volume projections against price trajectory assumptions. Industry-specific forecast inputs incorporated shea butter fractionation yield improvements and precision fermentation commercialization timelines for cocoa butter equivalent production.
Several conditions sit outside the modeled scope, including geopolitical disruption in West African sourcing corridors, abrupt REACH chemical disclosure expansions, and cocoa bean disease outbreaks. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption curves. Deviation in EU Green Deal audit frequency or Indian PLI scheme expansion for food processing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Premium Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Low-Calorie Candy Market
Confectionery
Confectionery Fillings Market
Confectionery
Black Treacle Market
Confectionery
Global Confectionery Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Brazil Chocolate Market
Confectionery
Caramel Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Gum Base Candy Market
Confectionery
Buttercream Frosting Market
Confectionery
UK Compound Chocolate Market
Confectionery
Global Candy Market
Confectionery
Japan Chocolate Market
Confectionery
Europe Dark Chocolate Market