
 Salted Caramel Products Market | 2026-2036
Salted Caramel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Salted Caramel Products Market Analytics
The premium confectionery tier is repositioning salted caramel as a craft-origin ingredient with provenance stories, while commodity producers compete on bulk sauce and candy volume. Ferrero Group leverages its hazelnut-caramel pairing expertise to sustain premium positioning across European retail. Mondelez International anchors North American mass-market distribution through familiar candy formats. Nestlé S.A. competes in the beverage infusion segment with salted caramel coffee creamers and ready-to-drink lines.
Salted caramel products combine heated sugar with dairy fat and sodium chloride to create a Maillard-reaction flavor profile, typically manufactured through controlled batch caramelization at 170–190°C for confectionery applications or continuous processing for industrial sauce volumes. The primary commercial purpose spans finished confectionery, beverage flavoring, and ingredient supply to bakery and dessert manufacturers. Chocolate and sauce categories dominate value capture due to higher per-unit premiums and repeat purchase frequency, while snack applications represent the fastest-growing segment as savory-sweet flavor profiles expand into popcorn and nut coatings. Food manufacturers as a customer type concentrate procurement volume, though specialty stores as a channel retain margin advantages through curated artisan selections.
The FDA governs caramel color additive specifications and labeling under 21 CFR 73.85, while the EU's EFSA sets maximum acrylamide thresholds that constrain high-temperature caramelization processes for products entering European markets. BIS in India enforces FSSAI-aligned standards for imported confectionery that require reformulation of certain caramel variants for local compliance. Stakeholders must monitor evolving clean-label demands against the technical necessity of processed caramel inputs, as regulatory divergence between jurisdictions reshapes formulation strategies and sourcing decisions without harmonized international standards.
Market Dynamics
The salted caramel market pivots on tightening clean-label mandates that clash with technical necessities of Maillard-reaction processing, forcing reformulation investments across European and North American supply chains.
Growth Catalysts
- Artisan bakery expansion:Specialty chains in France and Belgium are building salted caramel into signature flavor platforms, driving ingredient procurement volume for craft caramel suppliers.
- F-Gas Regulation compliance:The EU's tightened additive disclosure rules are advantaging domestic European producers with established REACH documentation over import-dependent competitors.
- Savory-sweet flavor convergence:Snack manufacturers are deploying salted caramel coatings on popcorn and nut clusters, opening new volume channels beyond traditional confectionery.
Market Restraints
- Dairy input cost volatility:Butter and cream price swings compress margins for batch-caramel producers dependent on fresh dairy rather than powdered alternatives.
- Acrylamide threshold constraints:EFSA maximum limits on high-temperature caramelization force process modifications that lengthen production cycles for European-bound products.
- Clean-label substitution pressure:Consumer preference for "natural" positioning threatens standard caramel color additives governed by 21 CFR 73.85.
Strategic Opportunities
- Beverage infusion white space:Ready-to-drink coffee and functional beverage categories in Germany and the UK show underpenetrated salted caramel positioning versus established chocolate and sauce segments.
- Indian market entry pathway:BIS-aligned FSSAI standards for imported confectionery create first-mover advantages for reformulation-capable exporters establishing local compliance.
- Direct-to-consumer channel emergence:Subscription dessert boxes and curated online marketplaces enable artisan producers to bypass conventional retail margin structures.
Industry Challenges
- Maillard reaction expertise scarcity:Batch caramelization at 170–190°C demands skilled temperature control that industrial food science programs inadequately cultivate.
- Dual jurisdiction compliance costs:Simultaneous FDA and REACH documentation requirements strain mid-tier producers without dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salted Caramel Products Market |
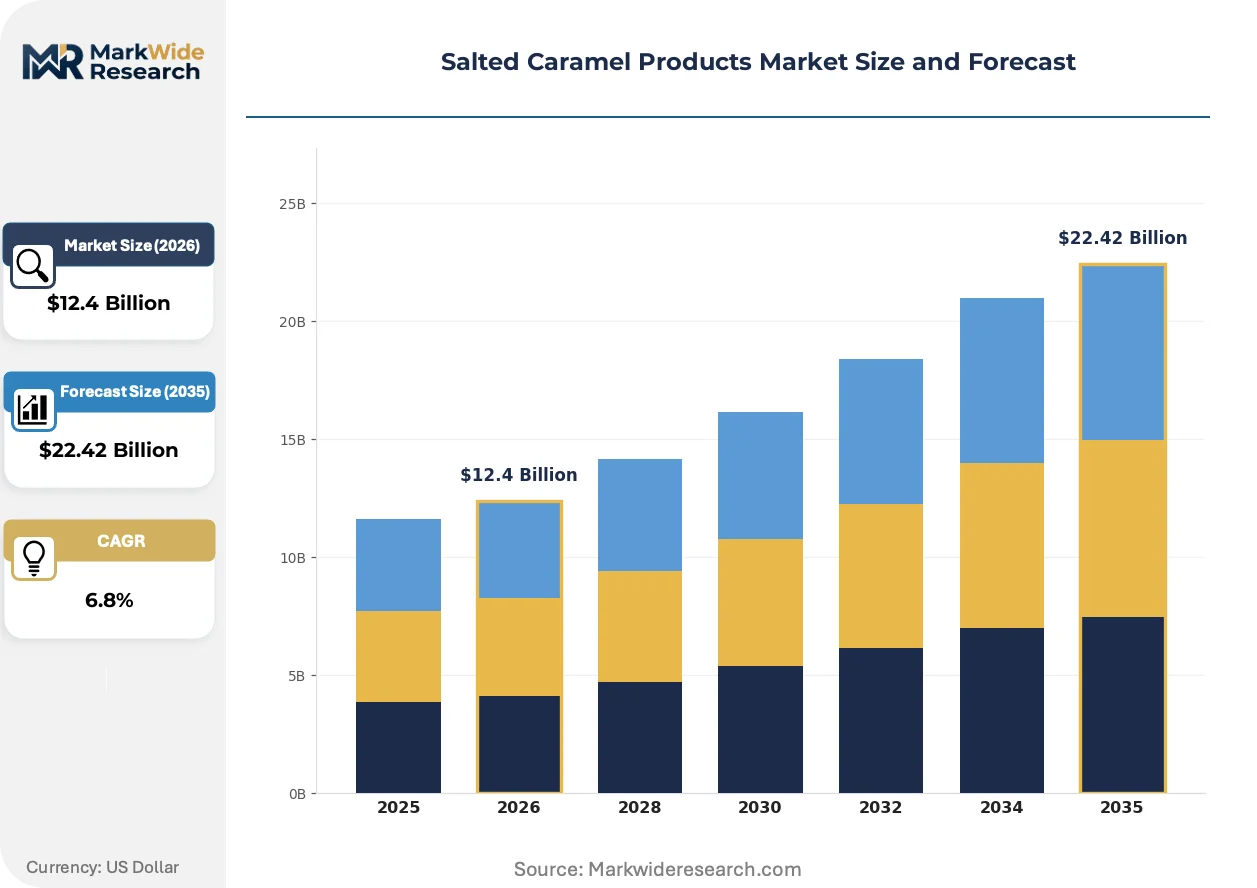
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Candy, Sauce, Snack Application: Baking, Confectionery, Beverage, Dessert Customer Type: Retail Consumers, Wholesale Buyers, Food Manufacturers, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ferrero Group, Cargill Incorporated, Mondelez International, Sensient Technologies Corporation, Kerry Group plc, Mars Incorporated, Nestlé S.A., Lindt & Sprüngli, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salted Caramel Products Market Evolving Landscape
Continuous processing systems and precision thermal controls are displacing traditional batch methods, while regulatory divergence between jurisdictions reshapes competitive positioning across premium and commodity tiers.
Thermal profiling sensors paired with AI-driven process control is automating caramelization consistency in industrial sauce production. Large-scale confectionery manufacturers in Germany and the Netherlands are deploying these systems to reduce batch-to-batch variation. This automation is compressing quality differentiation between mid-tier and premium producers.
REACH registration requirements for caramel color additives are tightening disclosure obligations for non-EU suppliers seeking European market access. The regulation now demands granular supply chain documentation that many import-reliant brands cannot satisfy. Chocolate and sauce categories face the steepest compliance investments given their higher European export exposure.
Curated online marketplaces and direct subscription channels are capturing growing share of premium salted caramel purchases from specialty food buyers. Traditional wholesale distribution through food service intermediaries is losing ground to platform-enabled producer-consumer connections. This shift concentrates in France and Belgium where artisan provenance narratives resonate strongest with digitally native consumers.
Salted Caramel Products Market Segmentation
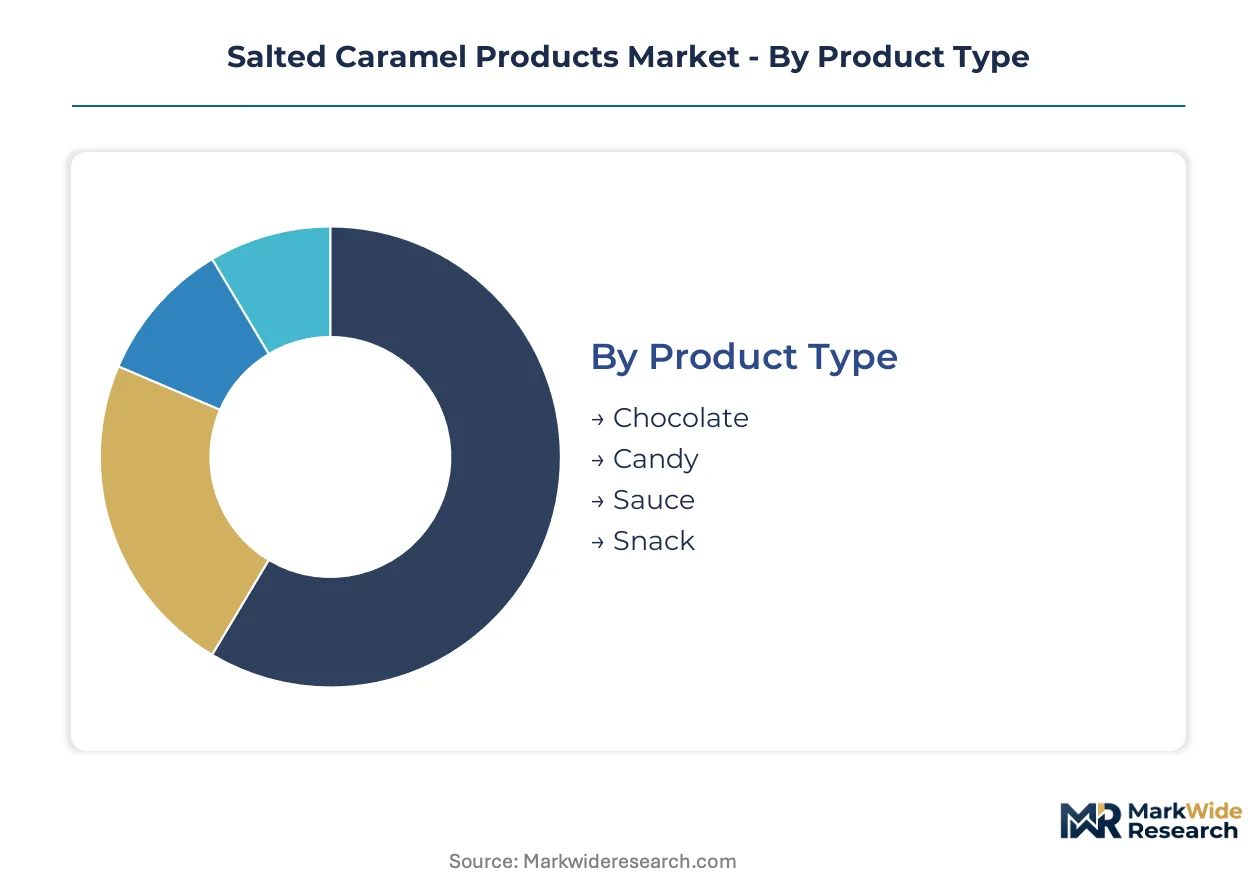
Salted caramel's versatility across finished goods and ingredient supply creates distinct competitive arenas with divergent margin structures and technical requirements. Understanding how demand fragments across product formats, use cases, and procurement relationships reveals where value capture concentrates versus where volume commoditization accelerates.
Product Type:
Standalone finished goods compete with embedded ingredient formats for shelf space and formulation budgets, with integration depth determining pricing power and repeat purchase mechanics.
- Chocolate:Enrobed bars and pralines combine salted caramel filling with cocoa butter matrices at 45-55% cacao content for premium positioning. French and Belgian chocolate houses concentrate procurement of craft caramel couverture, though EFSA acrylamide thresholds constrain high-temperature caramelization methods for European export compliance.
- Sauce:Pumpable formulations at 65-75% solids content serve both food service drizzle applications and home dessert finishing. Industrial continuous processing lines in Germany and the Netherlands supply private-label volumes to supermarket chains, while batch methods persist for specialty retail positioning.
- Candy:Chew and hard candy formats deliver shelf-stable portability through controlled moisture content below 5%. Mass-market distribution through North American convenience channels dominates volume.
- Snack:Popcorn and nut cluster coatings exploit savory-sweet convergence with fat-based adhesion systems. Rapid flavor fatigue cycles in this segment compress product development timelines.
Chocolate leads volumes today; snack coatings are gaining share fastest.
Application:
Cost tier stratification separates artisan craft positioning from industrial ingredient supply, with formulation complexity and thermal stability requirements determining margin capture.
- Confectionery:Finished candy and chocolate applications demand precise water activity control below 0.6 for shelf stability. Ferrero Group and Mondelez International anchor European and North American procurement respectively.
- Beverage:Coffee creamers and ready-to-drink formats require emulsion stability across pH ranges from 4.5 to 7.0. Nestlé S.A. has established early positioning in this underpenetrated category.
- Baking:Fillings and toppings for artisan bakery chains require pumpable viscosity at ambient temperatures. French specialty chains drive ingredient specification trends.
- Dessert:Ice cream variegates and plated dessert components compete on flavor impact concentration. Food service intermediaries dominate procurement volume.
Confectionery commands premium pricing; beverage applications show steepest expansion trajectory.
Customer Type:
Procurement scale and technical specification intensity separate mass-market volume buyers from curated artisan relationships with divergent service requirements.
- Food Manufacturers:Industrial buyers specify caramel with defined color units and viscosity ranges for automated production lines. REACH documentation requirements advantage domestic European suppliers over import-dependent competitors.
- Retail Consumers:Individual purchasers respond to provenance narratives and clean-label positioning in specialty and premium supermarket channels.
- Restaurants:Food service operators prioritize portion control formats and consistent flavor delivery across kitchen environments.
- Wholesale Buyers:Distributor intermediaries aggregate fragmented artisan production for institutional and hospitality procurement.
Food manufacturers concentrate procurement volume; retail direct channels are climbing the fastest.
Distribution Channel:
Geographic reach and margin retention trade off across platform-enabled direct sales versus conventional retail intermediaries with established foot traffic.
- Supermarkets:Mass-market retail chains in France, Germany, and the UK drive private-label volume and national brand placement fees.
- Specialty Stores:Curated confectionery retailers in Belgium and Paris retain margin advantages through artisan provenance narratives and limited distribution exclusives.
- Online Retail:Platform marketplaces and subscription dessert boxes enable producer-direct relationships bypassing wholesale margin structures.
- Direct Sales:Producer-owned retail and food service contracts capture full value chain economics for established craft brands.
Supermarkets anchor volume today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan caramel craftsmen in France and Belgium anchor European supply chains for premium confectionery, while industrial scale operations concentrate in Germany and the Netherlands for mass-market sauce production.
France
Traditional caramel craft methods in Brittany and Normandy supply premium chocolate houses with batch-processed couverture. The ANSM enforces strict additive disclosure under EU REACH alignment for imported confectionery. Paris-based specialty retailers curate artisan provenance narratives that command margin premiums through limited distribution exclusives.
Germany
Industrial continuous processing lines in North Rhine-Westphalia pump private-label sauce volumes to supermarket chains across Central Europe. The F-Gas Regulation demands granular supply chain documentation that advantages domestic producers with established ECHA registrations. Cologne and Düsseldorf clusters deploy AI-driven thermal profiling to reduce batch-to-batch variation in caramelization consistency.
United States
Mass-market candy distribution through North American convenience channels concentrates procurement volume for shelf-stable chew and hard candy formats. The FDA governs caramel color specifications under 21 CFR 73.85 with clean-label substitution pressure mounting. Chicago and Pennsylvania manufacturing hubs serve Mondelez International and The Hershey Company with automated production lines.
Belgium
Praline and enrobed bar production in Brussels and Liège combines salted caramel filling with cocoa butter matrices at premium cacao content tiers. EFSA acrylamide thresholds constrain high-temperature caramelization methods for European export compliance. Specialty retailers in Antwerp and Ghent retain margin advantages through curated artisan selections and direct-to-consumer platform relationships.
India
Reformulation-capable exporters target first-mover positioning as BIS-aligned FSSAI standards tighten for imported confectionery. The FSSAI requires specific caramel variant adjustments for local compliance that strain mid-tier producers without dedicated regulatory capacity. Maharashtra and Gujarat industrial corridors attract ingredient suppliers establishing regional manufacturing footprints.
Salted Caramel Products Market Competitive Landscape
Top-tier vendors anchor premium confectionery through craft-origin positioning, while commodity producers compete on bulk sauce and candy volume. Mid-tier players without dedicated regulatory affairs capacity strain under simultaneous FDA and REACH documentation requirements. Three strategic archetypes dominate: heritage chocolate houses with caramel expertise, diversified food conglomerates with beverage infusion capabilities, and industrial ingredient suppliers with continuous processing scale. Competitive moves concentrate on portfolio diversification into adjacent snack coatings and strategic partnerships for clean-label reformulation.
Within the heritage confectionery tier, Ferrero Group and Lindt & Sprüngli exemplify craft-origin positioning through provenance narratives and premium cacao-caramel pairings. Nestlé S.A. occupies a distinct position in beverage infusion with ready-to-drink coffee applications. Mondelez International anchors mass-market distribution through familiar North American candy formats. Kerry Group plc and Sensient Technologies Corporation represent the industrial ingredient supply archetype with formulation capabilities for private-label and food service channels.
| Leading Market Players |
|---|
| Ferrero Group |
| Cargill Incorporated |
| Mondelez International |
| Sensient Technologies Corporation |
| Kerry Group plc |
| Mars Incorporated |
| Nestlé S.A. |
| Lindt & Sprüngli |
| The Hershey Company |
| Others |
Value Network & Pricing Analysis
Butter and cream input costs transmit directly from Normandy and Brittany dairy cooperatives through batch-caramel producers to Paris specialty retailers, compressing margins at the craft tier while industrial sauce manufacturers in Germany absorb volatility through powdered dairy substitution and long-term offtake contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates premium chocolate houses purchasing provenance-documented caramel couverture with technical support from commodity buyers sourcing pumpable sauce on spot terms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU REACH alignment and volume scale. Pricing pressure stems from clean-label reformulation investments forced by EFSA acrylamide thresholds. Mass-market candy buyers exhibit highest price sensitivity, while French artisan retailers retain lowest sensitivity due to provenance narrative premiums.
Supply Chain Analysis
Fresh dairy supply rests on French and Belgian agricultural cooperatives, Madagascar vanilla bean imports, and German industrial glucose refineries. Caramel color additives, butterfat concentrates, and sea salt constitute critical formulation inputs. Single-source vulnerability concentrates in Breton artisan producers lacking diversified dairy procurement. Distribution runs through supermarket private-label aggregators in Germany, specialty confectionery retailers in Paris and Brussels, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The salted caramel market functions as a stable compounder anchored by repeat-purchase confectionery mechanics and flavor platform permanence in artisan bakery expansion.
For Market Incumbents: Cement craft-origin positioning through exclusive Brittany and Normandy dairy cooperative contracts that block competitor access to provenance-narrative inputs. Invest in REACH documentation capacity to exploit F-Gas Regulation compliance advantages over import-dependent rivals facing disclosure gaps. Threat: Mid-tier producers with dual FDA-REACH regulatory affairs capacity erode margin differentiation. For New Entrants and Emerging Players: Begin with beverage infusion white space in German and UK ready-to-drink coffee categories where salted caramel penetration lags chocolate and sauce saturation. Target direct-to-consumer subscription dessert boxes bypassing wholesale margin structures. Go-to-market angle: AI-driven thermal profiling partnerships with Dutch continuous processing equipment suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier producers strain under simultaneous FDA and REACH documentation requirements without dedicated regulatory capacity. Long-term viability favors heritage chocolate houses with captive caramel expertise and diversified food conglomerates with beverage infusion platforms. Acquisition target: Reformulation-capable exporters with established BIS-aligned FSSAI compliance for Indian market entry. Signal to watch: EFSA acrylamide threshold enforcement intensity affecting European export viability for high-temperature batch producers.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA acrylamide compliance secures European market access against import-dependent competitors. |
| Direct-to-Consumer Channel Launch | Subscription dessert boxes bypass wholesale margins in France and Belgium. |
| Backward Integration into Dairy Supply | Exclusive Breton cooperative contracts lock provenance narratives for premium positioning. |
| Beverage Infusion Platform Expansion | Ready-to-drink coffee applications exploit underpenetrated German and UK markets. |
| AI-Driven Thermal Profiling Deployment | Automation reduces batch-to-batch variation for industrial sauce scale in the Netherlands. |
Research Methodology
Bottom-up confectionery application modeling reconciled against top-down caramel ingredient supply tracking forms the analytical core. Primary interviews with artisan chocolate house procurement directors, industrial food manufacturer R&D leads, specialty retailer category buyers, and regulatory affairs consultants at REACH service providers combined with secondary validation. Secondary sources include EFSA additive safety assessments, FDA 21 CFR 73.85 filings, French ANSM disclosure records, and BIS FSSAI alignment notifications. Triangulation against customs trade data for caramel color additive flows and Nielsen retail audit data for confectionery category performance anchored volume estimates.
Input-output matrix framing connects dairy input price indices, Maillard-reaction process energy costs, and regulatory compliance expenditure assumptions to finished goods pricing tiers across the projection horizon. Segmentation dimensions modeled include product type, application category, customer procurement scale, and distribution channel format. CAGRs derived from trend extrapolation of artisan bakery SKU expansion rates and savory-sweet snack coating adoption curves. Forecast inputs incorporate EFSA enforcement intensity scenarios and F-Gas Regulation disclosure phase-in schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Madagascar vanilla supply, abrupt EU dairy subsidy reforms, and breakthrough clean-label caramel color alternatives eliminating Maillard-process dependency. Forecasts reflect documented assumptions about regulatory enforcement continuity and artisan bakery chain expansion cadence. A small set of named triggers warrants ongoing watch: EFSA acrylamide threshold revision proposals, BIS FSSAI standard finalization for Indian imports, and AI-driven thermal profiling cost curves enabling mid-tier automation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Fats Market
Confectionery
Ice Cream Coating Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Xylitol Lollipops Market
Confectionery
Caramel Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Global Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
North America Marshmallow Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Infused Fruits Jellies Market